
 Automotive Propeller Shaft Couplings Market | 2026-2036
Automotive Propeller Shaft Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Propeller Shaft Couplings Market Insights
NHTSA durability standards is restructuring the cost-of-entry calculus for propeller shaft coupling manufacturers serving North American OEMs. GKN Automotive leverages its integrated forging and machining footprint to sustain position in heavy-duty universal joint supply. Dana Incorporated anchors its competitive stance through captive heat treatment capacity that reduces third-party dependency. ZF Friedrichshafen differentiates via precision CNC turning operations that serve European premium passenger vehicle programs.
Automotive propeller shaft couplings are torque-transmitting mechanical interfaces that connect driveline segments while accommodating angular misalignment, typically manufactured through hot forging of alloy steel blanks followed by induction hardening of bearing surfaces to achieve 58-62 HRC surface hardness. These components enable power delivery from transmission to axle assemblies across variable operating angles and load conditions. Universal joint configurations dominate volume supply to commercial vehicle applications where articulation range requirements are most severe. Slip joint designs represent the fastest-expanding product category as automakers pursue modular platform architectures that accommodate variable wheelbase derivatives. Multi-link couplings concentrate margin pools in off-highway equipment where shock load tolerance commands specification premiums.
EPA emissions enforcement shapes material selection toward lighter forged alloys that reduce unsprung mass penalties, while NHTSA crashworthiness protocols mandate coupling retention integrity under impact loading. ECE R100 type approval requirements in Europe govern electromagnetic compatibility for electrically coupled monitoring systems integrated into advanced shaft designs. Stakeholders must monitor how pending revisions to ISO 26262 functional safety standards will reclassify torque sensor-integrated couplings within higher automotive safety integrity levels.
Market Dynamics
Commercial vehicle torque transmission requirements are intensifying adoption of multi-link coupling architectures, while NHTSA durability mandates in North America are restructuring material specifications toward induction-hardened shaft assemblies. These dual pressures are compressing supplier margins while elevating technical barriers to market entry.
Growth Catalysts
- EPA emissions enforcement:Lighter forged alloy specifications reduce unsprung mass penalties in heavy-duty truck applications. OEM procurement teams prioritize weight-optimized designs.
- Modular platform architectures:Slip joint configurations enable variable wheelbase derivatives across passenger vehicle lineups. Automakers consolidate coupling specifications to achieve scale economies.
- Germany's premium drivetrain engineering clusters:Concentrated supplier capabilities serve automakers across European markets. Technical expertise pools accelerate prototype-to-production cycles.
Market Restraints
- Alloy steel input volatility:Hot forging feedstock costs fluctuate with scrap metal and energy pricing. Margin compression hits mid-tier forging houses hardest.
- Supply concentration in induction hardening capacity:Specialized heat treatment infrastructure clusters in Germany and the US Midwest. Bottlenecks emerge during OEM volume ramp-ups.
- ISO 26262 functional safety reclassification:Pending revisions threaten to elevate torque sensor-integrated couplings to higher automotive safety integrity levels. Compliance costs escalate for sensor-equipped designs.
Strategic Opportunities
- Electric vehicle drivetrain integration:ECE R100 type approval requirements in Europe govern electromagnetic compatibility for monitoring-enabled shaft designs. First-movers capture specification-setting influence.
- Off-highway equipment shock load tolerance:Multi-link couplings command specification premiums in mining and construction machinery. Margin pools exceed on-highway commercial vehicle averages.
- Captive heat treatment backward integration:In-house induction hardening capacity reduces third-party dependency and accelerates turnaround times. OEMs favor suppliers with controlled metallurgical processes.
Industry Challenges
- Precision CNC turning talent scarcity:European premium passenger vehicle programs demand sub-micron tolerance capabilities. Machine operator recruitment lags capacity expansion plans.
- Integrated forging-to-machining capex cycles:Greenfield facilities require synchronized hot forging press and five-axis machining investments. Financing timelines stretch 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Propeller Shaft Couplings Market |
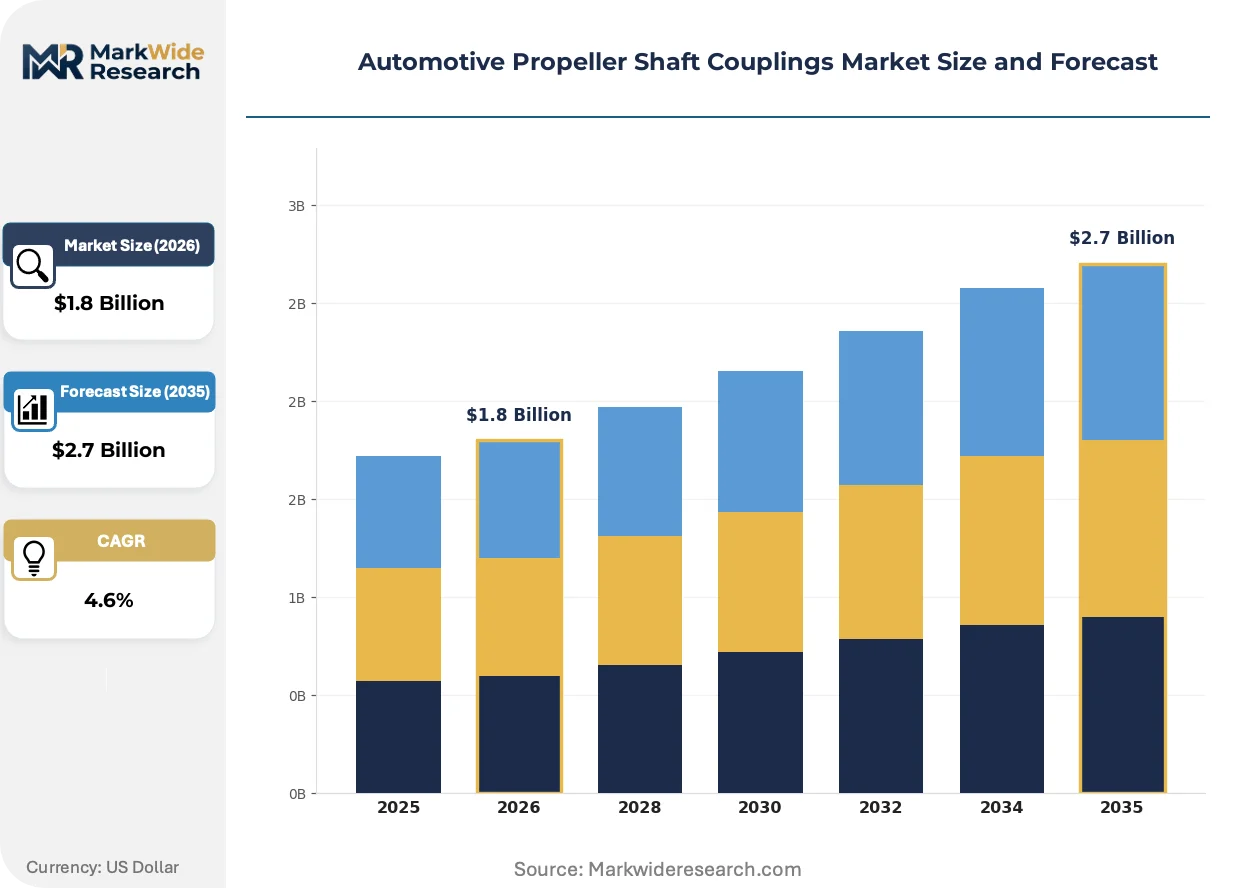
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slip Joint, Flange, Universal Joint, Elastomeric, One-Piece, Multi-Link Technology: Hot Forging, Cold Rolling, Machining, CNC Turning, Induction Hardening, Heat Treatment Application: Passenger Vehicles, Commercial Vehicles, Off-Highway Vehicles, Specialty Vehicles End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Dealers, Vehicle Refurbishers |
| Companies Covered | GKN Automotive, Dana Incorporated, American Axle & Manufacturing, BorgWarner, ZF Friedrichshafen, JTEKT Corporation, NTN Corporation, Schaeffler AG, Rheinmetall Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Propeller Shaft Couplings Market Trends and Innovations
Propeller shaft coupling engineering is pivoting toward sensor-integrated intelligent designs that transmit torque data to vehicle control modules. This convergence of mechanical and electronic systems is compressing traditional component boundaries.
Carbon fiber-reinforced polymer composite shaft tubes are rewriting strength-to-weight benchmarks for passenger vehicle applications. Luxury automakers in Germany specify these designs for reduced rotational inertia. The technology is compressing demand for conventional steel tubular shafts in segments above 400 Nm torque ratings.
NHTSA crashworthiness protocols now mandate coupling retention integrity under frontal impact loading. OEM engineering teams redesign yoke geometries and bearing retention mechanisms to satisfy penetration resistance thresholds. Heavy-duty universal joint suppliers serving North American commercial vehicle fleets face the steepest redesign cycles.
Fleet procurement teams now unbundle after-sales service contracts from initial component supply agreements. Third-party driveline specialists capture maintenance revenue previously retained by OEM captive service networks. This pattern concentrates in US long-haul trucking operations where total cost of ownership calculations dominate sourcing decisions.
Automotive Propeller Shaft Couplings Market Segmentation
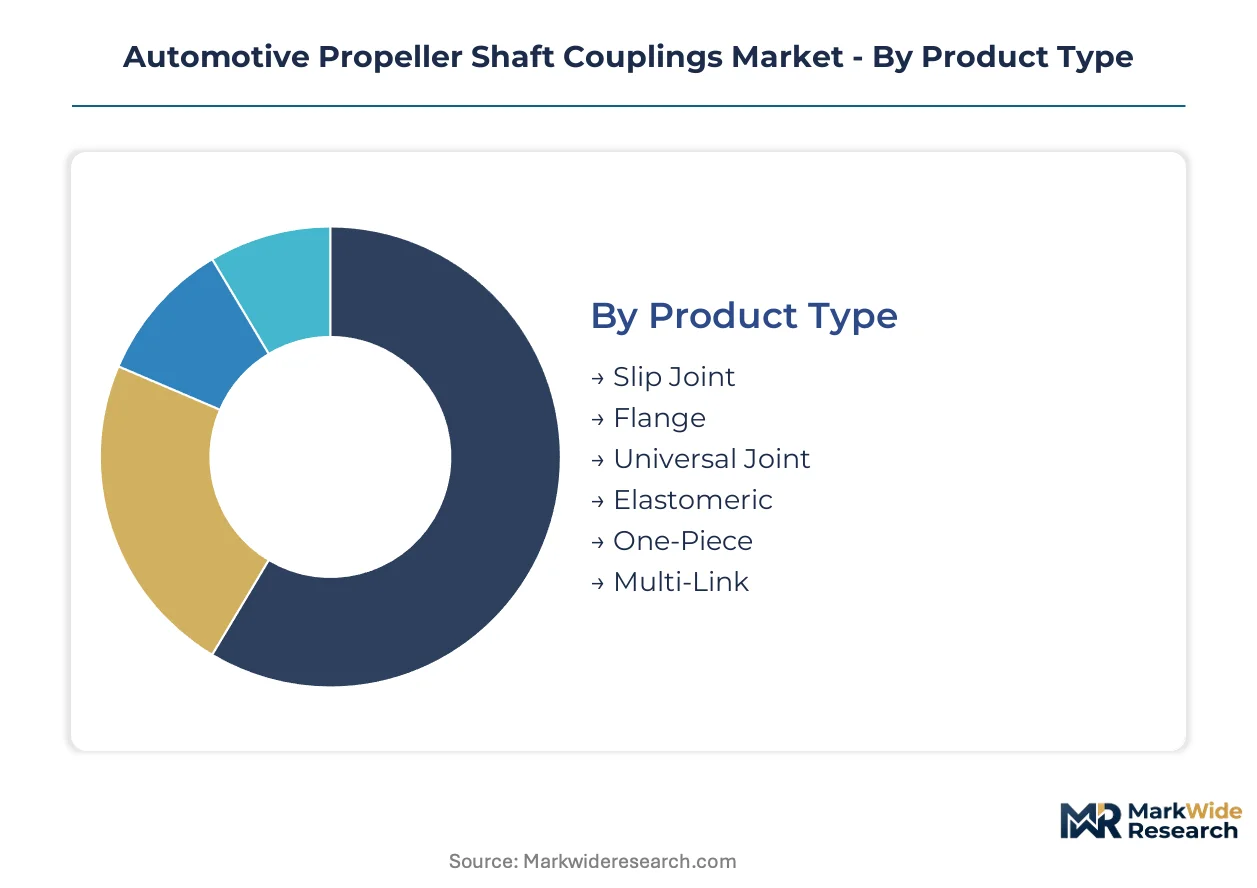
Propeller shaft coupling procurement splits sharply between high-volume standardized designs and specification-intensive premium architectures. Understanding where margin pools concentrate versus where volume flows determines supplier positioning strategy.
Product Type:
Universal joint configurations dominate commercial vehicle volume, while multi-link designs capture the steepest margin premiums in specialized applications.
- Universal Joint:Cross-and-bearing assemblies accommodate severe articulation angles in heavy-duty truck drivelines. Fleet procurement concentrates in North American long-haul configurations where durability mandates from NHTSA intensify specification requirements.
- Multi-Link:Articulated torque transmission systems integrate multiple pivot points for shock load distribution. Mining and construction equipment operators in Germany specify these for extreme duty cycles, commanding substantial price premiums over standard designs.
- Slip Joint:Telescoping shaft segments enable variable wheelbase accommodation across modular vehicle platforms.
- Flange:Rigid disc interfaces provide zero-backlash connections in fixed-geometry driveline segments.
- Elastomeric:Rubber-damped couplings isolate torsional vibrations in passenger vehicle applications.
- One-Piece:Monolithic forged shafts eliminate joint maintenance in sealed drivetrain architectures.
Today's leader: Universal joint. Tomorrow's challenger: Multi-link.
Technology:
Manufacturing process selection determines metallurgical performance thresholds and shapes supplier capital intensity profiles.
- Hot Forging:Alloy steel blanks deform at elevated temperatures to achieve grain flow alignment critical for fatigue resistance. OEMs in Germany prioritize forged yoke geometries for premium passenger vehicle programs where torsional stiffness specifications are most demanding.
- Induction Hardening:Localized electromagnetic heating rapidly quenches bearing surfaces to 58-62 HRC hardness without through-hardening distortion. NHTSA durability mandates in the US Midwest are accelerating captive capacity investments to control turnaround times.
- Cold Rolling:Room-temperature forming achieves dimensional precision for thin-walled tubular shaft segments.
- Machining:Subtractive material removal delivers tight tolerances on critical mounting interfaces.
- CNC Turning:Computer-controlled lathe operations produce symmetrical rotational components with sub-micron repeatability.
- Heat Treatment:Controlled thermal cycles relieve residual stresses and stabilize microstructures post-forging.
Hot forging anchors current supply. Induction hardening capacity is expanding most quickly.
Application:
Vehicle duty cycle severity dictates coupling architecture selection and drives aftermarket replacement frequency.
- Commercial Vehicles:Heavy-duty universal joints endure constant articulation under full torque loads. Fleet operators across US interstate corridors prioritize total cost-of-ownership calculations that favor induction-hardened assemblies with extended service intervals.
- Off-Highway Vehicles:Mining excavators and construction dozers subject couplings to impact loads exceeding on-highway specifications by orders of magnitude. German equipment manufacturers specify multi-link architectures that tolerate shock without catastrophic failure.
- Passenger Vehicles:Light-duty slip joints accommodate production variance in mass-market assembly lines.
- Specialty Vehicles:Military and emergency service platforms require hardened designs with redundant retention features.
Commercial vehicles generate current volume. Off-highway applications are gaining share fastest.
End User Industry:
Channel structure determines pricing power and shapes technical support requirements across the product lifecycle.
- OEMs:Original equipment manufacturers specify couplings during vehicle platform development and negotiate multi-year supply agreements. German premium automakers maintain direct engineering relationships with forging houses to accelerate prototype iterations.
- Tier-1 Suppliers:Integrated driveline module producers consolidate coupling procurement with axle and transmission assembly sourcing. Dana Incorporated and GKN Automotive leverage captive heat treatment capacity to defend position in North American OEM supply chains.
- Aftermarket Dealers:Independent distributors serve vehicle refurbishment and collision repair demand outside warranty periods.
- Vehicle Refurbishers:Remanufacturing specialists reclaim cores for cost-sensitive fleet maintenance programs.
OEMs control specification authority. Tier-1 suppliers are consolidating procurement influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized forging and heat treatment talent clusters in Germany's industrial heartland anchor European supply capacity. NHTSA regulatory enforcement in the United States Midwest concentrates induction hardening expertise. Japanese precision machining traditions sustain sub-micron tolerance capabilities for premium passenger vehicle programs.
United States
Long-haul commercial vehicle fleets across interstate corridors drive specification demand for extended-service-interval designs. NHTSA durability mandates compel OEMs toward induction-hardened shaft assemblies with verified retention integrity. Detroit-area forging houses and Ohio Valley heat treatment clusters control turnaround times for North American volume programs.
Germany
Premium automakers specify forged yoke geometries with demanding torsional stiffness thresholds for passenger vehicle platforms. ECE R100 type approval requirements govern electromagnetic compatibility for sensor-integrated shaft designs. Stuttgart and Munich engineering clusters accelerate prototype-to-production cycles through concentrated supplier capabilities.
Japan
Precision CNC turning operations serve domestic premium passenger vehicle programs with sub-micron repeatability requirements. METI industrial standards influence material selection protocols for lightweight forged alloys. Nagoya and Kansai manufacturing belts maintain integrated forging-to-machining footprints for just-in-time delivery.
China
Domestic commercial vehicle production scales drive volume demand for standardized universal joint configurations. MIIT vehicle certification requirements shape metallurgical specifications for heavy-duty applications. Yangtze River Delta forging clusters expand captive heat treatment capacity to reduce import dependency.
South Korea
Hyundai-Kia supplier networks prioritize modular platform compatibility through slip joint configurations. MFDS automotive component standards align with international durability protocols for export-oriented production. Busan-Ulsan industrial corridor concentrates machining capacity for regional OEM supply chains.
Automotive Propeller Shaft Couplings Market Competitive Landscape
The competitive structure tilts toward integrated forging-to-machining specialists with captive metallurgical capabilities. Tier-1 driveline module producers consolidate procurement influence while mid-tier forging houses face margin compression from alloy input volatility. Three archetypes dominate: European precision engineering specialists, North American heavy-duty commercial vehicle suppliers, and Asian scale-oriented fabricators. Capacity expansion and backward integration into heat treatment represent the primary competitive vectors.
Among European-based engineering specialists, ZF Friedrichshafen and Schaeffler AG occupy positions emphasizing precision manufacturing capabilities for premium passenger vehicle programs. GKN Automotive represents the integrated forging-and-machining archetype with established relationships across multiple OEM supply chains. Dana Incorporated anchors the North American commercial vehicle supplier tier with emphasis on captive process control.
| Leading Market Players |
|---|
| GKN Automotive |
| Dana Incorporated |
| American Axle & Manufacturing |
| BorgWarner |
| ZF Friedrichshafen |
| JTEKT Corporation |
| NTN Corporation |
| Schaeffler AG |
| Rheinmetall Automotive |
| Others |
Pricing and Supply Chain Analysis
NHTSA durability mandates for induction-hardened shaft assemblies are forcing OEM procurement teams toward suppliers with captive heat treatment capacity, compressing margins for forging houses dependent on third-party hardening services. Fleet operators unbundling after-sales contracts from initial supply agreements are reshaping how component pricing captures lifetime value.
Pricing Analysis
The bundled-versus-unbundled service split separates initial component supply from multi-year maintenance revenue, with third-party driveline specialists capturing service margins previously retained by OEM captive networks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in mid-tier forging segments is intensifying because alloy steel input volatility erodes fixed-price contract viability. Fleet procurement teams in North American long-haul trucking demonstrate highest price sensitivity, while German premium automakers prioritize torsional stiffness specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized induction hardening infrastructure concentrated in Germany and the US Midwest, where capacity bottlenecks emerge during OEM volume ramp-ups. Hot forging feedstock draws from alloy steel mills in China, Germany, and Japan, with bearing-grade steel specifications resting on scrap metal and energy pricing cycles. Tariff exposure on precision-machined components from European engineering clusters threatens cost structures for North American OEM programs. Distribution runs through Tier-1 driveline module producers who consolidate coupling procurement with axle and transmission assembly sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where captive heat treatment capacity in the US Midwest commands premium positioning against European forging houses facing elevated energy input costs.
For Market Incumbents: Lock in backward integration into induction hardening capacity to eliminate third-party dependency and accelerate turnaround times during OEM volume surges. Secure multi-year alloy steel offtake agreements to buffer margin compression from scrap metal volatility. Prioritize certification investment for ISO 26262 functional safety compliance as torque sensor integration elevates coupling classifications.
For New Entrants and Emerging Players: Digital aftermarket platforms offer direct channel access to fleet maintenance programs outside OEM captive service networks. Target US long-haul trucking refurbishment demand where total cost-of-ownership calculations dominate sourcing decisions. Pursue white-space positioning in off-highway equipment multi-link architectures where shock load tolerance commands specification premiums exceeding on-highway commercial vehicle averages.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier forging houses possessing integrated machining footprints but lacking captive metallurgical capacity, as OEM procurement shifts toward controlled process suppliers. The five-to-ten year viability window favors acquisition targets with established relationships across modular platform architectures. Monitor pending ISO 26262 revision implementation as inflection indicator for sensor-equipped coupling compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat Treatment Expansion | Eliminates third-party hardening bottlenecks for NHTSA-compliant shaft assemblies. |
| Modular Platform Standardization | Slip joint configurations enable variable wheelbase derivatives across vehicle lineups. |
| Sensor-Integrated Coupling Development | ECE R100 electromagnetic compatibility positions suppliers for EV drivetrain integration. |
| Alloy Steel Supply Agreement | Long-term offtake contracts buffer margin compression from scrap metal volatility. |
| Aftermarket Service Unbundling | Third-party maintenance revenue capture reshapes lifetime value extraction from fleet operators. |
Research Methodology
Multiple input streams — primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distribution heads; secondary validation through vehicle production databases, IHS Markit registration data, and SEC filings from listed driveline suppliers; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned forging house operations managers, induction hardening facility directors, and fleet maintenance procurement specialists across North American interstate corridors and German industrial clusters.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from production volume trajectories and content-per-vehicle assumptions, cross-referenced with OEM platform lifecycle schedules and regulatory implementation timelines for NHTSA durability mandates and pending ISO 26262 revisions.
The model assumes a particular technology adoption path for sensor-integrated intelligent coupling designs; alternative pathways for carbon fiber-reinforced polymer composite shaft tubes would alter the outlook for conventional steel tubular demand in segments above 400 Nm torque ratings. Forecasts reflect assumptions about modular platform proliferation rates and EV drivetrain integration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Brake Pad Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Germany Automotive Parts Die Casting Market