
 Autonomous Haulage Truck Market | 2026-2036
Autonomous Haulage Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Haulage Truck Market Outlook
Australian iron ore producers is consolidating autonomous haulage capacity across the Pilbara region. Komatsu anchors the heavy machinery segment through its FrontRunner AHS platform deployed at multiple mine sites. Caterpillar competes with its Command for Hauling system, sustaining deep integration with large-scale open-pit operations. Hitachi Construction Machinery differentiates through electric-drive autonomous trucks tailored for high-altitude copper extraction.
An autonomous haulage truck is a self-driving heavy-duty vehicle engineered for repetitive material transport in controlled industrial environments, typically integrating LiDAR arrays, differential GPS, and onboard machine learning inference engines to navigate haul roads without human operators. These systems execute programmed routes between excavation faces and processing facilities with centimeter-level positioning accuracy. Rigid trucks dominate current deployment volumes in deep-pit mining, while electric trucks represent the fastest-expanding technology segment as diesel cost volatility and underground ventilation constraints reshape procurement criteria. Articulated trucks occupy a narrower niche in rugged construction terrain where maneuverability outweighs payload maximization.
The US Mine Safety and Health Administration and Australia's Department of Industry, Science and Resources enforce divergent certification pathways for autonomous vehicle deployment, creating compliance complexity for multinational operators. China's MIIT mandates GB-standard functional safety assessments that restrict market access for uncertified foreign platforms. Stakeholders must monitor regulatory reciprocity negotiations between major mining jurisdictions to anticipate fleet standardization opportunities or fragmentation risks.
Market Dynamics
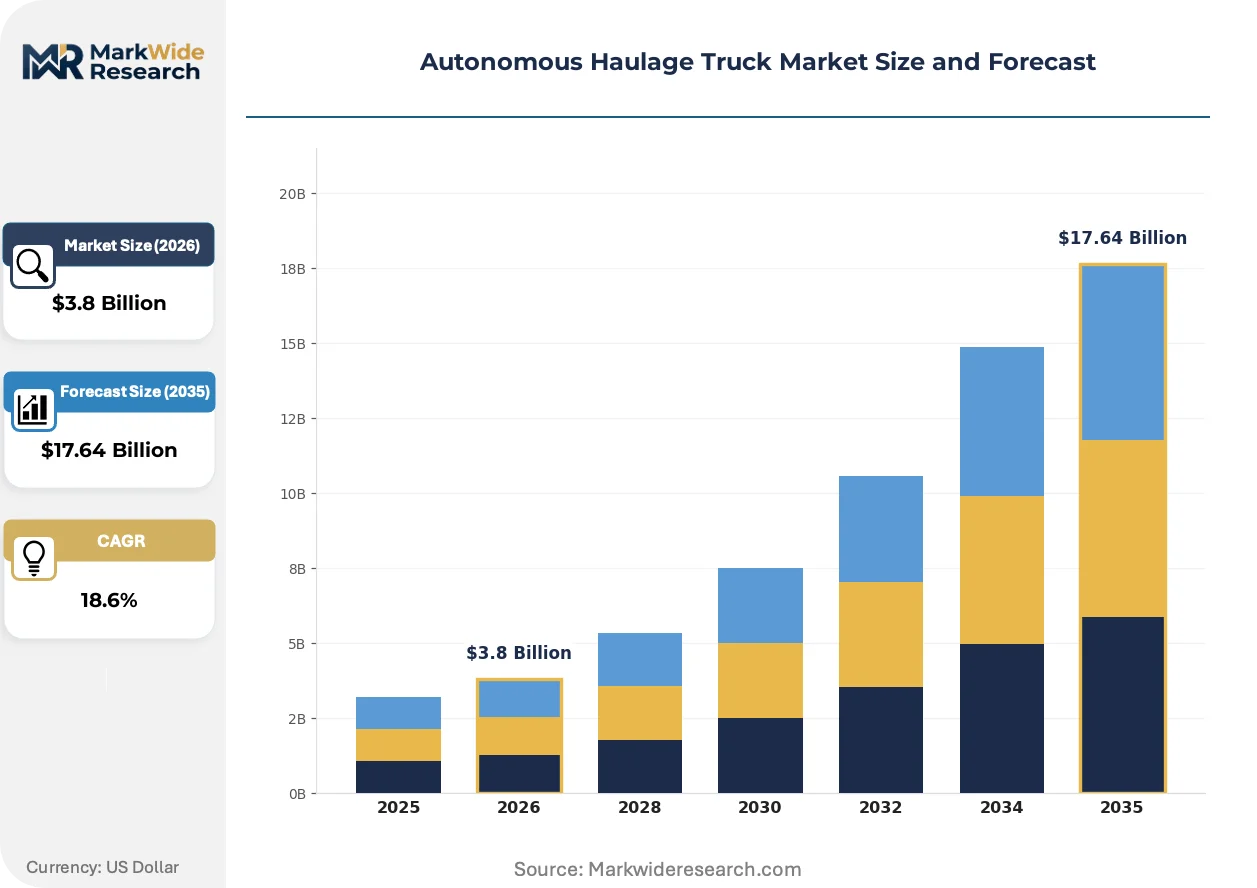
Autonomous haulage deployment is accelerating as mining operators confront diesel cost volatility and underground ventilation constraints that render electric-drive fleets economically imperative. The convergence of machine learning inference engines with differential GPS positioning is compressing deployment timelines across controlled industrial environments.
Growth Catalysts
- MIIT Safety Certification Framework:China's GB-standard functional safety assessments for unmanned mining vehicles are accelerating deployment timelines by establishing clear compliance pathways for domestic and foreign platforms.
- Underground Ventilation Economics:Copper and gold extraction operations in high-altitude Andean deposits are mandating zero-emission haulage to reduce ventilation infrastructure costs and improve worker safety conditions.
- LiDAR-GPS Sensor Fusion:Centimeter-level positioning accuracy on repetitive haul roads is eliminating collision risk and enabling 24-hour continuous operations without shift-change downtime.
Market Restraints
- High-Voltage Battery Cost Concentration:Lithium-nickel-manganese-cobalt cell supply concentrates in Chinese and South Korean manufacturing bases, exposing fleet operators to raw material price volatility and geopolitical supply disruption.
- Interoperability Fragmentation:Proprietary fleet management protocols from Komatsu, Caterpillar, and Hitachi prevent mixed-vendor autonomous truck deployment at single mine sites.
- Cyber-Physical Attack Surface:Connected haulage networks face ransomware and GPS spoofing threats that require continuous security patching and air-gapped operational technology architectures.
Strategic Opportunities
- Construction and Quarry Expansion:Articulated autonomous trucks are penetrating rugged terrain applications in Scandinavian aggregate extraction and Alpine tunneling projects where maneuverability outweighs payload maximization.
- EU Green Deal Carbon Border Adjustments:Embodied emissions regulations on imported iron ore are incentivizing Pilbara producers to electrify haulage fleets and secure preferential market access.
- Teleoperation Fallback Integration:5G-enabled remote operator centers in Perth and Santiago are converging with full autonomy to handle edge-case scenarios, reducing the technical barrier to unmanned deployment.
Industry Challenges
- Autonomous Systems Technician Shortage:Mining regions in Western Australia and Chile's Atacama lack sufficient personnel trained in LiDAR calibration, machine learning model retraining, and predictive maintenance of electric drivetrains.
- Legacy Fleet Stranding Risk:Diesel truck assets with remaining depreciation schedules create capital allocation conflicts for operators weighing early retirement against hybrid retrofit pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Haulage Truck Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Trucks, Articulated Trucks, Electric Trucks, Hybrid Trucks Technology: LiDAR, Computer Vision, GPS, Machine Learning Application: Mining, Construction, Logistics, Bulk Transport End User: Mining Companies, Construction Firms, Shipping Companies, Industrial Users |
| Companies Covered | Hitachi Construction Machinery, Aurora Innovation, Caterpillar, Gatik, Kodiak AI, Komatsu, Sandvik, Pony.ai, Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Haulage Truck Market Strategic Shifts
Electric-drive autonomous platforms are displacing diesel-mechanical haulage across deep-pit iron ore and copper extraction. Regulatory divergence between Australia's Department of Industry, Science and Resources and the US Mine Safety and Health Administration is forcing multinational operators toward modular certification architectures.
Battery-electric rigid haul trucks are expanding into Pilbara iron ore corridors where Rio Tinto and BHP have operationalized driverless networks. Surface mining operators in Western Australia are adopting 300-ton-class electric platforms at pace, compressing total cost of ownership calculations and displacing diesel procurement contracts that previously dominated 20-year mine life planning.
Australia's Department of Industry, Science and Resources maintains divergent certification pathways from the US Mine Safety and Health Administration, creating compliance complexity for multinational operators running fleets across both jurisdictions. Mining companies are responding by segregating fleet procurement by geography rather than pursuing unified global standards, fragmenting vendor scale economies and prolonging platform development cycles.
Service contracting is unbundling from equipment procurement as Komatsu and Caterpillar retain ownership of autonomous truck assets and charge per-ton-mile fees. Mining operators in Chile's Atacama region are displacing capital-heavy balance sheet expansion with operational expenditure models, transferring residual value risk to OEMs while demanding guaranteed uptime penalties in service level agreements.
Autonomous Haulage Truck Market Segmentation
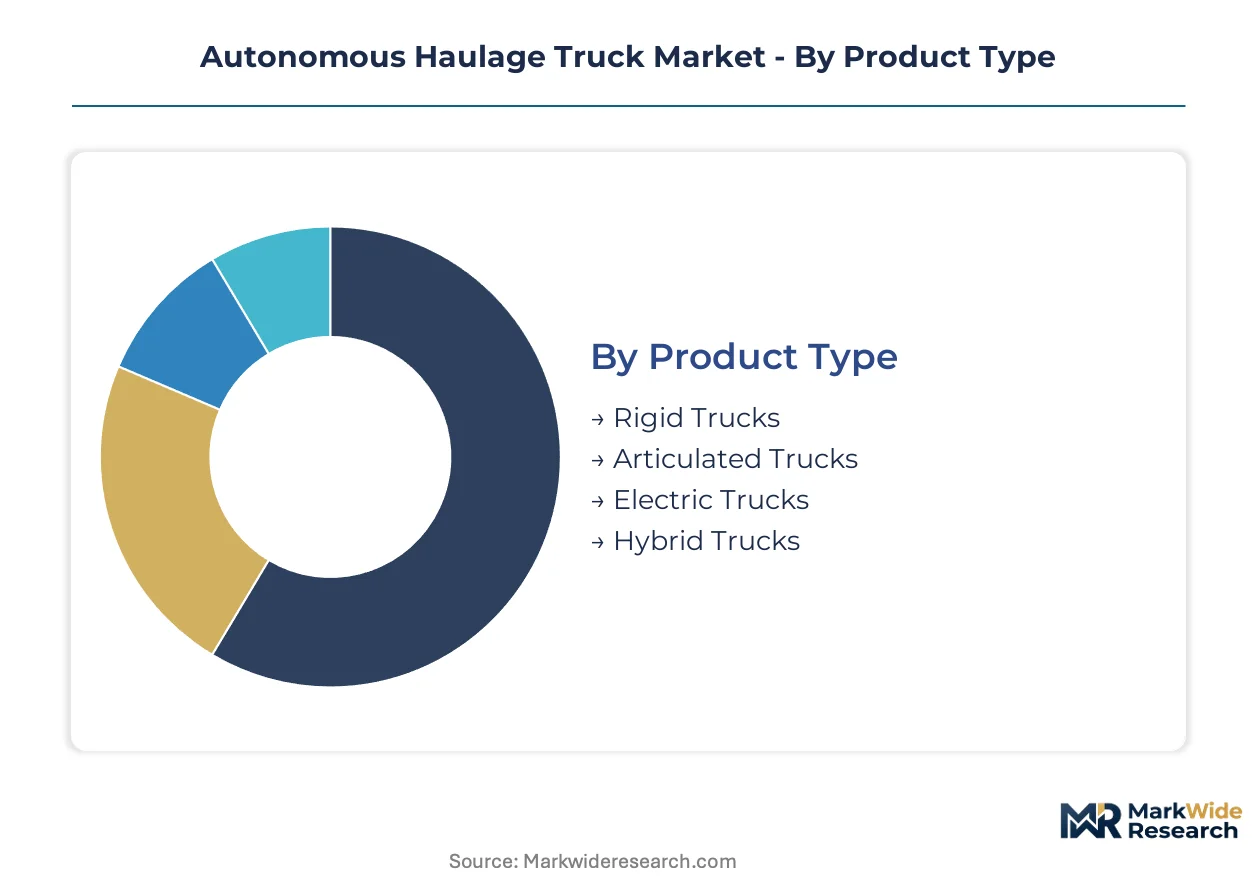
Segmentation in autonomous haulage reveals where capital allocation concentrates and how technology choices lock operators into specific operational models. Product type and technology selections determine fleet interoperability, energy infrastructure requirements, and regulatory compliance pathways across mining and construction verticals.
Product Type:
Capital intensity varies sharply across chassis configurations, with payload capacity and electrification infrastructure driving upfront investment hierarchies.
- Rigid Trucks:Fixed-axle heavy-duty platforms engineered for deep-pit mining with 200-400 ton payload ratings. Demand concentrates in Australia's Pilbara iron ore corridor where Rio Tinto and BHP have operationalized driverless networks, driven by 24-hour continuous haulage economics and shift-change elimination.
- Electric Trucks:Battery-electric or trolley-assist platforms eliminating diesel combustion in underground and surface operations. Chile's Atacama copper mines are mandating zero-emission haulage to reduce ventilation infrastructure costs and improve worker safety conditions in high-altitude deposits.
- Articulated Trucks:Pivot-steering configurations optimized for rugged terrain maneuverability in quarry and tunneling applications.
- Hybrid Trucks:Dual-powertrain systems combining diesel range extension with electric drive for transitional mine sites lacking charging infrastructure.
Rigid trucks absorb the bulk of installed capacity; electric trucks are expanding most quickly.
Technology:
Perception and navigation technology choices determine positioning accuracy, weather resilience, and cybersecurity exposure across deployment environments.
- LiDAR:Pulsed laser arrays generating 3D point clouds for centimeter-level obstacle detection and haul road mapping. Western Australian surface mining operators rely on LiDAR-GPS fusion to eliminate collision risk on repetitive routes between excavation faces and processing facilities.
- Machine Learning:Onboard inference engines processing sensor fusion data for real-time path planning and anomaly detection. China's MIIT safety certification framework is accelerating deployment timelines by establishing clear compliance pathways for domestically trained autonomous driving models.
- Computer Vision:Camera-based object classification and lane-keeping systems supplementing primary LiDAR perception.
- GPS:Differential and RTK-corrected satellite positioning providing baseline localization with centimeter-level accuracy.
LiDAR dominates current perception stacks; machine learning is climbing the fastest as model training pipelines mature.
Application:
Site-specific operational constraints shape technology requirements and vendor selection criteria across industrial verticals.
- Mining:Controlled-environment material transport between pit faces, crushers, and stockpiles with pre-mapped haul roads. Pilbara iron ore producers are consolidating autonomous haulage capacity as diesel cost volatility and ventilation economics render electric fleets economically imperative.
- Construction:Unstructured terrain earthmoving and aggregate transport where maneuverability outweighs payload maximization. Scandinavian aggregate extraction and Alpine tunneling projects are adopting articulated autonomous trucks for rugged terrain penetration.
- Logistics:Yard and terminal container movement in constrained industrial environments.
- Bulk Transport:Repetitive commodity movement along dedicated corridors in mining and port contexts.
Mining commands the dominant share of deployed fleets; construction is gaining share fastest as articulated platforms penetrate quarry applications.
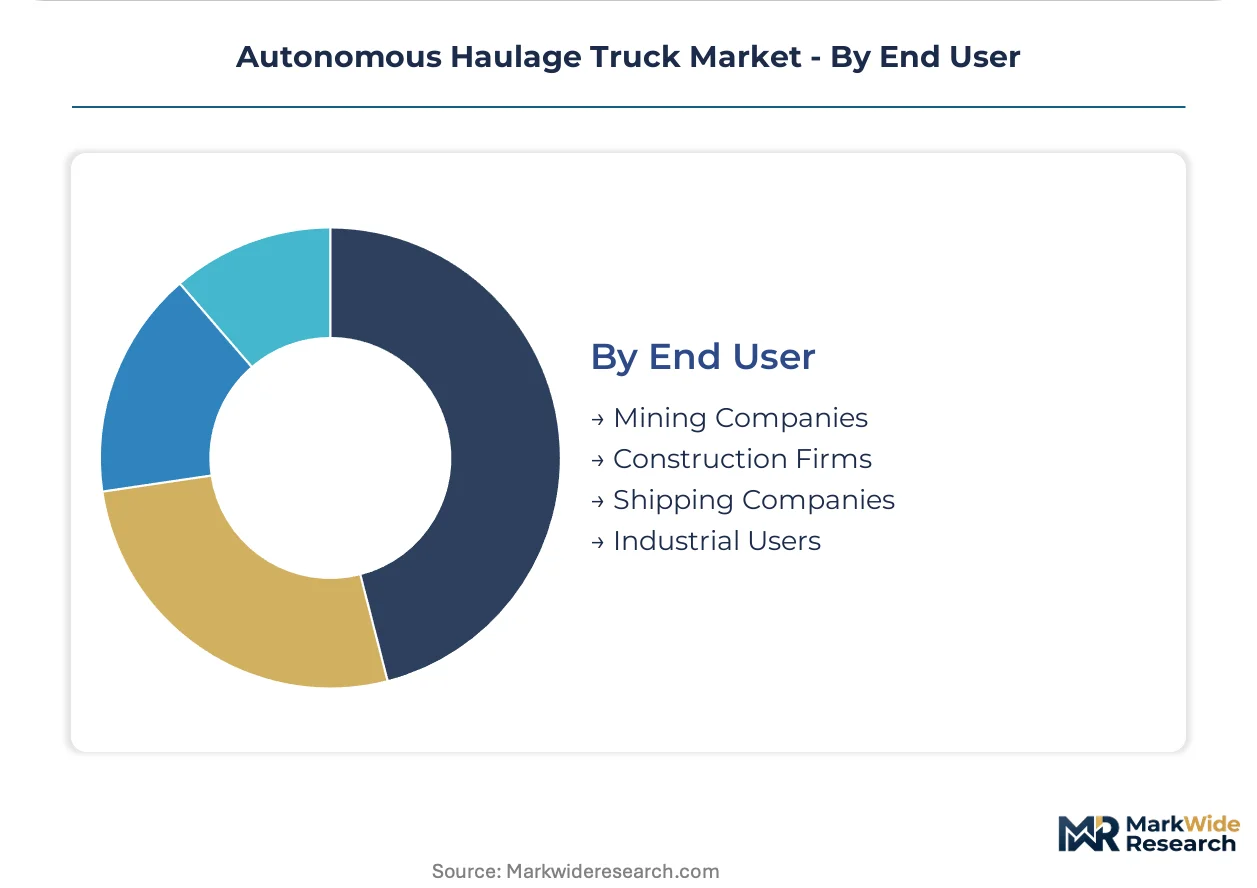
End User:
Procurement authority and fleet scale determine contract structures, from capital purchase to service-based per-ton-mile arrangements.
- Mining Companies:Large-scale open-pit and underground operators with 20-year mine life planning horizons. Surface mining operators in Western Australia and Chile's Atacama region are expanding fleet trials as service contracting unbundles from equipment procurement.
- Construction Firms:Project-based contractors with shorter asset utilization windows and fragmented site portfolios.
- Shipping Companies:Port terminal operators automating container and bulk material yard movements.
- Industrial Users:Captive mining and processing operations with vertically integrated material handling requirements.
Mining companies deploy the overwhelming majority of autonomous truck capacity; construction firms are adopting fastest where maneuverability requirements align with articulated platform capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara iron ore deposits anchor Australian deployment volumes. Chile's Atacama copper belt drives zero-emission mandates. China's MIIT certification framework accelerates domestic platform approvals.
Australia
Western Australia's Department of Industry, Science and Resources enforces autonomous vehicle certification distinct from US pathways. Rio Tinto and BHP have operationalized driverless networks across Pilbara corridors. Perth hosts teleoperation fallback centers converging with full autonomy systems.
Chile
Atacama copper extraction operations mandate zero-emission haulage to reduce ventilation infrastructure costs. The Ministry of Mining coordinates safety standards for unmanned vehicles in high-altitude deposits. Santiago-based remote operator centers handle edge-case scenarios for surface mining fleets.
China
MIIT's GB-standard functional safety assessments establish compliance pathways for unmanned mining vehicles. Domestic mining conglomerates accelerate fleet trials under accelerated deployment timelines. Inner Mongolia coal basins and Shanxi mineral corridors concentrate pilot program activity.
United States
The Mine Safety and Health Administration maintains divergent certification pathways from Australian regulators. Copper and gold extraction operations in Arizona and Nevada explore autonomous retrofit options. Southwestern surface mining districts confront interoperability fragmentation between proprietary fleet management protocols.
Sweden
Scandinavian aggregate extraction operations adopt articulated autonomous trucks for rugged terrain penetration. The Swedish Work Environment Authority coordinates with EU machinery directives on autonomous vehicle deployment. Kiruna iron ore districts and Alpine tunneling projects drive maneuverability-focused procurement.
Autonomous Haulage Truck Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined autonomy stacks. The market structures around heavy machinery incumbents with integrated autonomous platforms and technology specialists supplying perception and navigation modules. Three archetypes dominate: diversified industrial conglomerates with mining heritage, pure-play autonomous driving developers, and construction equipment specialists pivoting toward electrification. Consolidation pressures favor strategic partnerships over vertical integration, with capacity expansion concentrated in battery-electric drivetrain manufacturing.
Within the diversified industrial tier, Komatsu and Caterpillar anchor established positions through integrated autonomous haulage systems. Hitachi Construction Machinery occupies a specialization vector targeting high-altitude copper extraction with electric-drive configurations. Aurora Innovation and Gatik represent the software-defined autonomy archetype, supplying perception stacks and fleet management modules to industrial operators seeking modular deployment pathways rather than captive platform procurement.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| Aurora Innovation |
| Caterpillar |
| Gatik |
| Kodiak AI |
| Komatsu |
| Sandvik |
| Pony.ai |
| Volvo |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between GB-standard MIIT-certified platforms and uncertified foreign systems splits both pricing power and supplier access across Chinese and Australian mining corridors. Premium-tier autonomous haulage systems bundle guaranteed uptime penalties and residual value risk transfer, while commodity-tier procurement concentrates on capital-light per-ton-mile arrangements that expose operators to service fragmentation.
Pricing Analysis
Warranty bundling separates integrated autonomous haulage systems from unbundled software modules in contract structures. Komatsu and Caterpillar retain asset ownership and charge per-ton-mile fees, transferring residual value risk while commanding premium pricing through guaranteed uptime clauses. Price differentiation hinges on certification tier and fleet scale, with China's GB-standard compliance adding procurement cost for foreign platforms. Pricing pressure stems from battery cell supply volatility in Chinese and South Korean manufacturing bases. Construction firms exhibit highest price sensitivity due to fragmented site portfolios and shorter utilization windows.
Supply Chain Analysis
Regional distribution centers in Perth and Santiago anchor hub-and-spoke service networks for autonomous fleet support. Component manufacturing concentrates in China, Japan, and Germany, with LiDAR arrays and differential GPS modules drawing from specialized optical and semiconductor suppliers. High-voltage battery cell production rests on lithium-nickel-manganese-cobalt supply from Chinese and South Korean cathode manufacturers. Single-source vulnerability in machine learning inference chip supply creates procurement risk. Distribution runs through OEM-captive service depots and third-party maintenance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as interoperability fragmentation and certification complexity force sub-scale software vendors toward strategic exits or acquisition. Proprietary fleet management protocols from established heavy machinery producers create insurmountable switching costs for emerging autonomy stacks.
For Market Incumbents: Deepen backward integration into battery-electric drivetrain manufacturing to secure supply against Chinese and South Korean cell concentration. Expand Perth and Santiago teleoperation center capacity to capture service contracting unbundling from equipment procurement. Lock in long-term per-ton-mile agreements with Pilbara iron ore producers before EU Green Deal carbon border adjustments accelerate fleet electrification mandates. For New Entrants and Emerging Players: Enter via modular perception stack supply to construction firms in Scandinavian aggregate extraction and Alpine tunneling projects, where maneuverability requirements favor articulated platforms over rigid haulage systems. Target quarry applications with software-defined autonomy modules compatible with existing articulated truck chassis. Pursue white-label fleet management integration with construction equipment specialists pivoting toward electrification. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play autonomous driving developers possessing MIIT GB-standard certification pathways, given China's accelerated deployment timelines and domestic platform preference. Five-to-ten-year viability hinges on securing anchor contracts with mining operators transitioning from capital-heavy balance sheets to operational expenditure models. Monitor regulatory reciprocity negotiations between Australia's Department of Industry, Science and Resources and the US Mine Safety and Health Administration as inflection indicator for fleet standardization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Per-ton-mile Service Contracting | Komatsu and Caterpillar retain asset ownership while transferring residual value risk to balance-sheet-light operators. |
| GB-standard Certification Investment | MIIT compliance pathways unlock Chinese domestic mining markets and accelerate foreign platform deployment timelines. |
| Teleoperation Center Expansion | Perth and Santiago remote operator hubs converge with full autonomy to handle edge-case scenarios. |
| Articulated Platform Development | Scandinavian aggregate extraction and Alpine tunneling projects drive maneuverability-focused procurement. |
| Battery-electric Drivetrain Integration | Chile's Atacama copper mines mandate zero-emission haulage to reduce ventilation infrastructure costs. |
Study Parameters
Independent corroboration across autonomous systems technicians, mining fleet procurement directors, and OEM aftermarket service heads underwrites the qualitative findings. Primary interviews with maintenance directors at Pilbara operations, plant engineers in Chile's Atacama region, and LiDAR calibration specialists in Western Australia combined with secondary validation from SEC filings of heavy machinery producers, customs data on autonomous vehicle component trade flows, and MIIT certification registries. Bottom-up fleet deployment counts triangulate against top-down mining capital expenditure disclosures.
Comparable-period anchoring to historical autonomous haulage adoption curves in Western Australia and Chile's Atacama region structured the forecast window. The analytical framework models technology segmentation across LiDAR, machine learning, and GPS navigation stacks; product type across rigid, electric, articulated, and hybrid configurations; and application across mining, construction, logistics, and bulk transport. CAGRs derive from installed base expansion rates and replacement cycle compression. Forecast inputs include diesel-electric total cost of ownership crossover timelines and underground ventilation economics for zero-emission mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory reciprocity failures between Australian and US certification pathways. Outputs reflect assumptions on battery cell supply stability and machine learning model retraining infrastructure availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market