
 Intelligent Torque Controlled Coupling (ITCC) Market | 2026-2036
Intelligent Torque Controlled Coupling (ITCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Torque Controlled Coupling (ITCC) Market Foresight
Carbon fiber-reinforced polymer is consolidating as the preferred housing material in next-generation ITCC units, displacing cast aluminum in torque-critical applications. JTEKT Corporation leverages its bearing heritage to dominate precision torque vectoring modules for hybrid drivetrains. SKF Group anchors European supply through vertically controlled sensor-coupling production in Sweden and Germany. ZF Friedrichshafen AG differentiates via integrated mechatronic coupling systems that bridge mechanical and electronic architectures.
An Intelligent Torque Controlled Coupling is a dynamically adjustable drivetrain component that modulates torque transfer between rotating shafts through real-time sensor feedback and electromechanical actuation, typically operating within 50-500 Nm torque ranges with sub-100 millisecond response times. Its primary purpose is to optimize traction, reduce mechanical stress, and enable predictive maintenance in power transmission systems. Electronic couplings command the fastest expansion as automakers phase out purely mechanical torque splitters. Hybrid couplings capture concentrated margin pools where OEMs demand seamless transitions between electric and combustion torque paths. Smart couplings remain nascent but attract R&D investment from robotics firms seeking adaptive joint mechanisms.
EPA tailpipe regulations and NHTSA crashworthiness standards compel automakers to adopt lighter, more responsive torque management systems that improve fuel efficiency without compromising structural integrity. ECE R13 braking and stability directives in Europe mandate precise torque modulation for vehicle dynamics control, creating compliance-driven replacement cycles. ISO 26262 functional safety requirements shape electronics architecture decisions for sensor-integrated couplings. Stakeholders must monitor how silicon carbide power electronics and edge-computing torque algorithms redefine the boundary between mechanical coupling and full mechatronic subsystem.
Market Dynamics
Automotive OEMs are consolidating torque management functions into unified electronic architectures, compressing supplier tiers and elevating firmware-integrated coupling modules over discrete mechanical components. This structural consolidation favors suppliers with captive sensor production and algorithm development capabilities.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:NHTSA-administered mandates compel automakers to deploy lighter, more responsive torque splitters that reduce parasitic losses in all-wheel-drive architectures.
- Carbon fiber-reinforced polymer housings:Material substitution in torque-critical applications enables 40-60% mass reduction versus cast aluminum, directly supporting fleet efficiency targets.
- Germany-Japan-US manufacturing clusters:Precision drivetrain production concentrates in Stuttgart, Aichi Prefecture, and Detroit metropolitan areas, creating dense supplier ecosystems and rapid iteration cycles.
Market Restraints
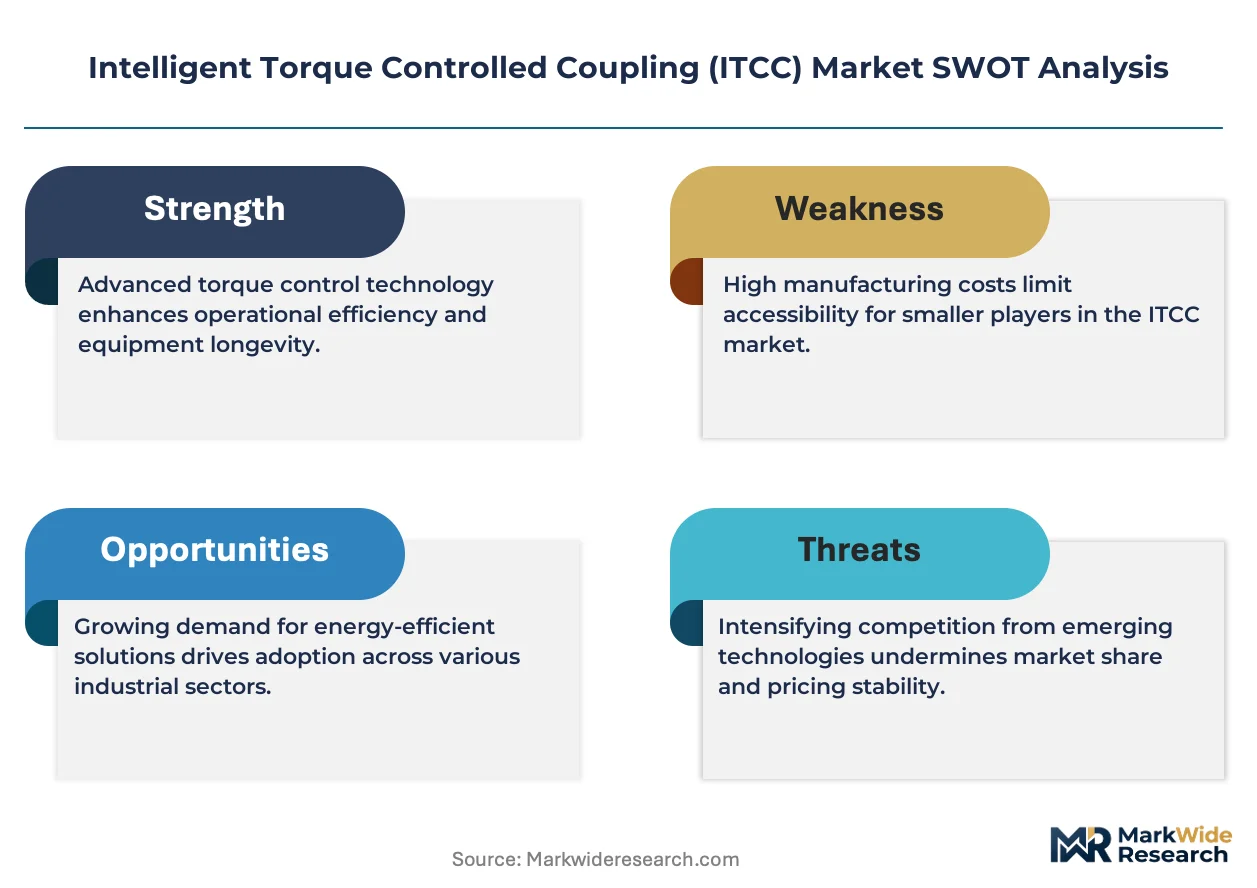
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese processing facilities transmit directly to permanent magnet actuator costs, compressing module margins.
- ISO 26262 functional safety certification:ASIL-D compliance for sensor-integrated couplings demands 18-24 month validation timelines, gating product releases.
- Electromagnetic torque vectoring:Hub-mounted electric motors in battery-electric platforms threaten to displace central coupling units in certain vehicle classes.
Strategic Opportunities
- Indian commercial vehicle segment:BIS certification alignment and PLI scheme incentives create entry pathways for torque management suppliers in domestic tractor and bus markets.
- Silicon carbide power electronics convergence:SiC inverter integration with coupling actuators enables sub-50 millisecond response times, opening robotics and industrial automation applications.
- EU Green Deal embedded carbon tracking:CSRD disclosure requirements favor suppliers with verified low-carbon supply chains, rewarding European sensor-coupling producers.
Industry Challenges
- Mechatronics systems integration:Bridging mechanical torque paths with electronic architectures demands firmware-hardware co-development capabilities scarce in traditional driveline suppliers.
- Edge-computing algorithm validation:Real-time torque prediction models require automotive-grade AI certification timelines that outpace software release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Torque Controlled Coupling (ITCC) Market |
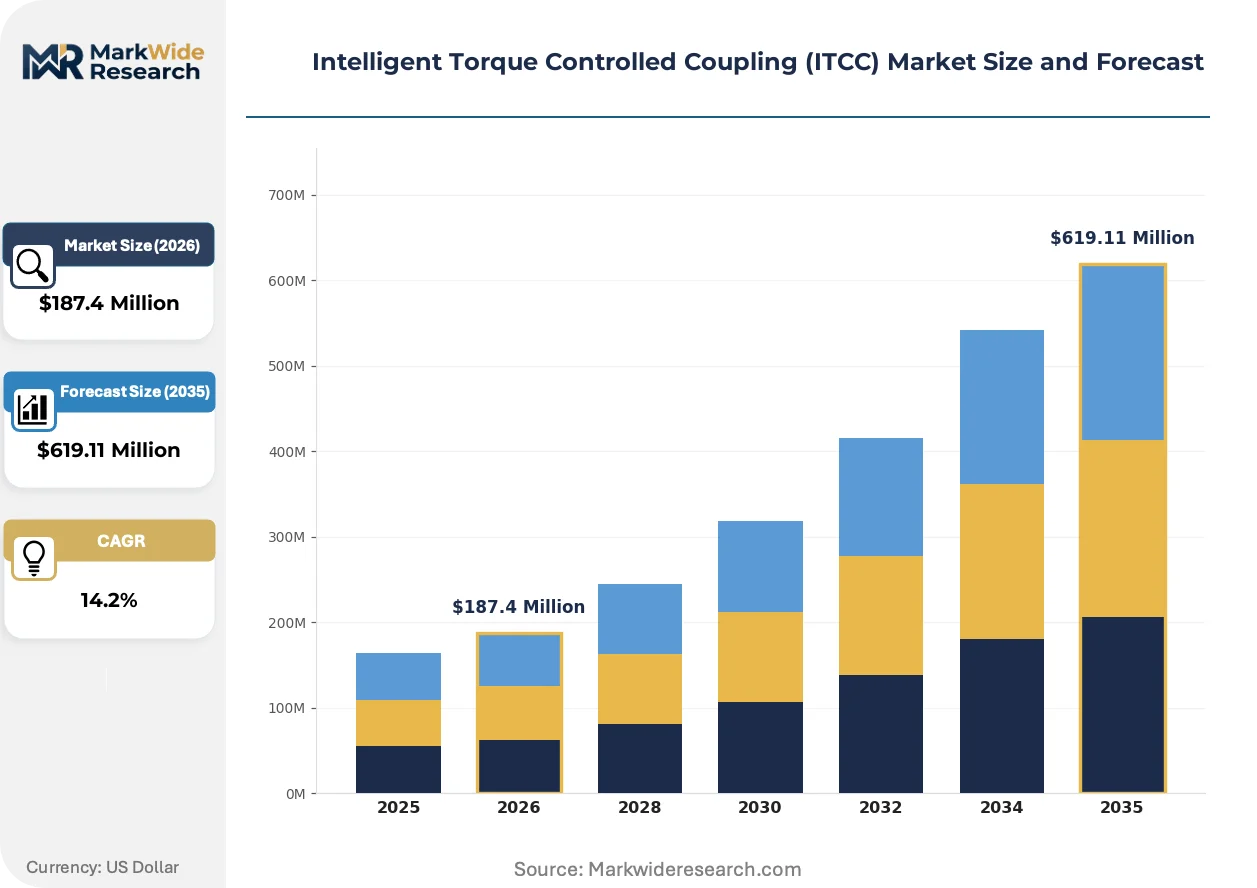
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Couplings, Electronic Couplings, Hybrid Couplings, Smart Couplings Application: Automobile Transmission, Industrial Machinery, Robotics, Aerospace Systems End User: Automotive OEMs, Manufacturing Plants, Aerospace Companies, Robotics Firms Technology: Sensor Integration, Feedback Control, Data Analytics, Wireless Communication |
| Companies Covered | JTEKT Corporation, SKF Group, ZF Friedrichshafen AG, Regal Rexnord Corporation, Voith GmbH, Continental AG, Ford, Vulkan Group, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Torque Controlled Coupling (ITCC) Market Shifts & Advancements
Three forces are restructuring competitive positioning in torque management: material substitution in housing architectures, functional safety mandates compressing development cycles, and procurement consolidation favoring subsystem integrators over component vendors.
Silicon carbide power semiconductors are decentralizing thermal management and response latency in next-generation coupling actuators. Tier 1 suppliers are adopting SiC inverter modules for torque vectoring applications, replacing silicon IGBT architectures. This transition is decentralizing the boundary between mechanical coupling hardware and full mechatronic subsystems, elevating firmware suppliers in value capture.
EU AI Act risk classification and ISO 26262 ASIL-D requirements are tightening validation protocols for sensor-integrated torque modules. European OEMs now demand traceable training data for machine learning-based torque prediction algorithms. Hybrid drivetrain programs face the steepest compliance burden, with German manufacturers leading in pre-certified architecture development.
Automotive procurement is consolidating vendor tiers through subsystem sourcing contracts that bundle sensors, actuators, and control algorithms. Tier 1 suppliers are absorbing Tier 2 component specialists to secure captive torque vectoring capability. This concentration is most visible in Japanese keiretsu structures, where bearing and sensor producers are merging development functions under single sourcing agreements.
Intelligent Torque Controlled Coupling (ITCC) Market Segmentation
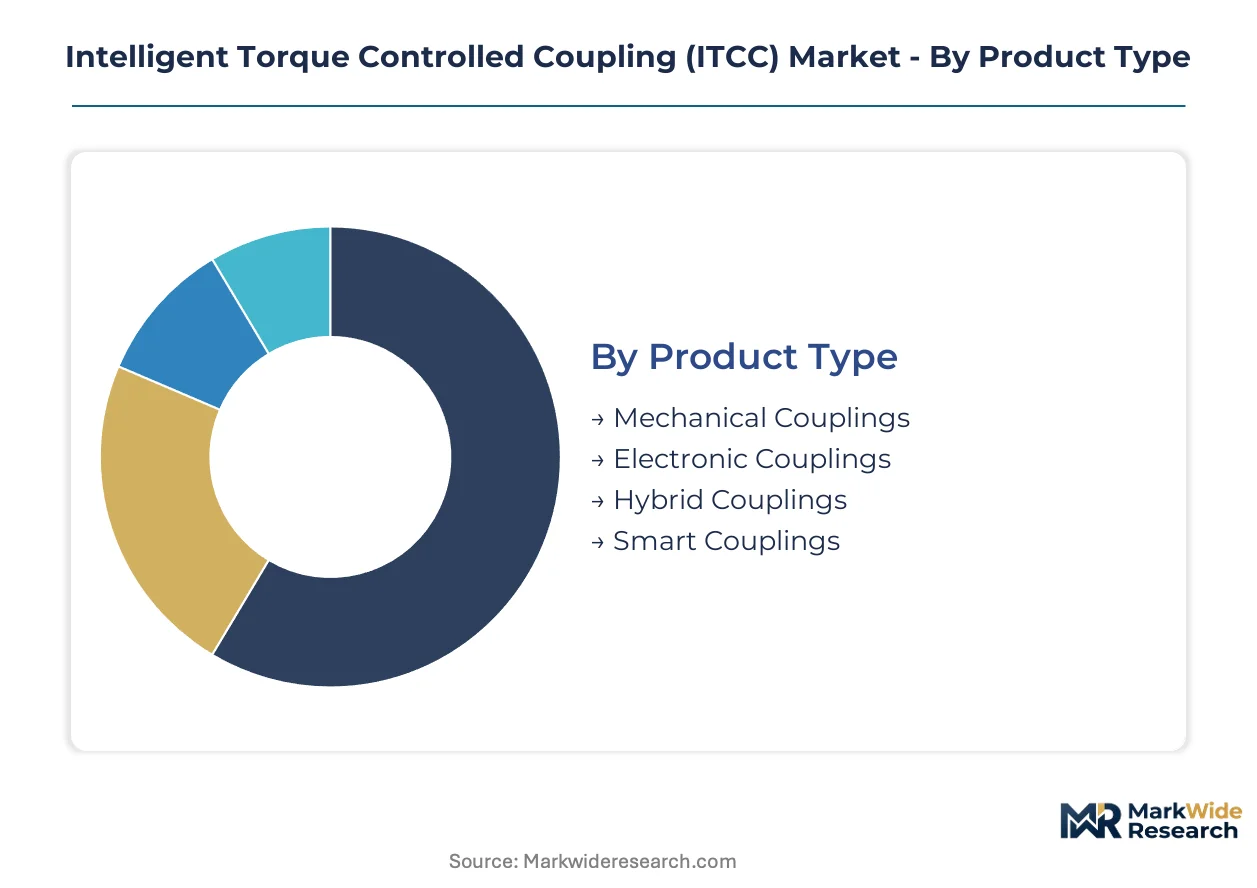
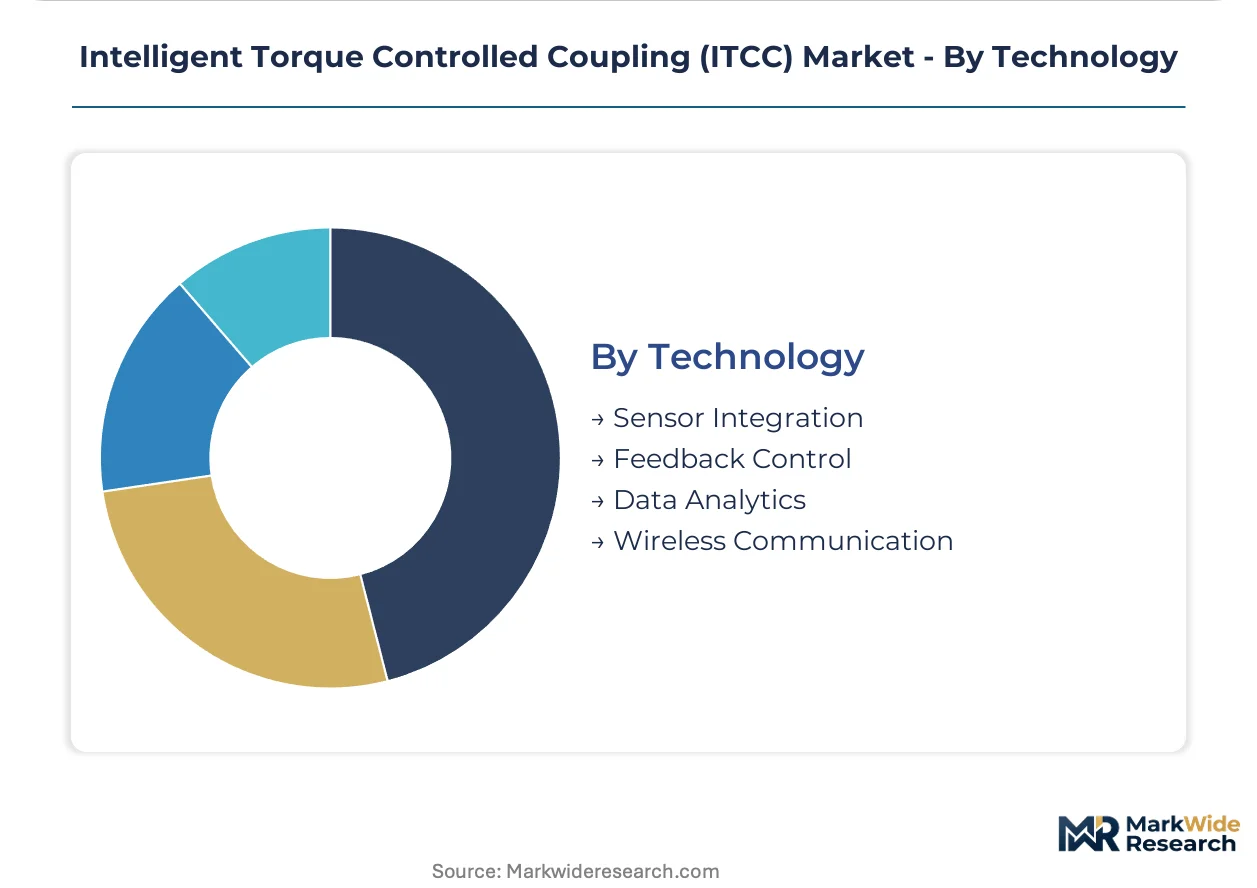
ITCC procurement patterns diverge sharply across torque ranges, response latency requirements, and firmware integration depth. Understanding these segment boundaries reveals where supplier capabilities align with buyer specifications and where capability gaps create margin compression.
Product Type:
Supply concentration in precision actuator manufacturing favors suppliers with captive sensor production and algorithm development capabilities.
- Electronic Couplings:These units deploy electromechanical actuators with real-time sensor feedback, achieving sub-100 millisecond torque modulation. Automotive OEMs in Germany and Japan are phasing out mechanical torque splitters in favor of these architectures to meet EPA fuel economy targets. Today's leader: Electronic Couplings. Tomorrow's challenger: Hybrid Couplings.
- Hybrid Couplings:Designed for seamless transitions between electric and combustion torque paths, these capture concentrated margin pools where drivetrain electrification demands dual-mode operation. OEM specifications from Stuttgart and Aichi Prefecture drive capability requirements here.
- Mechanical Couplings:Traditional torque transfer devices without electronic modulation, now relegated to cost-sensitive commercial vehicle applications in emerging markets.
- Smart Couplings:Emerging category integrating edge-computing algorithms for predictive maintenance; robotics firms in industrial automation clusters pilot adaptive joint mechanisms.
Cost tier stratification separates premium electronic architectures from commodity mechanical units, with hybrid systems commanding intermediate pricing.
Application:
Volume concentration in automotive transmission systems shapes manufacturing scale economies and supplier qualification protocols.
- Automobile Transmission:Dominant application spanning all-wheel-drive systems and torque vectoring modules. NHTSA safety mandates and ECE R13 stability directives compel precise torque modulation here. EPA Corporate Average Fuel Economy standards accelerate electronic coupling deployment across Detroit and Stuttgart manufacturing clusters.
- Industrial Machinery:Heavy equipment and process machinery employ ITCC units for load distribution and mechanical stress reduction. German precision drivetrain producers anchor European supply through vertically controlled sensor-coupling production.
- Robotics:Adaptive joint mechanisms in collaborative robots demand sub-50 millisecond response times, attracting silicon carbide power electronics integration.
- Aerospace Systems:Flight control surface actuation and landing gear systems require ASIL-D functional safety certification, extending validation timelines.
Automotive transmission absorbs the highest unit volumes; robotics applications exhibit the steepest expansion trajectory as SiC inverter integration opens new torque management architectures.
End User:
Customer type determines firmware integration depth and algorithm co-development requirements.
- Automotive OEMs:Consolidating torque management into unified electronic architectures, compressing supplier tiers and elevating subsystem integrators over discrete component vendors. German and Japanese keiretsu structures merge bearing and sensor development under single sourcing agreements.
- Manufacturing Plants:Industrial automation buyers prioritize predictive maintenance capabilities and verified low-carbon supply chains under EU Green Deal CSRD disclosure requirements.
- Aerospace Companies:Demanding traceable training data for machine learning-based torque prediction algorithms under tightening EU AI Act risk classification protocols.
- Robotics Firms:Seeking adaptive joint mechanisms with edge-computing torque algorithms; automotive-grade AI certification timelines outpace software release cycles here.
Automotive OEMs drive standardization; robotics firms pull innovation toward faster response architectures.
Technology:
Maturity gradients separate proven sensor architectures from emerging wireless and analytics capabilities.
- Sensor Integration:Core technology embedding torque, temperature, and position sensors within coupling housings. SKF Group and JTEKT Corporation leverage bearing heritage for precision sensor placement in hybrid drivetrain modules.
- Feedback Control:Real-time electromechanical actuation systems achieving 50-500 Nm torque ranges. ISO 26262 ASIL-D requirements shape electronics architecture decisions here.
- Data Analytics:Predictive maintenance algorithms processing sensor streams for failure mode anticipation. European OEMs now demand traceable training data under EU AI Act provisions.
- Wireless Communication:Emerging connectivity architecture enabling over-the-air firmware updates and cloud-based torque optimization; nascent adoption concentrated in robotics pilot programs.
Sensor integration and feedback control anchor current procurement; data analytics is climbing the fastest as predictive maintenance contracts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision drivetrain manufacturing for torque-controlled coupling systems, hosting dense supplier ecosystems that iterate rapidly on electronic torque vectoring modules for hybrid architectures.
United States
Detroit metropolitan OEMs drive electronic coupling adoption in all-wheel-drive trucks and SUVs under NHTSA crashworthiness standards. EPA Corporate Average Fuel Economy mandates compel lighter torque splitters that reduce parasitic losses. Michigan-based manufacturing clusters concentrate validation facilities for ASIL-D functional safety certification.
Germany
Baden-Württemberg precision engineering firms supply sensor-integrated couplings to Stuttgart automotive OEMs facing ECE R13 braking and stability directives. EU AI Act risk classification tightens validation protocols for machine learning-based torque prediction algorithms. SKF Group anchors European supply through vertically controlled production in Schweinfurt and Gothenburg.
Japan
Aichi Prefecture keiretsu structures merge bearing and sensor development under single sourcing agreements for hybrid drivetrain programs. METI industrial policy supports silicon carbide power electronics integration in next-generation actuators. JTEKT Corporation leverages bearing heritage to dominate precision torque vectoring modules.
India
Maharashtra and Tamil Nadu commercial vehicle hubs create entry pathways for torque management suppliers under BIS certification alignment and PLI scheme incentives. Domestic tractor and bus markets demand cost-optimized electronic couplings. Pune manufacturing corridors attract Tier 1 subsystem integrators seeking localized production.
South Korea
Gyeonggi-do battery-electric vehicle platforms test hub-mounted electric motors that threaten central coupling displacement in certain vehicle classes. MFDS automotive safety standards shape electronics architecture decisions. Seoul Capital Area R&D centers pilot silicon carbide inverter integration with coupling actuators for sub-50 millisecond response times.
Intelligent Torque Controlled Coupling (ITCC) Market Competitive Landscape
Global majors compete with regional champions across firmware-integrated torque management architectures, compressing supplier tiers as automotive OEMs consolidate procurement. Market structure tilts toward subsystem integrators with captive sensor production and algorithm development capabilities. Three archetypes dominate: bearing heritage specialists, vertically integrated mechatronics firms, and diversified automotive Tier 1 suppliers. Dominant competitive moves include strategic partnerships for silicon carbide power electronics convergence and geographic expansion into Indian commercial vehicle segments under PLI scheme incentives.
Within the bearing heritage tier, JTEKT Corporation and SKF Group occupy positions that exemplify precision sensor placement capabilities for hybrid drivetrain modules. ZF Friedrichshafen AG represents the vertically integrated mechatronics archetype, bridging mechanical torque paths with electronic architectures through unified control systems.
| Leading Market Players |
|---|
| JTEKT Corporation |
| SKF Group |
| ZF Friedrichshafen AG |
| Regal Rexnord Corporation |
| Voith GmbH |
| Continental AG |
| Ford |
| Vulkan Group |
| BorgWarner |
| Others |
Supply & Pricing Matrix
Keiretsu-backed Japanese suppliers and family-owned German precision engineering firms anchor ITCC manufacturing, creating ownership structures that resist price transparency and enforce long-term contracting discipline across Stuttgart and Aichi Prefecture production clusters.
Pricing Analysis
Neodymium and dysprosium price volatility in Chinese processing facilities transmits directly to permanent magnet actuator costs, forcing contract-based long-term offtake agreements as the dominant pricing model. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified sensor-integrated modules from basic electronic couplings and legacy mechanical units. Cost compression in economy-tier mechanical couplings is intensifying because Indian commercial vehicle buyers demand BIS-aligned certification at reduced specification levels. Commercial vehicle OEMs in Maharashtra and Tamil Nadu exhibit highest price sensitivity; German hybrid drivetrain programs show lowest sensitivity due to embedded firmware co-development requirements.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns, compelling Tier 1 subsystem integrators to establish localized production in Pune manufacturing corridors. Precision drivetrain manufacturing concentrates in Germany, Japan, and the United States, with sensor-coupling production anchored in Schweinfurt, Gothenburg, and Aichi Prefecture. Raw material dependencies rest on rare earth magnet supply from Chinese processing facilities, carbon fiber-reinforced polymer feedstock from European suppliers, and silicon carbide wafers from Japanese semiconductor foundries. Single-source vulnerability in neodymium supply creates structural risk exposure. Distribution runs through keiretsu-structured single sourcing agreements in Japan and consolidated subsystem contracts with Stuttgart OEMs in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ITCC market functions as a geographic-arbitrage play where EPA fuel economy enforcement in Detroit creates compliance-driven replacement cycles that Indian suppliers can exploit through BIS-aligned cost-optimized architectures.
For Market Incumbents: Cement captive sensor production capabilities through backward integration into torque sensor manufacturing, defending against silicon carbide power electronics convergence that elevates firmware suppliers in value capture. Add validation capacity in Michigan-based ASIL-D certification clusters to compress 18-24 month timelines that gate product releases. Lock in long-term rare earth supply contracts before Chinese processing facility volatility transmits to module margins.
For New Entrants and Emerging Players: The premium-economy price-point gap in electronic couplings creates entry space for mid-tier suppliers offering ISO 26262 ASIL-B certification at reduced firmware integration depth. Target Indian commercial vehicle segments under PLI scheme incentives where BIS certification alignment lowers barrier to entry. Pursue robotics applications demanding sub-50 millisecond response times as the most penetrable white-space, leveraging silicon carbide inverter partnerships as go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among bearing heritage specialists with precision sensor placement capabilities but limited algorithm development functions. Five-to-ten year viability hinges on firmware-hardware co-development capabilities as automotive OEMs consolidate procurement into unified electronic architectures. Watch for silicon carbide power electronics integration milestones as inflection indicator separating mechanical coupling vendors from full mechatronic subsystem suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Sub-50 millisecond response times open robotics and industrial automation applications beyond automotive. |
| ASIL-D Functional Safety Certification | Compressed validation timelines in Michigan and Stuttgart clusters accelerate product release cycles. |
| Indian PLI Scheme Manufacturing Localization | Pune corridors attract Tier 1 subsystem integrators seeking cost-optimized BIS-aligned production. |
| Carbon Fiber-Reinforced Polymer Housing Adoption | 40-60% mass reduction versus cast aluminum directly supports EPA fleet efficiency targets. |
| Predictive Maintenance Algorithm Development | EU AI Act traceable training data requirements favor suppliers with verified low-carbon supply chains. |
Research Methodology
Multiple input streams — OEM platform engineering interviews, Tier 1 supplier procurement discussions, regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged drivetrain development leads at Stuttgart and Detroit automotive clusters, sensor-coupling procurement managers at SKF Group and JTEKT Corporation, and robotics R&D directors in South Korean industrial automation centers. Secondary validation drew from EPA Corporate Average Fuel Economy compliance filings, NHTSA crashworthiness standard documentation, ECE R13 braking directive interpretations, and ISO 26262 functional safety certification databases. Bottom-up unit economics and top-down macroeconomic triangulation anchored value projections.
Historical production data cross-referenced against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include coupling architecture type, torque range tier, firmware integration depth, propulsion system compatibility, and regional manufacturing cluster. CAGRs derived from fitted growth curves applied to unit shipment trajectories, with silicon carbide adoption rates and hybrid drivetrain penetration curves serving as primary forecast inputs.
Caveats apply where rare earth magnet price volatility, ASIL-D certification timeline extensions, or hub-mounted electric motor displacement in battery-electric platforms could materially shift the outlook. A small set of named triggers — EPA regulatory stringency adjustments, EU AI Act enforcement patterns, and Indian PLI scheme renewal terms — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
France Automotive Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Door Module Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Subframe Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Australia Automotive Pneumatic Actuators Market