
 Mexico Automotive Pneumatic Actuators Market | 2026-2036
Mexico Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Pneumatic Actuators Market Foresight
Market Context
Querétaro's supplier park expansion is realigning component sourcing patterns for pneumatic actuation systems across central Mexico. Robert Bosch GmbH leverages its Guadalajara engineering center to sustain R&D proximity to major vehicle assemblers. SMC Corporation anchors its regional distribution through a dedicated facility serving Tier-1 suppliers in the Bajío corridor. Continental AG differentiates through integrated braking system modules that incorporate piston actuators for OEM platforms.
Technical Definition and Segment Structure
Mexico automotive pneumatic actuators are compressed-air-driven mechanical devices that convert pneumatic pressure into linear or rotary motion, typically operating at pressures between 40 and 120 psi to control valves, clamps, and positioning mechanisms in vehicle subsystems. These devices serve as critical motion control elements in braking, steering, and climate management assemblies where electromechanical alternatives face cost or reliability constraints at scale. Diaphragm actuators occupy the mature volume tier due to their established use in climate control and basic braking applications, while piston actuators capture higher-margin positions in steering and advanced suspension systems requiring greater force output. The OEM end user channel dominates procurement volumes, though Tier-1 suppliers increasingly specify modular setup installation methods to reduce assembly line complexity for vehicle assemblers in Puebla and Saltillo.
Regulatory Framework and Outlook
Mexico's Ministry of Economy administers PROSEC and IMMEX programs that shape duty structures for pneumatic component imports, while NOM safety standards govern actuator performance in braking and steering applications. The central bank and trade authorities monitor foreign supplier compliance with local content thresholds tied to tariff relief eligibility. Stakeholders must track evolving NOM technical specifications and IMMEX rule modifications to maintain competitive positioning in procurement decisions.
Market Dynamics
The Bajío automotive corridor's supplier park consolidation is compressing procurement radii for pneumatic actuation systems, forcing component distributors to relocate inventory nodes closer to Guanajuato and Querétaro assembly lines.
Growth Catalysts
- PROSEC Tariff Relief:Mexico's Sectoral Promotion Programs eliminate duties on precision-machined actuator housings imported from Asian supply bases, lowering landed costs for Tier-1 braking system integrators.
- Climate Control Assembly Expansion:HVAC module production in Aguascalientes is pulling diaphragm actuator volumes upward as OEMs dual-source thermal management components for North American vehicle platforms.
- Nearshoring Momentum:Foreign Tier-1 suppliers are establishing captive machining centers in Nuevo León to bypass trans-Pacific logistics congestion, creating localized demand for pneumatic subassemblies.
Market Restraints
- Aluminum Alloy Price Volatility:Piston actuator manufacturers face margin compression from fluctuating A380 aluminum ingot costs, which constitute 35-40% of raw material expenditure for force-intensive actuation products.
- Electromechanical Substitution:Brushless DC motor-actuator hybrids are capturing steering column applications where pneumatic systems previously dominated, eroding addressable market scope in chassis electronics.
- IMMEX Compliance Burden:Strict temporal export requirements under Mexico's Maquiladora program create working capital strain for suppliers holding pneumatic inventory beyond 18-month certification windows.
Strategic Opportunities
- Querétaro Supplier Park Density:Underutilized industrial parcels adjacent to existing Bosch and Continental facilities offer greenfield sites for pneumatic actuator test labs serving central Mexico's OEM cluster.
- NOM-114 Certification Gap:Fewer than twelve foreign suppliers hold current braking actuator homologation under Mexico's evolving safety standard, creating first-mover advantage for compliance-ready entrants.
- Digital Twin Integration:Convergence of pneumatic system simulation with IoT-enabled pressure monitoring is opening predictive maintenance service contracts for fleet operators in Mexican commercial vehicle segments.
Industry Challenges
- Precision Machining Talent Scarcity:CNC programming expertise for micro-finishing actuator cylinder bores remains concentrated in Monterrey and Guadalajara, constraining production scale-up in emerging Bajío supplier parks.
- Legacy Pneumatic-Electronic Interface Standards:Incompatible pressure sensor protocols between European and Asian actuator architectures force Mexican integrators to maintain dual qualification inventories, complicating assembly line flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Pneumatic Actuators Market |
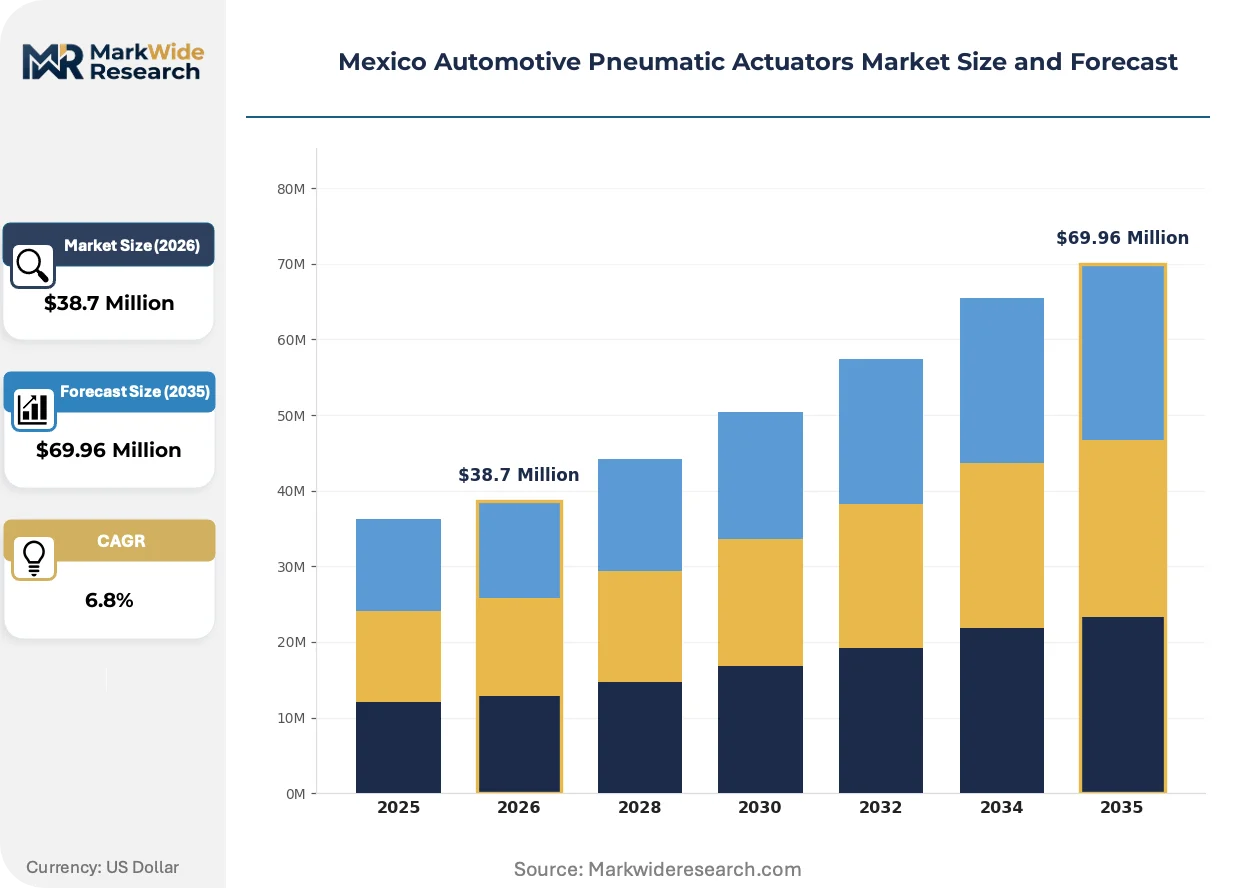
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Diaphragm Actuators, Piston Actuators, Electrical Actuators, Solenoid Actuators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application Type: Braking Systems, Steering Mechanisms, Climate Control, Suspension Systems Installation Method: Direct Mounting, Remote Mounting, Integration with ECU, Modular Setup |
| Companies Covered | ASCO Valve Inc, Schrader Duncan Limited, Robert Bosch GmbH, SMC Corporation, Bosch Rexroth AG, Continental AG, CTS Corporation, Festo AG & Co., Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Pneumatic Actuators Market Shifts & Advancements
Compressed air management architectures are undergoing modular redesign as OEMs seek to reduce assembly complexity and warranty exposure in braking and climate systems across Mexican production platforms.
Composite-reinforced polymer diaphragm technologies are consolidating traditional metal-bellows designs in climate control actuators. Tier-1 HVAC suppliers in Puebla are specifying glass-fiber nylon housings to achieve 15% weight reduction without pressure rating degradation. This materials shift is consolidating supplier tiers by eliminating secondary machining operations previously required for aluminum diaphragm cups.
NOM-114 brake system safety protocols are tightening actuator fatigue-test requirements for vehicles above 3.5 tonnes gross weight. Mexico's Ministry of Economy is aligning commercial vehicle standards with US FMVSS-121 benchmarks, forcing piston actuator redesigns for heavy-duty platforms assembled in Saltillo. The regulatory compression is accelerating homologation investment among brake system integrators serving dual US-Mexico production.
Fleet procurement departments are unbundling pneumatic actuator replacement from full-system service contracts, creating direct aftermarket channels bypassing traditional Tier-1 distribution. Large commercial vehicle operators in Nuevo León are establishing technical buying committees to source actuators independently from brake module assemblers. This disintermediation is most visible in long-haul trucking segments where pressure-actuated brake adjusters require 80,000-mile replacement cycles.
Mexico Automotive Pneumatic Actuators Market Segmentation
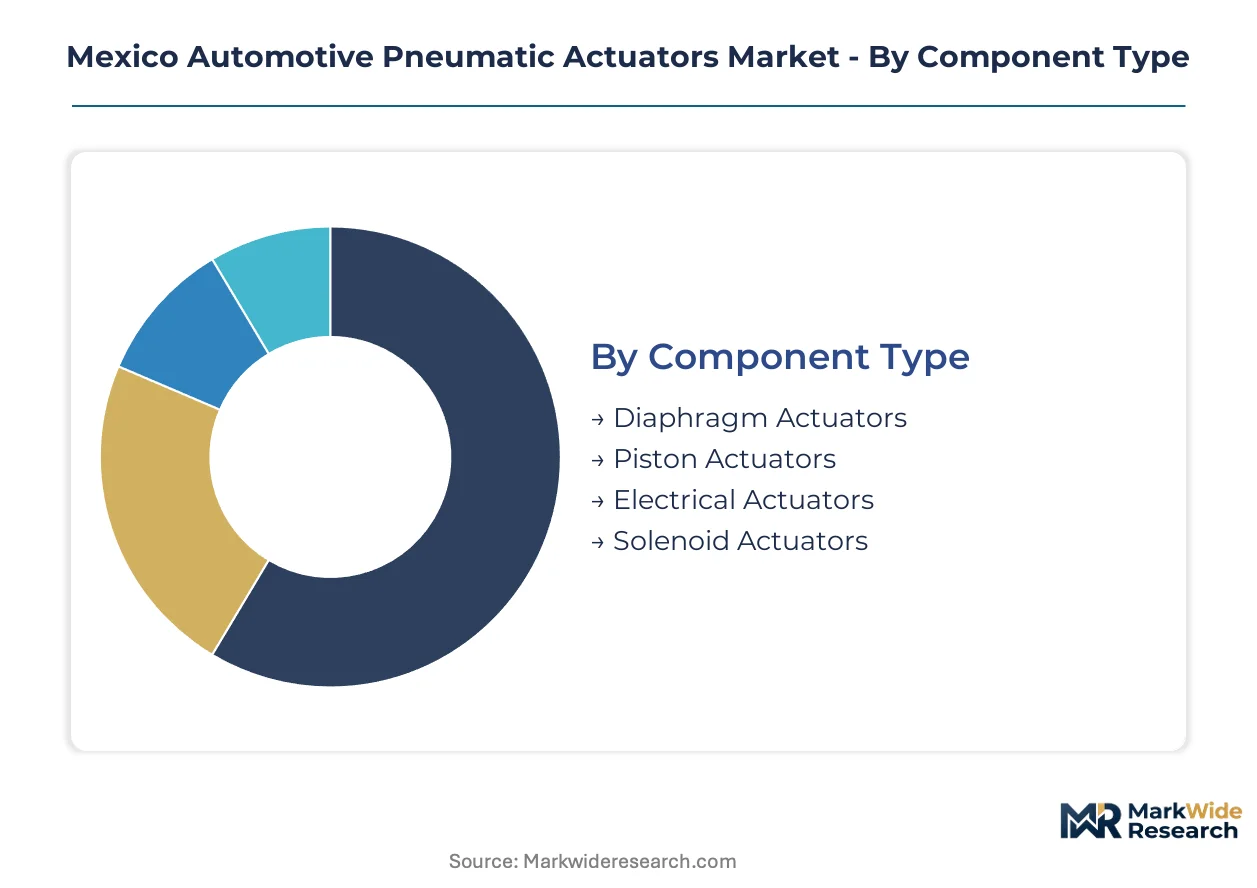
Pneumatic actuator procurement in Mexico follows distinct technical and commercial logics across component architectures, end-user channels, and vehicle subsystems. Understanding these segment boundaries clarifies where margin pools concentrate and which specification pathways dominate sourcing decisions.
Component Type:
Force output requirements and pressure tolerance thresholds drive buyer selection between diaphragm and piston architectures in Mexican braking and climate assemblies.
- Diaphragm Actuators:Flexible elastomer membranes convert pneumatic pressure into linear displacement across 40-80 psi operating ranges. Climate control module production in Aguascalientes pulls volumes upward as HVAC suppliers dual-source thermal management components for North American platforms.
- Piston Actuators:Cylindrical bore designs with precision-machined aluminum housings deliver higher force density for steering and heavy-duty braking applications. NOM-114 certification requirements for commercial vehicles above 3.5 tonnes are accelerating design refreshes among Saltillo brake system integrators.
- Electrical Actuators:Brushless DC motor hybrids are capturing steering column positions where pneumatic systems previously dominated.
- Solenoid Actuators:Electromagnetic coil designs serve rapid-response valve control in electronic braking distribution modules.
Volume sits with diaphragm designs; growth tilts toward piston actuators as commercial vehicle safety standards tighten.
End User:
Procurement authority and technical specification control vary sharply across the Mexican automotive supply chain hierarchy.
- OEMs:Vehicle assemblers in Guanajuato and Querétaro retain direct sourcing authority for safety-critical braking actuators requiring NOM homologation.
- Tier-1 Suppliers:Braking and climate system integrators in Puebla and Saltillo increasingly specify modular pneumatic subassemblies to reduce assembly line complexity for downstream customers.
- Aftermarket Providers:Fleet operators in Nuevo León are unbundling actuator replacement from full-system service contracts, creating direct procurement channels for pressure-actuated brake adjusters.
- Vehicle Assemblers:Final assembly facilities in the Bajío corridor consolidate inbound pneumatic components through supplier park consolidation strategies.
Specification authority concentrates with Tier-1 integrators; aftermarket direct procurement is expanding most quickly in long-haul commercial segments.
Application Type:
Subsystem functional requirements determine pressure range, cycle life, and environmental sealing specifications across Mexican production platforms.
- Braking Systems:Foundation brake and air disc actuators operate at 100-120 psi with fatigue-test requirements aligned to US FMVSS-121 benchmarks for dual-market production.
- Steering Mechanisms:Power steering assist actuators face displacement pressure from electromechanical rack-drive systems in passenger vehicle platforms.
- Climate Control:HVAC blend door and recirculation actuators prioritize low-pressure precision over force output, favoring diaphragm architectures.
- Suspension Systems:Active height adjustment actuators serve premium vehicle platforms with higher per-unit value but lower volume concentration.
Braking applications dominate unit volumes; climate control assemblies are gaining share fastest as thermal management module production expands.
Installation Method:
Assembly line integration preferences are shifting toward reduced touch labor and simplified quality verification protocols.
- Direct Mounting:Flange-attached actuators with pre-set pressure ports minimize field calibration requirements for high-volume braking module production.
- Remote Mounting:Flexible hose-connected configurations accommodate space-constrained engine bay layouts in compact vehicle platforms.
- Integration with ECU:Pressure sensor feedback loops require compatible electronic protocols, forcing dual qualification inventories among Mexican integrators.
- Modular Setup:Pre-tested pneumatic subassemblies arrive at Guanajuato assembly lines as sealed units, reducing warranty exposure for OEM quality departments.
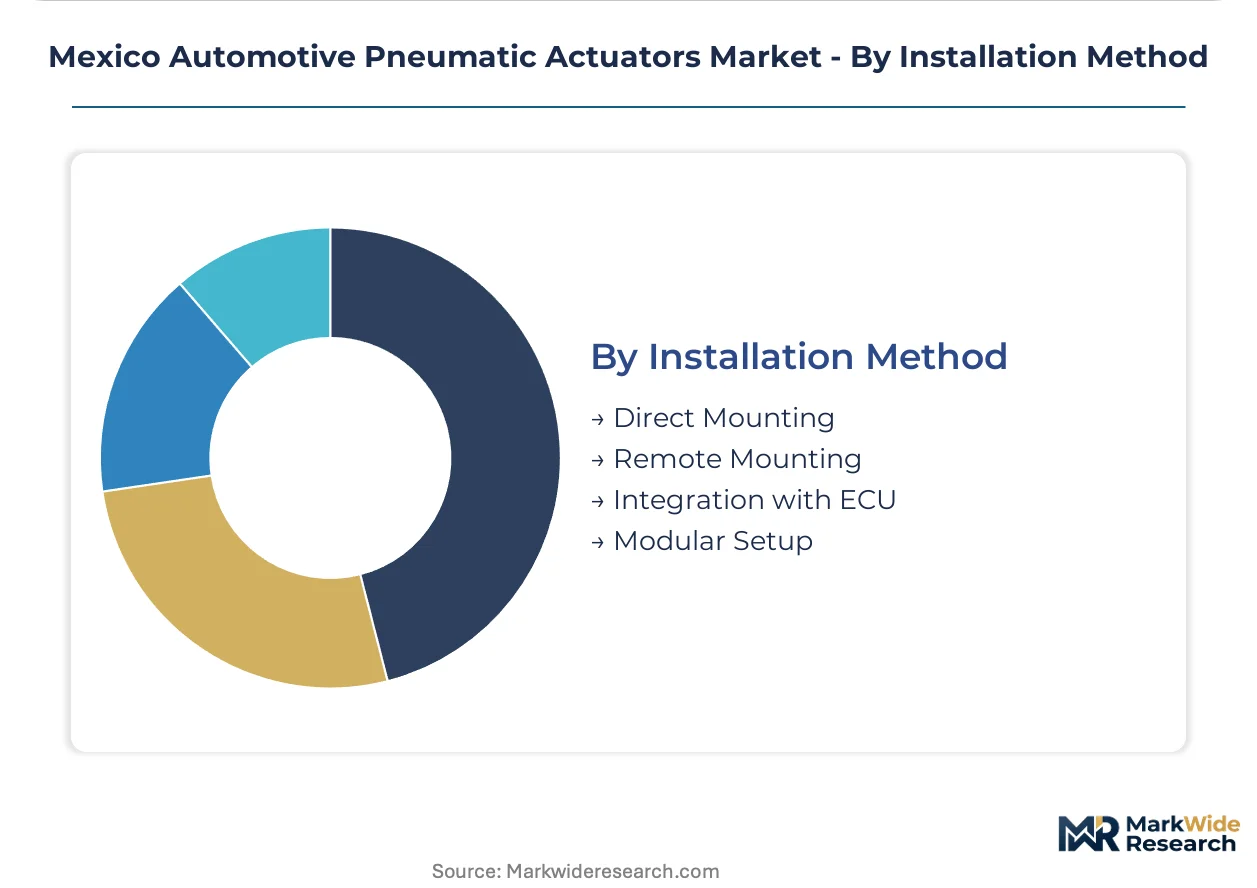
Direct mounting retains volume leadership; modular setup approaches are climbing the fastest as supplier park proximity compresses logistics lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum ingot supply from Guanajuato's smelter network anchors pneumatic actuator fabrication across central Mexico, with A380 alloy flows feeding precision machining clusters in the Bajío corridor.
Nuevo León
Monterrey's metalworking base supplies machined actuator housings to brake system integrators serving Saltillo heavy-duty truck plants. The state's IMMEX program administration accelerates duty-free component imports for Tier-1 suppliers establishing captive machining centers. Apodaca's industrial park concentration hosts foreign suppliers bypassing trans-Pacific logistics through nearshored production.
Guanajuato
Passenger vehicle OEM expansion in Silao and Irapuato pulls diaphragm actuator volumes for climate control module assembly. PROSEC tariff relief on precision-machined housings lowers landed costs for braking system suppliers. The León supplier park corridor compresses procurement radii, forcing distributors to relocate inventory nodes closer to assembly lines.
Querétaro
Aerospace-adjacent precision machining expertise transfers to automotive actuator cylinder bore finishing for steering applications. The state's supplier park expansion realigns component sourcing patterns across central Mexico. El Marqués industrial zone offers greenfield sites for pneumatic test labs serving the OEM cluster.
Jalisco
Robert Bosch GmbH leverages its Guadalajara engineering center to sustain R&D proximity to major vehicle assemblers. The metropolitan area's CNC programming talent pool supports micro-finishing operations for force-intensive piston actuators. Tonalá machining subcontractors serve brake module producers in neighboring states.
Aguascalientes
HVAC module production expansion pulls diaphragm actuator demand upward as OEMs dual-source thermal management components. The state's automotive corridor position links Bajío assembly operations with northern border export logistics. Local Tier-1 suppliers specify glass-fiber nylon housings to achieve weight reduction in climate control assemblies.
Mexico Automotive Pneumatic Actuators Market Competitive Landscape
Global majors compete with regional champions across distribution reach and homologation expertise, producing a tiered structure where European system integrators hold safety-critical braking positions while Asian component specialists capture climate control volumes. The vendor base separates into three archetypes: full-system integrators with NOM certification depth, modular subassembly suppliers leveraging PROSEC tariff engineering, and aftermarket-focused distributors serving fleet unbundling trends. Competitive moves concentrate on supplier park co-location for logistics compression and backward integration into aluminum precision casting to hedge A380 price volatility.
Within the full-system integrator tier, Continental AG and Robert Bosch GmbH exemplify European majors with established NOM-114 homologation pathways for commercial vehicle braking. SMC Corporation anchors the Asian specialist archetype through regional distribution infrastructure serving Tier-1 clusters. Bosch Rexroth AG occupies a position spanning both hydraulic and pneumatic motion control, reflecting portfolio diversification strategies among German industrial conglomerates.
| Leading Market Players |
|---|
| ASCO Valve Inc |
| Schrader Duncan Limited |
| Robert Bosch GmbH |
| SMC Corporation |
| Bosch Rexroth AG |
| Continental AG |
| CTS Corporation |
| Festo AG & Co. |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
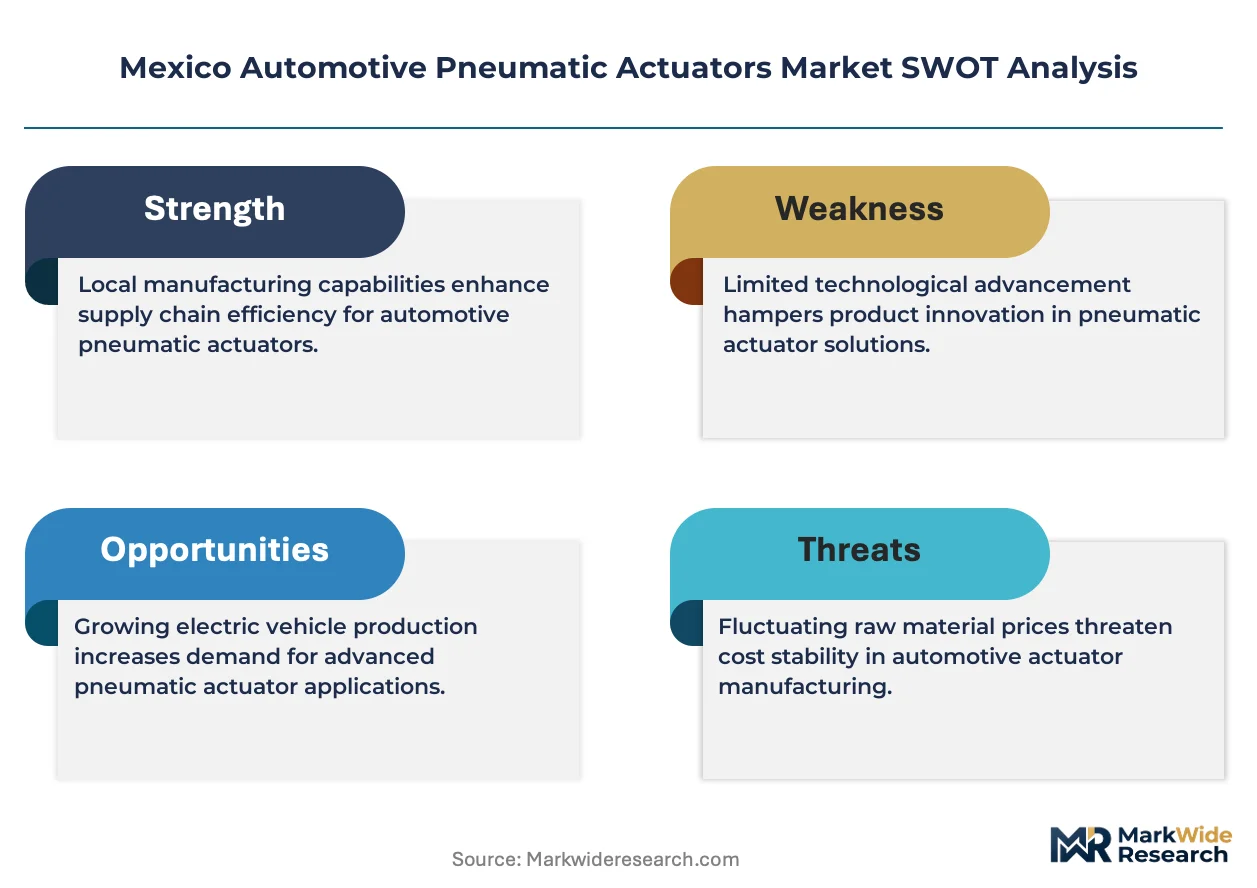
A380 aluminum ingot price volatility cascades through Mexican pneumatic actuator supply chains, compressing margins for piston actuator manufacturers while PROSEC tariff engineering creates pricing separation between duty-advantaged Tier-1 integrators and captive importers facing full landed cost exposure.
Pricing Analysis
Warranty bundling versus unbundled component sales defines pricing architecture across Mexican procurement channels. OEMs purchasing modular brake subassemblies absorb integrated warranty costs, while fleet operators sourcing direct aftermarket actuators face unbundled replacement pricing without system-level coverage. Price differentiation rests on NOM-114 certification status and volume scale, with homologated suppliers commanding premium positioning over uncertified competitors. Pricing pressure intensifies from electromechanical substitution in steering applications, forcing pneumatic specialists to absorb margin compression in chassis electronics segments. Aftermarket fleet buyers exhibit highest price sensitivity, prioritizing per-unit cost over lifecycle service agreements.
Supply Chain Analysis
Regional distribution centers in Querétaro and Guanajuato anchor hub-and-spoke inventory networks serving Bajío corridor assembly lines. Supply concentration draws from China, Germany, and domestic Mexican machining clusters for precision actuator housings. Raw material dependencies center on A380 aluminum ingots, elastomer diaphragm compounds, and precision-machined cylinder bores. Single-source vulnerability persists for NOM-certified brake actuators, where fewer than twelve foreign suppliers hold current homologation. Distribution runs through Tier-1 system integrators consolidating pneumatic subassemblies for OEM direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's automotive pneumatic actuator market is consolidating into a vertical-integration race where control over aluminum precision casting and NOM certification pathways determines sustainable margin capture.
For Market Incumbents: Anticipate electromechanical displacement in steering applications by deepening backward integration into aluminum casting operations in Guanajuato, hedging A380 price volatility through captive smelter relationships. Reinforce NOM-114 certification depth as a defensive moat against Asian competitors lacking homologation infrastructure. Priority lever centers on supplier park co-location with Bosch and Continental facilities to compress logistics lead times below emerging competitor reach. For New Entrants and Emerging Players: Digital twin integration for predictive maintenance contracts offers technology-first wedge into commercial vehicle fleet segments in Nuevo León, where operators are unbundling actuator procurement from brake system integrators. Target climate control diaphragm supply to Aguascalientes HVAC module producers, where dual-sourcing mandates create penetrable white space. Go-to-market angle emphasizes glass-fiber nylon housing specifications achieving weight reduction without pressure rating degradation. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining specialists with existing NOM brake actuator homologation in Querétaro's aerospace-adjacent supplier parks. Long-term viability hinges on 5-10 year platform standardization timelines across North American OEM production. Acquisition target archetype: mid-cap CNC finishing operations with latent automotive certification capacity. Signal to watch: IMMEX program modifications altering 18-month export window compliance burdens for inventory-heavy suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Casting | Captive A380 supply hedges raw material volatility for piston actuator manufacturers serving Saltillo heavy-duty plants. |
| NOM-114 Certification Investment | First-mover homologation advantage opens commercial vehicle braking positions above 3.5 tonnes gross weight. |
| Supplier Park Co-location | Proximity to Guanajuato and Querétaro assembly lines compresses procurement radii below distributor relocation thresholds. |
| Digital Twin Service Contracts | IoT-enabled pressure monitoring creates recurring revenue streams from Nuevo León long-haul fleet operators. |
| Composite Diaphragm Materials Transition | Glass-fiber nylon specifications eliminate secondary machining for Aguascalientes climate control module suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining structured interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and CNC machining subcontractors. Primary fieldwork validated production volume assumptions across Guanajuato, Querétaro, and Nuevo León assembly corridors. Secondary sources incorporated Mexico's Ministry of Economy PROSEC and IMMEX program documentation, NOM technical specifications, aluminum ingot price benchmarks, and vehicle production databases. Bottom-up actuator shipment estimates triangulated against top-down OEM platform content analysis.
Granularity-level modeling addressed component type distinctions between diaphragm and piston architectures, end-user channel bifurcation across OEM direct and aftermarket fleet procurement, and application segmentation across braking, steering, climate control, and suspension systems. CAGRs derived from production volume trajectories, content-per-vehicle assumptions, and platform lifecycle timing across the projection horizon. Industry-specific forecast inputs included NOM-114 regulatory alignment timelines, nearshoring investment flows into Nuevo León machining centers, and HVAC module production expansion in Aguascalientes.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, abrupt IMMEX rule modifications, and electromechanical substitution acceleration beyond current displacement patterns. Forecasts reflect documented assumptions regarding aluminum price stabilization and PROSEC program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Auto Fender Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Europe Automotive Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive Solenoid Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Seat Frame Market