
 Intelligent Rubber Tracks Market | 2026-2036
Intelligent Rubber Tracks Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Rubber Tracks Market Outlook
ISO 9001 quality certification is unwinding the competitive landscape for intelligent rubber tracks, forcing smaller suppliers to upgrade process documentation or exit OEM supply chains. Camso leverages its vertically integrated rubber compounding network across North American and European plants. Bridgestone sustains R&D intensity through dedicated materials science labs focused on aramid-reinforced track belts. Continental competes on embedded sensor integration, combining strain gauges with wireless telemetry modules for real-time wear monitoring.
Intelligent rubber tracks are composite propulsion systems comprising vulcanized rubber compounds reinforced with steel cables or textile layers, manufactured through calendering and continuous curing processes to deliver traction with minimal ground disturbance for off-road vehicles. Their primary purpose is enabling heavy equipment mobility across soft, uneven, or sensitive terrain while transmitting operational data through integrated electronics. Heavy-duty tracks dominate mining and large construction applications where load-bearing capacity determines replacement cycles and service revenue pools. GPS Tracking and Smart Sensors represent the fastest-expanding technology pairing, as fleet operators prioritize location-aware predictive maintenance over basic telematics. Lightweight tracks occupy a narrower but higher-margin niche in landscaping and turf-care equipment where surface damage avoidance commands premium pricing.
EPA emission standards for non-road diesel equipment indirectly shape track demand by extending machine replacement intervals and increasing attachment-level intelligence requirements. EMA's machinery directives in Europe enforce electromagnetic compatibility for onboard electronics, raising design barriers for sensor-integrated track systems. OSHA workplace safety regulations in the United States mandate rollover and stability monitoring, creating compliance pathways for intelligent tracks with tilt and vibration sensing. Stakeholders must weigh the capital intensity of embedding IoT modules against the recurring revenue potential of subscription-based fleet analytics platforms.
Market Dynamics
Sensor-embedded rubber track systems are restructuring competitive advantage around predictive maintenance data streams rather than commodity replacement cycles. OEMs now bundle telemetry-enabled tracks with fleet management subscriptions, shifting revenue from hardware margins to recurring analytics fees.
Growth Catalysts
- EMA Electromagnetic Compatibility Directives:European machinery safety mandates are accelerating sensor integration as a compliance pathway for construction and mining equipment manufacturers.
- Aramid-Reinforced Belt Construction:Advanced textile reinforcement extends track service intervals in high-load mining applications, reducing total cost of ownership for fleet operators.
- Precision Agriculture Corridor Concentration:Germany's intensive farming belt is concentrating demand for lightweight turf-protecting tracks with embedded soil compaction sensors.
Market Restraints
- Steel Cable Input Volatility:Fluctuating metallurgical commodity prices compress compounding margins for track belt manufacturers dependent on high-tensile cord supplies.
- F-Gas Regulatory Friction:Europe's phasedown of fluorinated greenhouse gases forces reformulation of specialized rubber curing agents, extending R&D validation timelines.
- Pneumatic Tire Substitution:Advanced airless radial tire designs threaten track adoption in select construction sub-segments where surface damage tolerance is higher.
Strategic Opportunities
- India Agricultural Mechanization:Tractor fleet expansion in Punjab and Haryana states creates unmet demand for affordable sensor-enabled tracks compatible with smallholder equipment scales.
- 5G-IoT Convergence:Low-latency cellular connectivity enables real-time strain monitoring and automated wear-threshold alerts previously impractical with earlier telemetry generations.
- OSHA Rollover Compliance Pathway:US workplace safety mandates for stability monitoring create embedded sensor demand in heavy construction verticals.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:Track manufacturers face acute shortages of firmware developers capable of integrating wireless modules with vulcanized rubber environments.
- ISO 9001 Certification Burden:Process documentation requirements for OEM supply chain entry impose capital and timeline penalties on smaller compounders lacking quality management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Rubber Tracks Market |
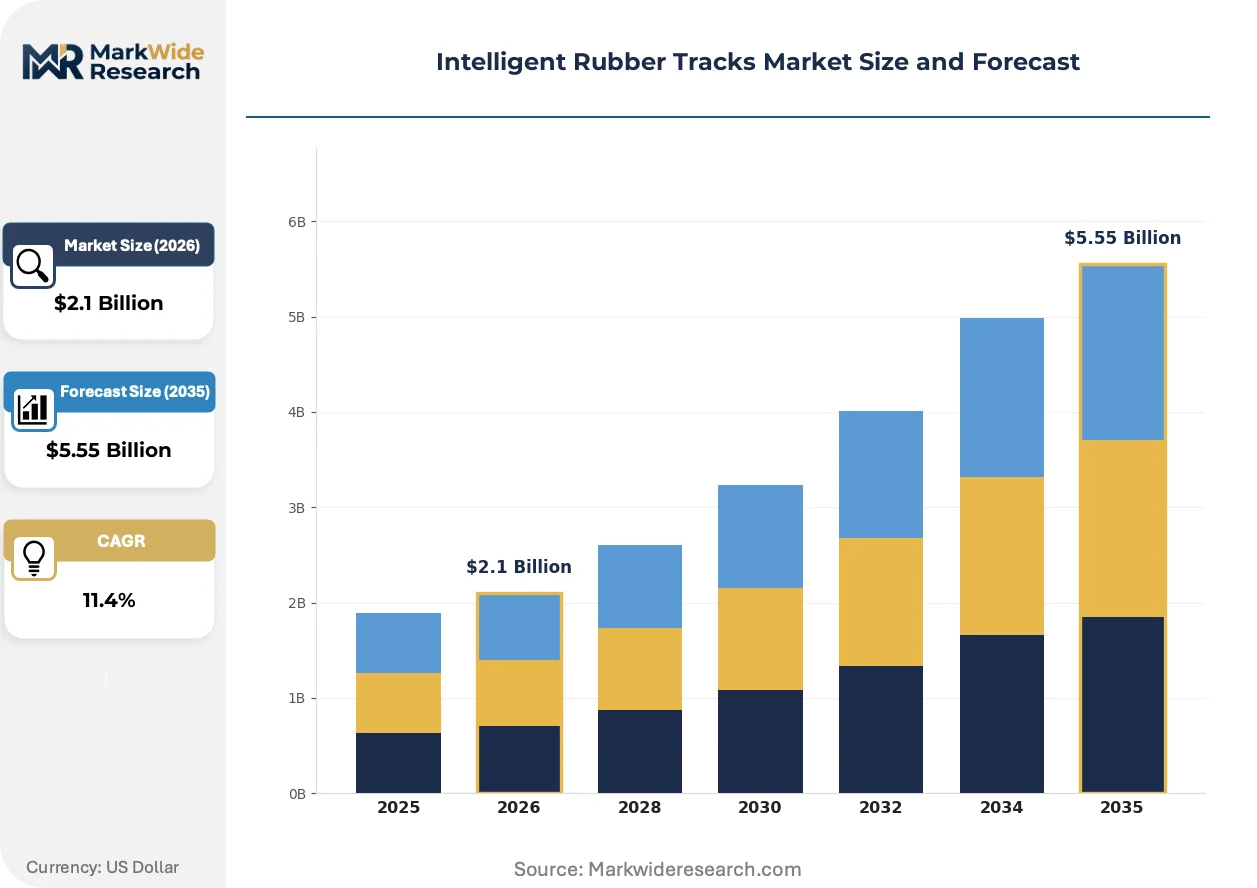
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tracks, Heavy-Duty Tracks, Lightweight Tracks, Multi-Surface Tracks End User: Agriculture, Construction, Landscaping, Mining Technology: GPS Tracking, Smart Sensors, Telemetry, IoT Integration Deployment: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | Camso, Bridgestone, Continental, McLaren Industries, Soucy, DRB, Chermack Machine, Mattracks, VTS Track Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Rubber Tracks Market Strategic Shifts
Digital thread integration across track lifecycle management is displacing discrete component sales with continuous performance-based relationships between suppliers and fleet operators.
Multi-layer strain gauge arrays embedded directly into rubber carcasses during calendering operations are fragmenting the traditional aftermarket. Mining contractors in Western Australia and Chile's Atacama operations are adopting these systems fastest, demanding predictive failure alerts rather than scheduled replacements. The technology is fragmenting service revenue pools away from distributors toward original equipment manufacturers capturing telemetry subscriptions.
Europe's F-Gas Regulation is forcing compound reformulation across vulcanization processes. Manufacturers must eliminate hydrofluorocarbon-based blowing agents from track production while maintaining density specifications for load-bearing performance. German and Italian rubber processors are responding fastest, securing early-mover positions in lower-emission track supply chains before 2030 phase-down deadlines tighten.
Fleet procurement departments are consolidating vendor relationships around integrated track-telemetry-data bundles. Construction equipment lessors in Texas and North Dakota are abandoning spot-buy replacement patterns for multi-year performance contracts covering hardware, installation, monitoring, and removal. This behavioral shift concentrates purchasing power with vertically integrated suppliers capable of underwriting full-lifecycle service commitments.
Intelligent Rubber Tracks Market Segmentation
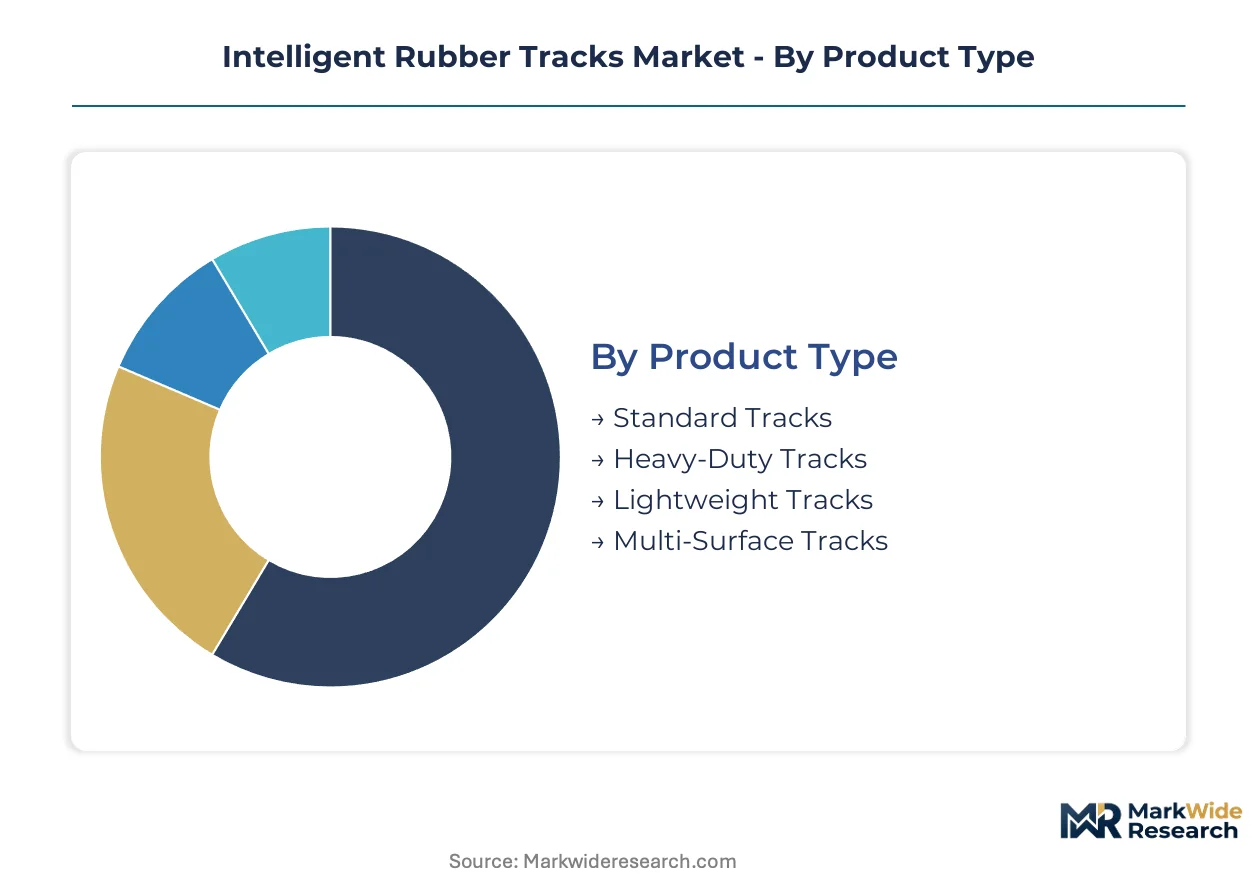
Segmentation in intelligent rubber tracks reveals how value migrates from commodity replacement parts toward data-enabled service ecosystems. Product architecture, end-use intensity, and embedded technology sophistication each create distinct margin architectures that suppliers must navigate.
Product Type:
Margin pools concentrate in applications where load-bearing specifications and sensor integration complexity intersect, rewarding compounders with materials science and electronics capabilities.
- Heavy-Duty Tracks:Steel-cable reinforced vulcanized rubber carcasses engineered for mining and large construction equipment. Western Australian iron ore operations and Chilean copper extraction drive specification intensity, with aramid textile hybrids gaining traction where extended service intervals justify premium positioning.
- Lightweight Tracks:Reduced ground pressure designs employing multi-layer textile reinforcement without steel cord. Germany's precision agriculture corridor concentrates procurement for turf-care and vineyard equipment where surface damage avoidance commands pricing power.
- Standard Tracks:Baseline construction-grade configurations serving mid-tier equipment fleets.
- Multi-Surface Tracks:Variable tread geometries optimized for terrain adaptability in mixed-use machinery.
Heavy-Duty Tracks hold installed capacity. Lightweight Tracks is rotating up the share rankings.
End User:
Volume concentration follows capital equipment replacement cycles, with mining and construction exhibiting longer purchase intervals but higher per-unit telemetry attachment rates.
- Construction:Earthmoving and lifting equipment fleets demanding predictive maintenance integration. Texas and North Dakota equipment lessors are consolidating procurement around multi-year performance contracts bundling hardware, monitoring, and removal services.
- Mining:Ultra-heavy load applications where strain gauge arrays embedded during calendering enable failure prediction. Contractors in Western Australia's Pilbara region and Chile's Atacama Desert are adopting these systems fastest, fragmenting aftermarket revenue toward OEM telemetry subscriptions.
- Agriculture:Tractor and harvester applications with soil compaction sensing requirements.
- Landscaping:Turf protection and noise-sensitive urban equipment.
Construction dominates current procurement volume. Mining is climbing the fastest on data service attach rates.
Technology:
Embedded electronics capability is becoming the primary vendor selection criterion as fleet operators prioritize operational visibility over base durability metrics.
- Smart Sensors:Multi-layer strain gauge arrays and accelerometers embedded directly into rubber carcasses during manufacturing. Real-time wear monitoring and automated threshold alerts are displacing scheduled replacement patterns in high-availability mining operations.
- GPS Tracking:Location-aware fleet management enabling geofencing and utilization optimization. European construction lessors leverage this pairing for equipment security and logistics coordination across dispersed job sites.
- Telemetry:Wireless data transmission modules integrated with vehicle CAN bus systems.
- IoT Integration:Full platform connectivity enabling predictive analytics and third-party fleet management software interoperability.
Smart Sensors holds technology leadership. GPS Tracking is gaining share fastest through bundling with fleet management subscriptions.
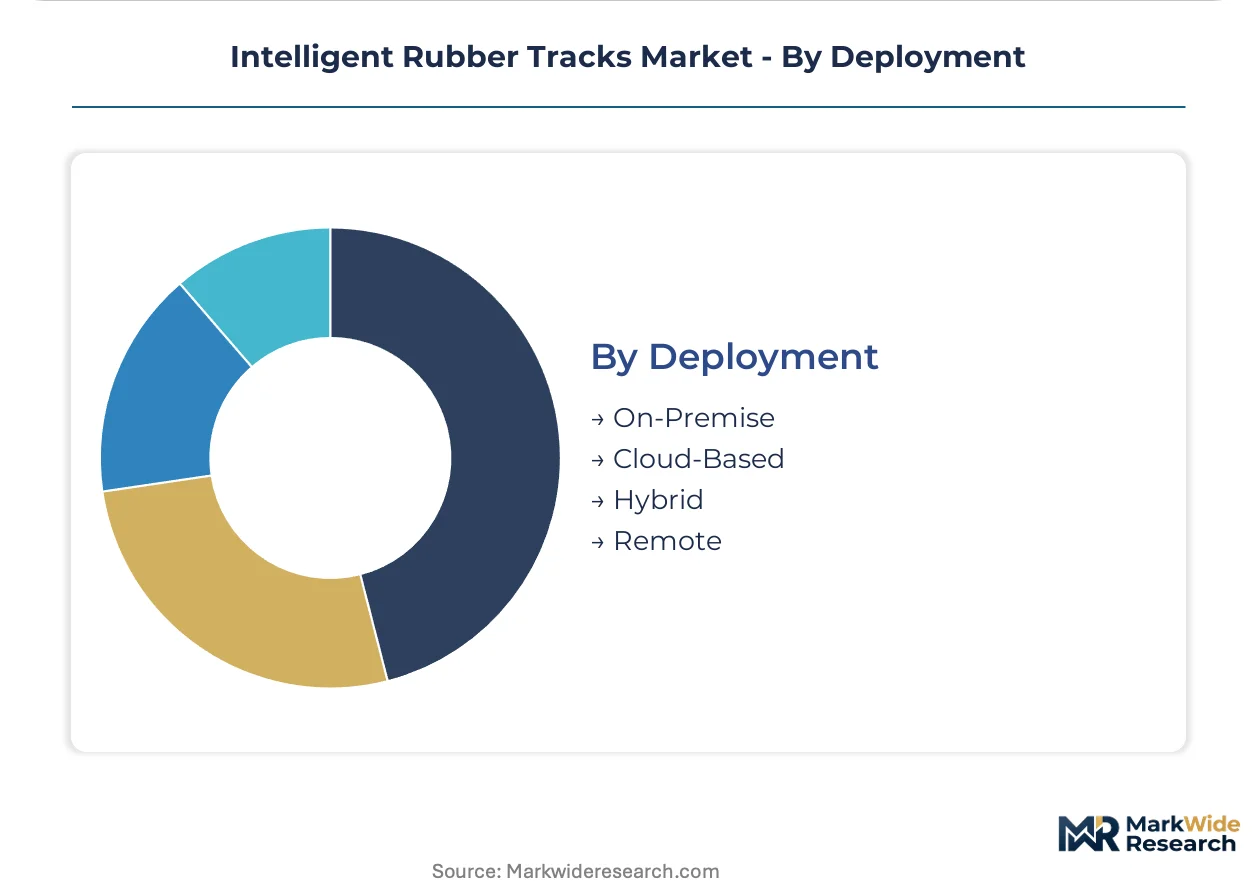
Deployment:
Data architecture choices reflect fleet scale, IT infrastructure maturity, and cybersecurity posture across operator profiles.
- Cloud-Based:Centralized data processing with subscription analytics access. Large construction lessors in North America and Europe prefer this model for multi-site fleet visibility and reduced on-site IT burden.
- Hybrid:Edge processing for critical alerts with cloud aggregation for longitudinal analysis. Mining operators in remote geographies with intermittent connectivity favor this architecture for operational continuity.
- On-Premise:Local data retention for cybersecurity-sensitive operators.
- Remote:Satellite or cellular backhaul for geographically dispersed equipment.
Cloud-Based holds current deployment majority. Hybrid is expanding most quickly among security-conscious industrial operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment lessors in Texas and North Dakota anchor procurement volume for telemetry-enabled track systems. Mining contractors across Western Australia's Pilbara region and Chile's Atacama Desert drive specification intensity for predictive maintenance integration. Precision agriculture operators in Germany's intensive farming belt concentrate demand for soil-compaction-sensing lightweight configurations.
United States
Construction equipment lessors in Texas and North Dakota are consolidating vendor relationships around multi-year performance contracts bundling hardware, installation, monitoring, and removal services. OSHA workplace safety mandates for rollover and stability monitoring create compliance pathways for intelligent tracks with embedded tilt and vibration sensing. EPA emission standards for non-road diesel equipment extend machine replacement intervals and intensify attachment-level intelligence requirements.
Germany
Precision agriculture operators in Germany's intensive farming belt concentrate procurement for lightweight turf-protecting tracks with embedded soil compaction sensors. Europe's F-Gas Regulation forces reformulation of specialized rubber curing agents, extending R&D validation timelines for compounders. Rubber processors in German industrial clusters are securing early-mover positions in lower-emission track supply chains before 2030 phase-down deadlines tighten.
Australia
Mining contractors in Western Australia's Pilbara region are adopting multi-layer strain gauge arrays fastest, demanding predictive failure alerts rather than scheduled replacements. The country's national mining safety regulator enforces equipment integrity standards that accelerate sensor-integrated track adoption for operational continuity. Perth-based fleet operators are fragmenting aftermarket revenue toward OEM telemetry subscriptions through real-time wear monitoring contracts.
Chile
Copper extraction operations in Chile's Atacama Desert drive specification intensity for heavy-duty tracks with aramid textile hybrids where extended service intervals justify premium positioning. The country's national mining regulator mandates equipment monitoring protocols that align with embedded sensor capabilities. Antofagasta-based contractors are consolidating purchasing power around vertically integrated suppliers capable of underwriting full-lifecycle service commitments.
India
Tractor fleet expansion in Punjab and Haryana states creates unmet demand for affordable sensor-enabled tracks compatible with smallholder equipment scales. The country's agricultural mechanization programs subsidize precision farming technology adoption. Ludhiana-based equipment fabricators are responding with simplified telemetry configurations that bridge cost barriers for mid-tier fleet operators.
Intelligent Rubber Tracks Market Competitive Environment
Player mix skews toward vertically integrated rubber compounders with captive steel cord and textile reinforcement capabilities. The competitive structure concentrates around three strategic tiers: premium sensor-integrated system suppliers, mid-market construction-grade fabricators, and regional agricultural equipment specialists. Dominant competitive moves include backward integration into rubber compounding networks and technology licensing partnerships for wireless telemetry module integration.
Within the premium integrated tier, Camso leverages its vertically integrated rubber compounding network across North American and European plants. Bridgestone occupies a position exemplifying sustained R&D intensity through dedicated materials science capabilities. Continental anchors the embedded electronics vector, combining strain gauges with wireless telemetry modules for real-time wear monitoring. These three represent the dominant archetypes: compounder-integrators, materials science laboratories, and sensor-platform developers.
| Leading Market Players |
|---|
| Camso |
| Bridgestone |
| Continental |
| McLaren Industries |
| Soucy |
| DRB |
| Chermack Machine |
| Mattracks |
| VTS Track Solutions |
| Others |
Value Chain & Pricing Dynamics
ISO 9001 certification gates both OEM supply chain entry and price differentiation simultaneously, forcing smaller compounders to absorb documentation costs or surrender margin to accredited competitors. This quality mandate concentrates purchasing power with vertically integrated suppliers capable of underwriting full-lifecycle service commitments while fragmenting aftermarket revenue toward telemetry-enabled system providers.
Pricing Analysis
Cost-plus contracts with steel cord indexation dominate heavy-duty track procurement, insulating manufacturers from metallurgical commodity swings while passing volatility through to mining and construction fleet operators. Price differentiation rests on ISO 9001 certification tier and embedded sensor integration depth, with telemetry-enabled systems commanding substantial premiums over baseline replacement configurations. Cost compression in standard-grade construction tracks is intensifying because pneumatic tire substitution threats limit pricing power in surface-damage-tolerant applications. Smallholder agricultural operators in India exhibit highest price sensitivity, whereas Australian mining contractors prioritize predictive maintenance value over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports fluctuate with container availability across Asia-Europe trade lanes, compounding margin pressure for German and Italian rubber processors dependent on Asian steel cord shipments. Manufacturing concentrates in Germany, Italy, and the United States, with aramid textile reinforcement sourcing anchored in North American and European chemical plants. Supply chain risk centers on single-source vulnerability for high-tensile cord supplies from specialized metallurgical producers. Distribution runs through OEM captive channels and authorized aftermarket service networks, with fleet lessors consolidating procurement around multi-year performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent rubber tracks represent a high-growth disruption as 5G-IoT convergence enables real-time strain monitoring previously impractical with earlier telemetry generations. This technological inflection shifts competitive advantage from commodity replacement cycles toward predictive maintenance data streams and recurring analytics revenue.
For Market Incumbents: Consolidate rubber compounding capabilities through backward integration into captive steel cord and textile reinforcement networks, defending against pneumatic tire substitution threats in construction sub-segments. Deepen sensor-platform development through firmware engineering talent acquisition, securing ISO 9001 certification barriers against smaller compounders lacking quality management infrastructure. Prioritize multi-year performance contract underwriting to capture fleet procurement consolidation in Texas and North Dakota equipment leasing markets. For New Entrants and Emerging Players: Differentiate on affordable telemetry configurations tailored to smallholder tractor fleets in India's Punjab and Haryana states, where agricultural mechanization subsidies bridge cost barriers for mid-tier operators. Target Germany's precision agriculture corridor with lightweight turf-protecting tracks featuring simplified soil compaction sensing. Pursue technology licensing partnerships for wireless module integration rather than captive embedded systems development. For Investors and Strategic Acquirers: Europe's F-Gas Regulation reshapes the acquisition landscape toward lower-emission rubber compounders with validated reformulation pipelines ahead of 2030 phase-down deadlines. Long-term viability favors vertically integrated suppliers combining materials science capabilities with sensor-platform development. The signal to watch is mining contractor adoption velocity for predictive failure alert systems in Western Australia's Pilbara region and Chile's Atacama Desert.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Camso's North American and European plant network secures captive supply of specialized vulcanized compounds. |
| Embedded Sensor Platform Development | Continental's strain gauge and wireless telemetry integration enables real-time wear monitoring subscriptions. |
| Aramid-Reinforced Belt Construction | Bridgestone's materials science laboratories extend service intervals for high-load mining applications. |
| Multi-Year Performance Contract Underwriting | Construction lessors in Texas consolidate vendor relationships around bundled hardware, monitoring, and removal services. |
| Lower-Emission Compound Reformulation | German and Italian processors secure early-mover positions ahead of F-Gas Regulation 2030 deadlines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings, equipment production databases, and industry association reports covering construction and mining machinery. Primary interviews engaged OEM procurement teams, fleet maintenance directors, rubber compound plant managers, and aftermarket service heads across North America, Europe, and Asia-Pacific. Bottom-up unit shipment estimates triangulate against top-down equipment fleet penetration analysis.
Segmentation dimensions modeled include product architecture, end-use intensity, embedded technology sophistication, and deployment architecture across the projection horizon. CAGRs derive from equipment replacement cycle analysis, technology adoption curve modeling, and regulatory compliance timeline assessment. Forecast inputs incorporate metallurgical commodity price trajectories, 5G network rollout schedules, and precision agriculture subsidy program expansions.
The analysis sits within stated boundaries; outcomes outside sustained mining capital expenditure levels, F-Gas Regulation enforcement intensity, or 5G-IoT convergence timelines would require recalibration. Forecasts reflect documented assumptions regarding sensor integration cost curves and fleet operator willingness-to-pay for predictive maintenance subscriptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Car Sunshade Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
HCV Axles Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Rear Axle Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Idler Arm Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Self Loading Trailer Market