
 Mexico Automotive EPS Market | 2026-2036
Mexico Automotive EPS Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive EPS Market Foresight
Buyer concentration among Mexico-based OEM assembly operations is decoupling from legacy supplier hierarchies as new crossover and SUV platforms multiply nearshored capacity. Robert Bosch GmbH leverages its integrated sensor-to-actuator architecture to anchor high-volume contracts with transplant manufacturers in Querétaro and Guanajuato. Nexteer Automotive competes through its column-assist specialization and proximity engineering centers in Mexico, while JTEKT Corporation sustains rack-assist dominance via captive forging and machining investments in the Bajío region.
Automotive electric power steering replaces hydraulic pump-driven assistance with a brushless motor mounted on the steering column or rack, drawing vehicle electrical power to reduce parasitic engine load and improve fuel economy by eliminating belt-driven hydraulic circulation. Rack-assist configurations occupy the majority share in Mexico's output profile due to their compatibility with heavier SUVs and crossovers assembled for North American export. Column-assist systems lead in compact hatchback and sedan applications where packaging constraints and cost floors dominate procurement criteria, while steer-by-wire technology remains pre-commercial in Mexican assembly though Tier-1 R&D programs are active.
NOM-194-SCFI safety standards and USMCA regional value-content rules shape component sourcing decisions, forcing EPS suppliers to document North American steel and aluminum provenance for tariff compliance. The Secretariat of Economy and PROFECO monitor aftermarket replacement quality, creating a dual-track regulatory environment for OE and service-channel products. Stakeholders must track NOM evolution toward autonomous-vehicle readiness and the energy-efficiency thresholds that Mexico's energy regulatory commission will embed in future automotive component certifications.
Market Dynamics
OEM procurement from passenger vehicle manufacturers is decoupling from traditional tier-1 dependency as domestic SUV and crossover production expands across the Bajío automotive cluster. This structural shift is compressing supplier hierarchies and forcing direct engineering relationships between assemblers and component specialists.
Growth Catalysts
- USMCA regional value-content rules:Tariff compliance requirements force EPS suppliers to document North American steel and aluminum provenance, creating captive demand for localized forging and machining capacity.
- Bajío SUV and crossover assembly expansion:Nearshored production platforms multiply rack-assist system demand as heavier vehicle architectures displace compact sedan output.
- NOM-194-SCFI safety standard evolution:Mexico's Secretariat of Economy tightens component traceability mandates, accelerating replacement of legacy hydraulic steering in aftermarket channels.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in brushless motor rotor assemblies compress margin stability for rack-assist producers.
- Querétaro-Guanajuato supplier concentration:Three integrated tier-1 facilities control majority sensor-to-actuator output, creating single-source vulnerability for transplant OEMs.
- Steer-by-wire technical immaturity:Redundancy requirements for fail-operational architectures delay commercial deployment despite active R&D programs.
Strategic Opportunities
- Aguascalientes autonomous-vehicle readiness:NOM standard evolution toward ADAS compatibility creates first-mover advantage for suppliers pre-certifying steer-by-wire platforms.
- Aftermarket service-channel bifurcation:PROFECO quality monitoring separates OE-grade from economy replacement demand, enabling premium positioning for documented provenance products.
- Energy-efficiency certification convergence:Mexico's energy regulatory commission embeds automotive component thresholds, rewarding brushless motor architectures with preferential procurement status.
Industry Challenges
- Embedded software validation timelines:Functional safety certification for ISO 26262 ASIL-D compliance extends development cycles by 14-18 months.
- Legacy hydraulic technician displacement:Service channel retraining requirements create friction in aftermarket penetration as electronic diagnostics replace mechanical troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive EPS Market |
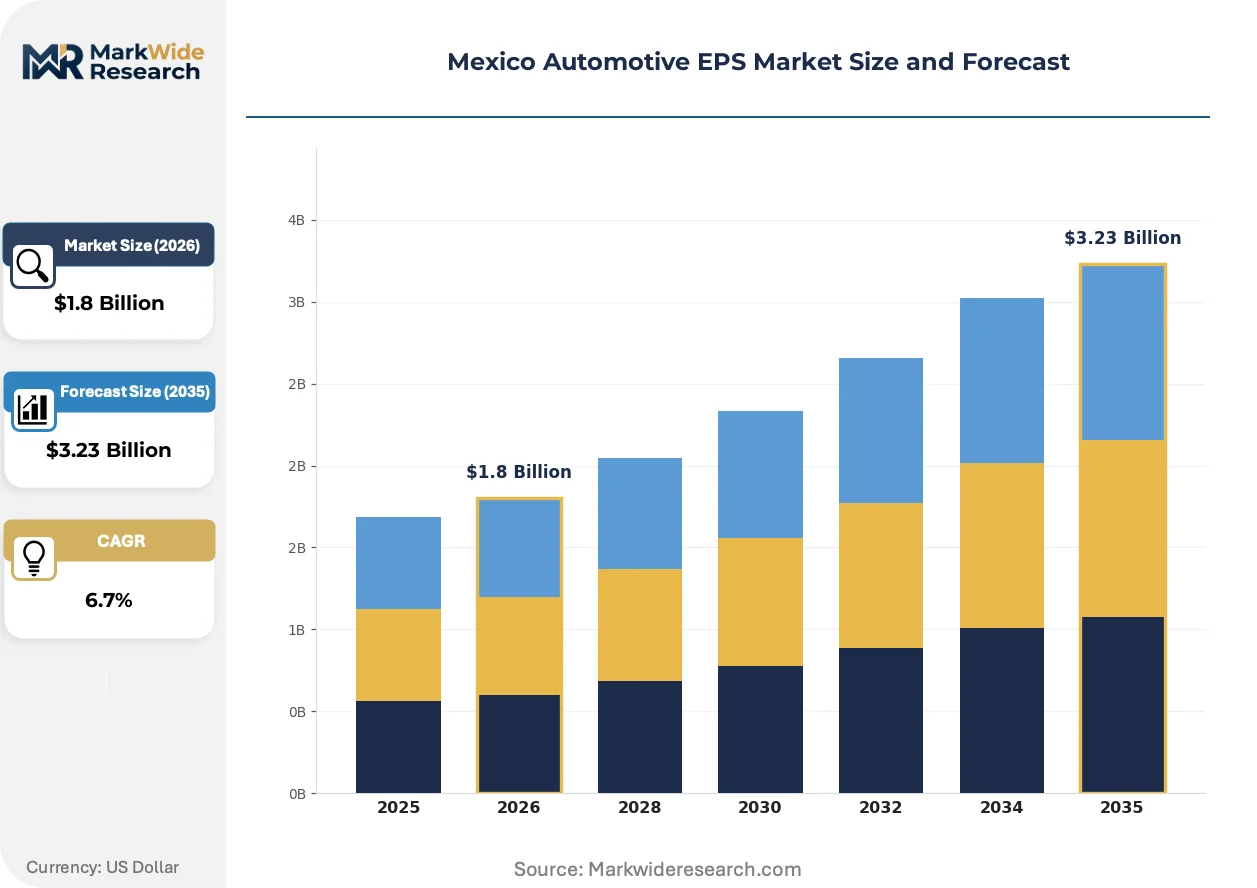
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Electric Power Steering, Electro-Hydraulic Steering End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Heavy-duty Trucks Technology: Steer-by-wire, Variable Ratio Steering, Torque Control, Integrated Systems Vehicle Type: Hatchbacks, Sedans, SUVs, Crossovers |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, NSK Ltd, Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis, Mando Corporation, Delphi Automotive Systems, GKN PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive EPS Market Shifts & Advancements
Brushless motor architectures and integrated sensor fusion are compressing the traditional separation between steering mechanics and vehicle control systems. Three distinct trajectories are reshaping how EPS technology is engineered, regulated, and procured.
Brushless permanent-magnet synchronous motors with integrated torque-angle sensors are consolidating the discrete component layers that historically separated steering column manufacturers from motor suppliers. Tier-1 engineering centers in Querétaro now specify unified electromechanical modules that combine position sensing, motor control, and mechanical assist in single-source contracts. This consolidation is eliminating multi-vendor integration risk while compressing procurement negotiation leverage for standalone sensor or motor specialists.
NOM-194-SCFI safety standards and USMCA regional value-content rules are tightening in parallel, forcing dual-track compliance documentation for both crashworthiness performance and material provenance. The Secretariat of Economy now requires batch-level traceability for aluminum castings and steel forgings used in rack housings, adding administrative overhead that favors suppliers with captive upstream metal processing. Tier-1 procurement teams are responding by consolidating supplier audits around integrated forge-machine-assemble operations rather than distributed component sourcing.
Direct OEM engineering engagement is displacing traditional tier-1 mediated specification for crossover and SUV platforms assembled in Guanajuato. Vehicle manufacturers now embed EPS requirements into platform architecture decisions earlier in development cycles, compressing the window for supplier technical proposals. This behavioral shift is most visible in rack-assist procurement for mid-size SUV exports, where assemblers specify motor torque curves and packaging envelopes before selecting integration partners.
Mexico Automotive EPS Market Segmentation
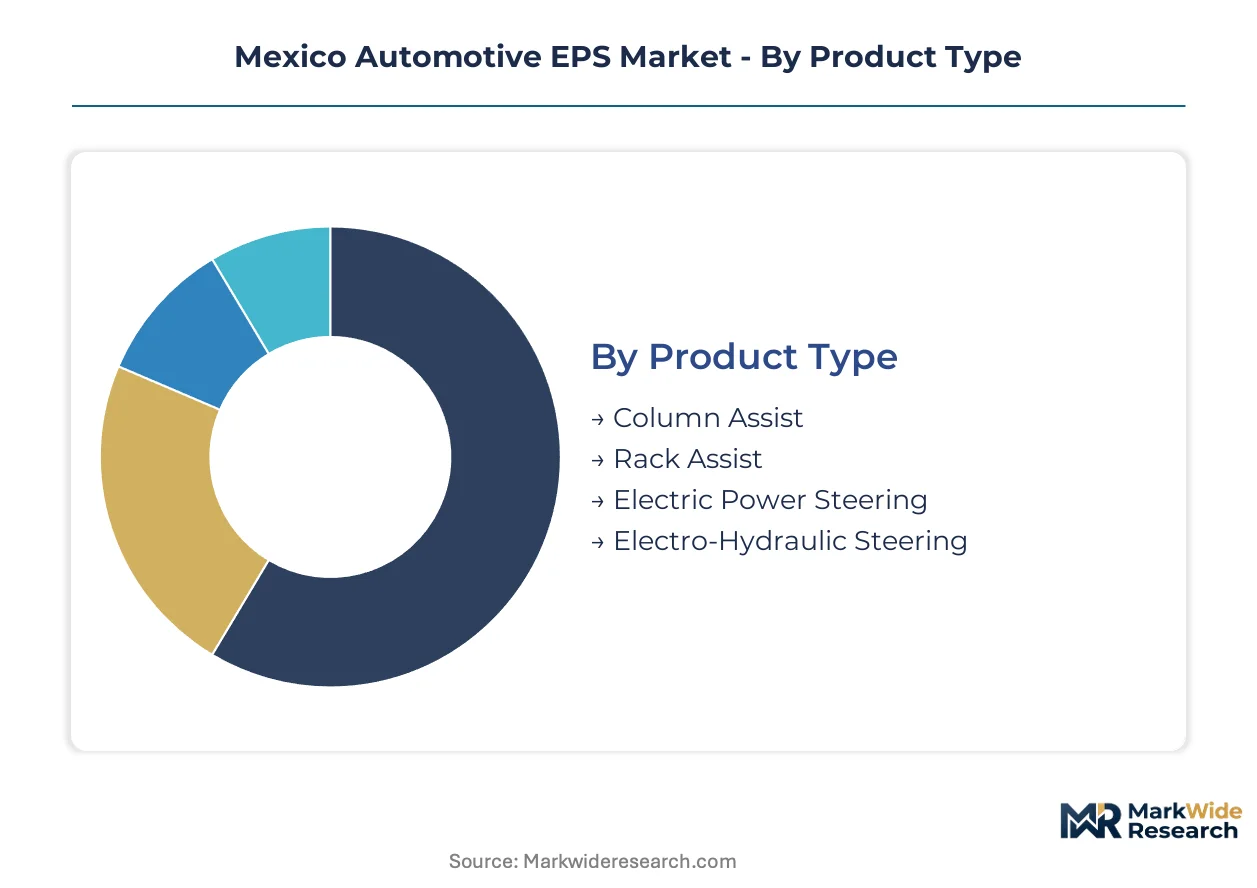
Mexico's EPS segmentation reflects the tension between standalone steering modules and embedded electromechanical architectures. Procurement patterns in the Bajío cluster increasingly favor integrated systems that consolidate sensor fusion with motor control.
Product Type:
Integration depth varies sharply across product categories, with column-mounted systems remaining modular while rack-assist configurations embed deeper into chassis architecture.
- Column Assist:Brushless motors mount directly to the steering column shaft, delivering assist torque through a worm gear reduction. Compact packaging dominates procurement for Aguascalientes hatchback production where firewall clearance limits rack-mounted alternatives. NOM-194-SCFI compliance costs run lower due to simpler mechanical redundancy.
- Rack Assist:High-torque motors integrate into the steering rack housing, driving the pinion through a ball-screw mechanism. Guanajuato SUV assembly lines specify these for vehicles exceeding 1,800 kg curb weight where column torque limits prove inadequate. USMCA aluminum provenance rules favor captive forging investments by tier-1 suppliers.
- Electric Power Steering:Umbrella category spanning both assist architectures with unified motor-inverter control.
- Electro-Hydraulic Steering:Hybrid design retaining hydraulic assist with electric pump drive; declining share in Mexican OE procurement.
Rack-assist systems lead volumes today; column-assist configurations are gaining share fastest in compact vehicle platforms.
End User:
Cost-tier stratification separates high-volume OE contracts from fragmented aftermarket channels, with commercial vehicle procurement demanding heavier-duty torque specifications.
- Passenger Vehicles:Transplant OEMs in Querétaro and Guanajuato drive rack-assist demand for crossover exports to the United States. Platform consolidation around C-segment SUVs compresses supplier negotiation windows.
- Commercial Vehicles:Light commercial van production in Puebla specifies modified rack-assist with reinforced housings. PROFECO aftermarket monitoring creates dual-track quality tiers for service-channel replacement.
- Two-wheelers:Minimal penetration; electric scooter EPS remains pre-commercial in Mexican assembly.
- Heavy-duty Trucks:Hydraulic retention dominates; EPS torque density insufficient for Class 8 applications.
Passenger vehicle procurement anchors revenue; commercial vehicle replacement demand is expanding most quickly as fleet operators retrofit older platforms.
Technology:
Technology maturity curves separate production-ready architectures from pre-commercial platforms awaiting NOM autonomous-vehicle alignment.
- Steer-by-wire:Eliminates mechanical steering column entirely through triple-redundant motor actuation. Aguascalientes engineering centers pilot test fleets for future NOM ADAS certification, though fail-operational redundancy requirements delay commercial deployment.
- Variable Ratio Steering:Electronically modulated rack gearing adjusts effective steering ratio by vehicle speed. Integrated into premium crossover platforms where parking maneuverability conflicts with highway stability requirements.
- Torque Control:Software-defined assist curves replacing mechanical torsion bar feedback.
- Integrated Systems:Sensor-to-actuator consolidation in single-source modules.
Variable ratio steering leads installed base; steer-by-wire platforms are climbing the fastest toward certification readiness.
Vehicle Type:
Application-specific packaging constraints dictate motor placement and torque specification across the Mexican assembly mix.
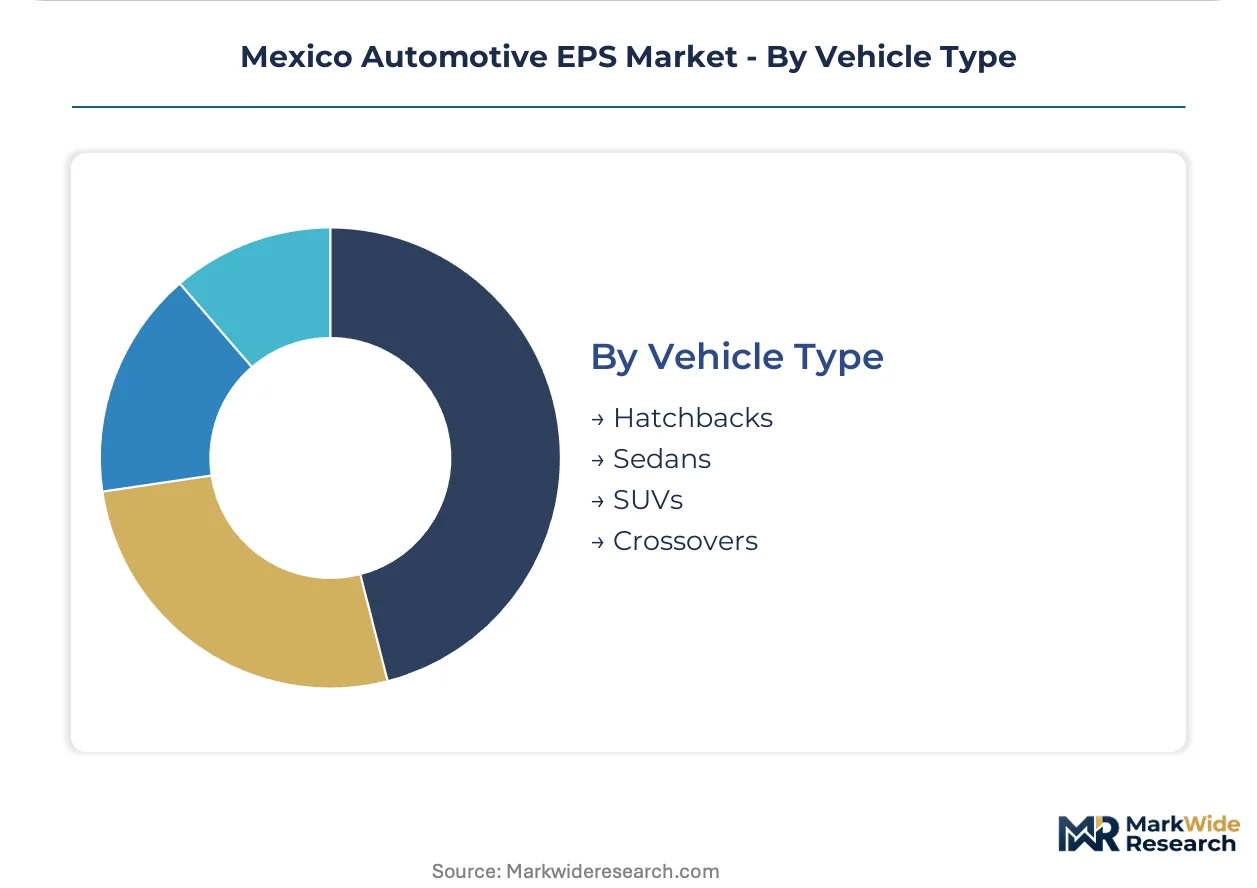
- Hatchbacks:Column-assist dominance driven by engine bay packaging limits and cost floors. Compact B-segment platforms from Guanajuato plants prioritize firewall clearance over steering precision.
- Sedans:Mid-size three-box configurations split between column and rack assist based on platform age. Legacy architectures retain column mounting; new modular platforms specify rack integration.
- SUVs:Rack-assist standard for body-on-frame and unibody architectures above 2,000 kg gross vehicle weight.
- Crossovers:Fastest-growing assembly category in the Bajío cluster; unibody construction with elevated ride height demands rack-assist torque density.
SUVs lead current output volumes; crossovers are gaining share fastest as nearshored capacity displaces traditional sedan production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico outpaces Canada in EPS supplier density despite smaller domestic vehicle consumption, while the United States absorbs the majority of rack-assist systems assembled in Bajío export plants.
Bajío Region
Guanajuato and Aguascalientes anchor rack-assist production for crossover exports to the United States. NOM-194-SCFI traceability mandates from the Secretariat of Economy force batch-level documentation of aluminum castings. Querétaro engineering centers host integrated sensor-to-actuator development for transplant OEM platforms.
Nuevo León
Monterrey metropolitan area concentrates commercial vehicle steering component machining for light-duty truck platforms. The state's economic development agency coordinates workforce retraining programs for hydraulic-to-electric technician transition. García and Santa Catarina industrial parks host tier-2 forging operations supplying rack housing castings.
Jalisco
Guadalajara electronics manufacturing corridor produces motor control modules and torque-angle sensors for column-assist systems. PROFECO aftermarket quality monitoring creates dual certification tracks for OE-grade versus economy replacement channels. El Salto and Tlajomulco industrial zones specialize in brushless motor winding and inverter assembly.
Mexico City Metro
Tlalnepantla and Cuautitlán Izcalli host headquarters operations for major tier-1 suppliers coordinating Bajío production networks. The Federal Consumer Prosecutor's office enforces PROFECO standards for steering component warranty claims. Lerma Valley logistics corridors channel finished EPS modules to Lázaro Cárdenas port for Central American export.
Northern Border States
Chihuahua and Coahuila assemble column-assist systems for compact vehicle platforms re-exported under USMCA tariff preferences. Baja California maquiladora operations handle final motor-inverter integration for just-in-time delivery to San Diego-Tijuana automotive corridor. Customs documentation for regional value-content compliance concentrates in Ciudad Juárez brokerage operations.
Mexico Automotive EPS Market Competitive Landscape
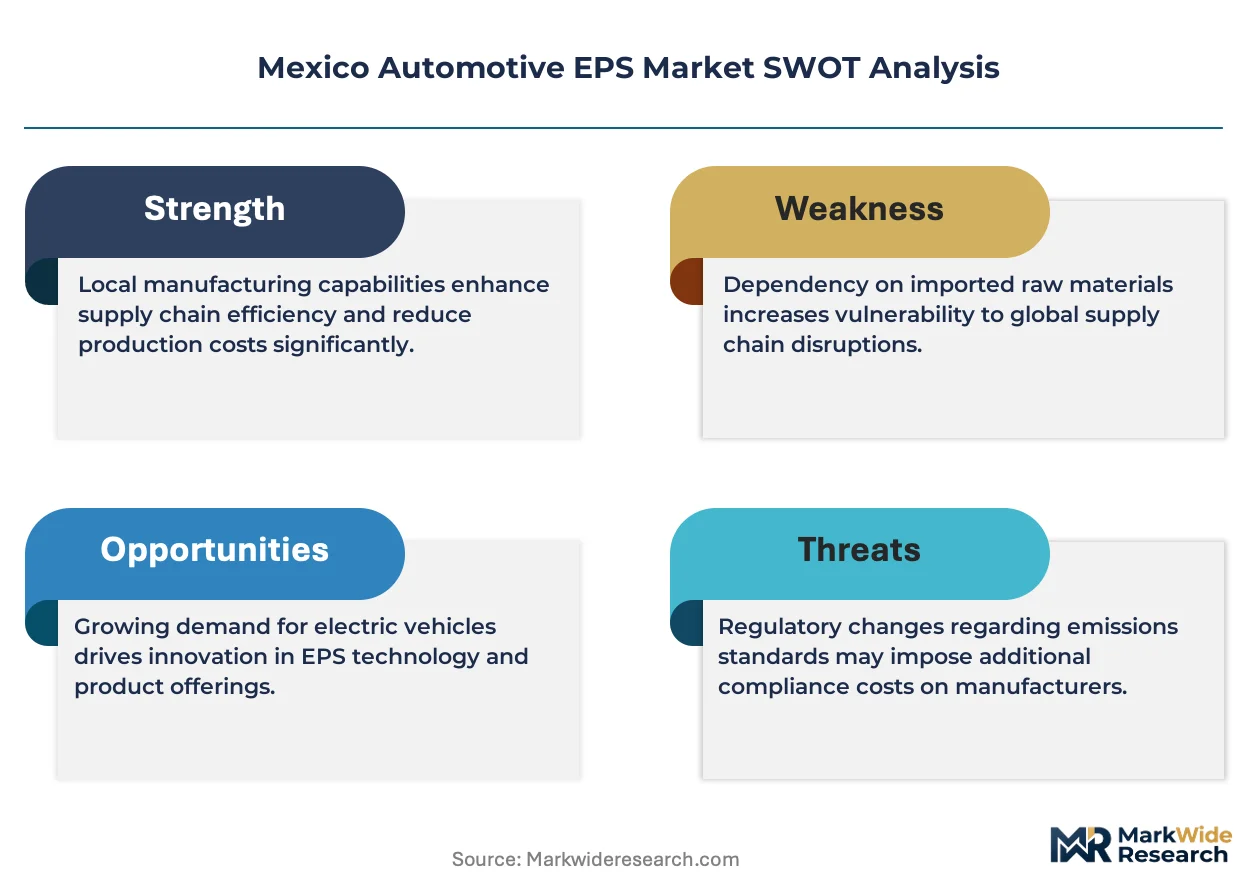
German and Japanese producers anchor the integrated systems tier; Korean and North American specialists hold positions in modular component supply. The vendor base splits between consolidated forge-machine-assemble operations and distributed sensor-motor-controller specialists. Two strategic archetypes dominate: captive forging investors with upstream metal processing and software-defined control houses with ISO 26262 certification capabilities. Competitive moves concentrate on backward integration into aluminum provenance documentation and engineering center proximity to Bajío assembly plants.
Within the integrated tier-1 archetype, Robert Bosch GmbH, JTEKT Corporation, and Nexteer Automotive exemplify contrasting geographic and technical positioning. Bosch represents the German engineering-center model with Querétaro-based sensor-to-actuator consolidation. JTEKT occupies a position reflecting Japanese captive forging investments in rack-assist machining capacity. Nexteer sits within the North American column-assist specialization anchored by proximity engineering presence. These three names illustrate how supplier strategy fragments across rack versus column architectures, integrated versus modular system design, and upstream metal processing versus downstream software control.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| NSK Ltd |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Mando Corporation |
| Delphi Automotive Systems |
| GKN PLC |
| Others |
Supply & Pricing Matrix
Transplant OEM assembly operations in Querétaro and Guanajuato concentrate procurement leverage around contract-based long-term offtake agreements, anchoring rack-assist pricing to aluminum provenance documentation costs under USMCA regional value-content rules. This buyer concentration compresses margin negotiation windows for tier-1 suppliers while rewarding integrated forge-machine-assemble operations with tariff compliance premiums.
Pricing Analysis
Capacity additions in captive forging facilities across the Bajío region are reshaping price floors for rack-assist modules by internalizing aluminum casting costs previously exposed to spot market volatility. Three-tier pricing structure across OE-grade, documented-provenance aftermarket, and economy replacement channels differentiates by NOM-194-SCFI certification level and batch traceability depth. Cost compression in column-assist segments runs through brushless motor supplier consolidation as worm gear reduction specialists absorb inverter assembly functions. Fleet operators retrofitting commercial vehicles exhibit highest price sensitivity; premium crossover platforms show lowest sensitivity due to platform-locked specification windows.
Supply Chain Analysis
USMCA regional value-content rules and NOM-194-SCFI batch traceability mandates are forcing dual-track compliance documentation that reshapes sourcing decisions across Mexican EPS production networks. Geographic supply concentration centers on Japan, Germany, and South Korea for torque-angle sensors and motor control modules, while rare earth magnet processing draws from China and domestic Mexican forging supplies rack housing aluminum. Single-source vulnerability pervades the Querétaro-Guanajuato corridor where three integrated tier-1 facilities control majority sensor-to-actuator output. Distribution runs through just-in-time sequencing to Bajío assembly plants with Lázaro Cárdenas port handling Central American aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Mexico's automotive EPS sector rests on brushless motor architecture standardization eliminating hydraulic technician displacement costs, while rack-assist premiumization for crossover exports captures aluminum provenance compliance premiums.
For Market Incumbents: Cement backward integration into aluminum forging capacity in Guanajuato to capture USMCA regional value-content tariff credits and neutralize rare earth magnet cost volatility through long-term offtake structures. Deepen ISO 26262 ASIL-D certification capabilities to extend development cycle lock-in against emerging software-defined control houses. Prioritize engineering center proximity to Aguascalientes autonomous-vehicle pilot programs to pre-position for NOM ADAS alignment. For New Entrants and Emerging Players: Enter via aftermarket service-channel bifurcation created by PROFECO quality monitoring, targeting economy replacement demand for legacy hydraulic steering displacement in commercial vehicle fleets. The most penetrable segment sits in light commercial van retrofit markets around Puebla where technician retraining friction slows incumbent penetration. Pursue direct distribution partnerships with regional fleet maintenance operators rather than tier-1 mediation. For Investors and Strategic Acquirers: Japanese automotive component conglomerates represent the most active acquirer in this space, seeking captive forging assets to secure aluminum provenance documentation for USMCA compliance. Long-term viability over the next decade hinges on steer-by-wire platform readiness as NOM standards evolve toward autonomous-vehicle compatibility. Target acquisition archetype: integrated sensor-to-actuator specialists with existing ISO 26262 certification and Bajío engineering center presence. Monitor NOM-194-SCFI revision timelines as the critical inflection signal for fail-operational redundancy investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around C-segment SUV architectures compresses supplier qualification cycles for rack-assist modules. |
| Backward Integration into Aluminum Forging | Captive casting operations in Guanajuato satisfy USMCA regional value-content rules for tariff-free export to US assembly plants. |
| Software-Defined Vehicle Investment | Torque curve programming and variable ratio steering integration position suppliers for steer-by-wire transition readiness. |
| Geographic Manufacturing Footprint | Querétaro engineering center proximity to transplant OEM platforms accelerates direct specification engagement. |
| Aftermarket Channel Partnership | PROFECO-monitored quality tiers enable premium positioning for documented-provenance replacement modules in service channels. |
Research Methodology
Direct dialogue with tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and PROFECO regulatory compliance officers grounded qualitative assessment of NOM-194-SCFI implementation timelines and USMCA documentation practices. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs trade records, and Secretariat of Economy regulatory filings. Bottom-up segment sizing triangulated against top-down market envelope checks derived from OEM assembly capacity announcements across the Bajío cluster.
Bottom-up modeling aggregated unit economics across column-assist, rack-assist, and pre-commercial steer-by-wire configurations, with top-down cross-checks against regional automotive production forecasts and content-per-vehicle assumptions across propulsion architectures. Segmentation dimensions included vehicle class, assist architecture type, OEM tier positioning, and regional production cluster concentration. CAGRs derived from regression analysis of historical platform rollout cadences and nearshored capacity expansion schedules, with torque density requirements and brushless motor adoption curves as industry-specific forecast inputs.
Inputs from OEM procurement teams and tier-1 engineering centers were available through the study window; gaps in steer-by-wire commercial deployment timelines and NOM ADAS standard revision schedules introduce uncertainty bands around technology transition assumptions. Forecasts reflect documented platform commitments and regulatory alignment trajectories, with rare earth magnet price volatility and single-source supplier concentration representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market