
 Automotive Electronic Suspension System (ESS) Market | 2026-2036
Automotive Electronic Suspension System (ESS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electronic Suspension System (ESS) Market Insights
China is fragmenting as domestic EV manufacturers build proprietary chassis control competencies alongside established foreign suppliers. ZF Friedrichshafen AG leverages its integrated actuator portfolio to sustain technology leadership in magnetorheological valve systems. Continental AG anchors European supply relationships through localized software development centers for adaptive damping algorithms. Tenneco Inc. competes on cost-engineered semi-active modules targeting volume OEM programs in North America.
Automotive Electronic Suspension System (ESS) denotes electronically controlled chassis architectures that modulate damping force, ride height, or spring rate through sensor-fed algorithms, typically operating at response frequencies below 100 Hz and hydraulic pressures of 100–200 bar to optimize tire contact patch dynamics. The primary commercial purpose centers on reconciling ride comfort with lateral stability across variable road surfaces and driving maneuvers. Semi-active suspension dominates current OEM fitment due to its cost-calibrated performance envelope, while magnetorheological technology captures expanding margin pools in luxury and performance vehicle applications. Electrohydraulic architectures retain structural importance in commercial vehicle segments where payload compensation requirements persist.
NHTSA Federal Motor Vehicle Safety Standards, EU General Safety Regulation, and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval protocols collectively mandate stability-critical chassis systems in new vehicle categories, directly shaping ESS specification thresholds and homologation pathways. China's MIIT new energy vehicle technical guidelines further condition market access through domestic software localization requirements. Stakeholders must monitor regulatory divergence between cybersecurity-enabled over-the-air update capabilities and traditional mechanical safety certification frameworks.
Market Dynamics
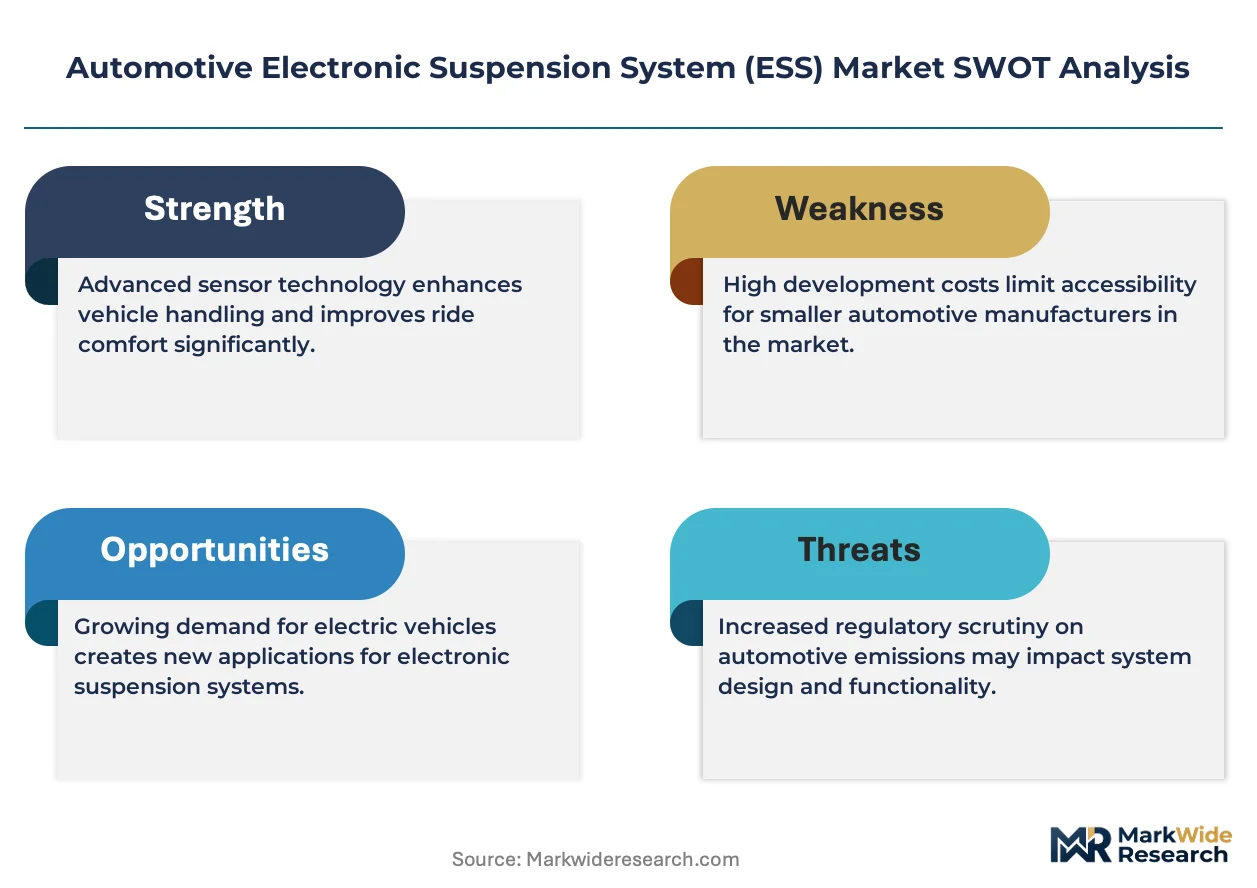
Magnetorheological valve architectures are compressing the performance-cost gap between semi-active and fully active suspension tiers, forcing suppliers to recalibrate module positioning across OEM price bands.
Growth Catalysts
- NHTSA stability mandates:Federal Motor Vehicle Safety Standards now require electronically modulated chassis control for certain vehicle weight classes, compelling OEM integration of sensor-fed damping systems.
- EV chassis differentiation:Chinese premium electric vehicle manufacturers treat adaptive suspension as a core brand attribute, driving specification escalation in battery-electric platforms.
- Algorithm sophistication:Machine learning-enabled predictive damping—processing road surface data at sub-100 Hz frequencies—is expanding the addressable performance envelope beyond traditional PID control architectures.
Market Restraints
- Rare earth magnet supply concentration:Magnetorheological fluid production depends on neodymium and dysprosium sourcing concentrated in Chinese refining operations, creating input cost volatility and geopolitical exposure.
- Homologation timeline friction:EU General Safety Regulation type-approval protocols for cybersecurity-enabled over-the-air suspension updates extend certification cycles by 8-14 months versus mechanical-only systems.
- Hydraulic actuator cost floor:Precision-machined servo valves and high-pressure sealing systems impose material and tolerance costs that resist scale economies below 150,000 annual units per platform.
Strategic Opportunities
- Commercial vehicle payload compensation:Electrohydraulic architectures with real-time ride height adjustment address unmet needs in European heavy-duty freight segments where axle load regulations vary by member state.
- Software localization incentives:China's MIIT new energy vehicle technical guidelines reward chassis control algorithms developed through domestic engineering centers, creating captive demand for regional R&D investment.
- Aftermarket retrofit channels:Semi-active damper upgrade kits for performance vehicle owners—distributed through specialized tuners rather than OEM service networks—unlock margin pools outside original equipment supply chains.
Industry Challenges
- Embedded systems cybersecurity certification:UN ECE R155 and ISO/SAE 21434 compliance for suspension control units demands specialized hardware security module integration that extends development timelines and requires rare skill sets in automotive cryptography.
- Legacy platform integration complexity:Retrofitting electronically controlled damping onto architectures originally designed for passive suspension requires mechanical packaging compromises and CAN bus bandwidth reallocation that strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electronic Suspension System (ESS) Market |
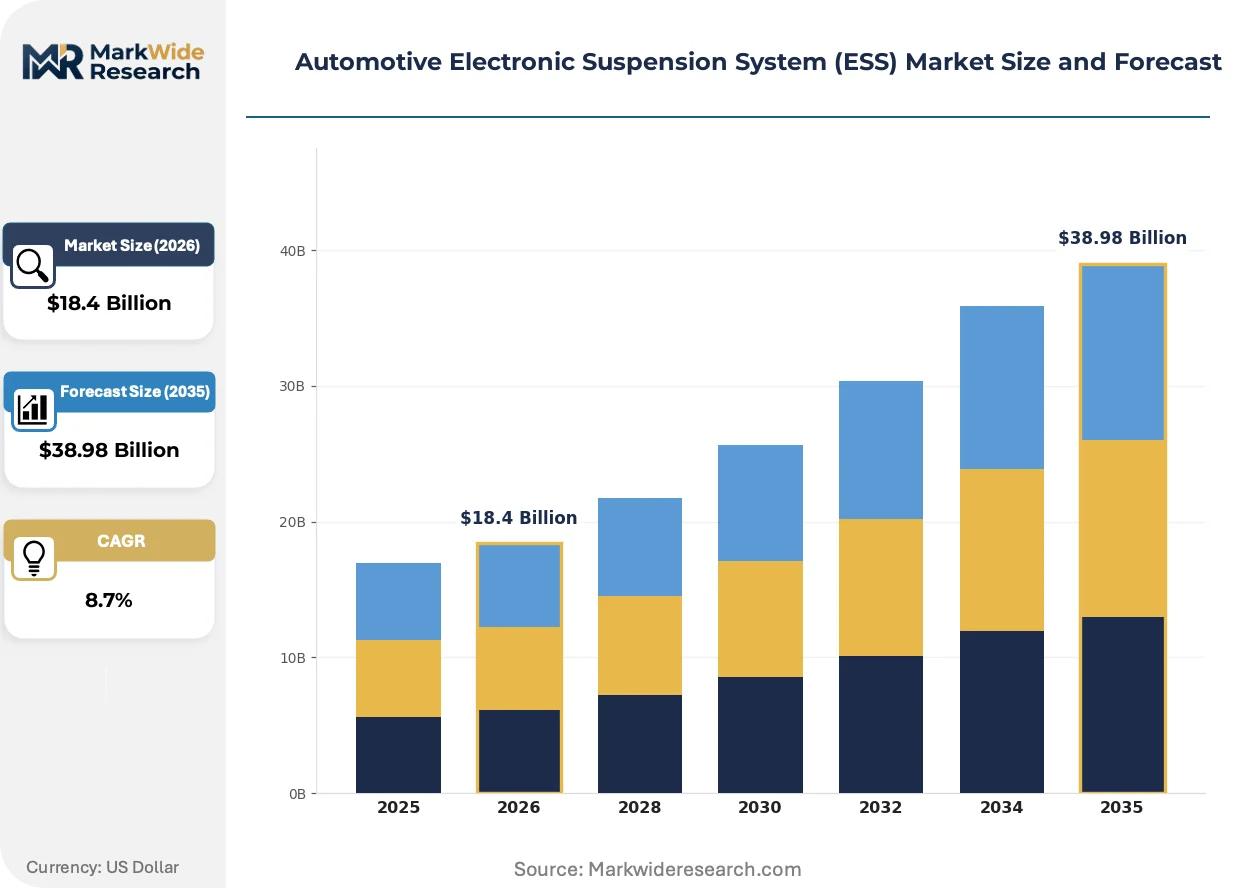
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Suspension, Semi-Active Suspension, Passive Suspension, Adaptive Suspension Technology: Magnetorheological, Electrohydraulic, Pneumatic, Variable Damping End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Sports Cars |
| Companies Covered | ZF Friedrichshafen AG, Continental AG, Tenneco Inc., Magna International Inc., KYB Corporation, ThyssenKrupp AG, Hitachi Astemo Ltd., BWI Group, Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electronic Suspension System (ESS) Market Trends and Innovations
Control architectures are converging across passenger car, commercial vehicle, and off-highway equipment segments, dissolving traditional silos in chassis electronics procurement and forcing suppliers to build transferable platform competencies.
Magnetorheological damping is hybridizing with conventional hydraulic valving to create dual-mode actuators that switch between energy-efficient passive operation and high-bandwidth active control. Tier 1 suppliers are shipping these modules to German and Japanese luxury OEMs for 2026 platform launches. The technology is hybridizing cost structures by collapsing the historical three-tier pricing hierarchy into two overlapping performance bands.
EU General Safety Regulation mandates for intelligent speed adaptation and lane-keeping assistance are forcing suspension systems to integrate with ADAS sensor fusion stacks rather than operate as standalone chassis subsystems. This regulatory pressure is accelerating software-defined damper control development. European premium OEMs are responding by consolidating supplier relationships around vendors capable of delivering integrated chassis-ADAS software stacks.
Fleet operators in North American long-haul trucking are unbundling suspension maintenance from powertrain service contracts, creating standalone procurement channels for predictive damper health monitoring. Specialized telematics providers are displacing traditional parts distributors in this segment. The shift is most visible in California and Texas, where large fleet concentrations enable outcome-based service pricing tied to cargo damage reduction metrics.
Automotive Electronic Suspension System (ESS) Market Segmentation
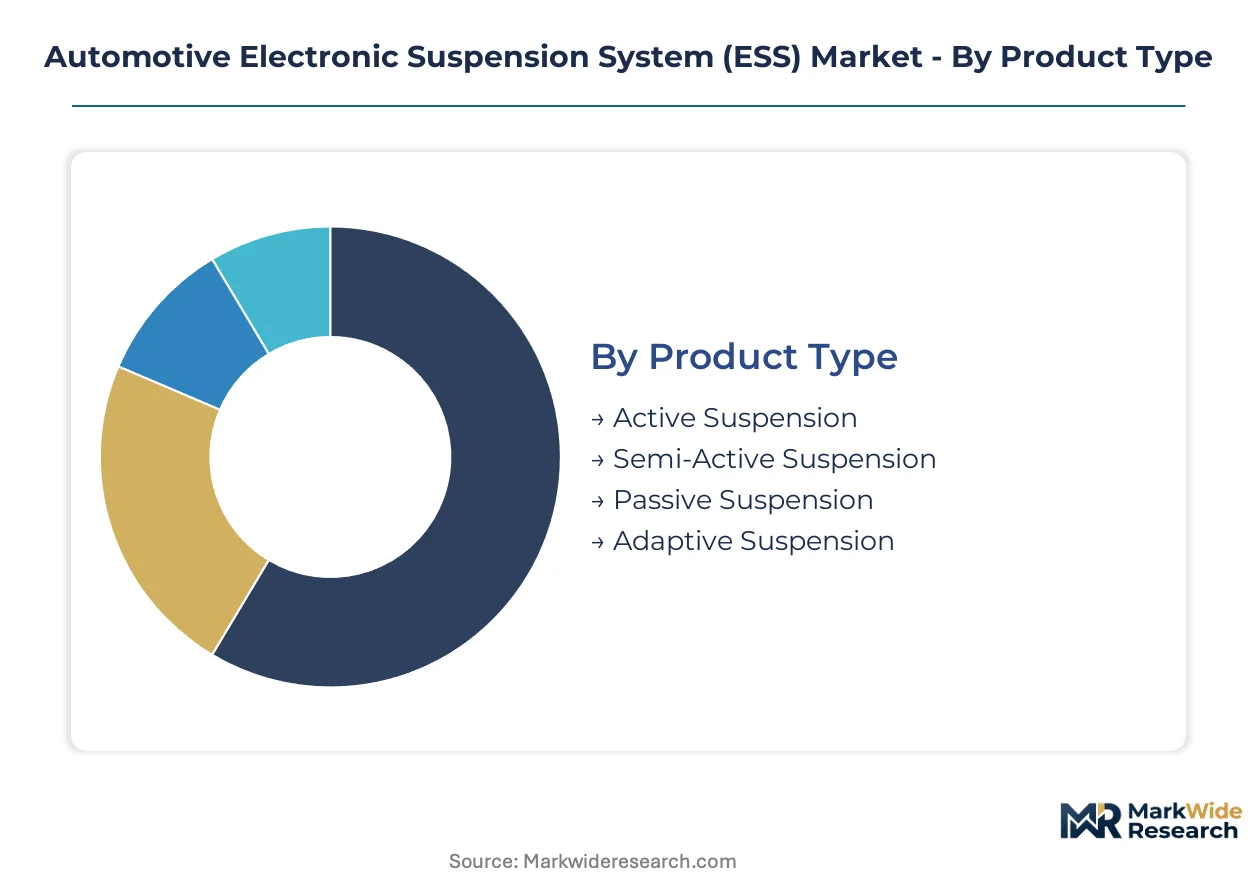
Electronic suspension procurement cycles vary dramatically by product architecture and technology maturity. OEMs reset platform specifications every 5-7 years, but component-level sourcing decisions refresh faster in segments where algorithmic differentiation accelerates obsolescence. Understanding these velocity differentials shapes supplier capacity planning and R&D allocation priorities.
Product Type:
Semi-active architectures turn over fastest as damper valve designs iterate annually, while fully active systems lock in platform commitments for entire vehicle generations. Passive suspension refresh cycles stretch longest where cost engineering dominates procurement criteria.
- Semi-Active Suspension:Solenoid-controlled hydraulic valves modulate damping force within 10-20 milliseconds using sensor feedback loops. Chinese EV manufacturers specify these systems most aggressively, treating chassis responsiveness as a core brand attribute in premium battery-electric platforms.
- Active Suspension:Electrohydraulic or electromechanical actuators deliver continuous force generation independent of road input, requiring dedicated high-voltage architectures. German luxury OEMs concentrate development spending here, integrating active systems with predictive road-scanning lidar for autonomous driving readiness.
- Adaptive Suspension:Multi-mode damper systems switch between comfort and sport calibrations via driver-selectable maps. Japanese manufacturers favor this architecture for its reliability record and lower service network complexity.
- Passive Suspension:Fixed-rate springs and dampers without electronic control persist in entry vehicle segments and emerging market platforms where unit cost targets resist electronic content expansion.
Semi-active architectures dominate installed base. Active suspension is where expansion concentrates.
Technology:
Cost tiering separates these technologies sharply. Magnetorheological fluids command premium positioning, while pneumatic solutions anchor value-engineered commercial vehicle applications.
- Magnetorheological:Iron particle suspensions in synthetic oil change viscosity under magnetic field application, enabling sub-5 millisecond response times. United States-based performance vehicle manufacturers specify these systems for track-capable models, though rare earth magnet supply concentration in Chinese refining operations creates input cost volatility.
- Electrohydraulic:High-pressure servo valves and accumulators deliver precise force control for ride height management. European heavy-duty freight operators demand these architectures for real-time payload compensation across varying axle load regulations.
- Variable Damping:Twin-tube or mono-tube dampers with electronically controlled bypass valves balance performance against manufacturing simplicity. Volume OEM programs in North America source these modules for mid-luxury crossover platforms.
- Pneumatic:Air spring and compressor assemblies provide load-leveling without hydraulic complexity. Commercial vehicle assemblers in India specify pneumatic systems for bus and coach applications where road quality varies unpredictably.
Variable damping holds the broadest OEM qualification base. Magnetorheological technology is climbing the fastest.
End User:
Customer type determines specification authority and contract structure. Vehicle assemblers retain final integration responsibility, but Tier-1 suppliers increasingly own algorithm development.
- OEMs:Brand-holding manufacturers define chassis performance targets and approve supplier nominations. German and Japanese OEMs maintain the most centralized suspension engineering organizations, specifying valve tolerances and control logic in-house.
- Tier-1 Suppliers:Integrated module producers deliver damper, sensor, and controller as a single system. ZF Friedrichshafen AG and Continental AG compete most intensely for these contracts, differentiating through software localization capabilities.
- Aftermarket Providers:Specialized tuners and performance shops distribute upgrade kits outside OEM service networks. California and Texas host the most developed retrofit channels, where fleet operators unbundle suspension maintenance from powertrain contracts.
- Vehicle Assemblers:Contract manufacturers building for multiple brands execute supplier-directed specifications without design authority. Chinese domestic EV brands rely heavily on assembler relationships for chassis system integration.
Tier-1 suppliers dominate engineering value capture. Aftermarket providers are gaining share fastest in predictive health monitoring segments.
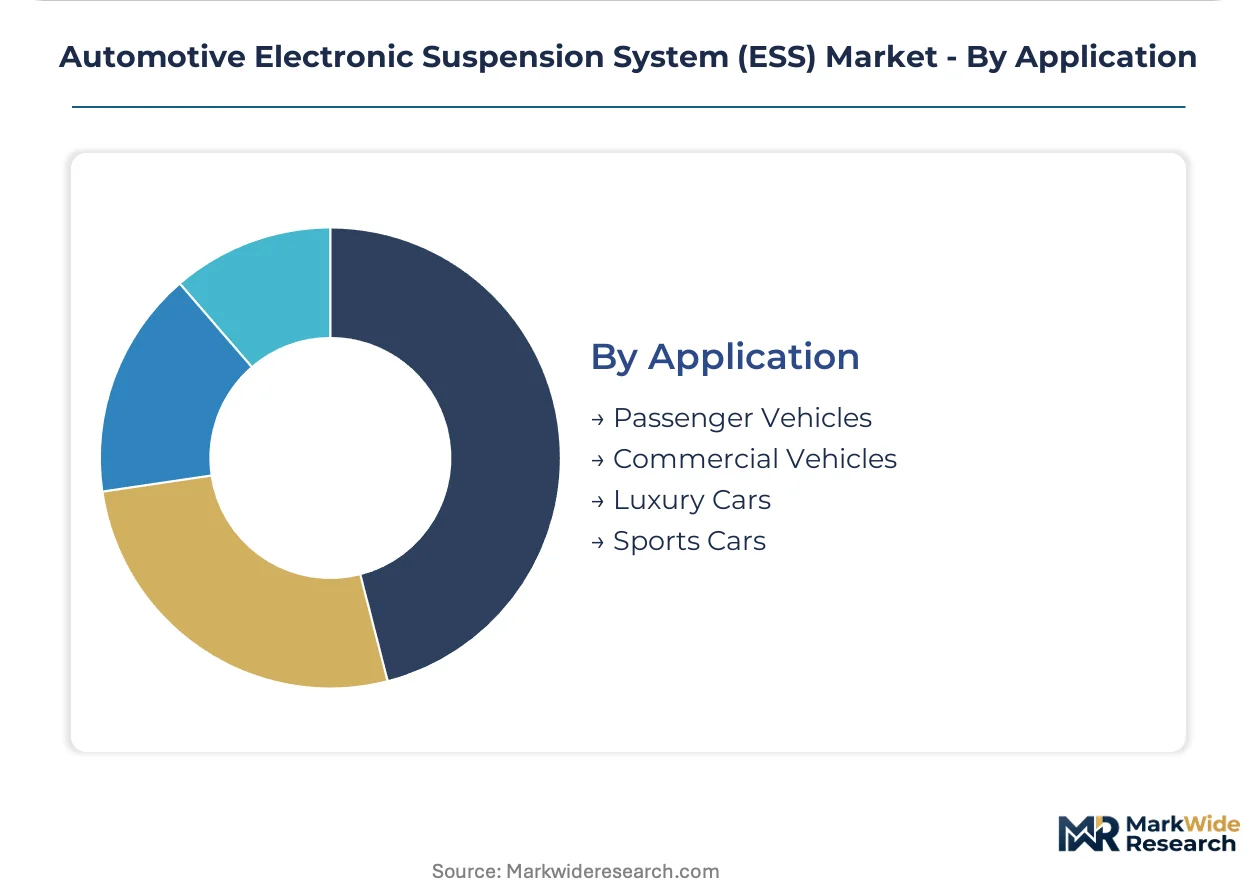
Application:
Volume scale and margin structure diverge sharply across vehicle categories. Luxury applications fund technology development that later migrates downmarket.
- Luxury Cars:Adaptive damping and active roll control serve as standard equipment in vehicles above $80,000 price points. NHTSA stability mandates and EU General Safety Regulation requirements accelerate specification escalation in this segment.
- Passenger Vehicles:Mid-size sedans and crossovers represent the largest unit volume opportunity, though cost engineering pressure limits electronic content penetration. Semi-active systems are climbing fastest here as magnetorheological costs compress.
- Commercial Vehicles:Heavy-duty trucks and buses require payload compensation and ride height adjustment for regulatory compliance. European axle load regulations vary by member state, creating specialized demand for electrohydraulic architectures.
- Sports Cars:Track-focused performance vehicles prioritize response bandwidth over comfort calibration. Italian and German sports car manufacturers specify the most aggressive damper valving for circuit driving modes.
Passenger vehicles anchor unit volume. Luxury cars concentrate margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA stability mandates in the United States are conditioning specification thresholds that propagate through German and Japanese regulatory frameworks, creating synchronized demand cycles across three distinct manufacturing geographies.
United States
Performance vehicle manufacturers specify magnetorheological systems for track-capable models, while fleet operators in California and Texas unbundle suspension maintenance from powertrain contracts. NHTSA Federal Motor Vehicle Safety Standards now require electronically modulated chassis control for certain vehicle weight classes. Detroit's automotive corridor anchors supplier engineering centers serving domestic OEM integration programs.
Germany
Luxury OEMs concentrate development spending on active suspension integrated with predictive road-scanning lidar for autonomous driving readiness. EU General Safety Regulation mandates for intelligent speed adaptation force suspension systems to integrate with ADAS sensor fusion stacks. Stuttgart and Munich host consolidated supplier relationships around vendors capable of delivering integrated chassis-ADAS software stacks.
China
Domestic EV brands prioritize advanced chassis technology as a differentiation tool in premium segments, treating adaptive suspension as a core brand attribute. MIIT new energy vehicle technical guidelines reward chassis control algorithms developed through domestic engineering centers. Shanghai and Shenzhen anchor regional R&D investment responding to software localization incentives.
Japan
Manufacturers favor multi-mode damper systems for reliability records and lower service network complexity. Ministry of Land, Infrastructure, Transport and Tourism type-approval protocols mandate stability-critical chassis systems in new vehicle categories. Nagoya and Tokyo metropolitan areas concentrate suspension engineering organizations specifying valve tolerances and control logic in-house.
South Korea
Domestic OEMs source semi-active modules aggressively for mid-luxury crossover platforms, balancing performance against manufacturing simplicity. National automotive safety regulators align specification thresholds with EU and US frameworks to maintain export market access. Seoul Capital Area hosts integrated module producers competing for Tier-1 supplier contracts through software capabilities.
Automotive Electronic Suspension System (ESS) Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The supplier base organizes around three distinct competitive positions: integrated actuator specialists commanding magnetorheological valve architectures, cost-engineered module producers targeting volume OEM programs, and software-centric vendors capturing algorithm development value. Market structure favors consolidation around vendors capable of delivering both hardware precision and localized control logic. Dominant competitive moves include strategic partnerships for ADAS integration and geographic expansion through domestic engineering center establishment.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Continental AG exemplify the capability-concentrated tier, occupying positions where actuator portfolio breadth intersects with software localization competencies. Tenneco Inc. represents the cost-engineered alternative, anchoring the scale-driven segment through semi-active module production for high-volume North American platforms. These three entities collectively illustrate how supplier positioning stratifies across technology intensity and price band targets.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Continental AG |
| Tenneco Inc. |
| Magna International Inc. |
| KYB Corporation |
| ThyssenKrupp AG |
| Hitachi Astemo Ltd. |
| BWI Group |
| Mando Corporation |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's freight rate volatility transmits directly into ESS module landed costs, amplifying price spreads between magnetorheological valve systems sourced from Chinese rare earth refineries and variable damping architectures manufactured in European machining clusters. This logistics cost dynamic reinforces supplier concentration in high-performance tiers while compressing margins for semi-active damper producers serving volume OEM programs.
Pricing Analysis
Geographic price spreads between German-engineered active suspension modules and Chinese-manufactured semi-active systems have widened as rare earth magnet input costs fluctuate. Pricing stratifies across premium magnetorheological, standard electrohydraulic, and economy variable damping tiers, with certification grade under EU General Safety Regulation and volume scale as primary differentiation drivers. Pricing pressure stems from hydraulic actuator cost floors that resist scale economies below 150,000 annual units per platform. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while luxury OEMs remain least sensitive due to brand premium absorption capacity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for magnetorheological fluid producers dependent on neodymium and dysprosium refining. Component manufacturing concentrates in Germany, China, and Japan, with precision-machined servo valves and high-pressure sealing systems as critical inputs. Single-source vulnerability persists for rare earth magnet supply from Chinese refining operations. Distribution runs through Tier-1 supplier direct OEM contracts, with aftermarket retrofit channels gaining share in predictive health monitoring segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Electronic Suspension System market is entering a cyclical recovery phase as NHTSA stability mandates force replacement demand across commercial vehicle fleets and Chinese EV platform launches accelerate specification escalation.
For Market Incumbents: Insulate algorithm development value through captive software localization centers in Shanghai and Shenzhen responding to MIIT technical guidelines. Deepen backward integration into magnetorheological fluid formulation to offset rare earth supply concentration risk. Prioritize cybersecurity certification investment under UN ECE R155 to extend development timelines as a competitive moat against emerging software-centric entrants. For New Entrants and Emerging Players: Aftermarket predictive damper health monitoring for North American long-haul trucking fleets represents the most penetrable entry point, given unbundling of suspension maintenance from powertrain service contracts. Software-defined damper control modules for Chinese domestic EV brands offer second-mover advantage through domestic engineering center establishment. Partner with specialized telematics providers rather than traditional parts distributors to access fleet procurement channels. For Investors and Strategic Acquirers: Integrated chassis-ADAS software stack vendors with demonstrated EU General Safety Regulation compliance represent the highest-conviction acquisition archetype for exposure to regulatory-driven consolidation. Long-term viability hinges on algorithm sophistication bandwidth rather than actuator manufacturing scale. Monitor homologation timeline friction for cybersecurity-enabled over-the-air updates as an inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Software Localization Center Establishment | MIIT technical guidelines in China reward domestic algorithm development with market access preferences. |
| Cybersecurity Certification Investment | UN ECE R155 compliance extends development timelines and creates scarcity value for qualified vendors. |
| Magnetorheological Fluid Backward Integration | Captive rare earth supply reduces exposure to Chinese refining concentration and input cost volatility. |
| Aftermarket Telematics Partnership | Fleet operators in California and Texas unbundle suspension maintenance, creating standalone procurement channels. |
| ADAS Sensor Fusion Integration | EU General Safety Regulation mandates force suspension systems into chassis-ADAS software stacks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA Federal Motor Vehicle Safety Standards filings, EU General Safety Regulation type-approval databases, MIIT new energy vehicle technical guidelines, and IHS Markit vehicle production data. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and fleet maintenance managers across United States, German, Chinese, and Japanese manufacturing clusters. Bottom-up module shipment estimates triangulate against top-down vehicle production forecasts by propulsion architecture and content per vehicle assumptions.
Forecast inputs incorporate vehicle class segmentation, propulsion architecture differentiation, electronic content per vehicle trajectories, OEM tier stratification, and regional production cluster dynamics across the analysis window. CAGRs derive from regression analysis of historical platform specification refresh cycles correlated with regulatory mandate implementation timelines. Algorithm sophistication curves and rare earth magnet price elasticity assumptions inform technology migration scenarios between semi-active and fully active architectures.
Practitioners should monitor rare earth supply disruption indicators, homologation timeline extensions for cybersecurity-enabled systems, and fleet operator contract unbundling velocity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market