
 Automotive Electronic Logging Device (ELD/E-Log) Market | 2026-2036
Automotive Electronic Logging Device (ELD/E-Log) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electronic Logging Device (ELD/E-Log) Market Intelligence
The availability of data science talent within fleet operations is bifurcating the competitive landscape between basic compliance and advanced analytics. Large-scale providers like Trimble leverage their established presence in transportation technology to serve enterprise clients. Samsara differentiates with a cloud-native platform integrating video and telematics for comprehensive operational visibility. Geotab competes on an open-platform model, enabling a broad ecosystem of third-party integrations for fleet operators.
An Automotive Electronic Logging Device is a certified hardware unit connecting to a vehicle's engine control module, often via the CAN Bus, to record driving time. Its primary purpose is to automate Hours of Service (HOS) compliance, replacing paper logbooks. While HOS Compliance is the core application, advanced Fleet Management features like route optimization are driving new growth. Mobile ELD solutions, utilizing smartphones, are gaining traction with smaller carriers due to lower upfront costs.
Regulatory frameworks are the primary market enabler, with the US Department of Transportation's ELD mandate setting a precedent. Similar regulations from Transport Canada and European Union rules for digital tachographs create compulsory demand for compliant devices. The key strategic decision for vendors and fleet managers is how to leverage captured data for predictive maintenance and safety analytics beyond basic compliance.
Market Dynamics
The market's central dynamic is the evolution from mandatory compliance hardware to integrated data platforms. While regulatory frameworks like the US Department of Transportation's ELD mandate created the initial demand, the current competitive axis is the value extracted from captured telematics data for operational efficiency.
Growth Catalysts
- Regulatory Mandates:Rules from the US DOT and Transport Canada create compulsory, non-discretionary demand for certified devices in North American commercial trucking.
- Insurance Premium Incentives:Commercial auto insurers offer reduced premiums for fleets using ELD data for safety monitoring, creating a direct financial incentive.
- Fleet Management Integration:Convergence with FMS platforms enables value-added services like route optimization, expanding the device's role beyond simple HOS logging.
Market Restraints
- Upfront Hardware Costs:The initial investment for certified hardware and installation remains a significant barrier for owner-operators and small fleets.
- Legacy Vehicle Integration:Connecting ELDs to older trucks lacking standardized CAN Bus ports is complex, costly, and requires specialized adapters or custom work.
- Data Privacy Concerns:Driver and union concerns regarding constant location tracking and potential misuse of data can create resistance to full implementation.
Strategic Opportunities
- Expansion in Emerging Markets:Countries like Brazil and Australia are evaluating HOS regulations, presenting a growth opportunity for vendors ahead of future mandates.
- Predictive Maintenance Services:Leveraging engine fault code data from ELDs to offer predictive maintenance analytics is a high-value service beyond basic compliance.
- AI-Powered Analytics:Applying AI to telematics data can identify patterns for accident prediction, creating new subscription-based revenue streams for providers.
Industry Challenges
- Data Science Talent Scarcity:A shortage of data scientists within fleet operations limits carriers' ability to translate raw ELD data into actionable business intelligence.
- Backend System Integration:Integrating cloud-native ELD platforms with legacy, on-premise Transportation Management Systems (TMS) is a significant technical challenge for large fleets.
- Data Standardization Gaps:A lack of universal standards for telematics data formats complicates analysis for fleets that use hardware from multiple ELD vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electronic Logging Device (ELD/E-Log) Market |
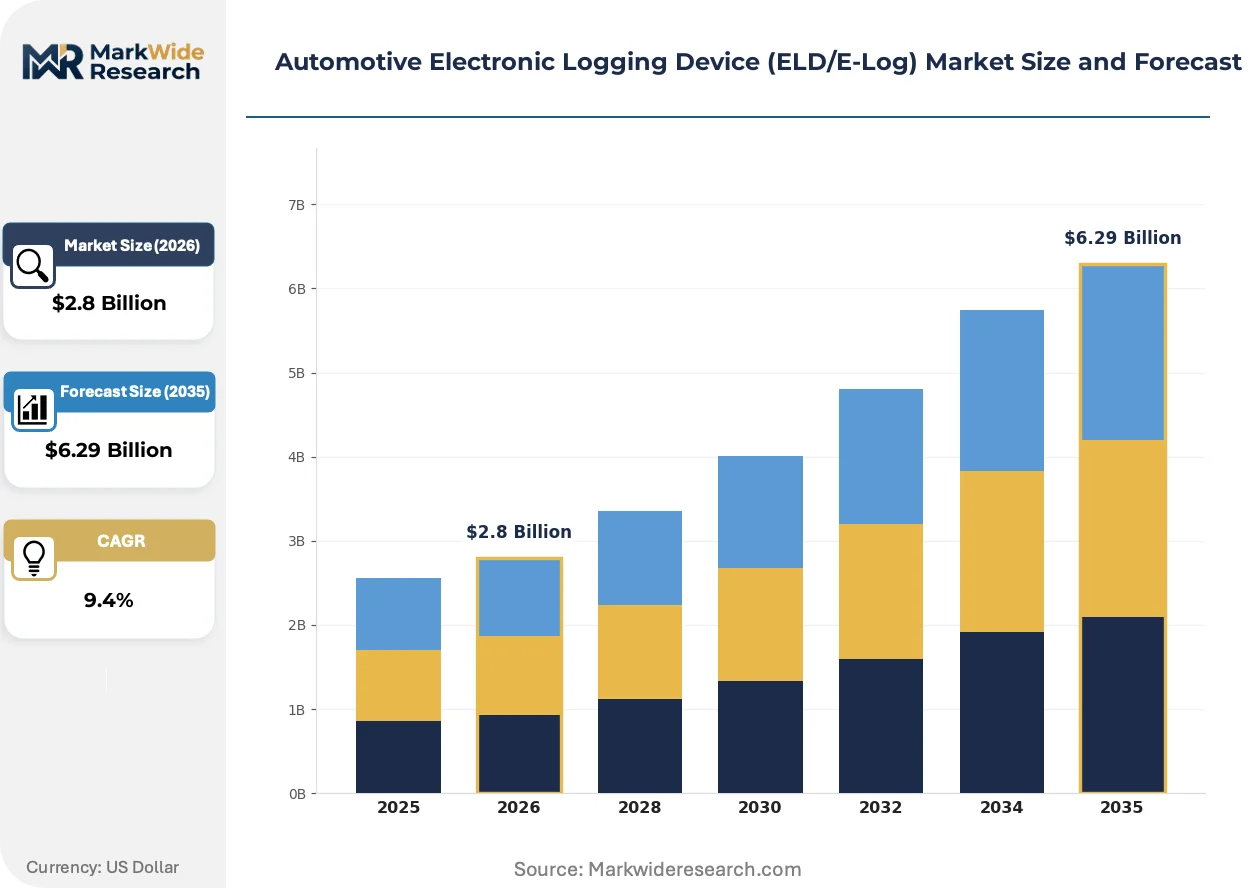
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart ELD, Dedicated ELD, Mobile ELD, Integrated ELD, Wired ELD Technology: Bluetooth, GPS, Cellular Network, CAN Bus Interface, Wi-Fi Application: Fleet Management, Hours of Service Compliance, Driver Performance Monitoring, Route Optimization, Maintenance Scheduling End User: Long-Haul Trucking, Local Delivery, Freight Carriers, Vehicle Leasing Companies, Transport Operators |
| Companies Covered | Garmin, Trimble, Samsara, Geotab, Azuga, Motive, Verizon Connect, Omnitracs, EROAD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electronic Logging Device (ELD/E-Log) Market Strategic Shifts & Innovations
The ELD market is transitioning from a hardware-centric tool into a software-defined ecosystem. This shift is driven by the increasing value of data analytics for enhancing safety, efficiency, and predictive management across commercial fleets.
Bring Your Own Device (BYOD) solutions use a driver's smartphone as the interface, connected via Bluetooth to a small dongle. Smaller carriers and owner-operators are rapidly adopting these systems due to minimal upfront hardware costs. This trend is miniaturizing the dedicated ELD hardware into a simple data dongle, shifting value to the mobile software and cloud platform.
European Union regulations for Smart Tachograph version 2 are expanding the scope of mandatory data collection. The rules mandate features like automatic border crossing detection, going beyond traditional Hours of Service tracking. All new heavy vehicles in the EU are affected, forcing vendors to develop next-generation devices and fleets to manage more complex data.
A demand-side shift from one-time hardware sales to recurring subscription services is altering vendor business models. The traditional model is being replaced by tiered Software-as-a-Service (SaaS) bundles including compliance, video telematics, and analytics. This is most visible among large enterprise fleets in the United States seeking integrated, scalable platforms.
Automotive Electronic Logging Device (ELD/E-Log) Market Segmentation
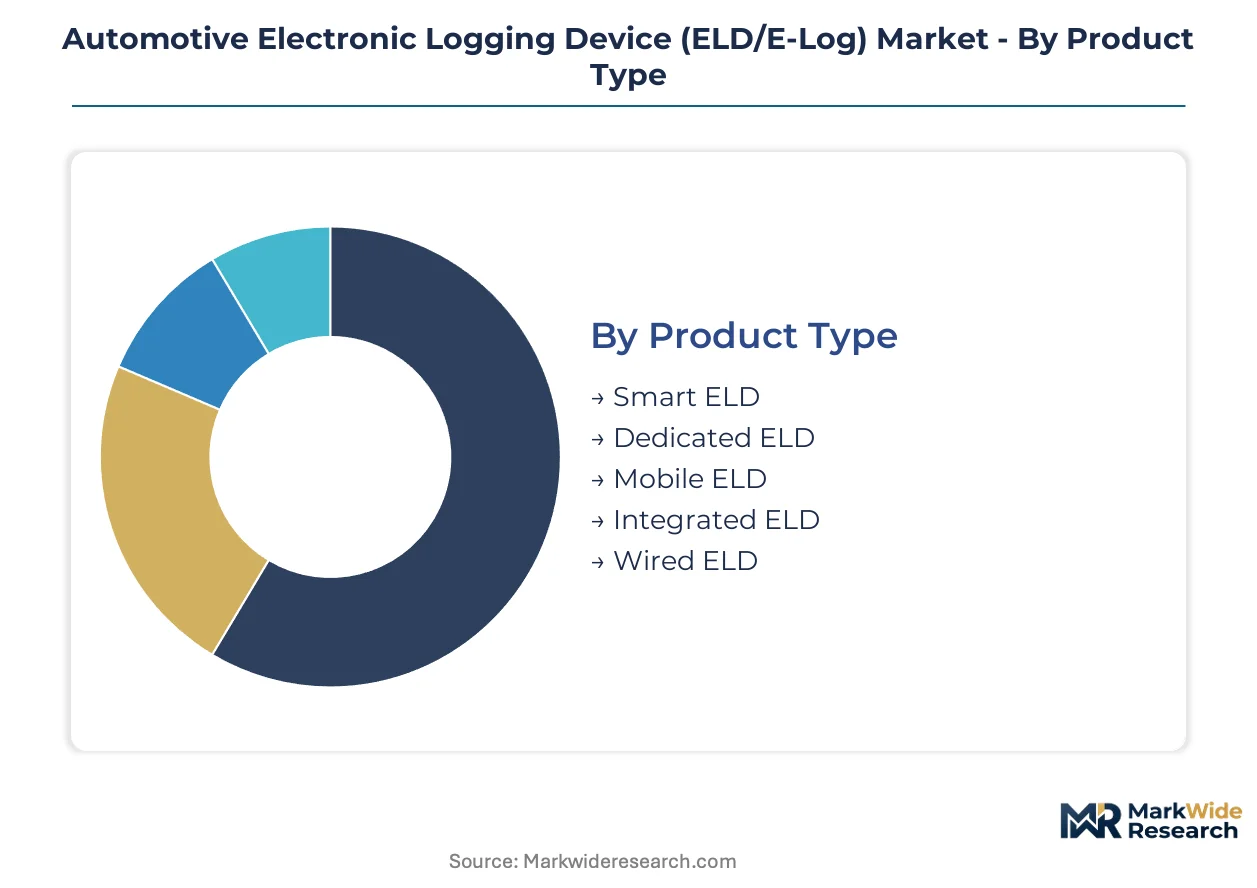
Understanding the Automotive Electronic Logging Device market through segmentation reveals how regulatory compliance mechanisms intersect with evolving technological capabilities. This granular view clarifies how different product types and underlying technologies address varied application needs and serve distinct end-user operational models. Analyzing these segments provides insight into the market's current structure and future growth trajectories.
Product Type:
Regulatory differentiation drives the adoption patterns across various ELD product types, influencing their design and market penetration. Devices must meet specific governmental certification standards to ensure accurate Hours of Service (HOS) logging and data integrity.
- Dedicated ELD:These are purpose-built hardware units directly integrated with the vehicle's engine control module, providing robust, tamper-resistant data capture for HOS compliance. Demand concentrates in large fleet operations in the United States due to strict federal mandates requiring certified, reliable solutions.
- Mobile ELD:This category leverages smartphones or tablets as the driver interface, connecting via Bluetooth to a small vehicle dongle for data transmission. Smaller carriers and owner-operators in North America favor these solutions due to their significantly lower upfront hardware costs and ease of deployment.
- Smart ELD:These devices incorporate advanced features such as AI-driven analytics, real-time alerts, and integration with broader telematics platforms.
- Integrated ELD:Solutions that combine ELD functionality directly within a broader fleet management system, offering a unified platform for multiple operational tasks.
- Wired ELD:Devices that establish a physical, hardwired connection to the vehicle's diagnostic port, ensuring stable data transfer without wireless interference.
Established volume favors Dedicated ELD; emerging adoption favors Mobile ELD.
Technology:
Cost tiering influences the selection of underlying technologies, balancing between real-time data transmission needs and hardware integration complexities. Each technology enables distinct levels of data fidelity and communication speed for ELD functionalities.
- CAN Bus Interface:This technology directly taps into the vehicle's internal communication network, extracting precise engine data, mileage, and driving status. Commercial fleets prioritize this interface for its accuracy and direct access to critical operational parameters.
- Cellular Network:Utilized for real-time transmission of HOS data, GPS coordinates, and telematics information from the ELD to cloud-based platforms. This connectivity is critical for dispatch, compliance monitoring, and advanced analytics in long-haul trucking.
- Bluetooth:Enables short-range wireless communication, primarily used to connect mobile devices (smartphones/tablets) to a vehicle's ELD dongle.
- GPS:Provides precise location tracking and mileage calculations, essential for HOS compliance, route optimization, and geofencing capabilities.
- Wi-Fi:Often used for local data synchronization or connecting ELD devices to in-cab tablets for driver access to logs and other applications.
Adoption of CAN Bus Interface underpins fundamental data capture, while Cellular Network enables advanced connectivity features.
Application:
The application scope defines the primary use cases for ELD systems, ranging from basic regulatory adherence to comprehensive operational enhancements. Each application addresses specific pain points or efficiency goals for commercial fleets.
- Hours of Service Compliance:The foundational application of ELDs, automating the recording of driving time to meet federal and provincial regulations in countries like the United States and Canada. This application remains the primary market driver due to its mandatory nature for commercial carriers.
- Fleet Management:This broad application integrates ELD data with other telematics to optimize overall fleet operations, including asset tracking, vehicle diagnostics, and driver behavior monitoring. Large enterprise fleets leverage these integrated platforms for holistic visibility and control.
- Driver Performance Monitoring:Utilizes ELD data on speed, harsh braking, and acceleration to assess and improve driver safety and efficiency.
- Route Optimization:Leverages GPS data from ELDs to plan more efficient routes, reducing fuel consumption and delivery times for transport operators.
- Maintenance Scheduling:Uses engine fault codes and mileage data from ELDs to proactively schedule vehicle maintenance, minimizing downtime for freight carriers.
Core regulatory functions drive demand for Hours of Service Compliance, with Fleet Management expanding operational efficiencies.
End User:
Volume and operational scale categorize end-users, highlighting how different fleet sizes and operational models adopt ELD technology. Each segment has distinct requirements for deployment, features, and cost structures.
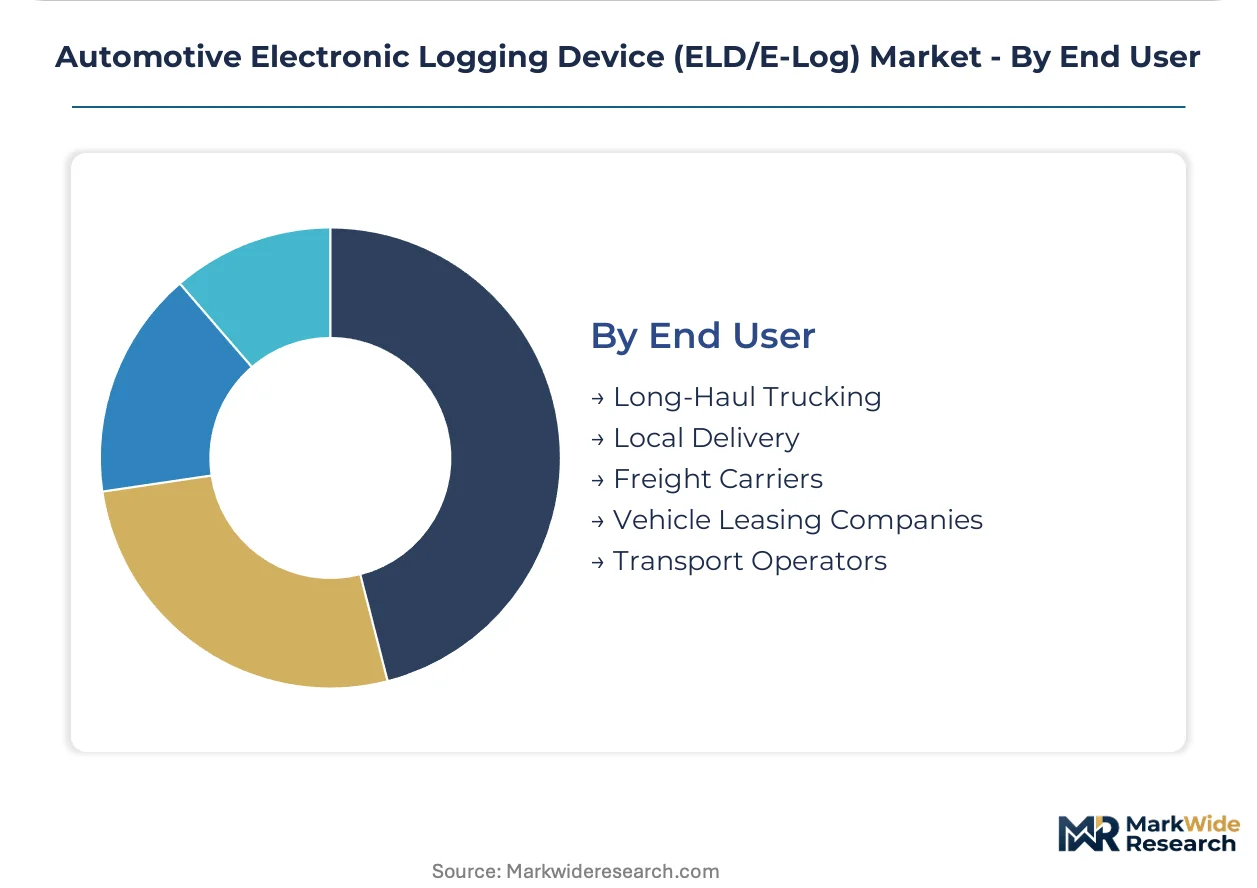
- Long-Haul Trucking:This segment represents the largest end-user base, characterized by extensive driving hours and strict HOS compliance requirements across vast geographical areas. North American long-haul carriers are the primary adopters due to the comprehensive ELD mandates.
- Local Delivery:Fleets operating within defined urban or regional areas, often with multiple stops and shorter driving cycles, utilize ELDs for compliance and route efficiency. Growing e-commerce volumes drive demand for ELD solutions in this segment.
- Freight Carriers:Companies specializing in the transportation of goods, encompassing both long-haul and regional operations, rely on ELDs for regulatory adherence and logistical optimization.
- Transport Operators:A broad category including passenger transport, specialized hauling, and other commercial vehicle operations that require HOS logging.
- Vehicle Leasing Companies:Provide ELD-equipped vehicles to their clients, offering compliance solutions as part of their service package.
The largest fleets prioritize Long-Haul Trucking, while Local Delivery caters to specialized operational needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Transportation's ELD mandate established a foundational market for electronic logging devices. This regulation created compulsory demand, driving early adoption across North American commercial trucking. Subsequent mandates in other regions continue to shape market expansion.
United States
United States demand for ELDs stems primarily from the federal Hours of Service (HOS) mandate. The US Department of Transportation (DOT) requires certified devices for commercial vehicles, ensuring compliance and enhancing road safety. Major logistics hubs like Chicago and Atlanta see high ELD deployment among large trucking fleets.
Canada
Transport Canada regulations drive significant ELD adoption across Canadian commercial trucking operations. The federal ELD mandate ensures consistent HOS compliance for carriers operating inter-provincially or internationally. Vancouver and Toronto serve as key centers for ELD integration into cross-border and domestic logistics.
Germany
European Union rules for digital tachographs mandate data collection for driving and rest times, influencing ELD market evolution. The German Federal Motor Transport Authority (KBA) oversees compliance for heavy vehicles within Germany. Munich and Hamburg feature advanced telematics integration within their freight and transport sectors.
Brazil
Brazil's growing commercial vehicle sector shows increasing interest in ELD solutions for fleet efficiency. The National Traffic Department (DENATRAN) is evaluating potential HOS regulations to improve road safety and driver welfare. São Paulo and Rio de Janeiro are emerging hubs for early ELD trials and adoption within logistics companies.
Australia
Australian transport operators are exploring ELD technology to enhance safety and productivity. The National Heavy Vehicle Regulator (NHVR) is considering new HOS compliance frameworks for heavy vehicles. Sydney and Melbourne represent key markets for early ELD pilots and implementation within freight and delivery services.
Automotive Electronic Logging Device (ELD/E-Log) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the ELD market. The competitive landscape bifurcates between established providers offering comprehensive enterprise solutions and agile innovators focusing on mobile or cloud-native platforms. Strategic archetypes include large-scale transportation technology companies, specialized telematics firms, and emerging software-as-a-service (SaaS) providers. Portfolio diversification into advanced analytics and strategic partnerships are key competitive moves.
Within the enterprise solutions segment, Trimble exemplifies a provider leveraging its established presence in transportation technology to serve large fleet clients. This company's offerings often cater to complex operational needs, integrating ELD functions with broader fleet management systems. Samsara, a cloud-native platform specialist, differentiates through integrating video and telematics for comprehensive operational visibility, appealing to fleets seeking advanced data insights. Geotab occupies a position as an open-platform enabler, fostering a broad ecosystem of third-party integrations for diverse fleet operators. Its strategy focuses on flexibility and customization through extensive API access, supporting a wide range of fleet sizes and operational models.
| Leading Market Players |
|---|
| Garmin |
| Trimble |
| Samsara |
| Geotab |
| Azuga |
| Motive |
| Verizon Connect |
| Omnitracs |
| EROAD |
| Others |
Cost & Logistics Intelligence
Shifting from dedicated ELD hardware to mobile ELD software platforms is reshaping manufacturing focus and value capture. This transition influences where components are sourced and how pricing models evolve from one-time sales to recurring subscriptions.
Pricing Analysis
Price spreads for ELD solutions show regional variations, with North America commanding higher average subscription rates due to strict mandates. The dominant pricing structure is SaaS-tiered, offering compliance, telematics, and advanced analytics bundles. Price differentiation stems from certification levels and the breadth of integrated fleet management features. Pricing softness affects basic compliance hardware due to mobile ELD alternatives, while large enterprise fleets prioritize value-added services over cost, making owner-operators highly price-sensitive.
Supply Chain Analysis
Inbound logistics costs, particularly for semiconductor chips and electronic components, impact ELD hardware manufacturing. Supply chain concentration for these critical components centers heavily in China and other East Asian nations. The industry relies on a stable supply of CAN Bus connectors and other specialized electronics. A structural risk involves single-source vulnerability for certain proprietary hardware elements. Distribution runs through direct sales channels for enterprise clients and a network of resellers for smaller carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ELD market is expanding beyond initial compliance, driven by the increasing penetration of advanced telematics and data analytics. This shift represents an early-cycle expansion phase, moving from mandatory adoption to value-driven integration.
For Market Incumbents: Compound existing client relationships by expanding integrated fleet management platforms. Defend against cloud-native SaaS providers by acquiring specialized AI analytics firms to enhance predictive maintenance capabilities. Invest in API development for seamless integration with legacy Transportation Management Systems, strengthening enterprise client stickiness. Prioritize certification investment for new regulatory mandates, such as Smart Tachograph version 2 in the EU.
For New Entrants and Emerging Players: Certification fast-tracking for mobile ELD solutions offers a rapid entry point into the owner-operator segment. Target emerging markets like Brazil and Australia, anticipating future HOS regulations, with low-cost, easy-to-deploy BYOD offerings. Focus on niche applications, such as specialized hauling, where current solutions lack tailored analytics. A go-to-market angle involves bundling basic compliance with scalable, subscription-based advanced features as fleets grow.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized telematics firms, offering opportunities for platform consolidation. The market's long-term viability extends across a 5-10 year window, driven by the increasing value of operational data. Target cloud-native telematics platforms with robust AI/ML capabilities and strong recurring revenue models. A key signal to watch is the pace of consolidation among mid-sized SaaS ELD providers, indicating market maturity and M&A readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI/ML Analytics Provider | Enhances predictive capabilities for fleet maintenance and safety. |
| Expand Mobile ELD Portfolio | Captures market share from owner-operators and small fleets. |
| Develop Open API Ecosystem | Fosters third-party integrations and platform stickiness. |
| Invest in EU Smart Tachograph 2 Compliance | Ensures access to the European commercial vehicle market. |
| Form Strategic Partnerships with Insurers | Creates financial incentives for ELD adoption through reduced premiums. |
Research Approach
Operator-level perspectives from fleet managers, ELD software engineers, and regulatory compliance officers anchored the qualitative base. This primary fieldwork was triangulated with extensive secondary research, including US DOT filings, Transport Canada reports, and commercial vehicle registration databases. A bottom-up and top-down analytical approach validated market sizing and segmentation across various operational models.
Sensitivity analysis informed the projection framework across the analysis window, modeling various adoption scenarios. The framework segmented the market by product type, underlying technology, application, and end-user, alongside regional regulatory nuances. CAGRs were derived by assessing historical growth trends and future compliance rates. Commercial vehicle sales data and HOS mandate enforcement levels served as key forecast inputs.
Decision-makers should treat outputs as directional under current regulatory stability and technology adoption rate assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, acknowledging potential shifts from unforeseen regulatory changes or rapid technological disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market