
 US Automotive EPS Market | 2026-2036
US Automotive EPS Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive EPS Market Outlook
ISO 26262 functional safety certification is bifurcating the supplier base into qualified tier-1 integrators and peripheral component vendors. Robert Bosch GmbH leverages its semiconductor and sensor portfolio to sustain integrated EPS module production. Nexteer Automotive anchors its position through manufacturing scale across Midwest production facilities. ZF Friedrichshafen AG competes on steering system architectures that span passenger and commercial vehicle platforms.
US Automotive EPS encompasses electromechanical steering assistance systems that replace hydraulic pumps with brushless DC motors, torque sensors, and electronic control modules to reduce fuel consumption and enable advanced driver assistance features. Electric Power Steering dominates installed volume across passenger vehicles, while Column-Assisted Steering configurations command margin pools in light truck applications where packaging constraints favor integrated column designs. Brushless DC Motor technology leads technology segment value due to thermal efficiency requirements, and Control Module integration intensifies as automakers consolidate ECU architectures.
NHTSA Corporate Average Fuel Economy standards and EPA emissions regulations directly shape OEM procurement priorities toward EPS adoption over hydraulic alternatives. The SEC climate disclosure rules and California Air Resources Board zero-emission vehicle mandates create additional compliance layers affecting steering system electrification roadmaps. Stakeholders must monitor how NHTSA updates to FMVSS 126 electronic stability control requirements will redefine torque sensor performance thresholds and supplier qualification timelines.
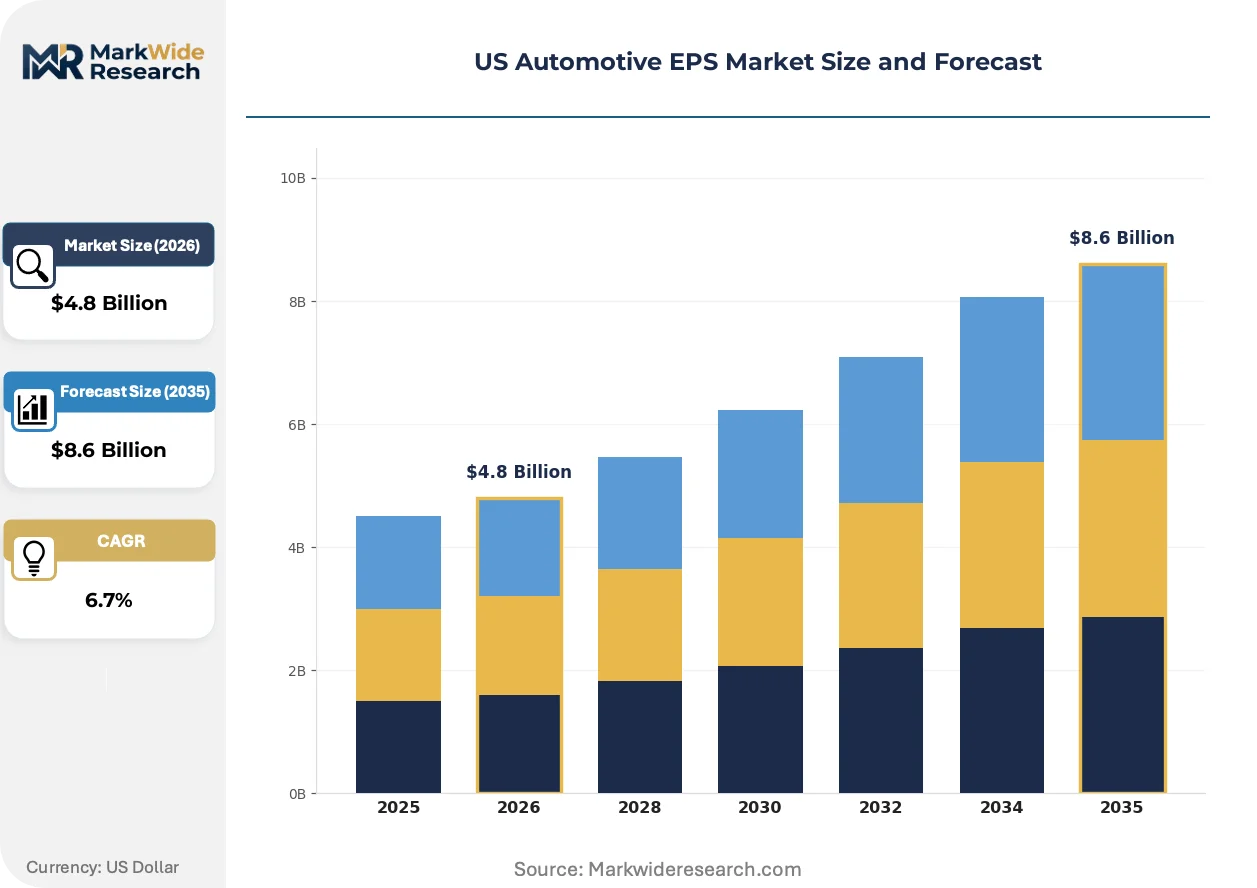
Market Dynamics
NHTSA fuel economy mandates and EPA emissions regulations are compressing procurement timelines as OEMs replace hydraulic steering with electromechanical systems to shed parasitic engine load. Supplier qualification cycles have shortened while ISO 26262 certification requirements have sharpened technical barriers.
Growth Catalysts
- Corporate Average Fuel Economy standards:NHTSA mandates force automakers toward EPS to improve fleet-wide efficiency metrics. Light truck manufacturers in Michigan and Ohio are expanding orders for brushless DC motor systems.
- Brushless DC motor thermal efficiency:Advanced motor designs reduce heat dissipation requirements. Southeast automotive corridor assembly plants in Tennessee, South Carolina, and Alabama prioritize these configurations for high-duty-cycle applications.
- Electronic stability control integration:FMVSS 126 updates require torque sensor performance upgrades. Tier-1 integrators are capturing module consolidation contracts as automakers reduce ECU counts.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing depends on concentrated overseas refining capacity. Brushless DC motor producers face input cost volatility and geopolitical exposure.
- ISO 26262 ASIL-D certification timelines:Functional safety qualification stretches 18-24 months for new sensor architectures. Peripheral component vendors lack capital to bridge this gap.
- Hydraulic steering residual demand:Heavy-duty commercial vehicle segments retain hydraulic systems for extreme load conditions. EPS thermal limits constrain penetration in these niche applications.
Strategic Opportunities
- Steer-by-wire architecture convergence:Integration of EPS with autonomous driving platforms creates new module categories. Control unit suppliers can capture value from sensor fusion requirements.
- SEC climate disclosure compliance:Scope 3 emissions tracking pushes OEMs toward documented supply chain decarbonization. Certified EPS suppliers gain preferred vendor status in sustainability scoring.
- Midwest manufacturing cluster expansion:Ohio and Indiana production facilities offer proximity to Detroit Three engineering centers. Regional suppliers reduce logistics costs and improve just-in-sequence delivery.
Industry Challenges
- Embedded software talent scarcity:Functional safety firmware development requires specialized engineers familiar with AUTOSAR and ASIL-rated systems. Recruiting bottlenecks delay product validation cycles.
- Legacy vehicle platform integration:Retrofitting EPS into existing electrical architectures demands custom harness and power management solutions. Engineering resources fragment across one-off adaptation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive EPS Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Power Steering, Hydraulic Power Steering, Electro-Hydraulic Power Steering, Column-Assisted Steering Technology: Stroke Motor, Brushless DC Motor, Torque Sensor, Control Module End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Light Trucks, Heavy-Duty Trucks |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, ZF Friedrichshafen AG, Robert Bosch GmbH, NSK Ltd., Hyundai Mobis Co., Mitsubishi Electric Corporation, Denso Corporation, Hitachi Astemo, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive EPS Market Strategic Shifts
Electrification of steering systems is accelerating module consolidation as automakers reduce component counts. Three interconnected developments are compressing supplier margins while opening new technical differentiation paths.
Brushless DC motor technology is fragmenting competitive positioning across the supplier base. These motors deliver superior thermal efficiency for high-torque steering assist. Light truck manufacturers in the Southeast automotive corridor are specifying them for towing and payload applications. The technology is fragmenting incumbent supplier relationships as motor specialists bypass traditional tier-1 integrators.
NHTSA updates to FMVSS 126 electronic stability control requirements are tightening torque sensor performance thresholds. The regulation mandates faster response times and higher accuracy across temperature extremes. Passenger vehicle platforms face the steepest compliance curves. Suppliers are requalifying sensor architectures ahead of enforcement deadlines to maintain OEM qualification status.
Automaker procurement teams are consolidating ECU sourcing around integrated steering modules. Discrete component purchasing is giving way to subsystem contracts with single-source accountability. Tier-1 integrators with semiconductor and sensor portfolios are capturing these consolidated awards. The shift is most visible among Detroit Three programs where engineering headcount constraints favor outsourced module development.
US Automotive EPS Market Segmentation
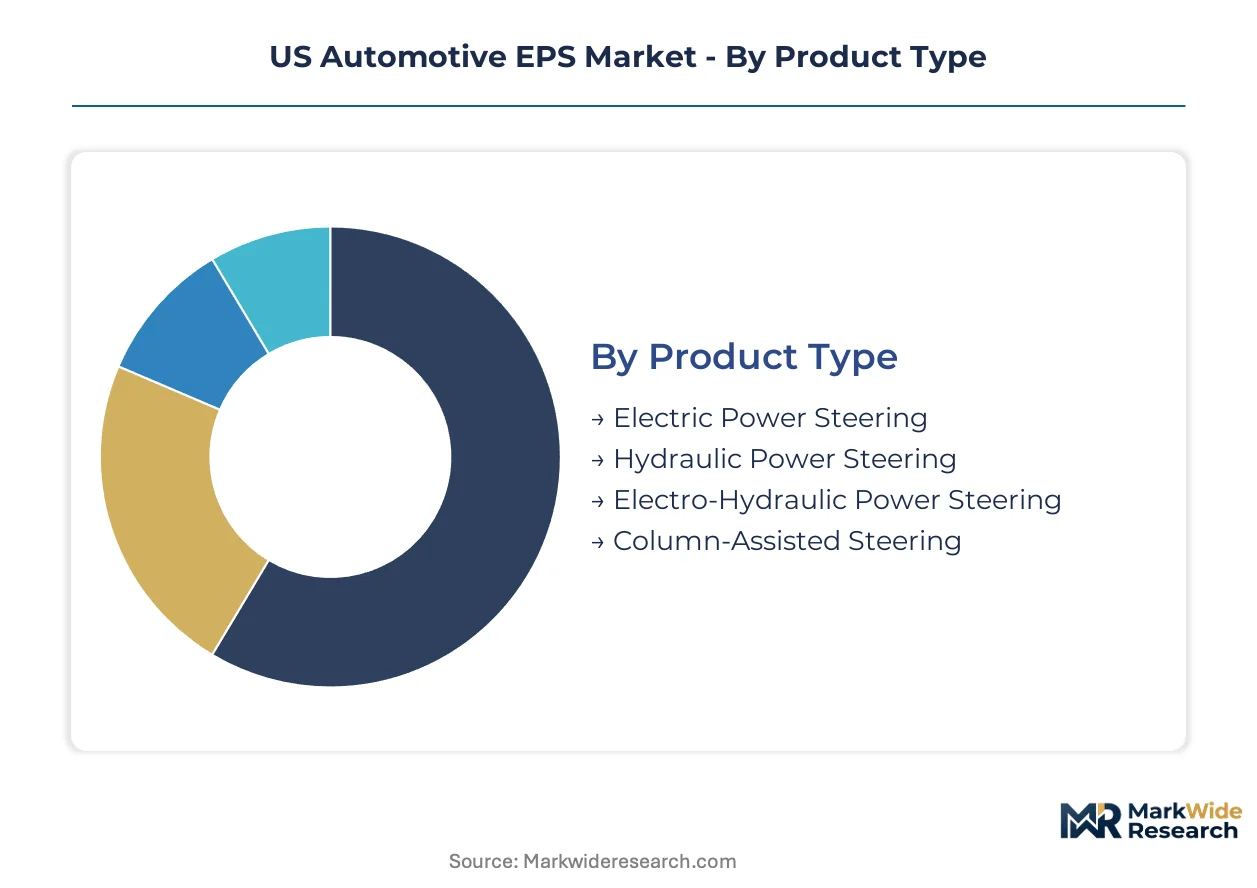
Segmentation in the US Automotive EPS Market reveals how regulatory pressure and platform electrification reshape procurement patterns across distinct technology tiers and vehicle categories. Understanding these divisions exposes where supplier margins concentrate and where volume growth accelerates.
Product Type:
Domestic production clusters in Michigan and Ohio favor integrated column designs for light trucks, while export-oriented passenger platforms drive rack-mounted configurations for compact vehicles.
- Electric Power Steering:Fully electromechanical systems replace hydraulic pumps with brushless DC motors and electronic control modules. Passenger vehicle assembly plants across the Southeast automotive corridor specify these for NHTSA fuel economy compliance, with Tennessee and Alabama facilities leading procurement volume.
- Column-Assisted Steering:Integrated motor and control unit designs mount directly to the steering column, reducing packaging complexity. Light truck manufacturers in Michigan prioritize this configuration for towing applications where cabin space constraints limit rack-mounted alternatives.
- Hydraulic Power Steering:Engine-driven pump systems retain niche presence in heavy-duty commercial segments requiring sustained high-torque assist.
- Electro-Hydraulic Power Steering:Hybrid architectures combine electric motor control with hydraulic actuation, serving transitional platforms bridging legacy and full-electric steering.
Electric Power Steering holds the largest share; momentum sits with Column-Assisted Steering.
Technology:
Cost stratification separates commodity motor components from integrated control systems commanding premium pricing.
- Brushless DC Motor:Permanent magnet synchronous designs deliver superior thermal efficiency and torque density for high-duty-cycle applications. Southeast automotive corridor plants specify these for light truck towing configurations where heat dissipation limits conventional brushed alternatives.
- Control Module:Integrated ECU architectures consolidate torque processing, motor drive, and vehicle network communication. Tier-1 integrators capture these contracts as automakers reduce discrete component counts and outsource subsystem development.
- Stroke Motor:Linear actuator designs serve specialized rack-mounted applications requiring precise position control.
- Torque Sensor:Magnetostrictive and Hall-effect sensing elements measure driver input for closed-loop assist algorithms, with NHTSA FMVSS 126 updates tightening accuracy requirements.
Brushless DC Motor dominates installed value; Control Module integration is expanding most quickly.
End User:
Customer concentration varies sharply between captive OEM supply and fragmented aftermarket channels.
- OEMs:Detroit Three manufacturers and transplant automakers specify EPS at platform conception, locking in multi-year supply agreements with tier-1 integrators. NHTSA Corporate Average Fuel Economy mandates drive procurement timelines, with engineering centers in Michigan and Ohio anchoring qualification activity.
- Tier-1 Suppliers:Delphi, Bosch, and Nexteer package complete steering subsystems for direct vehicle assembly, consolidating semiconductor, sensor, and motor sourcing under single-source accountability.
- Vehicle Assemblers:Contract manufacturing operations in the Southeast automotive corridor integrate EPS modules into finished vehicles.
- Aftermarket Providers:Independent distributors serve collision repair and retrofit demand, though EPS complexity limits this channel relative to hydraulic alternatives.
OEMs command the largest procurement volume; Tier-1 Suppliers are gaining share fastest through module consolidation.
Application:
Vehicle duty cycle determines thermal specification and margin structure across passenger and commercial segments.
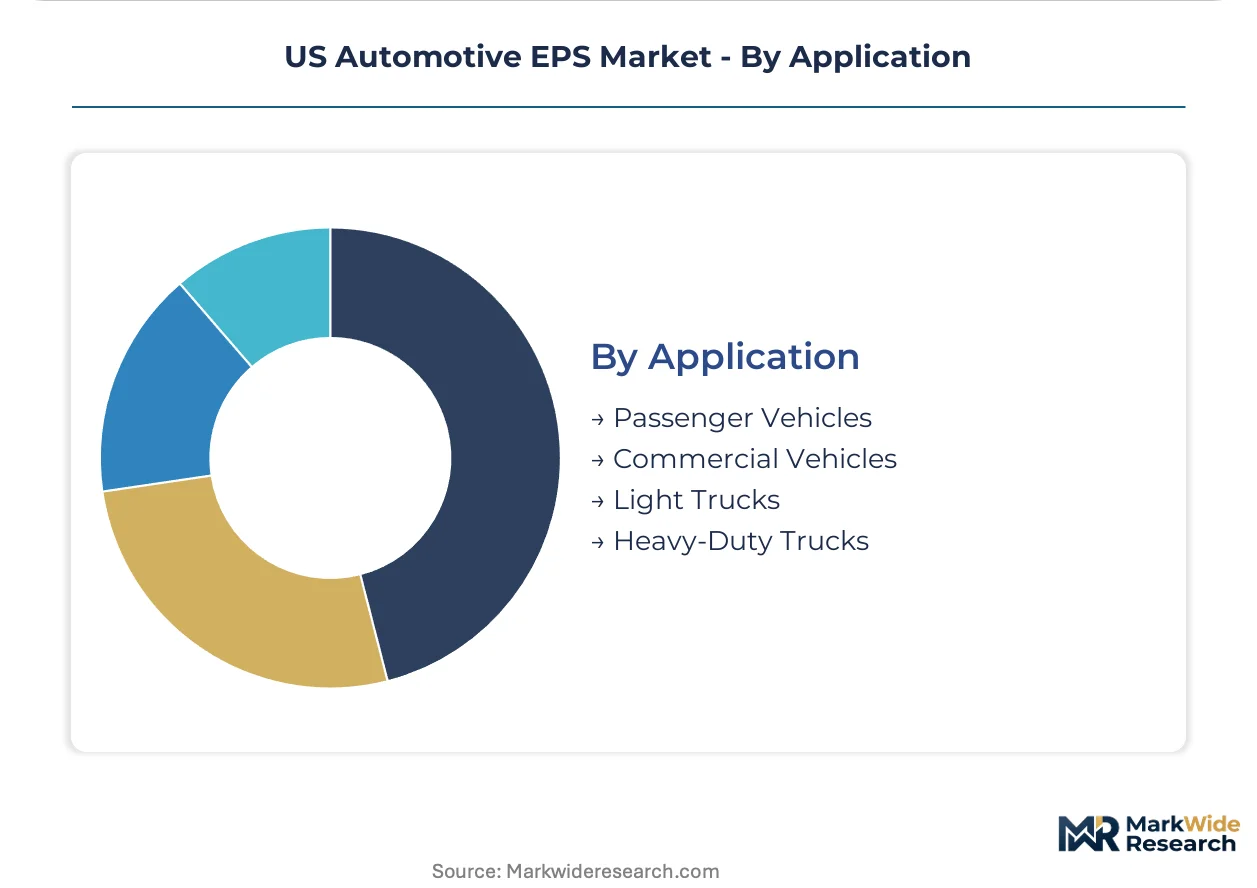
- Passenger Vehicles:Compact and mid-size platforms prioritize packaging efficiency and fuel economy, driving rack-mounted EPS adoption. Assembly plants across Ohio, Kentucky, and Tennessee produce these configurations at highest volume.
- Light Trucks:Full-size pickup and SUV platforms require higher torque assist for towing and payload, favoring column-assisted or dual-pinion rack designs. Michigan and Indiana production facilities specialize in these higher-capacity systems.
- Commercial Vehicles:Delivery van and medium-duty truck segments adopt EPS for urban stop-start efficiency, though thermal limits constrain penetration.
- Heavy-Duty Trucks:Extreme load conditions and sustained high-torque demand preserve hydraulic system dominance in long-haul applications.
Passenger Vehicles retain the largest share; Light Trucks show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest OEM engineering centers and Southeast transplant assembly plants concentrate procurement authority for US Automotive EPS systems. Tier-1 integrators locate manufacturing capacity near these buyer clusters to compress logistics cycles and support just-in-sequence delivery.
Michigan
Detroit Three headquarters and light truck engineering centers drive specification authority for high-torque column-assisted configurations. NHTSA Corporate Average Fuel Economy mandates accelerate platform electrification timelines. Warren and Sterling Heights production facilities anchor module integration capacity for full-size pickup programs.
Ohio
Passenger vehicle assembly plants and powertrain R&D operations generate demand for rack-mounted EPS systems. EPA emissions regulations shape supplier qualification requirements. The Dayton-Springfield corridor hosts brushless DC motor manufacturing clusters serving Midwest OEM programs.
Tennessee
Transplant automaker assembly operations prioritize fuel economy-optimized steering systems for compact and mid-size platforms. SEC climate disclosure rules influence supply chain sustainability scoring. The Nashville-Franklin automotive corridor concentrates EPS module integration for export-oriented production.
South Carolina
BMW and Volvo assembly plants specify thermal-efficient steering configurations for high-duty-cycle applications. NHTSA FMVSS 126 updates drive torque sensor performance upgrades. The Upstate region around Greer anchors sensor and control module supplier operations.
Alabama
Mercedes-Benz and Hyundai-Kia assembly facilities generate procurement volume for integrated steering subsystems. State economic development incentives attract tier-1 supplier manufacturing investments. The Tuscaloosa-Montgomery production corridor specializes in column-assisted EPS for light truck platforms.
US Automotive EPS Market Competitive Environment
Player mix skews toward diversified tier-1 automotive suppliers with integrated electromechanical portfolios. Market structure concentrates around a half-dozen full-system integrators capable of ISO 26262 ASIL-D certification and multi-platform program execution. Two strategic archetypes dominate: semiconductor-rich diversified industrials leveraging sensor and control module integration, and steering-focused specialists anchoring position through manufacturing scale and OEM relationship depth. Competitive moves center on module consolidation contracts capturing ECU integration scope, and geographic proximity investments compressing logistics costs to Midwest and Southeast assembly corridors.
Within the integrated-system tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify diversified industrial positioning through electromechanical and sensor portfolio breadth. Nexteer Automotive occupies a position representing steering-specialist scale, with Midwest manufacturing footprint aligned to Detroit Three engineering centers. JTEKT Corporation anchors the Japanese supplier archetype, while Hyundai Mobis Co. represents Korean chaebol-affiliated tier-1 integration. These five entities collectively illustrate the competitive spectrum from diversified industrial conglomerates to focused steering system specialists.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| NSK Ltd. |
| Hyundai Mobis Co. |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Hitachi Astemo, Ltd. |
| Others |
Value Chain & Pricing Dynamics
ISO 26262 ASIL-D certification gates both supplier qualification and price differentiation in US Automotive EPS procurement, concentrating margin capture among tier-1 integrators while peripheral vendors face compressed pricing power from extended validation timelines. NHTSA fuel economy mandates compress OEM procurement cycles, amplifying the premium commanded by pre-certified module suppliers against uncertified alternatives.
Pricing Analysis
Cost-plus contracts with rare earth magnet indexation dominate tier-1 EPS procurement, with neodymium and dysprosium price volatility passed through via quarterly adjustments. Pricing stratifies across ASIL-D certified integrators, ASIL-B qualified component vendors, and non-certified commodity motor suppliers, with the Detroit Three exhibiting highest price sensitivity in light truck programs where volume scale offsets certification premiums. Cost compression in brushless DC motor components is intensifying because motor specialists are bypassing traditional integrators, eroding historical markup structures.
Supply Chain Analysis
Inbound logistics costs from Asian rare earth refining centers through West Coast ports constrain just-in-sequence delivery windows for Southeast automotive corridor assembly plants. Neodymium and dysprosium sourcing draws from concentrated Chinese refining capacity, while semiconductor-grade torque sensors and control module ASICs rest on Taiwan and South Korea fabrication. Single-source vulnerability in permanent magnet supply creates tariff exposure risk. Distribution runs through tier-1 integrator hubs in Michigan and Ohio before final assembly sequencing to OEM lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Automotive EPS is approaching a platform-economics inflection as steer-by-wire architectures demand unified sensor fusion and software stack interoperability across autonomous driving platforms. Module consolidation contracts are rewiring competitive boundaries around integrated electromechanical portfolios rather than discrete component supply.
For Market Incumbents: Compound manufacturing scale advantages in Midwest production clusters by anchoring brushless DC motor capacity near Detroit Three engineering centers. Deepen backward integration into torque sensor semiconductor sourcing to defend against motor specialists encroaching on module integration scope. Prioritize ASIL-D certification maintenance ahead of NHTSA FMVSS 126 enforcement deadlines to preserve OEM qualification status. For New Entrants and Emerging Players: ISO 26262 fast-track partnerships with established tier-1 integrators offer the most viable path around 18-24 month certification barriers. Target aftermarket collision repair channels where EPS complexity limits incumbent presence and price sensitivity runs lower than OEM procurement. Pursue white-label control module development for commercial vehicle retrofits as the fastest-penetrable segment outside passenger vehicle platform lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across steer-by-wire R&D programs as sensor fusion requirements expand engineering headcount needs. Five-to-ten year viability favors suppliers with demonstrated multi-platform execution and captive semiconductor access. Acquisition target archetype: steering-focused specialists with ISO 26262 credentials and Southeast corridor manufacturing presence. Watch NHTSA updates to electronic stability control torque thresholds as the signal indicating qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated EPS architectures reduce ECU counts for Detroit Three electrification roadmaps. |
| Software-Defined Vehicle Investment | Steer-by-wire integration with ADAS platforms creates new sensor fusion value capture. |
| Geographic Manufacturing Footprint | Midwest and Southeast corridor proximity compresses logistics costs for just-in-sequence delivery. |
| Battery Supply Agreement | EPS thermal efficiency gains extend electric vehicle range for NHTSA compliance scoring. |
| Charging Infrastructure Partnership | Commercial fleet electrification expands EPS adoption in delivery van stop-start applications. |
Study Parameters
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership service operations anchored the qualitative base for this study. Primary interview findings triangulated against vehicle production databases, IHS Markit registration data, NHTSA FMVSS docket filings, and SEC climate disclosure submissions. Bottom-up unit volume estimates across vehicle class, propulsion architecture, and regional production clusters converged with top-down market value reconciliation.
Sensitivity analysis tested forecast robustness across alternative NHTSA enforcement timelines and rare earth price trajectory assumptions. Segmentation dimensions modeled include product type, technology tier, end-user channel, and application duty cycle, with vehicle content per unit and OEM procurement tier as automotive-specific variables. CAGRs derived from regression-adjusted production forecasts incorporating platform electrification curves and regulatory compliance deadlines.
Underlying assumptions cover NHTSA fuel economy mandate continuity and rare earth supply chain stability, with deviation risk concentrated in geopolitical trade policy shifts and ISO 26262 certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market