
 Digital Video Recorder Market | 2026-2036
Digital Video Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Video Recorder Market Analysis
Commercial property managers is unwinding from residential subscribers as the dominant demand archetype for digital video recorder systems. Hangzhou Hikvision Digital Technology leverages integrated camera-recorder bundles to dominate enterprise security deployments across Asia. Dahua Technology competes through AI-enhanced analytics engines embedded in network DVR hardware. TiVo Corporation sustains brand recognition in consumer time-shifting applications despite cord-cutting headwinds.
A digital video recorder captures, compresses, and stores video streams to local hard disk or networked storage for deferred playback, typically supporting H.264/H.265 codecs and 1080p to 4K resolution pipelines. Network DVR architectures now lead product type segmentation as Ethernet and Wi-Fi connectivity displace coaxial installations in retrofit projects. Cloud DVR deployments represent the fastest-expanding feature category, though standalone DVR units still anchor margin pools in cost-sensitive emerging markets where bandwidth constraints persist.
FCC encryption mandates and ETSI data retention standards shape product certification timelines on both sides of the Atlantic, while China's GB standards and MIIT network security rules govern domestic manufacturing compliance. Regulatory fragmentation across these jurisdictions forces manufacturers to maintain multiple firmware branches and testing protocols. Stakeholders must monitor evolving cybersecurity labeling requirements as governments tighten supply chain scrutiny on video surveillance components.
Market Dynamics
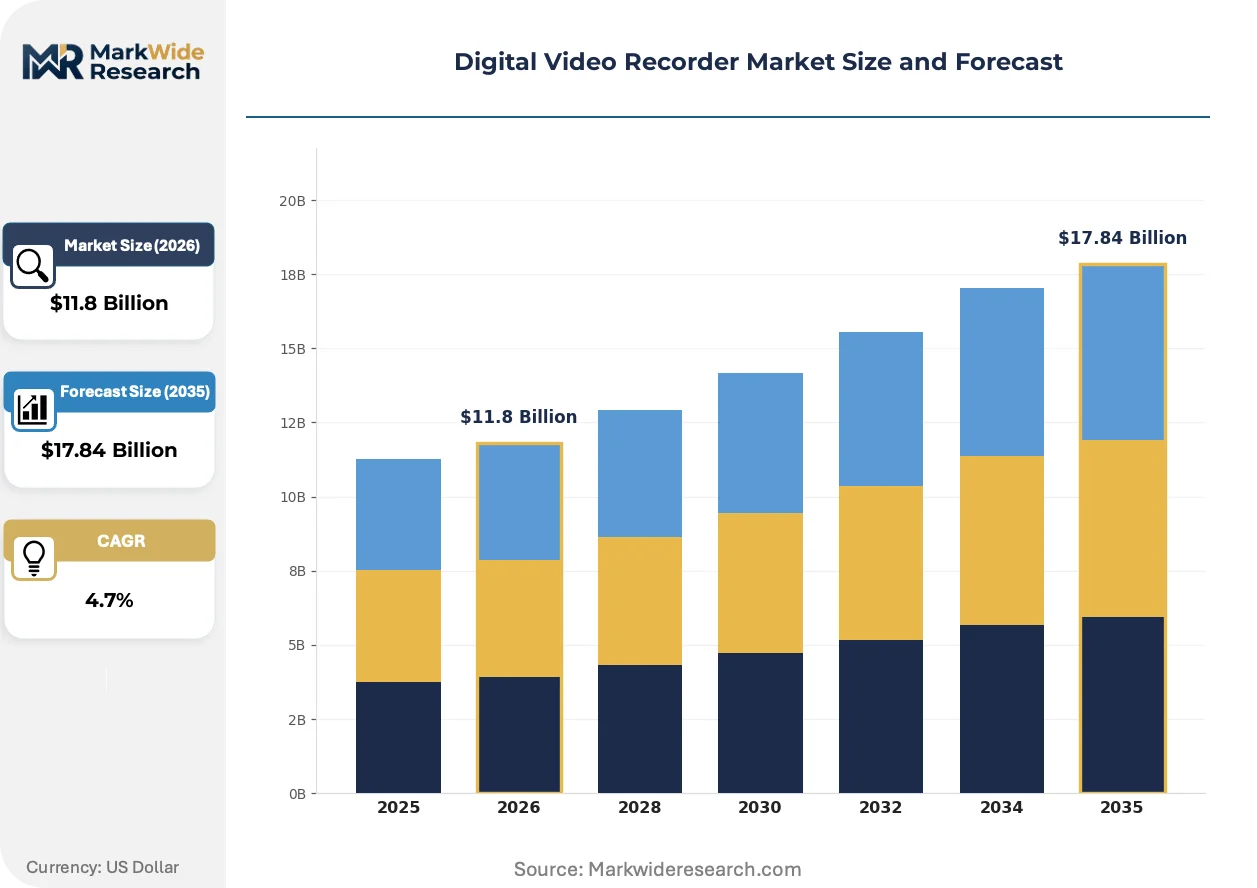
Cloud DVR architectures are compressing deployment timelines for commercial security integrators while FCC encryption mandates force firmware revalidation cycles across North American product lines.
Growth Catalysts
- Commercial property security mandates:Retail and logistics operators in the United States are upgrading analog installations to network DVR systems to satisfy insurer risk assessment protocols.
- ETSI data retention standards:European commercial landlords must retain surveillance footage for specified periods, expanding networked storage deployments across office and industrial properties.
- H.265 codec adoption:Compression efficiency gains from HEVC pipelines are halving storage costs for 4K video streams in bandwidth-constrained emerging markets.
Market Restraints
- Hard disk supply concentration:HDD component sourcing clusters in Thailand and Malaysia expose DVR manufacturers to flood and geopolitical disruption risks.
- Legacy coaxial infrastructure:Existing RG-59 cabling in aged commercial buildings constrains network DVR retrofit economics for small-property owners.
- Subscription fatigue:Cloud storage recurring fees are prompting budget-conscious buyers to defer upgrades or select hybrid local-cloud architectures.
Strategic Opportunities
- India smart city infrastructure:Municipal surveillance tenders in Mumbai and Delhi are specifying network DVR compliance for traffic management and public safety installations.
- AI-analytics convergence:Edge-computing DVR units combining video storage with real-time object detection are opening premium pricing tiers in banking and critical infrastructure.
- Brazilian logistics modernization:Warehouse operators across São Paulo state are deploying fleet-tracking-integrated DVR systems for cargo security and insurance verification.
Industry Challenges
- Cybersecurity certification timelines:Multi-jurisdiction firmware validation for FCC, ETSI, and MIIT compliance is extending product launch windows by six to nine months.
- Legacy system integration:Hybrid deployments bridging coaxial analog cameras with IP-based network DVRs require specialized middleware that fragments vendor support ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Video Recorder Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone DVR, DVD Recorder, Network DVR, Cloud DVR End User: Residential, Commercial, Educational, Healthcare Features: Time Shifting, Streaming, Multi-Channel, High Definition Connectivity: Wi-Fi, Ethernet, HDMI, USB |
| Companies Covered | Hangzhou Hikvision Digital Technology, Dahua Technology, TiVo Corporation, Sony Corporation, Samsung Electronics, LG Electronics, Panasonic Corporation, Cisco Systems, DISH Network Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Video Recorder Market Emerging Trajectories
Video compression, connectivity protocols, and procurement models are simultaneously transforming how security infrastructure is specified, deployed, and monetized across commercial and consumer segments.
Edge-based AI inference engines embedded directly into network DVR hardware are supplanting centralized server architectures for real-time analytics. Large-format retail chains in the United States are deploying these units to reduce bandwidth consumption and cloud compute fees. The shift is compressing total cost of ownership curves for multi-site operators while elevating hardware margin pools for manufacturers with silicon design partnerships.
FCC Part 15 encryption mandates for wireless surveillance transmissions are forcing firmware architecture redesigns across Wi-Fi-enabled DVR product lines. Manufacturers must now submit pre-market certification documentation demonstrating AES-256 implementation for cloud-connected units. Consumer electronics vendors with limited regulatory affairs staffing are outsourcing compliance validation to third-party test laboratories, extending development cycles.
Security-as-a-service contracting is displacing capital expenditure procurement among mid-market commercial property managers. Managed service providers in Germany and France are bundling network DVR hardware, installation, and cloud storage into fixed monthly fees. The model concentrates buyer relationships with integrators rather than manufacturers, compressing brand loyalty and elevating price transparency pressures across standard-performance tiers.
Digital Video Recorder Market Segmentation
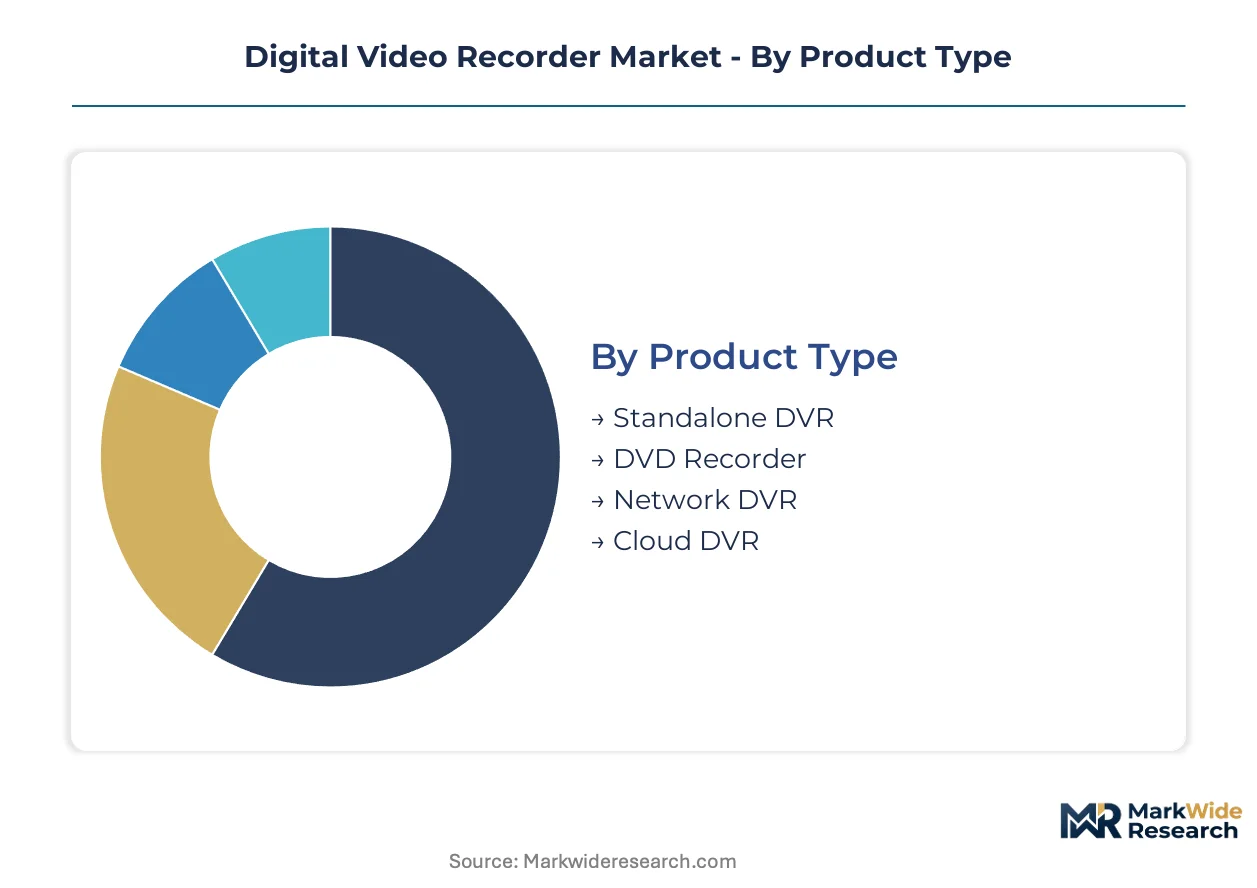
Segmentation in the digital video recorder market reveals how substitution pressures from cloud architectures and mobile streaming are fragmenting demand across hardware categories. Each dimension exposes divergent buyer priorities: commercial integrators prioritize network connectivity while residential users weigh upfront cost against recurring subscription burdens.
Product Type:
Network DVR and Cloud DVR segments face the most acute substitution threat as edge-computing cameras and software-defined surveillance platforms displace dedicated recording hardware.
- Network DVR:Ethernet-connected units process IP camera streams through H.264/H.265 codecs, storing footage on local NAS or edge servers. Retail chains in the United States are deploying these systems to satisfy insurer risk protocols while avoiding cloud latency. Network DVR anchors the volume base while Cloud DVR gains share at the steepest rate.
- Cloud DVR:Architectures stream encrypted video directly to remote data centers, eliminating on-premise storage hardware. Commercial property managers in Germany and France are adopting security-as-a-service bundles that embed Cloud DVR functionality, though bandwidth constraints in emerging markets slow penetration.
- Standalone DVR:Self-contained units with internal hard drives persist in cost-sensitive residential markets and legacy coaxial retrofits where network infrastructure is absent.
- DVD Recorder:Optical media-based recording has contracted to niche archival applications in legal and medical compliance scenarios where physical media custody is mandated.
Network DVR commands the largest installed base while Cloud DVR climbs the fastest as managed service providers consolidate buyer relationships.
End User:
Commercial deployments generate the highest per-unit revenue and drive feature roadmaps, while residential demand splinters between cord-cutting streaming services and time-shifting traditionalists.
- Commercial:Property managers, logistics operators, and retail chains specify network DVR systems with AI-analytics integration and multi-site central management. FCC encryption mandates and ETSI data retention standards shape procurement checklists across North American and European deployments.
- Residential:Consumer demand concentrates in time-shifting applications and whole-home DVR services, though subscription fatigue is prompting defections to ad-supported streaming platforms.
- Educational:Campus security administrators in India are specifying network DVR compliance for smart city infrastructure tenders in Mumbai and Delhi.
- Healthcare:Hospital facilities require HIPAA-aligned encryption and extended retention periods for liability protection, favoring hardened network DVR architectures with audit logging.
Commercial installations dominate revenue contribution while Healthcare shows the steepest specification upgrade trajectory.
Features:
Feature differentiation increasingly concentrates in analytics-enabled capabilities that transform raw storage into actionable security intelligence.
- Time Shifting:Pause-and-rewind live television functionality persists in consumer cable and satellite bundles despite cord-cutting headwinds.
- Streaming:Remote mobile access to live and recorded footage has become table stakes for commercial DVR specifications.
- Multi-Channel:Simultaneous recording from 16 to 64 camera inputs anchors enterprise security deployments in banking and critical infrastructure.
- High Definition:4K resolution pipelines are displacing 1080p in new installations as H.265 codec adoption halves storage cost per pixel.
Multi-Channel configurations anchor the commercial volume base while AI-enhanced analytics (often bundled with High Definition tiers) gains share fastest.
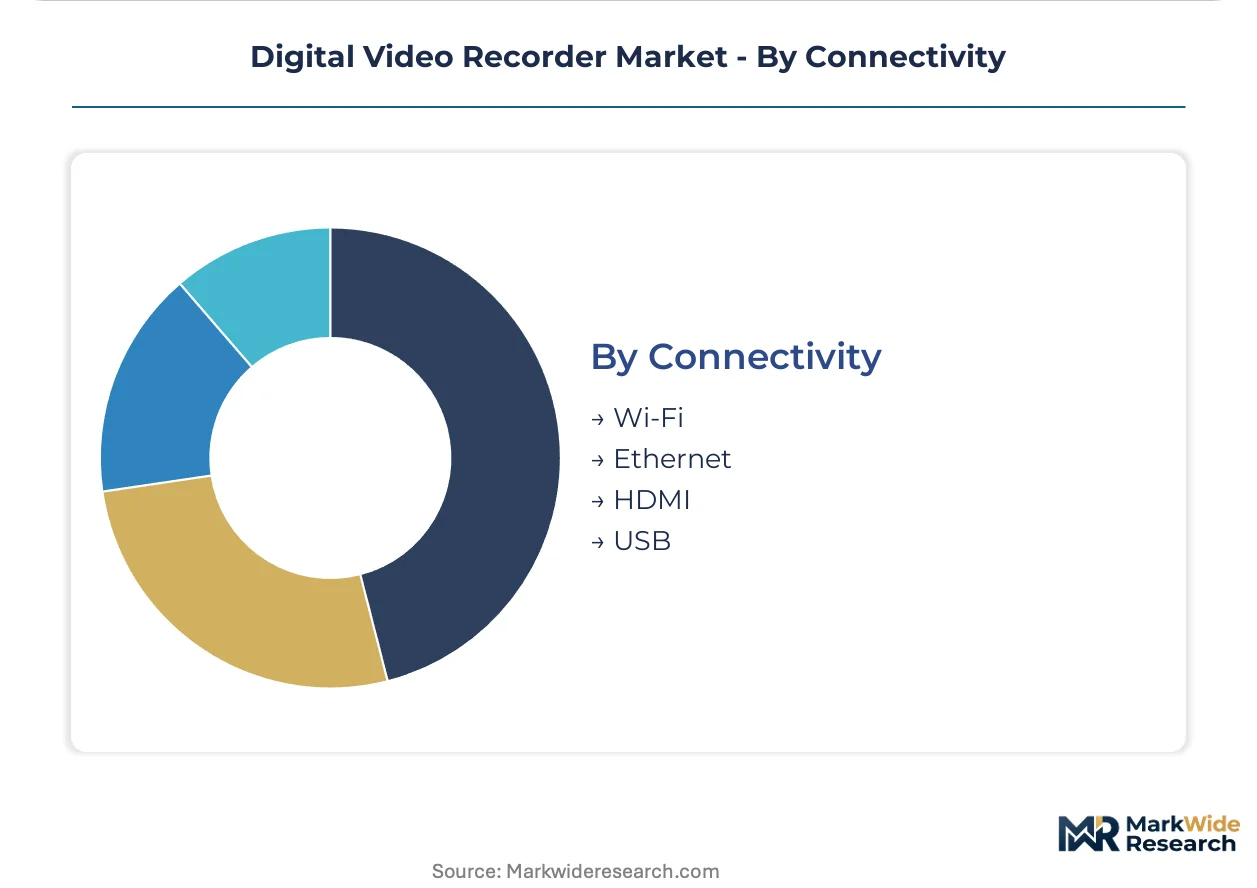
Connectivity:
Physical interface selection determines retrofit economics and cybersecurity exposure across deployment scenarios.
- Ethernet:Wired connectivity dominates commercial installations for bandwidth reliability and FCC Part 15 encryption compliance in Wi-Fi-constrained environments.
- Wi-Fi:Wireless architectures accelerate residential and small-business deployments, though firmware revalidation cycles for AES-256 mandates extend product launch windows.
- HDMI:Direct display output persists for local monitoring stations in retail and educational settings.
- USB:Peripheral connectivity supports local backup, firmware updates, and emergency export in bandwidth-failure scenarios.
Ethernet anchors the reliability-critical volume base while Wi-Fi expands fastest in cost-optimized residential and small-commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers ship network DVR hardware to commercial security integrators across Germany, the United States, and India, with FCC and ETSI certification requirements determining market access timelines in each destination.
United States
Retail chains and logistics operators upgrade analog installations to satisfy insurer risk protocols. FCC Part 15 mandates AES-256 encryption for Wi-Fi-enabled units, extending firmware revalidation cycles. Dallas-Fort Worth anchors commercial security deployment clusters where property managers specify multi-site central management capabilities.
Germany
Commercial landlords deploy networked storage to meet ETSI data retention standards for surveillance footage. Managed service providers bundle hardware and cloud storage into fixed monthly fees, compressing brand loyalty. The Ruhr industrial corridor concentrates security-as-a-service contracting among mid-market property managers.
China
Domestic manufacturing clusters supply integrated camera-recorder bundles across Asia-Pacific commercial deployments. MIIT network security rules and GB standards govern product certification for domestic sales. Hangzhou anchors enterprise security production where AI-enhanced analytics engines embed directly into network DVR hardware.
India
Municipal surveillance tenders in Mumbai and Delhi specify network DVR compliance for traffic management and public safety. Smart city infrastructure programs accelerate procurement timelines for campus security administrators. Karnataka's technology corridor hosts system integrators bridging legacy coaxial infrastructure with IP-based installations.
Brazil
Warehouse operators across São Paulo state deploy fleet-tracking-integrated DVR systems for cargo security and insurance verification. Bandwidth constraints slow cloud DVR penetration, preserving demand for standalone units with internal storage. The Santos logistics hub concentrates retrofit demand among port operators modernizing analog surveillance infrastructure.
Digital Video Recorder Market Vendor Landscape
Player mix skews toward integrated security conglomerates with silicon design partnerships and consumer electronics vendors with legacy brand recognition. Tiered concentration separates enterprise-focused network DVR specialists from residential time-shifting incumbents. Strategic archetypes include integrated camera-recorder bundlers, AI-analytics engine developers, and managed service enablers. Dominant competitive moves span firmware architecture redesigns for multi-jurisdiction compliance and edge-computing silicon partnerships for real-time analytics integration.
Within the integrated security tier, Hangzhou Hikvision Digital Technology and Dahua Technology occupy positions exemplifying Chinese manufacturing scale and domestic standard compliance. TiVo Corporation represents the consumer time-shifting archetype, sustaining brand recognition despite cord-cutting headwinds. These three entities collectively illustrate how geographic origin and historical positioning determine competitive strategy within diverging commercial and residential demand segments.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology |
| Dahua Technology |
| TiVo Corporation |
| Sony Corporation |
| Samsung Electronics |
| LG Electronics |
| Panasonic Corporation |
| Cisco Systems |
| DISH Network Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day component lead times for H.265 codec chipsets concentrate pricing power with Taiwanese foundry partners and compress margins for second-tier DVR assemblers. This inventory tightness intersects with FCC encryption mandate compliance costs to stratify hardware tiers.
Pricing Analysis
Three-generation pricing spreads separate H.265-enabled network DVR units from legacy H.264 inventories and emerging AI-analytics premium tiers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier standalone units intensifies because Thai HDD supply concentration limits component sourcing flexibility. Residential subscribers exhibit highest price sensitivity while healthcare facilities with HIPAA mandates show lowest.
Supply Chain Analysis
Port congestion on the Shanghai–Los Angeles trade lane elevates inbound logistics costs for Chinese-manufactured network DVR hardware. Manufacturing gravity centers on China, Thailand, and Malaysia. Production draws from hard disk drives, H.265 SoC processors, and AES-256 encryption modules. Single-source vulnerability in HDD component sourcing exposes assemblers to flood disruption risks. Distribution runs through commercial security integrators and managed service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware architecture expertise for multi-jurisdiction compliance represents the scarcest capability in this market, separating viable competitors from marginal players. The gap widens as FCC, ETSI, and MIIT validation timelines extend product launch windows.
For Market Incumbents: Consolidate silicon design partnerships to secure H.265 codec allocation priority and compress procurement lead times. Deepen backward integration into edge-computing AI modules to defend margin pools against software-defined surveillance substitutes. Channel control through exclusive managed service provider agreements protects brand position against security-as-a-service bundlers. For New Entrants and Emerging Players: Lead with hybrid local-cloud architectures targeting Brazilian warehouse operators and Indian municipal surveillance tenders where bandwidth constraints slow pure cloud DVR penetration. Brazil's Santos logistics hub and India's smart city infrastructure programs represent the most penetrable geographies. Go-to-market through fleet-tracking system integrators bypasses incumbent channel lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-analytics-enabled network DVR sub-segments as edge-computing silicon requirements escalate. Long-term viability favors manufacturers with captive firmware development capabilities and multi-jurisdiction certification track records. Acquisition targets should demonstrate MIIT compliance documentation and Hangzhou or Shenzhen engineering presence. The signal to watch is FCC pre-market approval queue length as inflection indicator for competitive positioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Architecture Redesign | AES-256 compliance for FCC Part 15 mandates revalidates Wi-Fi-enabled product lines. |
| Edge-Computing Silicon Partnership | Real-time object detection integration elevates hardware margins in banking deployments. |
| Security-as-a-Service Bundling | German and French managed service providers consolidate buyer relationships through fixed monthly fees. |
| Multi-Jurisdiction Certification Investment | Parallel FCC, ETSI, and MIIT validation extends launch windows but secures market access. |
| Hybrid Local-Cloud Architecture Launch | Brazilian and Indian bandwidth constraints preserve demand for standalone storage tiers. |
Methodological Framework
Cross-validation between commercial security integrator interviews and FCC certification database analysis anchors the qualitative findings. Primary fieldwork engaged DVR product managers, regulatory affairs specialists at surveillance hardware vendors, property management procurement directors, and managed service provider operations heads. Secondary validation drew from FCC Equipment Authorization Database entries, ETSI standards documentation, MIIT network security filings, and customs trade records. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Sensitivity analysis across codec adoption curves, encryption mandate implementation timelines, and cloud storage pricing elasticity shapes the analytical framework. Segmentation dimensions span product architecture, end-use vertical, feature tier, and connectivity protocol across the projection horizon. CAGRs derive from logistic diffusion modeling of H.265 replacement cycles and cloud DVR penetration rates. Forecast inputs include HDD supply lead times and smart city infrastructure procurement schedules.
Forecasts assume regulatory continuity in FCC Part 15 encryption mandates, ETSI data retention standards, and MIIT network security rules; material policy shifts would require re-modeling. Supply disruption scenarios and cybersecurity labeling requirement accelerations represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market