
 Video Decoder Market | 2026-2036
Video Decoder Market Size, Share, and Industry Trends Forecast 2026-2036
Video Decoder Market Analytics
The capability gap between fabless designers and integrated foundry operators is rotating competitive capital allocation across the video decoder landscape. Texas Instruments leverages its analog-digital integration to sustain margins in broadcast infrastructure. Analog Devices anchors its position through high-speed signal conditioning paired with decoder silicon. Broadcom dominates set-top box and cable gateway sockets where it controls reference design channels.
A video decoder converts compressed digital video streams into uncompressed frames through algorithms executed on dedicated silicon or programmable logic, with modern implementations processing HEVC streams at 120 frames per second for 8K resolution. The device serves broadcast receivers, security cameras, and streaming endpoints by reconstructing viewable imagery from bandwidth-efficient bitstreams. Hardware decoders occupy the highest volume tier in automotive infotainment and gaming consoles where thermal constraints rule out software alternatives. Cloud-based decoders are expanding fastest among telecommunication providers operating edge nodes for live streaming. The AV1 technology segment is gaining structural share as royalty-free positioning attracts media content producers seeking to escape HEVC patent pools.
The FCC in the United States mandates ATSC 3.0 broadcast standards that require next-generation decoder capabilities in consumer electronics. The EU AI Act and GDPR frameworks in Europe impose transparency and data governance requirements on video surveillance decoders processing biometric footage. China's MIIT enforces GB standards for domestic streaming hardware that shape export compatibility for foreign suppliers. Stakeholders must monitor codec standardization battles between AV1 and VVC to anticipate which technology investments will lock in decoder architecture decisions across the coming product cycles.
Market Dynamics
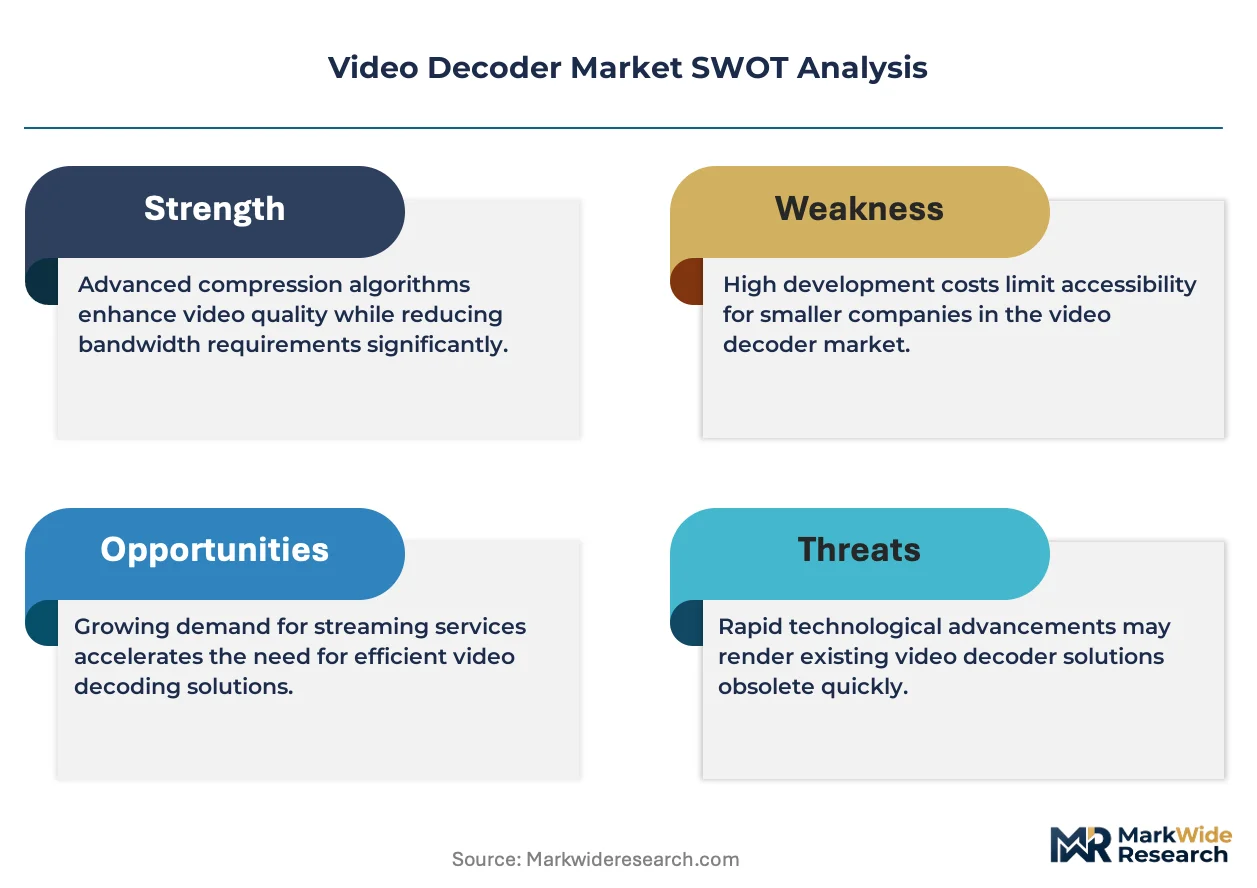
The AV1 codec mandate under the EU Green Deal is forcing hardware architecture decisions across broadcast, streaming, and surveillance equipment, compressing design cycles for decoder silicon vendors.
Growth Catalysts
- ATSC 3.0 mandate:The FCC requires next-generation decoder capabilities in US consumer electronics, pulling hardware refreshes across cable gateways and set-top boxes.
- Smart city surveillance buildouts:China, Germany, and the United States are deploying 8K-capable security networks requiring high-throughput decoder silicon at edge nodes.
- HEVC patent pool escape:Royalty-free AV1 positioning attracts media content producers seeking to reduce streaming infrastructure licensing burdens.
Market Restraints
- Foundry capacity concentration:Taiwan-based advanced node production creates supply vulnerability for fabless decoder designers targeting 4nm implementations.
- Codec standardization friction:Parallel AV1 and VVC development paths force dual-architecture investments, inflating R&D burn rates.
- Thermal constraints in automotive:Automotive infotainment systems limit decoder power envelopes, ruling out software-only solutions and compressing gross margins.
Strategic Opportunities
- Edge streaming nodes:Telecommunication providers in the United States and Germany are deploying cloud-based decoders for live streaming, creating white space in edge compute infrastructure.
- EU AI Act compliance:Transparency requirements for biometric footage processing create demand for decoder-integrated audit logging in European surveillance networks.
- 8K broadcast infrastructure:North American sports networks and European public broadcasters are upgrading transmission chains, requiring 120fps HEVC decoder refreshes.
Industry Challenges
- Codec firmware integration:Decoder vendors must maintain simultaneous AV1, HEVC, and legacy H.264 pipelines, complicating validation cycles and field upgrade logistics.
- Signal conditioning talent scarcity:High-speed analog-digital interface design expertise concentrates at Analog Devices and Texas Instruments, constraining competitor hiring pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Decoder Market |
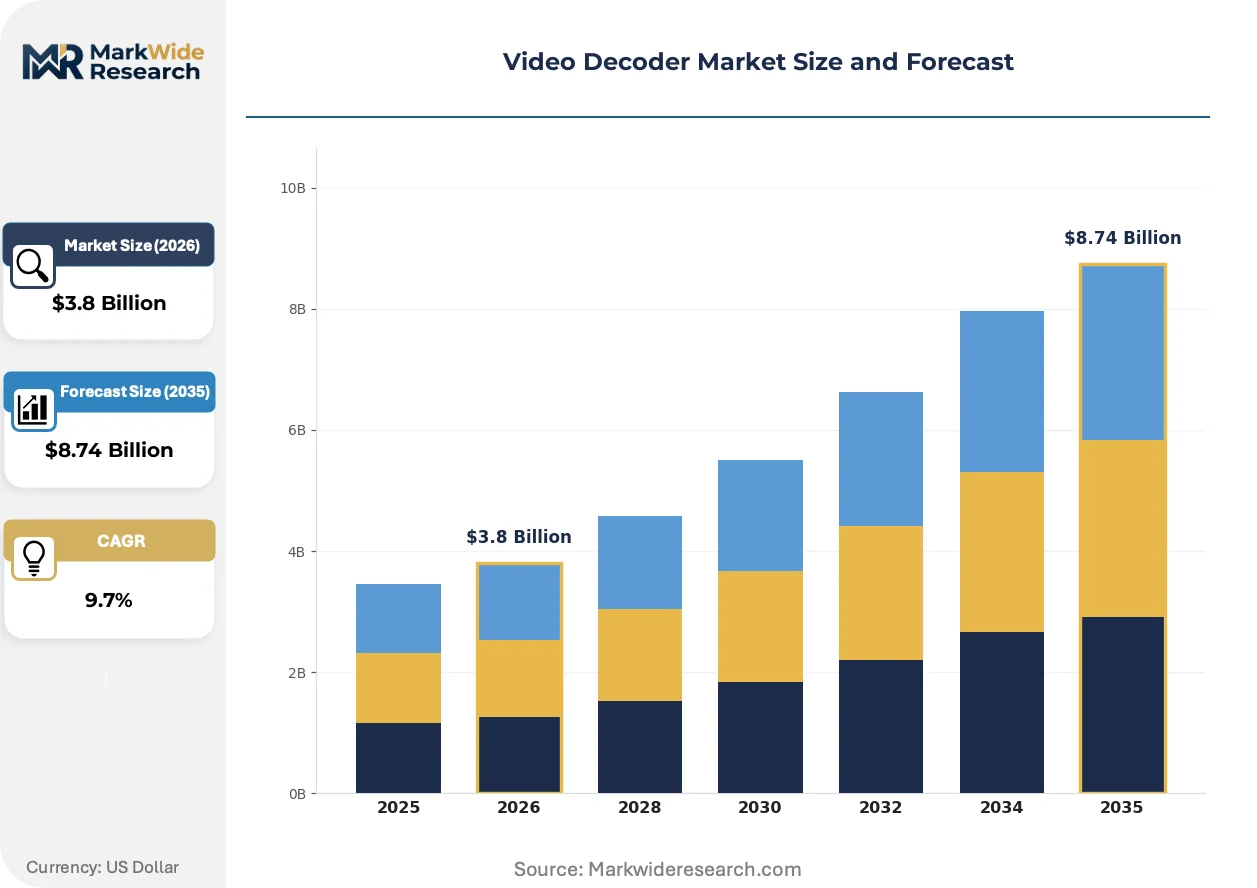
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Decoder, Hardware Decoder, Hybrid Decoder, Cloud-Based Decoder, Embedded Decoder Technology: H.264, HEVC, VP9, AV1, MPEG-2, MPEG-4 Application: Broadcasting Systems, Video Surveillance, Streaming Services, Video Conferencing, Automotive Infotainment, Gaming Consoles End User: Telecommunication Providers, Media Content Producers, Security Agencies, Consumer Electronics Manufacturers, Enterprise IT Firms |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., Broadcom Inc., Ambarella, Inc., NVIDIA Corporation, Intel Corporation, MediaTek Inc., Realtek Semiconductor Corp., Qualcomm Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Decoder Market Evolving Landscape
Codec architecture is fragmenting across royalty-free and patent-encumbered paths, while thermal and efficiency mandates reshape hardware-software partitioning decisions.
AV1 hardware acceleration is fragmenting decoder implementation strategies across fabless silicon vendors. The royalty-free codec reduces streaming infrastructure costs for media platforms operating at scale. Set-top box manufacturers and smart TV OEMs are prioritizing AV1 silicon over VVC alternatives to avoid patent pool exposure, compressing HEVC's remaining dominance window.
EU AI Act transparency requirements are mandating audit trails for biometric video processing in surveillance equipment. Decoder vendors must integrate logging firmware that flags algorithmic decision points in real-time streams. Security camera OEMs serving European smart city contracts are redesigning system-on-chip architectures to embed compliance features, extending product development timelines by 9-14 months.
Telecommunication providers are unbundling decoder procurement from legacy set-top box supply agreements. Edge streaming infrastructure operators now source decoder silicon directly from fabless vendors, bypassing traditional cable gateway OEM channels. This pattern is most visible in Germany and the United States, where live sports streaming investments are pulling hardware decisions away from incumbent cable operators toward cloud-native video platforms.
Video Decoder Market Segmentation
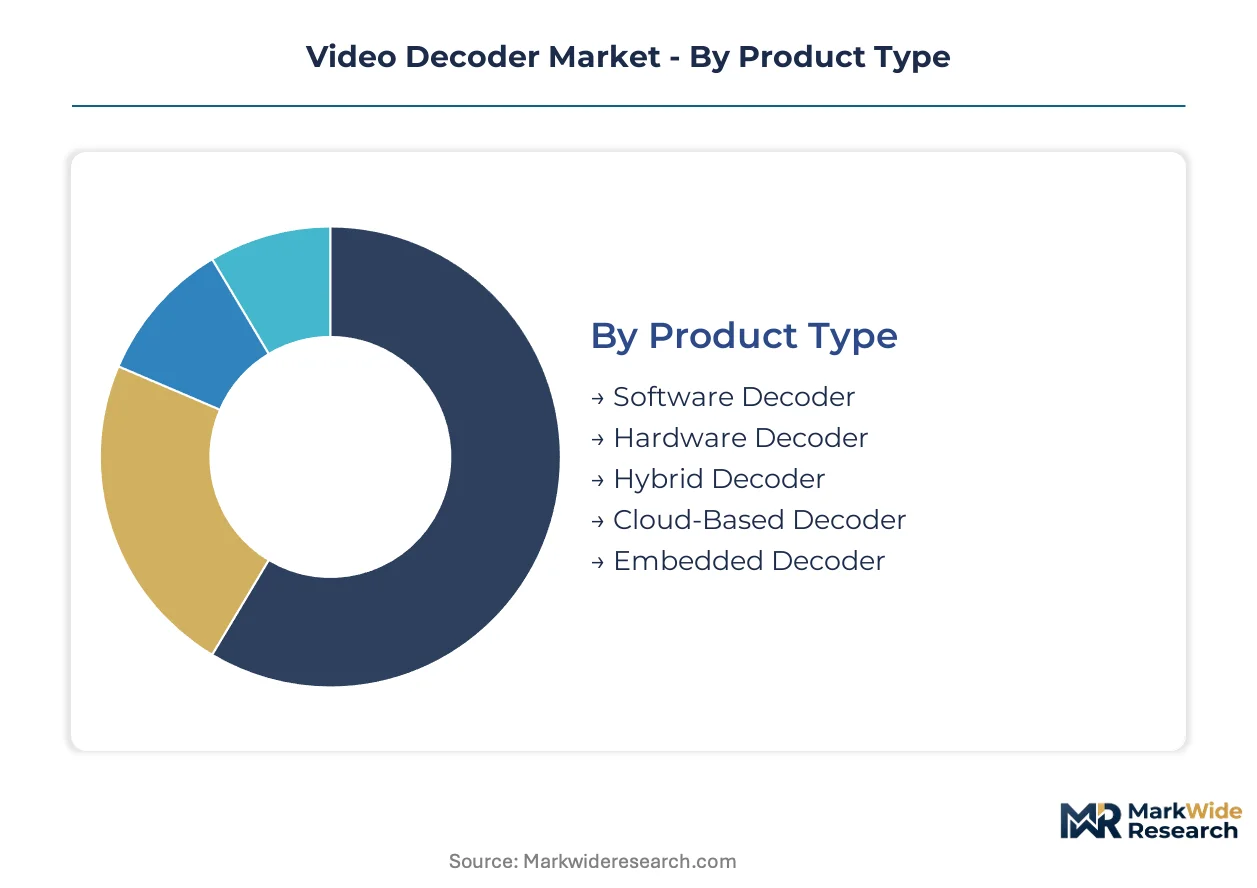
Video decoder segmentation reflects divergent thermal, latency, and licensing constraints across broadcast infrastructure, edge surveillance, and consumer streaming endpoints. Architecture choices between dedicated silicon, programmable logic, and cloud-native instances determine cost structures and regulatory compliance pathways for equipment vendors.
Product Type:
FCC ATSC 3.0 mandates and EU Green Deal efficiency standards are fragmenting hardware-software partitioning decisions across decoder implementations.
- Hardware Decoder:Dedicated silicon architectures process HEVC streams at 120fps for 8K resolution in automotive infotainment and gaming consoles where thermal envelopes rule out software alternatives. Demand concentrates in China, the United States, and Germany as data center buildouts and smart city surveillance networks accelerate 4nm decoder deployments.
- Cloud-Based Decoder:Virtualized decoder instances running on edge compute nodes enable live streaming scalability without dedicated premises equipment. Telecommunication providers in the United States and Germany are unbundling procurement from legacy set-top box agreements, pulling hardware decisions toward cloud-native video platforms.
- Software Decoder:CPU- and GPU-based implementations serve low-latency video conferencing and enterprise IT workloads where flexibility outweighs power efficiency requirements.
- Hybrid Decoder:Partitioned architectures split processing between fixed-function blocks and programmable cores for mid-tier streaming devices balancing cost and performance.
- Embedded Decoder:System-on-chip integrations target security camera OEMs serving European smart city contracts requiring EU AI Act-compliant audit logging firmware.
Established volume favors Hardware Decoder; emerging adoption favors Cloud-Based Decoder.
Technology:
Codec selection determines patent exposure, bandwidth efficiency, and hardware refresh cycles across decoder silicon roadmaps.
- AV1:Royalty-free positioning attracts media content producers seeking to escape HEVC patent pools, compressing design cycles for decoder vendors under EU Green Deal mandates. Set-top box manufacturers and smart TV OEMs are prioritizing AV1 silicon over VVC alternatives to avoid licensing exposure.
- HEVC:Mature ecosystem and broadcast infrastructure lock-in sustain demand for 4K/8K streaming and ATSC 3.0 cable gateways despite accumulating patent royalties.
- H.264:Legacy compatibility requirements preserve installed base in video surveillance and enterprise conferencing systems with minimal hardware upgrade pressure.
- VP9:Google-backed codec maintains presence in browser-based streaming and Android ecosystem devices without full AV1 hardware acceleration.
- MPEG-2:Broadcast transmission chains in mature markets continue legacy support for satellite and terrestrial distribution infrastructure.
- MPEG-4:Declining deployment in consumer electronics gives way to HEVC and AV1 transitions in new product introductions.
Patent-encumbered HEVC retains infrastructure dominance; royalty-free AV1 gains share fastest among streaming-native deployments.
Application:
End-use thermal constraints and real-time requirements dictate hardware-software partitioning across decoder procurement decisions.
- Streaming Services:North American and European platforms are expanding decoder deployments to support 4K and 8K content delivery, with edge node processing requirements pulling cloud-based decoder demand.
- Video Surveillance:8K-capable security networks in China, Germany, and the United States require high-throughput decoder silicon at edge nodes with EU AI Act transparency mandates for biometric footage processing.
- Broadcasting Systems:FCC ATSC 3.0 standards mandate next-generation decoder capabilities in US consumer electronics, pulling hardware refreshes across cable gateways and set-top boxes.
- Automotive Infotainment:Thermal constraints limit decoder power envelopes, ruling out software-only solutions and compressing gross margins for dedicated silicon vendors.
- Gaming Consoles:Fixed thermal budgets and low-latency requirements sustain hardware decoder integration in premium consumer electronics.
- Video Conferencing:Enterprise IT firms prioritize software flexibility over dedicated silicon for multi-codec interoperability in hybrid work environments.
Surveillance and broadcasting anchor hardware volume; streaming services drive cloud-based decoder expansion.
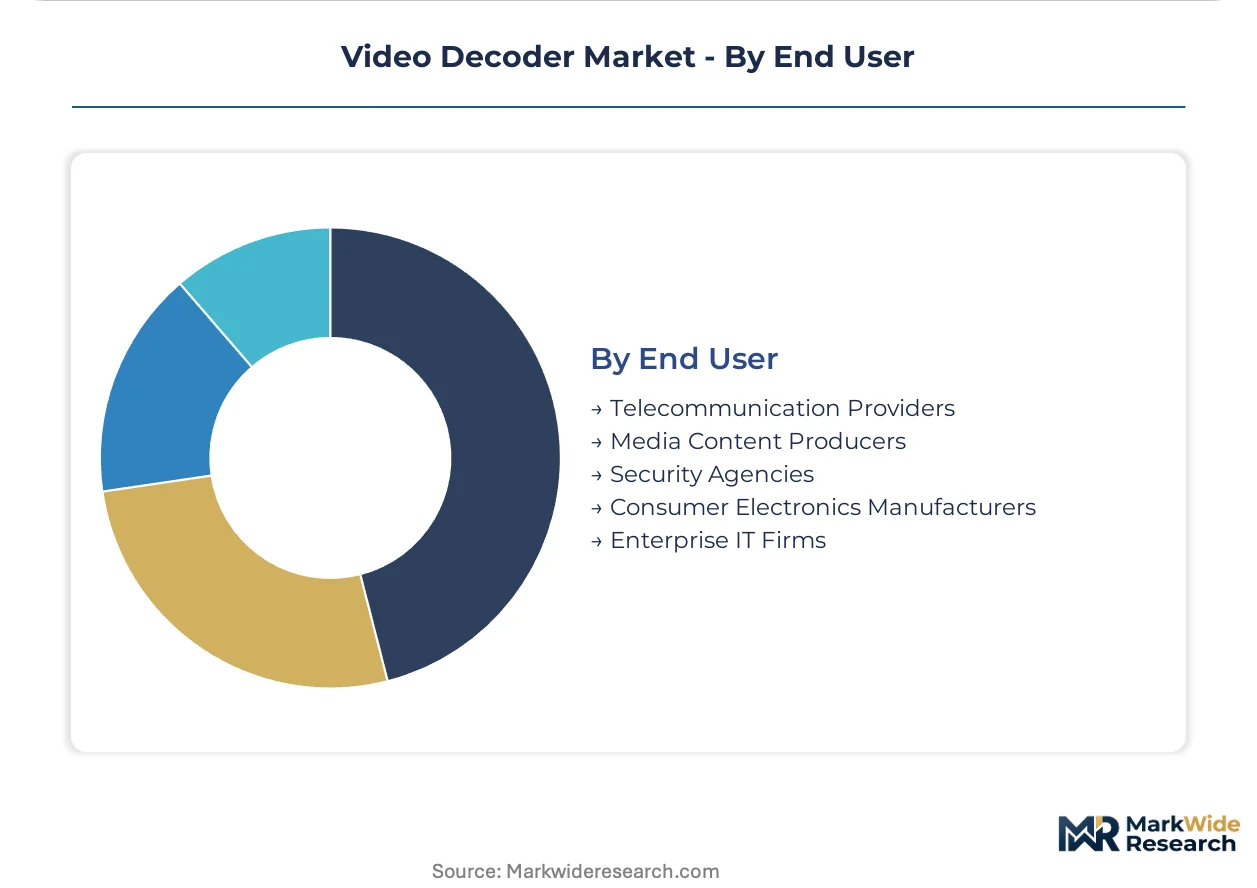
End User:
Procurement authority shifts between integrated OEMs and direct silicon sourcing reshape decoder vendor channel strategies.
- Telecommunication Providers:Edge streaming infrastructure operators in Germany and the United States now source decoder silicon directly from fabless vendors, bypassing traditional cable gateway OEM channels for live sports streaming investments.
- Media Content Producers:Royalty-free AV1 positioning reduces streaming infrastructure licensing burdens for platforms operating at scale, influencing codec standardization battles.
- Security Agencies:Smart city surveillance buildouts in China, Germany, and the United States deploy 8K-capable networks requiring high-throughput decoder silicon with audit logging compliance.
- Consumer Electronics Manufacturers:Set-top box and smart TV OEMs prioritize AV1 silicon to avoid patent pool exposure, compressing HEVC's remaining dominance window.
- Enterprise IT Firms:Video conferencing and internal streaming deployments favor software decoder flexibility for rapid codec transitions without hardware refresh cycles.
Traditional OEM procurement favors Consumer Electronics Manufacturers; disintermediation trends favor Telecommunication Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing leverage for AV1-compliant decoder silicon while China captures volume premiums through data center buildouts. This asymmetry reflects divergent regulatory pressures and procurement authority structures across major demand centers.
United States
Telecommunication providers in Dallas and Atlanta are unbundling decoder procurement from legacy cable gateway agreements for live sports streaming infrastructure. The FCC mandates ATSC 3.0 broadcast standards requiring next-generation decoder capabilities in consumer electronics. Silicon Valley clusters anchor cloud-based decoder development for edge compute nodes.
China
MIIT enforces GB standards for domestic streaming hardware that shape export compatibility requirements for foreign suppliers. Shenzhen and Beijing concentrate smart city surveillance network deployments requiring 8K-capable decoder silicon at massive scale. Yangtze River Delta manufacturing clusters supply automotive infotainment systems with thermal-constrained decoder implementations.
Germany
Bavaria-based automotive OEMs limit decoder power envelopes in infotainment systems, compressing margins for dedicated silicon vendors. The EU Green Deal AV1 codec mandate forces hardware architecture decisions across broadcast equipment manufacturers. Munich and Stuttgart anchor 8K broadcast infrastructure upgrades for sports networks and public broadcasters.
Japan
METI industrial policy supports domestic semiconductor ecosystem development for broadcast and surveillance decoder applications. Tokyo and Osaka metropolitan areas concentrate gaming console manufacturing sustaining hardware decoder integration. Kansai region clusters specialize in high-speed signal conditioning for broadcast infrastructure equipment.
South Korea
Seoul Capital Area telecommunication providers deploy edge streaming nodes requiring cloud-based decoder scalability. MFDS regulatory frameworks intersect with broadcast equipment standards for medical imaging decoder applications. Busan-Ulsan industrial corridors supply consumer electronics manufacturers prioritizing AV1 silicon over patent-encumbered alternatives.
Video Decoder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the video decoder landscape. Fabless designers specializing in programmable logic and dedicated silicon architectures compete against integrated foundry operators with captive analog-digital integration capabilities. Two strategic archetypes dominate: broadcast infrastructure specialists leveraging reference design control, and automotive-surveillance hybrid players optimizing for thermal constraints. Competitive moves concentrate on strategic partnerships for codec firmware integration and geographic expansion into EU AI Act compliance markets.
Within the analog-digital integration tier, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions where high-speed signal conditioning expertise constrains competitor hiring pipelines. Broadcom Inc. anchors the set-top box and cable gateway segment through reference design channel control. These three companies exemplify how decoder vendor strategies diverge between margin defense in mature broadcast infrastructure and volume capture in cloud-native streaming deployments.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Broadcom Inc. |
| Ambarella, Inc. |
| NVIDIA Corporation |
| Intel Corporation |
| MediaTek Inc. |
| Realtek Semiconductor Corp. |
| Qualcomm Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
FCC ATSC 3.0 certification requirements gate both supplier qualification and price differentiation simultaneously, forcing decoder vendors to absorb compliance testing costs while tiering offerings around broadcast versus streaming performance envelopes. This regulatory threshold compresses margins for uncertified entrants while enabling premium positioning for verified silicon architectures.
Pricing Analysis
Configured-to-order decoder silicon commands spreads versus standard catalog parts, with customization premiums reflecting codec firmware integration complexity and thermal envelope specifications. Pricing stratifies across premium, standard, and economy tiers based on resolution throughput and automotive qualification grade. Cost compression in mid-tier streaming hardware intensifies as telecommunication providers consolidate procurement volumes for edge node deployments. Consumer electronics manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize thermal reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs through Taiwan Strait shipping lanes constrain just-in-time delivery windows for advanced node decoder silicon. Taiwan, South Korea, and the United States anchor wafer fabrication capacity, drawing from EUV lithography equipment and specialty substrate materials. Single-source vulnerability concentrates at TSMC's leading-edge foundry nodes. Distribution runs through fabless vendor-direct channels to telecommunication providers and traditional OEM procurement networks to consumer electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among telecommunication providers unbundling decoder procurement from legacy cable gateway agreements, fragmenting incumbent channel control while creating direct-sourcing leverage for volume purchasers.
For Market Incumbents: Fortify reference design control in set-top box and cable gateway sockets against cloud-native streaming platform disintermediation. Deepen backward integration into high-speed signal conditioning IP to constrain competitor hiring pipelines. Prioritize R&D investment in EU AI Act-compliant audit logging firmware for European surveillance contracts. For New Entrants and Emerging Players: Anchor in edge streaming infrastructure white space created by telecommunication provider procurement unbundling in Germany and the United States. Target cloud-based decoder virtualization for live sports streaming deployments. Pursue direct fabless vendor relationships bypassing traditional OEM channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive-surveillance hybrid players holding thermal-constrained decoder architectures. Five-to-ten year viability hinges on codec standardization battle outcomes between AV1 and VVC. Watch AV1 hardware acceleration adoption curves in smart TV OEM procurement decisions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Codec Firmware Integration Partnership | Dual-architecture AV1-HEVC pipelines reduce validation cycle risk for broadcast equipment vendors. |
| EU AI Act Compliance Certification | Audit logging capabilities unlock European smart city surveillance contract eligibility for security camera OEMs. |
| Edge Compute Node Deployment | Cloud-native decoder virtualization captures live sports streaming infrastructure spend from cable operators. |
| Automotive Thermal Architecture Investment | Low-power 4nm implementations secure infotainment socket wins with Bavaria-based OEMs. |
| Direct Telecommunication Provider Channel | Bypassing traditional OEM procurement captures unbundled decoder silicon sourcing in Dallas and Atlanta markets. |
Research Methodology
A standing panel of decoder silicon product managers, telecommunication provider procurement officers, broadcast equipment engineering directors, and automotive infotainment platform architects provided ongoing calibration. Primary interview findings triangulated against secondary sources including FCC equipment authorization databases, ETSI codec standardization filings, MIIT GB standard publications, and hyperscaler edge infrastructure capex disclosures. Bottom-up unit shipment estimates reconciled with top-down semiconductor foundry capacity allocations.
Consistency checks validated model outputs against external benchmarks across the projection horizon. Segmentation dimensions spanned hardware-software-cloud deployment models, resolution throughput tiers, application end-uses, and regional regulatory clusters. CAGRs derived from iterative regression against codec transition timelines and infrastructure refresh cycles. Industry-specific inputs incorporated ATSC 3.0 mandate compliance schedules and EU Green Deal efficiency implementation trajectories.
Underlying assumptions cover foundry node availability, codec standardization stability, and trade lane logistics continuity, with deviation risk concentrated in Taiwan Strait shipping disruptions and patent pool litigation outcomes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market