
 Smart Wiring Devices Market | 2026-2036
Smart Wiring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wiring Devices Market Analysis
Market Context
Asian contract manufacturers is consolidating capacity for smart switch and outlet assemblies serving North American and European OEM brands. Schneider Electric leverages its European distribution network to sustain specification-grade positioning across commercial building projects. Legrand Group anchors its portfolio through dedicated smart home subsidiaries focused on retrofit-friendly form factors. Siemens AG competes on industrial-grade connectivity modules that bridge building automation with enterprise energy platforms.
Technical Definition and Segment Structure
Smart wiring devices encompass electrically connected switches, outlets, plugs, and sensors that enable remote or automated control of power delivery, typically integrating wireless transceivers operating at 2.4 GHz with load-rated relay mechanisms and occupancy-detecting passive infrared elements. These devices serve the primary commercial purpose of reducing manual switching labor, enabling granular energy metering at the circuit level, and supporting centralized building management system integration. Smart switches carry the largest installed base among product types due to straightforward replacement of legacy wall controls, while smart sensors represent the fastest-expanding margin pool as they bundle environmental monitoring with occupancy logic. Wi-Fi technology dominates residential retrofit channels because it eliminates hub dependencies, whereas Zigbee sustains its position in new construction where mesh reliability and lower per-node power draw justify dedicated gateway infrastructure.
Regulatory Framework
The Federal Communications Commission governs radio emission profiles for Wi-Fi and Zigbee transceivers sold in the United States, while the EU Radio Equipment Directive mandates interoperability testing and cybersecurity baselines for connected devices entering European markets. Ecodesign requirements under the EU Green Deal progressively tighten standby power limits, pushing manufacturers toward relay architectures with sub-watt idle consumption. Stakeholders must monitor divergence between regional cybersecurity certification schemes as a determinant of which product variants achieve market access without costly redesign cycles.
Market Dynamics
The smart wiring devices market is undergoing a fundamental restructuring as building electrification mandates and native smart home protocol integration in new construction compress traditional retrofit timelines and reward specification-grade positioning.
Growth Catalysts
- EU Green Deal Ecodesign:Progressive standby power limits under the EU Green Deal are forcing relay architecture redesigns toward sub-watt idle consumption, opening specification-grade positioning for compliant manufacturers.
- Sun Belt residential construction:Texas, Florida, and Arizona builders are embedding Matter and Zigbee protocols natively during rough-in, eliminating retrofit friction and accelerating switch outlet penetration.
- Industrial energy platforms:Siemens AG and similar industrial automation vendors are bridging building automation with enterprise energy management systems, pulling smart wiring devices into facility-wide metering architectures.
Market Restraints
- Copper and rare earth price volatility:Relay mechanisms and wireless transceivers depend on copper windings and neodymium magnets, exposing margin structures to commodity swings from Chinese processing concentration.
- FCC and EU RED divergence:The Federal Communications Commission's emission profiles and the EU Radio Equipment Directive's cybersecurity baselines are diverging on interoperability testing, forcing costly dual-certification for cross-Atlantic vendors.
- Hub-dependent Zigbee substitution:Wi-Fi Direct and Thread protocols are eliminating gateway infrastructure requirements in residential retrofit, compressing Zigbee's addressable market to new construction niches.
Strategic Opportunities
- Retrofit-friendly form factors:Legrand Group's dedicated smart home subsidiaries demonstrate margin capture through backward-compatible designs that minimize electrician labor in Germany and France's aging housing stock.
- Environmental-occupancy sensor bundling:Passive infrared elements combined with air quality monitoring are opening commercial building automation contracts previously held by standalone sensor vendors.
- Mesh reliability in multi-dwelling units:Zigbee's lower per-node power draw and self-healing topology address density challenges in Singapore and South Korean apartment towers where Wi-Fi congestion degrades performance.
Industry Challenges
- Cybersecurity certification timeline compression:The EU Radio Equipment Directive's evolving baselines and state-level IoT security laws in California and Oregon are forcing firmware revision cycles that strain engineering bandwidth.
- Legacy electrical contractor skill gaps:Electricians trained on analog switching lack fluency in commissioning mesh networks and troubleshooting 2.4 GHz interference, creating installation quality variance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wiring Devices Market |
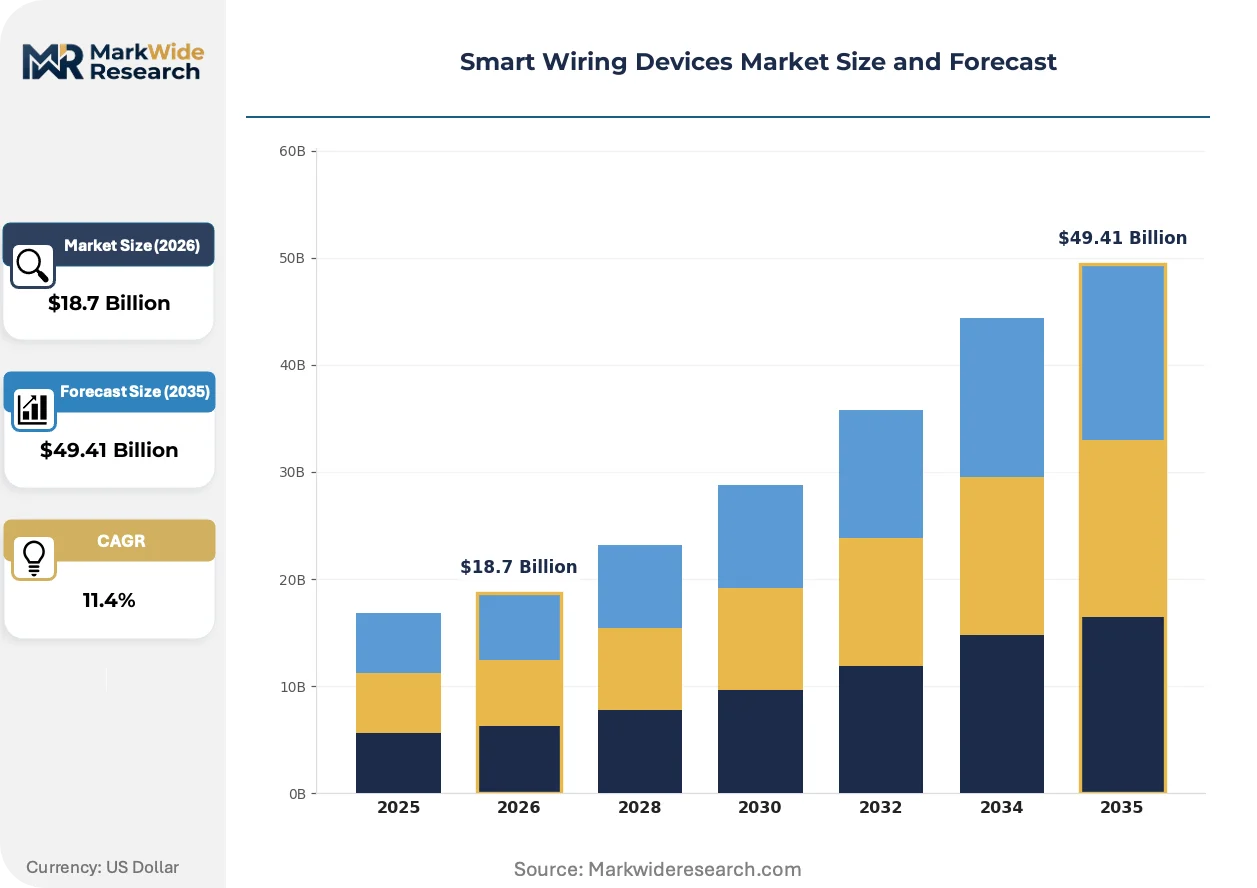
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Switches, Smart Outlets, Smart Plugs, Smart Sensors Technology: Zigbee, Z-Wave, Wi-Fi, Bluetooth End User: Residential, Commercial, Industrial, Hospitality Application: Lighting Control, Energy Management, Security Systems, Home Automation |
| Companies Covered | Honeywell International Inc., Legrand Group, Schneider Electric, Eaton Corporation, Crestron Electronics, Inc., Siemens AG, Lutron Electronics Co., Inc., Johnson Controls International plc, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wiring Devices Market Emerging Trajectories
Wireless protocol unification and edge computing migration are compressing hardware differentiation cycles while elevating software-defined functionality as the primary competitive battleground.
Matter protocol stacks are consolidating fragmented smart home ecosystems into a single application-layer standard. Residential builders in Arizona and Texas are specifying Matter-native devices during pre-wire to eliminate hub fragmentation. This convergence is consolidating vendor development roadmaps around unified SDKs and compressing SKU proliferation.
The EU Green Deal's Ecodesign requirements are tightening standby power limits for connected devices. Manufacturers are redesigning relay architectures toward latching mechanisms and energy-harvesting switches. Germany and France's national building efficiency codes are most affected, with specifiers now requiring sub-watt idle certification for commercial project eligibility.
Building management system procurement is rotating toward outcome-based energy reduction contracts rather than hardware capex. Facility managers in Singapore and Dubai are unbundling device supply from installation and commissioning services. This disintermediation is compressing distributor margins while elevating system integrator influence over specification authority.
Smart Wiring Devices Market Segmentation
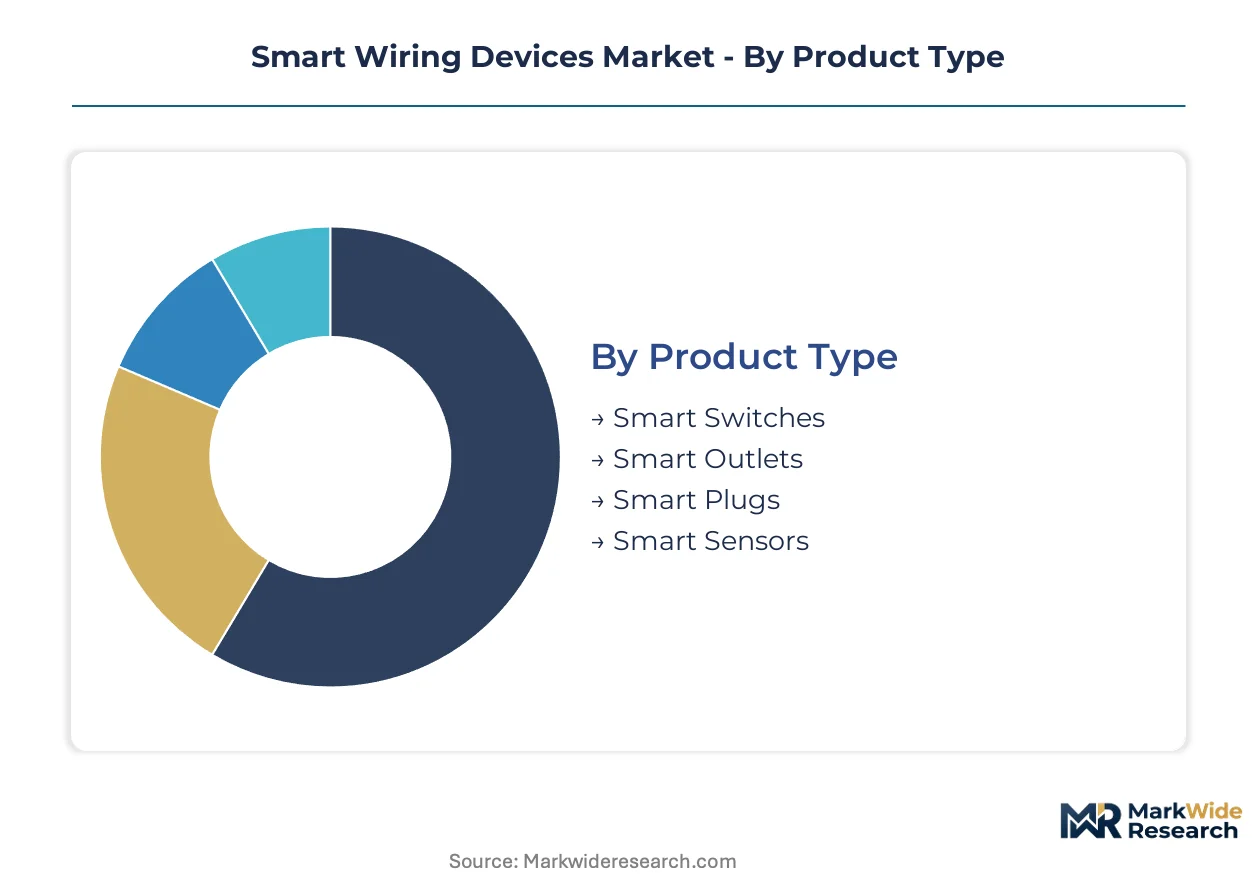
Smart wiring devices serve distinct upgrade cycles across residential retrofit, new construction, and commercial renovation channels. Segment boundaries determine which technical specifications, certification requirements, and distribution strategies unlock procurement decisions in each vertical.
Product Type:
Replacement cycles vary dramatically by product type, with wall-mounted devices demanding electrician labor while plug-in units enable consumer self-installation.
- Smart Switches:Wall-mounted relay mechanisms with 2.4 GHz transceivers that replace legacy toggle controls. Demand concentrates in Sun Belt states where Texas and Florida builders specify Matter-native units during rough-in to eliminate downstream retrofit friction.
- Smart Sensors:Passive infrared elements bundled with air quality or ambient light detection for occupancy-driven automation. Singapore and South Korean multi-dwelling unit developers specify these for mesh density where Wi-Fi congestion degrades performance.
- Smart Outlets:Receptacle replacements with integrated metering and remote switching capability. Legrand Group's retrofit-friendly designs capture margin in Germany and France's aging housing stock.
- Smart Plugs:Portable adapters adding connectivity to existing appliances without electrical work. Wi-Fi Direct protocols dominate this segment through elimination of hub dependencies.
Volume placements concentrate in Smart Switches; the faster expansion belongs to Smart Sensors.
Technology:
Protocol selection locks manufacturers into distinct certification pathways and power architecture requirements that reshape margin structures.
- Wi-Fi:Direct-to-router connectivity eliminating gateway infrastructure. Residential retrofit channels in the United States favor this technology for consumer self-installation simplicity.
- Zigbee:Mesh topology with sub-watt per-node power draw and self-healing reliability. New construction specifications in Arizona and Texas embed this natively during pre-wire.
- Z-Wave:Sub-GHz frequency mesh avoiding 2.4 GHz congestion. Security system integrators specify this for dedicated automation backbones in commercial hospitality deployments.
- Bluetooth:Low-energy beaconing for proximity-based control and commissioning. Industrial facility managers leverage this for temporary access credentialing without network infrastructure.
Wi-Fi commands the largest installed base; Zigbee sustains premium positioning in specification-grade new construction.
End User:
Customer type determines procurement authority, installation labor requirements, and integration depth with existing building management infrastructure.
- Residential:Single-family and multi-family dwellings with consumer or electrician installation. Sun Belt builders in Texas and Florida are embedding native protocols during construction to compress traditional retrofit timelines.
- Commercial:Office buildings, retail, and institutional facilities requiring BMS integration. Singapore facility managers are unbundling device supply from commissioning services under outcome-based energy reduction contracts.
- Industrial:Manufacturing and warehouse environments bridging automation with enterprise energy platforms. Siemens AG pulls smart wiring into facility-wide metering architectures.
- Hospitality:Hotels and serviced apartments prioritizing guest experience automation. Dubai developers specify environmental-occupancy sensor bundling for premium property differentiation.
Residential generates the highest unit volumes; Commercial yields the steepest expansion trajectory as BMS procurement rotates toward performance contracting.
Application:
Use case focus determines sensor fusion requirements, software platform integration, and regulatory compliance scope.
- Lighting Control:Occupancy-driven switching and dimming with daylight harvesting algorithms. Germany's national building efficiency codes mandate sub-watt idle certification for commercial project eligibility.
- Energy Management:Circuit-level metering and load scheduling for demand response. EU Green Deal Ecodesign requirements are forcing relay architecture redesigns toward latching mechanisms.
- Security Systems:Integration with access control and surveillance for automated responses. Z-Wave protocols dominate this segment for dedicated automation backbones.
- Home Automation:Unified control of multiple device categories through single interfaces. Matter protocol stacks are consolidating fragmented ecosystems into single application-layer standards.
Lighting Control retains the deepest installed base; Energy Management is climbing the fastest as electrification mandates tighten operational efficiency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper processing concentration in China anchors relay mechanism supply chains, while rare earth magnet sourcing from Chinese refiners shapes transceiver component availability. Finished device demand distributes across construction clusters in North America, Europe, and Asia-Pacific where building electrification mandates accelerate specification-grade procurement.
United States
Sun Belt residential construction in Texas, Florida, and Arizona embeds Matter and Zigbee protocols natively during rough-in. The FCC governs 2.4 GHz emission profiles for Wi-Fi and Zigbee transceivers. Dallas-Fort Worth metro builders specify smart switches and outlets during pre-wire to eliminate downstream retrofit friction.
Germany
Aging housing stock drives retrofit-friendly smart outlet demand through Legrand Group's backward-compatible designs. The EU Green Deal Ecodesign mandates sub-watt idle consumption for relay architectures. Berlin and Munich commercial projects now require standby power certification for eligibility under national building efficiency codes.
China
Asian contract manufacturers consolidate capacity for smart switch and outlet assemblies serving North American and European OEM brands. The MIIT oversees domestic radio equipment standards and dual carbon goals push industrial facility metering. Shenzhen and Dongguan clusters produce mesh network modules for export markets.
Singapore
Multi-dwelling unit developers specify Zigbee sensors for mesh density where Wi-Fi congestion degrades performance in high-rise towers. The country's building regulator enforces energy efficiency standards for commercial developments. Marina Bay and Orchard Road hospitality projects bundle environmental-occupancy sensors for premium automation differentiation.
France
Retrofit channel expansion targets aging residential electrical infrastructure through specification-grade smart switches. ANSM and national regulators align with EU Radio Equipment Directive cybersecurity baselines. Lyon and Marseille contractors procure backward-compatible devices minimizing electrician labor in historic building renovations.
Smart Wiring Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent connectivity platforms and energy-harvesting form factors. The vendor base stratifies across three tiers: diversified electrical conglomerates with distribution depth, dedicated smart home subsidiaries focused on retrofit channels, and industrial automation vendors bridging building management with enterprise platforms. Dominant competitive moves include strategic partnerships with residential builders for native protocol specification and geographic expansion through regional certification acquisition.
Among diversified electrical conglomerates, Schneider Electric and Legrand Group exemplify specification-grade positioning through European distribution networks and dedicated smart home subsidiaries respectively. Siemens AG occupies a position bridging industrial-grade connectivity modules with facility-wide energy management architectures. These three anchors represent distinct competitive archetypes: distribution-led specification capture, retrofit-focused margin extraction, and industrial-to-commercial platform extension.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Legrand Group |
| Schneider Electric |
| Eaton Corporation |
| Crestron Electronics, Inc. |
| Siemens AG |
| Lutron Electronics Co., Inc. |
| Johnson Controls International plc |
| ABB Ltd. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal Ecodesign mandates for sub-watt idle consumption are forcing relay architecture redesigns, compelling manufacturers to absorb latching mechanism costs or pass them through to specification-grade buyers in Germany and France.
Pricing Analysis
Warranty and commissioning service bundling separates premium-tier vendors from unbundled hardware suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales support depth. Cost compression in the economy tier is intensifying because Wi-Fi Direct modules eliminate gateway infrastructure and attract price-sensitive residential retrofit consumers. Commercial facility managers in Singapore exhibit the lowest price sensitivity due to outcome-based energy reduction contracts, while residential plug-in buyers in the United States drive the steepest discount pressure.
Supply Chain Analysis
Copper winding supply rests on Chinese smelter concentration, while neodymium magnet sourcing draws from Chinese rare earth refiners. Relay mechanisms and 2.4 GHz transceiver modules hinge on Asian contract manufacturing clusters in Shenzhen and Dongguan. Single-source vulnerability in Chinese rare earth processing exposes margin structures to export restriction shocks. Distribution runs through electrical wholesale networks and direct OEM procurement channels serving North American and European specification markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart wiring devices market sits in a protocol-transition phase where Matter-native specification is displacing fragmented Zigbee and Z-Wave legacy installations in new construction.
For Market Incumbents: Hedge against Wi-Fi Direct commoditization by deepening certification investment for EU Radio Equipment Directive cybersecurity baselines and securing native protocol specification with Sun Belt residential builders. Channel control through electrical distributor exclusivity agreements protects specification-grade positioning against direct-to-consumer entrants. For New Entrants and Emerging Players: E-commerce marketplace routes unlock residential retrofit penetration where consumer self-installation bypasses electrician labor bottlenecks. White-space concentrates in retrofit-friendly smart outlet form factors for Germany and France's aging housing stock, and in environmental-occupancy sensor bundling for Singapore multi-dwelling units. Direct-to-consumer positioning with Matter-native plug-and-play messaging captures price-sensitive switch replacement demand. For Investors and Strategic Acquirers: The window for entry favors industrial automation vendors with facility-wide energy management platforms bridging into commercial building automation. Long-term viability hinges on software-defined functionality rather than hardware margin capture. The signal to monitor is Matter protocol adoption velocity among top-ten residential builders as inflection indicator for specification authority consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Native specification with Texas and Florida builders eliminates downstream retrofit friction and hub fragmentation. |
| EU Cybersecurity Compliance Investment | Radio Equipment Directive baseline alignment secures market access without costly dual-certification cycles. |
| Retrofit-Friendly Form Factor Development | Backward-compatible designs minimize electrician labor in Germany and France's aging residential infrastructure. |
| Environmental-Occupancy Sensor Bundling | Passive infrared plus air quality monitoring displaces standalone sensor vendors in Singapore commercial contracts. |
| Industrial Energy Platform Integration | Bridge building automation with enterprise metering architectures following Siemens AG's facility-wide architecture model. |
Methodological Framework
Document review covered regulatory filings with the FCC and EU Radio Equipment Directive, trade customs data, and SEC disclosures from electrical equipment manufacturers, complemented by interviews with product managers at smart home subsidiaries, specification engineers at residential builders, procurement leads at electrical distributors, and commissioning specialists at building management system integrators. Secondary validation drew from Ecodesign requirement databases, Matter protocol specification documents, and national building efficiency code registers. Bottom-up unit shipment estimates triangulated against top-down construction spend allocations.
Segment-level value outputs trace product type, technology protocol, end-user vertical, and application use case across the projection horizon. CAGRs derive from modeled replacement cycles, new construction penetration curves, and retrofit adoption rates. Industry-specific forecast inputs include copper and rare earth price trajectory assumptions, regional certification timeline compression, and electrician labor availability indices.
The model holds under stable regulatory enforcement timelines and construction spend patterns; deviation in cybersecurity certification acceleration or commodity price spikes would shift volume and value trajectories. A small set of named triggers warrants ongoing watch: Matter protocol adoption velocity among top-tier builders, EU Ecodesign standby power limit tightening schedules, and Chinese rare earth export policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market