
 Digital Instrument Transformer Market | 2026-2036
Digital Instrument Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Instrument Transformer Market Outlook
Asian capacitor-grade silicon steel producers are pivoting toward higher-purity laminations for digital instrument transformer cores. General Electric leverages its Alstom grid heritage to sustain large-scale manufacturing for North American utility tenders. ABB anchors European digital substation projects with IEC 61850-compliant optical current transformer platforms. Siemens competes through integrated digital signal processing modules that merge measurement and protection functions.
A digital instrument transformer converts high-voltage or high-current signals into standardized digital outputs using optical fiber or PCB-based sensing elements, achieving accuracy classes of 0.2S or better for revenue metering and protection relaying. Optical fiber technology leads in extra-high-voltage installations above 245 kV where conventional iron-core designs face saturation limits. PCB technology dominates distribution-level deployments below 72.5 kV, where cost sensitivity and space constraints favor compact Rogowski coil or resistive-divider architectures. Combined transformer configurations are gaining traction in digital substations seeking unified voltage and current acquisition points.
The IEC 61850 standard from the International Electrotechnical Commission defines substation communication protocols that mandate sampled value interfaces, directly shaping digital instrument transformer interoperability requirements. IEEE C57.13 in the United States governs accuracy and burden specifications for instrument transformers deployed in revenue metering circuits. China's GB standards and State Grid Corporation technical specifications enforce local type-testing regimes that filter market access for non-domestic suppliers. Stakeholders must monitor evolving accuracy demands from distributed energy resource interconnection codes and decide between optical versus PCB sensing investments before procurement cycles lock in.
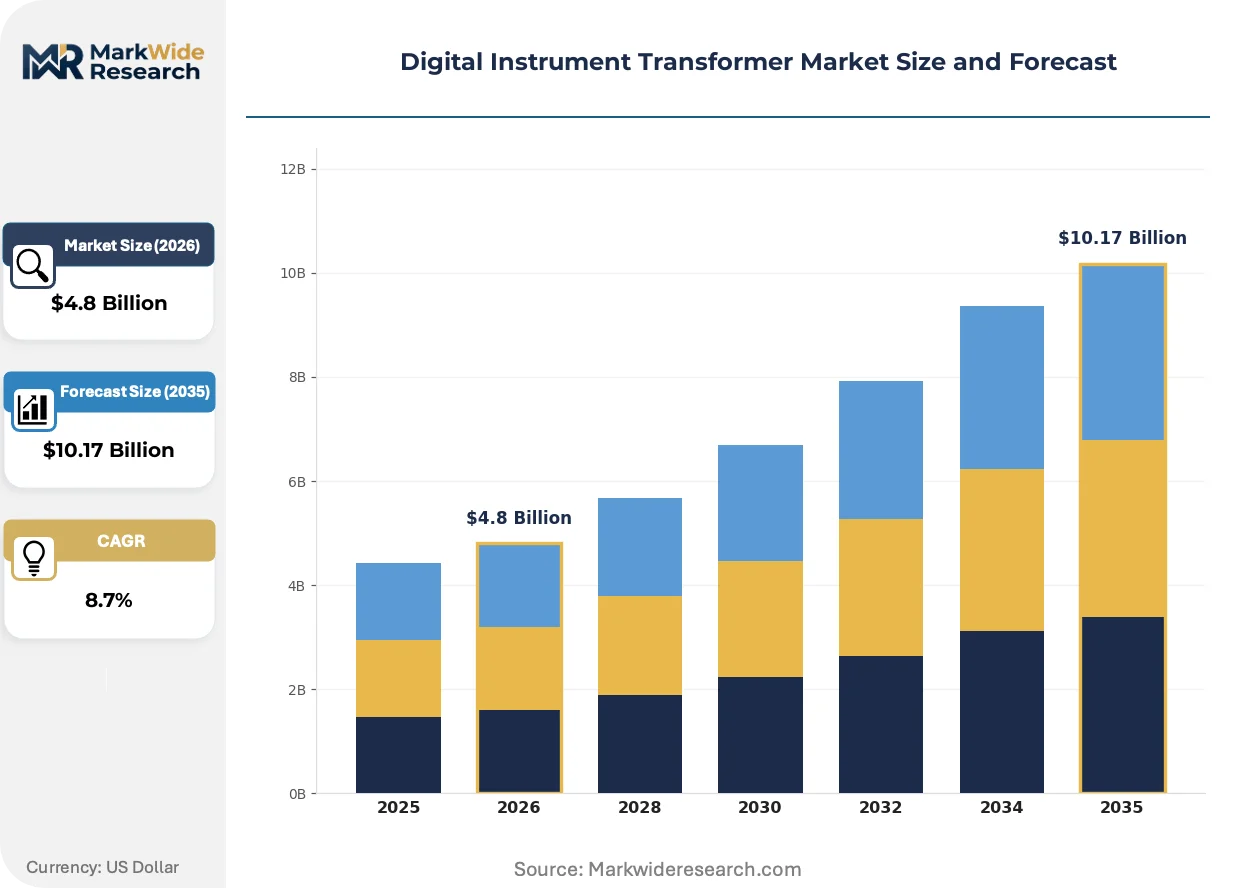
Market Dynamics
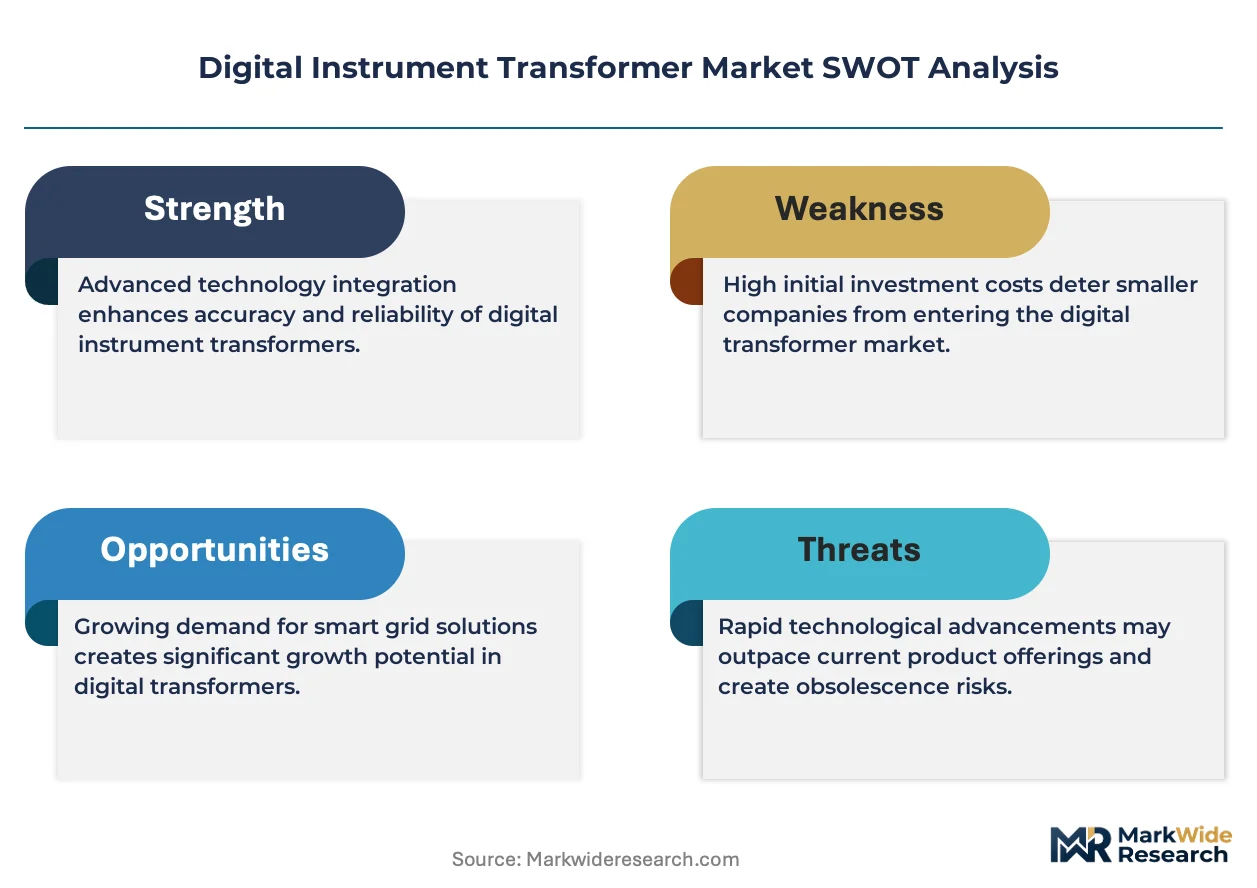
IEC 61850 standardization is compressing product development cycles while optical fiber sensing architectures displace conventional iron-core designs above 245 kV, forcing manufacturers to retool for unified measurement-protection platforms.
Growth Catalysts
- Offshore wind integration mandates:Germany's transmission operators are retrofitting converter stations with digital instrument transformers to handle bidirectional power flows from North Sea wind farms.
- Smart grid capital allocation:US utility providers under FERC Order 2222 are accelerating replacement of electromechanical infrastructure with sampled-value interfaces for distributed resource coordination.
- Optical sensing maturation:Advances in Faraday-effect current sensing and Pockels-cell voltage measurement are eliminating magnetic saturation constraints in extra-high-voltage installations.
Market Restraints
- Capacitor-grade silicon steel supply concentration:Asian producers control lamination purity grades required for PCB-based Rogowski coil cores, creating input cost volatility for distribution-level manufacturers.
- GB standards compliance friction:China's State Grid technical specifications enforce local type-testing regimes that filter market access for non-domestic suppliers seeking grid interconnection.
- Technical limitation in harsh environments:Optical fiber sensors face signal degradation from temperature cycling and vibration in outdoor substation installations above 400 kV.
Strategic Opportunities
- Digital substation convergence:Combined voltage-current acquisition platforms are unifying protection and metering functions, opening retrofit opportunities in aging European transmission infrastructure.
- India's renewable integration push:CEA mandates for wide-area monitoring systems are creating first-mover advantages for IEC 61850-compliant optical current transformer deployments.
- Resistive-divider channel expansion:Compact PCB architectures are penetrating commercial-industrial microgrids through electrical distributors serving space-constrained urban substations.
Industry Challenges
- IEC 61850 engineering talent scarcity:Substation automation integrators face shortages of engineers proficient in sampled value engineering and process bus configuration.
- Legacy electromechanical integration complexity:Brownfield utilities must maintain parallel analog and digital protection schemes during multi-year transition periods, doubling relay panel footprint.
- Accuracy class certification timelines:0.2S revenue metering validation requires extended field trials under IEEE C57.13, stretching product launch schedules for new optical sensing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Instrument Transformer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Transformer, Current Transformer, Combined Transformer, Digital Relay Technology: PCB Technology, Optical Fiber Technology, Wireless Communication, Digital Signal Processing End User: Utility Providers, Industrial Manufacturers, Commercial Buildings, Renewable Energy Sector Installation: Indoor Installation, Outdoor Installation, Panel Mount, Rack Mount |
| Companies Covered | General Electric, ABB, Siemens, Schneider Electric SE, ARTECHE, RITZ Instrument Transformers GmbH, Sieyuan Electric Co. Ltd., Takaoka Toko Co. Ltd., BHEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Instrument Transformer Market Strategic Shifts
Digital substation architectures are collapsing the historical separation between measurement and protection functions, creating demand for unified sensing platforms that stream sampled values directly to process buses.
Rogowski coil PCB assemblies with integrated analog-to-digital converters are unifying current measurement and signal conditioning into single surface-mount modules. Distribution utilities below 72.5 kV are adopting these compact architectures to eliminate separate secondary wiring runs. This unification is compressing panel space requirements and reducing installation labor by half in urban retrofit projects.
China's GB/T 20840 series is mandating digital output interfaces for all new grid-connected instrument transformers, accelerating domestic optical sensor production. State Grid procurement specifications now require sampled value compliance as a baseline qualification. Manufacturers serving this market are reconfiguring test laboratories to parallel IEC 61850-9-2LE and GB protocol validation.
Electrical distributors are bundling digital instrument transformers with engineering services for microgrid developers seeking turnkey interconnection packages. This channel shift displaces traditional specification-driven procurement through consulting engineers. The pattern is most visible in US commercial-industrial segments where project developers prioritize single-source accountability over lowest-first-cost component sourcing.
Digital Instrument Transformer Market Segmentation
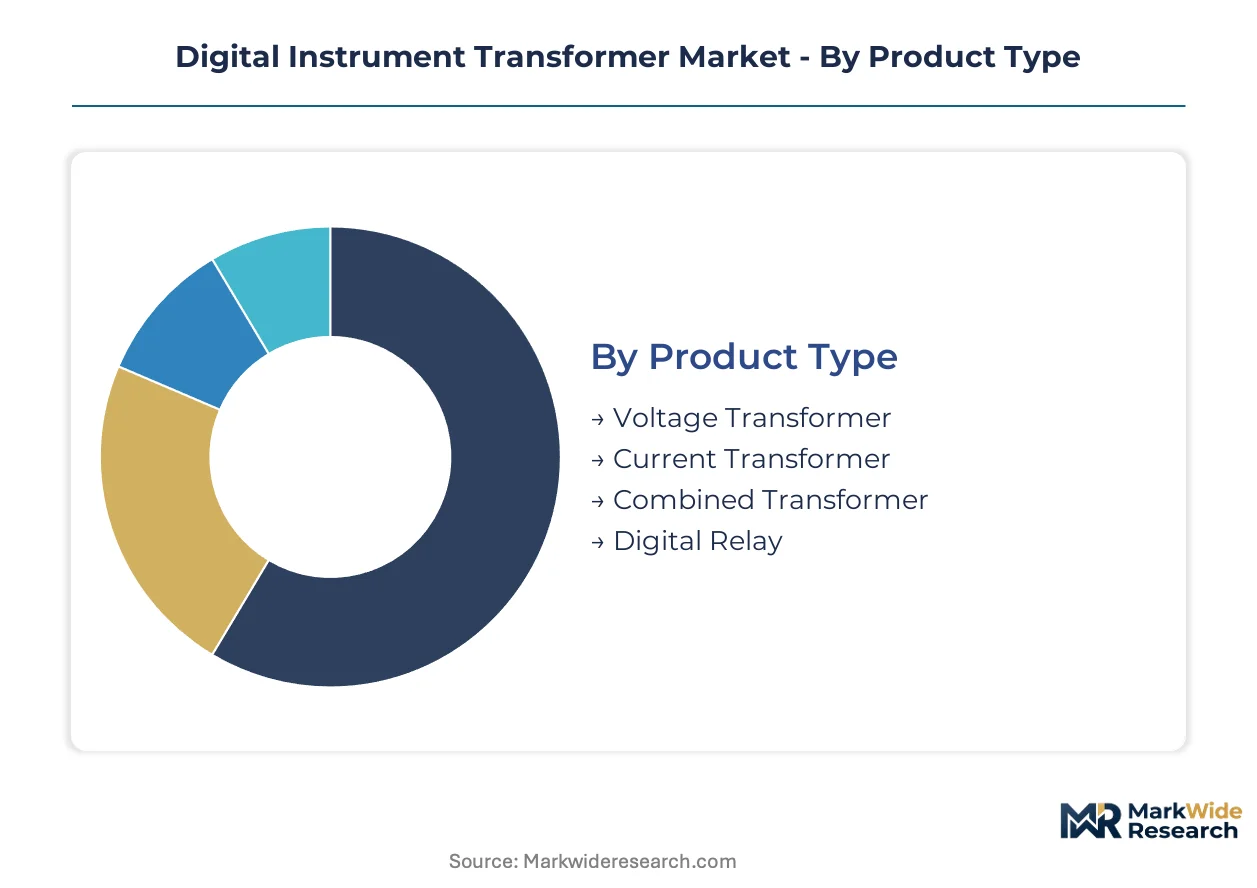
Digital instrument transformer procurement decisions hinge on voltage class, interoperability requirements, and installation environment. Buyers weigh optical fiber accuracy against PCB cost efficiency while navigating IEC 61850 compliance mandates across substation retrofit and greenfield projects.
Product Type:
Buyers prioritize accuracy class certification and protection-monitoring integration when selecting transformer architectures for substation deployments.
- Current Transformer:Optical fiber designs using Faraday-effect sensing eliminate magnetic saturation in installations above 245 kV. Demand concentrates in Germany where transmission operators retrofit North Sea offshore wind converter stations for bidirectional power flow measurement.
- Combined Transformer:Unified voltage-current acquisition platforms stream sampled values to single process bus connections. Germany's transmission operators specify these for digital substation retrofits seeking to collapse legacy relay panel footprints.
- Voltage Transformer:Pockels-cell optical sensors achieve 0.2S accuracy classes for revenue metering in extra-high-voltage circuits.
- Digital Relay:Integrated protection modules with embedded signal processing reduce external wiring complexity.
Current Transformer leads on scale; Combined Transformer leads on momentum.
Technology:
Technology selection tracks voltage tier and environmental exposure, with optical architectures commanding premium positioning above 245 kV.
- Optical Fiber Technology:Faraday-effect current sensing and Pockels-cell voltage measurement operate without magnetic cores. Extra-high-voltage installations above 400 kV in China adopt these for immunity to saturation and reduced insulation requirements.
- PCB Technology:Rogowski coil assemblies with surface-mount ADCs integrate measurement and signal conditioning. Distribution utilities below 72.5 kV in the United States deploy these compact modules for urban substation retrofits where panel space constraints dominate.
- Digital Signal Processing:Integrated modules merge protection and metering algorithms in unified hardware platforms.
- Wireless Communication:IEEE 802.11-based sampled value transmission eliminates copper process bus cabling in remote monitoring applications.
Optical Fiber Technology commands the premium tier; PCB Technology expands most quickly in volume terms.
End User:
End-user segments diverge on procurement channel, with utilities specifying through consulting engineers and microgrid developers sourcing via electrical distributors.
- Utility Providers:Transmission and distribution operators under FERC Order 2222 in the United States accelerate electromechanical replacement with IEC 61850-compliant sampled value interfaces. Capital allocation prioritizes wide-area monitoring integration for distributed resource coordination.
- Renewable Energy Sector:Offshore wind developers in Germany require bidirectional measurement at converter stations. CEA mandates in India drive first-mover deployments of optical current transformers for grid interconnection compliance.
- Industrial Manufacturers:Steel and chemical plants specify combined transformers for captive substation protection upgrades.
- Commercial Buildings:Microgrid developers in urban United States markets procure through distributors seeking turnkey interconnection packages.
Utility Providers anchor procurement volume; Renewable Energy Sector shows the steepest expansion trajectory.
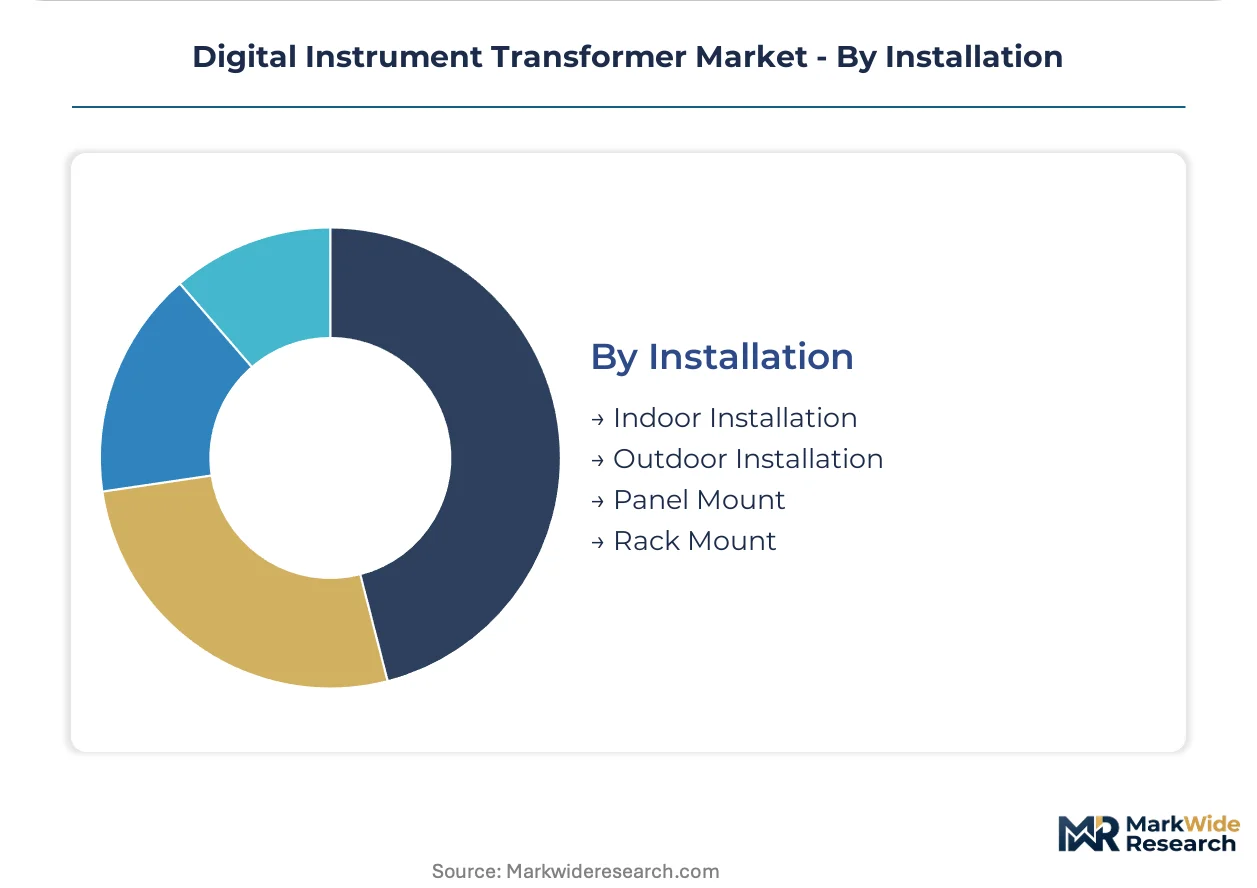
Installation:
Installation type determines enclosure ratings, thermal management, and vibration resistance specifications for substation deployments.
- Outdoor Installation:Optical fiber sensors in metal-clad enclosures face signal degradation from temperature cycling and vibration above 400 kV. German transmission operators specify these for North Sea converter station retrofits with harsh marine exposure.
- Indoor Installation:PCB-based Rogowski coils in climate-controlled relay buildings achieve extended calibration intervals. Distribution utilities in the United States favor these for urban substation modernization projects.
- Panel Mount:Compact form factors integrate into existing switchgear assemblies without structural modification.
- Rack Mount:Standardized 19-inch enclosures accommodate test laboratory and mobile substation applications.
Outdoor Installation dominates transmission-level revenue; Indoor Installation gains share fastest in distribution retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined compliance pathways for IEC 61850 certification. Cost-of-compliance gaps between Europe's stringent type-testing regimes and Asia's accelerated approval timelines are concentrating optical sensor assembly in East Asian industrial clusters.
Germany
Transmission operators retrofit North Sea converter stations for offshore wind integration. The EU Green Deal and national renewable energy targets mandate bidirectional power flow measurement at grid interconnection points. Industrial activity clusters in Hamburg and Lower Saxony, where converter station projects drive demand for combined transformer platforms.
United States
Utility providers accelerate smart grid deployments under FERC Order 2222 for distributed resource coordination. IEEE C57.13 governs accuracy specifications for revenue metering circuits in wholesale electricity markets. Procurement concentrates in Texas and California, where independent system operators prioritize wide-area monitoring infrastructure.
China
State Grid Corporation technical specifications enforce GB/T 20840 digital output mandates for all new grid-connected transformers. The dual carbon goals program accelerates replacement of electromechanical infrastructure in transmission corridors. Manufacturing concentrates in Jiangsu and Shandong provinces, where domestic optical sensor production scales for 400 kV installations.
India
CEA mandates for wide-area monitoring systems create first-mover deployment opportunities for optical current transformers. Central Electricity Authority regulations require sampled value interfaces for renewable energy interconnection compliance. Project activity clusters in Gujarat and Tamil Nadu, where solar and wind integration drives substation modernization.
Japan
Utilities deploy compact PCB-based transformers for urban substation retrofits constrained by space limitations. METI grid modernization programs prioritize earthquake-resistant digital architectures for critical infrastructure resilience. Manufacturing and deployment concentrate in the Kanto region around Tokyo, where dense load centers necessitate panel-space optimization.
Digital Instrument Transformer Market Competitive Environment
German and Swiss producers anchor the premium tier for IEC 61850-compliant optical platforms; Chinese specialists hold cost-optimized positions in distribution-voltage PCB assemblies. The vendor base stratifies across three tiers: integrated conglomerates with grid heritage, mid-cap specialists focused on optical sensing, and domestic champions serving protected procurement channels. Consolidation pressure intensifies as unified measurement-protection platforms displace standalone product lines. Capacity expansion in Faraday-effect sensor manufacturing and strategic partnerships for GB standards compliance represent dominant competitive vectors.
Among European-integrated conglomerates, General Electric and ABB exemplify archetypes leveraging Alstom grid heritage and optical current transformer platforms respectively. Siemens occupies a position bridging integrated signal processing with merged measurement-protection functions. These three anchors represent strategic postures available to competitors: heritage-driven large-scale manufacturing, standards-compliant platform specialization, and convergence-focused module integration.
| Leading Market Players |
|---|
| General Electric |
| ABB |
| Siemens |
| Schneider Electric SE |
| ARTECHE |
| RITZ Instrument Transformers GmbH |
| Sieyuan Electric Co. Ltd. |
| Takaoka Toko Co. Ltd. |
| BHEL |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between IEC 61850-compliant optical platforms and distribution-voltage PCB assemblies manifests in dual pricing architectures and geographically separated sourcing networks. Premium-tier manufacturers anchor Faraday-effect sensor production in German and Swiss industrial clusters, while cost-optimized Rogowski coil assembly concentrates in East Asian electronics manufacturing corridors.
Pricing Analysis
Distributor margins in electrical supply channels compress PCB-based transformer pricing by fifteen to twenty percent below direct-OEM optical fiber procurement. Three-tier pricing structure across premium IEC 61850-certified, standard utility-grade, and economy distribution-tier levels tracks accuracy class and protection-monitoring integration depth. Pricing pressure stems from Asian capacitor-grade silicon steel supply volatility feeding into lamination input costs. Microgrid developers sourcing through electrical distributors exhibit highest price sensitivity; German transmission operators demonstrate lowest sensitivity due to offshore wind mandate compliance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for optical sensor module fulfillment. Manufacturing concentrates in China, Germany, and Japan for Faraday-effect cores, precision winding equipment, and surface-mount ADC assemblies respectively. Raw material dependencies include high-purity silicon steel laminations, specialty optical fibers, and ceramic substrate PCBs. Single-source vulnerability concentrates in Asian capacitor-grade silicon steel refining capacity. Distribution runs through authorized electrical distributors for sub-72.5 kV deployments and direct utility contracting for extra-high-voltage installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as offshore wind integration mandates and digital substation retrofits shift procurement toward 0.2S accuracy-class optical platforms with unified measurement-protection convergence.
For Market Incumbents: Cement dominance in IEC 61850 engineering talent pools through captive training programs and certification partnerships with substation automation integrators facing acute sampled value engineering scarcity. Expand Faraday-effect sensor manufacturing capacity in East Asian industrial clusters to capture cost-of-compliance advantages against European type-testing regimes. Vertical integration into high-purity silicon steel lamination sourcing mitigates Asian supply concentration volatility threatening PCB-based product margins. For New Entrants and Emerging Players: Electrical distributors serving US commercial-industrial microgrid developers offer the most penetrable channel for compact PCB-based Rogowski coil assemblies with turnkey interconnection bundling. Target India's renewable integration push under CEA wide-area monitoring mandates for first-mover optical current transformer deployments ahead of domestic incumbent capacity buildout. Pursue GB standards compliance partnerships with Chinese testing laboratories to unlock State Grid procurement qualification pathways filtered against non-domestic suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap optical sensing specialists possessing IEC 61850-9-2LE process bus validation capabilities and established utility specification relationships. Long-term viability over the five-to-ten year window rests on convergence toward unified measurement-protection platforms displacing standalone transformer and relay product lines. Watch for inflection in brownfield utility parallel analog-digital protection scheme transition timelines, as accelerated retirement of electromechanical infrastructure signals premium platform procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Compliance Partnership | Unlocks State Grid procurement access for optical sensor manufacturers seeking China market entry. |
| IEC 61850 Engineering Talent Acquisition | Addresses critical scarcity constraining substation automation integrator capacity expansion. |
| Faraday-Effect Sensor Capacity Expansion | Captures offshore wind converter station retrofit demand in German North Sea transmission corridors. |
| Rogowski Coil PCB Module Integration | Compresses panel space requirements for US urban distribution substation modernization projects. |
| Combined Transformer Platform Development | Unifies voltage-current acquisition for digital substations collapsing legacy relay panel footprints. |
Study Parameters
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market's utility planning officers, substation automation integrators, electrical distributor category managers, and optical sensor manufacturing engineers. Secondary validation draws from IEC 61850 standard documentation, State Grid Corporation technical specifications, FERC Order 2222 implementation filings, and CEA wide-area monitoring system mandates. Bottom-up project pipeline analysis triangulates against top-down transmission infrastructure investment forecasts.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include voltage class tier, technology architecture, end-user procurement channel, and installation environment exposure. CAGRs derive from installed base replacement cycles, renewable interconnection mandates, and digital substation capital allocation patterns. Industry-specific forecast inputs incorporate offshore wind converter station commissioning schedules and electromechanical infrastructure age profiles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IEC 61850 standard evolution, GB standards compliance pathway modifications, and capacitor-grade silicon steel supply restructuring. Forecasts reflect documented assumptions regarding utility capital commitment continuity and regulatory mandate enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market