
 USB Devices Market | 2026-2036
USB Devices Market Size, Share, and Industry Trends Forecast 2026-2036
USB Devices Market Outlook
Project finance for automated surface-mount assembly lines is tilting capital requirements toward scaled manufacturers. Kingston Technology leverages captive NAND flash supply to sustain margin control across USB flash drive portfolios. Samsung Electronics anchors high-volume production of USB-C controller chips, while ADATA Technology specializes in ruggedized industrial-grade USB storage for field applications.
USB devices comprise standardized interconnect hardware including connectors, cables, hubs, and flash storage media engineered to Universal Serial Bus protocol specifications up to USB4 Version 2.0 delivering 80 Gbps bandwidth. These components enable power delivery, data synchronization, and peripheral expansion across computing, mobile, and embedded systems. USB flash drives and USB-C hubs currently lead product-type revenue pools, with peripheral integration applications growing fastest as hybrid work models multiply docking station deployments. Enterprise end users represent the most concentrated margin pool due to bulk procurement contracts and security-certified product requirements.
The USB Implementers Forum certifies protocol compliance, while the EU Common Charger Directive mandates USB-C ports on portable electronics sold in member states, forcing hardware redesigns across OEM supply chains. China's MIIT enforces GB/T national standards for connector durability and electromagnetic compatibility, shaping export manufacturing specifications. Stakeholders must monitor whether India's BIS certification expansion to consumer electronics will replicate the EU's standardization pressure across South Asian supply chains.
Market Dynamics
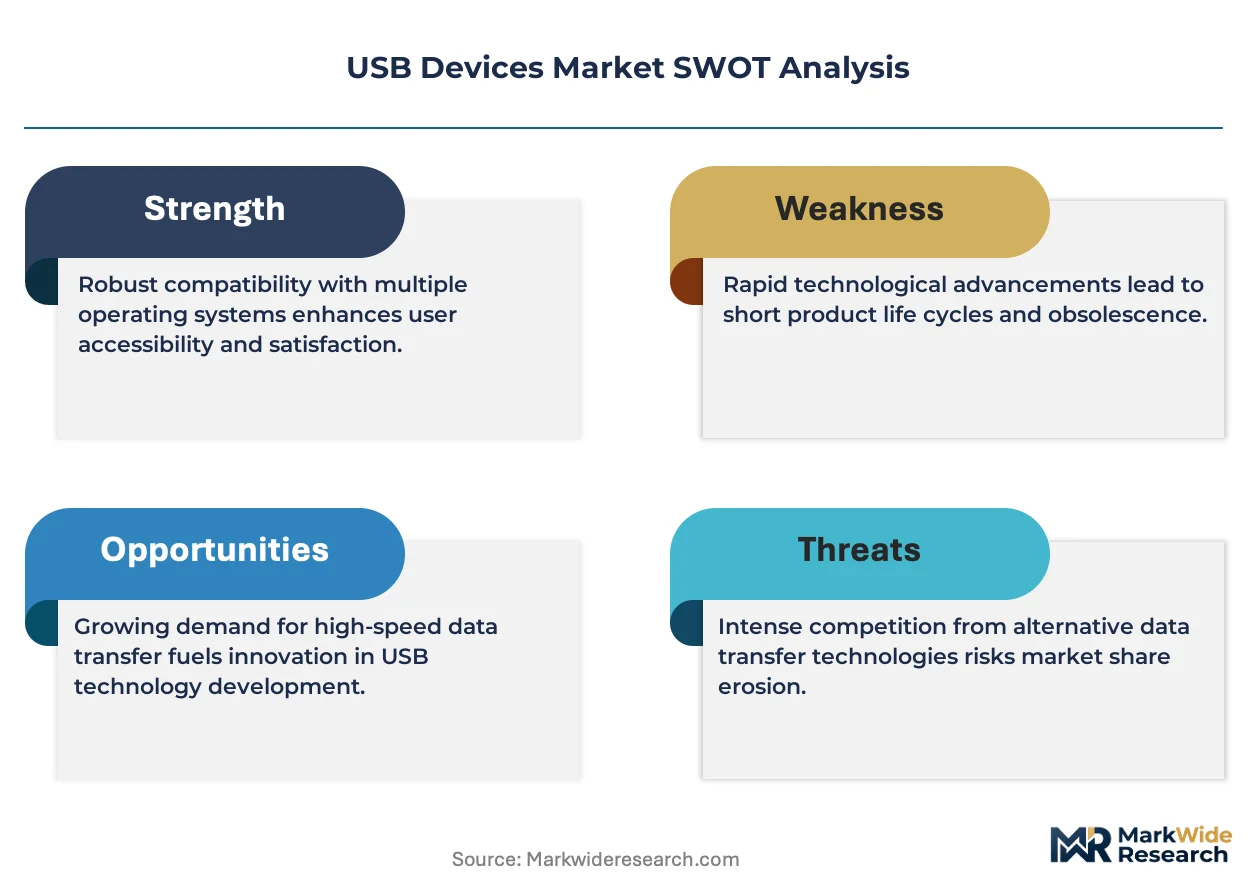
The USB Devices Market is being structurally compressed by the EU Common Charger Directive, which mandates USB-C standardization across portable electronics and is forcing hardware redesigns throughout OEM supply chains.
Growth Catalysts
- Enterprise IT refresh cycles:Corporate workspaces are expanding procurement of USB-C hubs and docking stations to support hybrid work infrastructure. Bulk procurement contracts from Fortune 500 firms concentrate demand volume.
- EU Common Charger Directive:The mandate requiring USB-C ports on all portable electronics sold in member states is accelerating replacement demand across smartphone, tablet, and peripheral categories.
- Dongguan-Shenzhen manufacturing corridor:China's electronics cluster supplies the majority of global USB cable and connector volumes, enabling cost-efficient scaling for export markets.
Market Restraints
- Controller chip supply concentration:Samsung Electronics anchors high-volume production of USB-C controller silicon, creating single-source vulnerability for tier-two manufacturers.
- NAND flash price volatility:Kingston Technology's captive NAND supply provides margin insulation unavailable to assemblers purchasing spot-market memory chips.
- USB4 Version 2.0 certification complexity:The 80 Gbps bandwidth specification demands expensive test equipment and extended validation timelines, raising barriers for new entrants.
Strategic Opportunities
- Industrial field applications:ADATA Technology's ruggedized USB storage segment remains underpenetrated by standard consumer-grade competitors, offering margin expansion potential.
- India BIS certification expansion:The Bureau of Indian Standards is extending mandatory certification to consumer electronics, potentially replicating EU standardization pressure across South Asian supply chains.
- Peripheral integration convergence:USB-C power delivery combined with DisplayPort alternate mode is collapsing multiple cable categories into single-solution docking architectures.
Industry Challenges
- USB-IF compliance timeline compression:Certification backlog at the USB Implementers Forum is extending product launch windows for protocol-compliant devices.
- Legacy USB-A inventory stranding:Enterprises face write-down risk on existing peripheral fleets as USB-C mandates accelerate obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Devices Market |
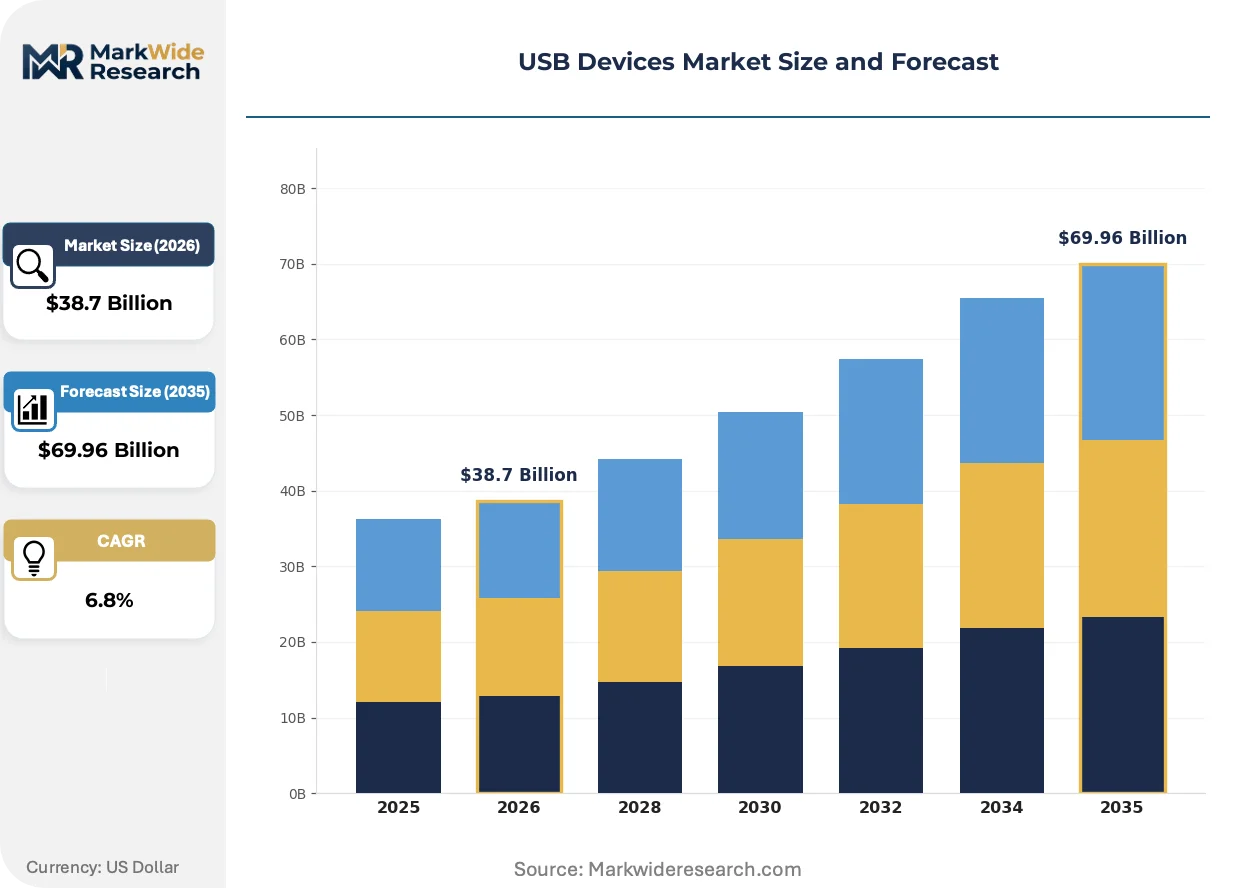
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Flash Drives, USB Hubs, USB Chargers, USB Cables Application: Data Storage, Charging, Device Connectivity, Peripheral Integration End User: Consumers, IT Professionals, Educational Institutions, Enterprises Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Kingston Technology, SanDisk, Samsung Electronics, Transcend Information, Toshiba Corporation, Corsair Gaming, ADATA Technology, Dell Technologies, HP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Devices Market Strategic Shifts
Active cable architectures and integrated controller silicon are compressing the traditional separation between passive interconnect and active signal conditioning, reshaping how manufacturers source and assemble USB device components.
USB4 Version 2.0 active cable technology embeds retimer and redriver chips directly within connector housings to maintain signal integrity across 80 Gbps transmission distances. Data center operators and high-resolution display manufacturers are adopting these cables for workstation-to-peripheral connections exceeding two meters. This integration is rendering obsolete the discrete signal booster boxes that previously extended USB-C run lengths.
The EU Common Charger Directive is forcing hardware redesigns across OEM supply chains by mandating USB-C as the universal charging interface for portable electronics sold in member states. Smartphone and tablet manufacturers must retool connector layouts and eliminate proprietary charging ports, compressing design cycle timelines. Peripheral suppliers serving the European market are experiencing accelerated demand for USB-C hub and adapter products as consumers bridge legacy device compatibility.
Enterprise procurement teams are consolidating vendor relationships around security-certified USB storage suppliers capable of meeting FIPS 140-2 or Common Criteria requirements. Financial services and healthcare verticals are displacing open-market flash drive purchases with contracted supply agreements featuring centralized device management and remote kill capabilities. This concentration is most visible in North American and Western European corporate IT departments managing hybrid workforces with strict data loss prevention protocols.
USB Devices Market Segmentation
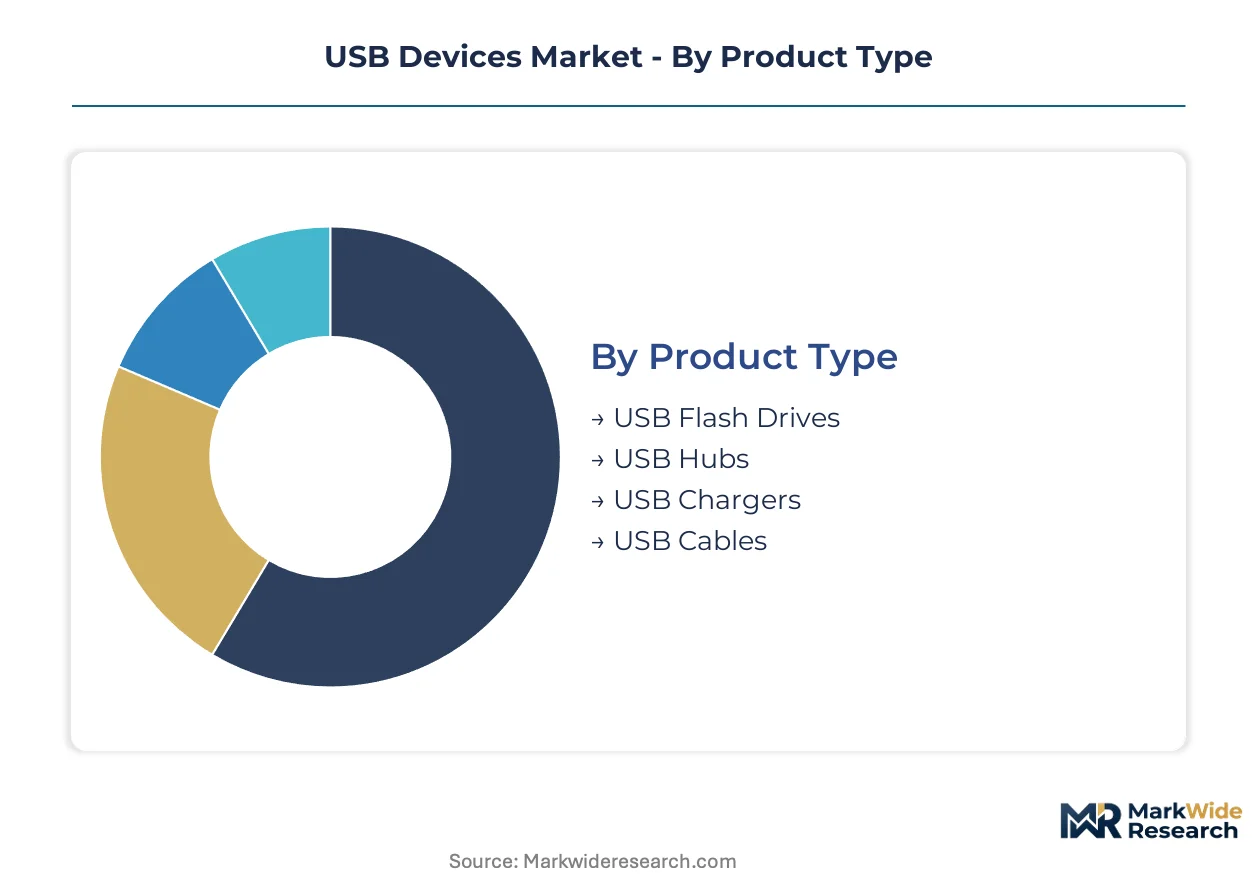
USB device procurement cycles vary dramatically across segments, with enterprise docking infrastructure refreshing every three to four years while consumer cable replacements occur continuously. Understanding these differential turnover rates enables manufacturers to calibrate inventory and pricing strategies against predictable replacement waves.
Product Type:
Refresh cycles compress from years for flash storage to months for consumable cables, creating divergent margin profiles across hardware categories.
- USB Flash Drives:NAND flash-based removable storage media with capacities spanning entry-level to enterprise-encrypted tiers. Corporate IT departments in financial services and healthcare verticals are consolidating procurement around FIPS 140-2 certified suppliers with remote device management capabilities.
- USB Hubs:Multi-port expansion docks integrating USB-C power delivery with DisplayPort alternate mode for single-cable workstation architectures. Fortune 500 hybrid work programs are driving bulk procurement of docking stations with 85W+ power delivery and dual 4K display support.
- USB Chargers:Power delivery adapters ranging from 5W legacy units to 240W USB-C PD 3.1 compliant supplies. The EU Common Charger Directive is eliminating proprietary charging ports across smartphone OEM supply chains.
- USB Cables:Passive and active interconnects spanning USB 2.0 through USB4 Version 2.0 specifications. China's Dongguan-Shenzhen manufacturing corridor supplies the majority of global volumes with cost-efficient scaling.
USB Cables dominate installed base by unit volume. USB Hubs are where expansion concentrates as enterprise docking architectures displace discrete peripheral connections.
Application:
Functional requirements fragment across use cases, with enterprise security protocols imposing certification burdens absent from consumer charging applications.
- Data Storage:Removable flash media and external SSD enclosures for file transport and backup. Ruggedized industrial-grade designs from specialized suppliers address field applications in energy and construction verticals.
- Charging:Power delivery infrastructure for smartphones, tablets, laptops, and emerging IoT device categories. Regulatory mandates in Europe are collapsing proprietary charging ecosystems into standardized USB-C implementations.
- Device Connectivity:Point-to-point links between hosts and peripherals including printers, scanners, and audio equipment. Legacy USB-A inventory faces accelerated obsolescence as USB-C mandates proliferate through OEM supply chains.
- Peripheral Integration:Consolidated docking architectures combining data, video, and power over single-cable connections. Hybrid work models are multiplying deployment of integrated hub solutions in corporate workspaces.
Charging commands the highest unit volume. Peripheral Integration is climbing the fastest as enterprises consolidate cable categories into unified docking infrastructures.
End User:
Purchasing sophistication ranges from price-sensitive individual consumers to security-audited enterprise procurement teams with centralized device management requirements.
- Consumers:Individual purchasers selecting based on price, brand recognition, and compatibility with existing device ecosystems. Online retail channels dominate this segment with transparent price comparison and rapid delivery expectations.
- IT Professionals:Technical buyers evaluating specifications including bandwidth certification, power delivery profiles, and build quality for departmental deployments. This cohort drives demand for USB-IF certified active cables in professional workstation environments.
- Educational Institutions:Bulk procurement from K-12 and higher education systems with standardized device programs. Chromebook and tablet charging cart installations create concentrated demand for multi-port USB-C charging infrastructure.
- Enterprises:Corporate IT departments with security-certified supply agreements, remote kill capabilities, and data loss prevention protocols. Financial services and healthcare verticals are displacing open-market purchases with contracted vendor relationships.
Consumers represent the broadest installed base. Enterprises are gaining share fastest as security requirements and hybrid work infrastructure drive formalized procurement channels.
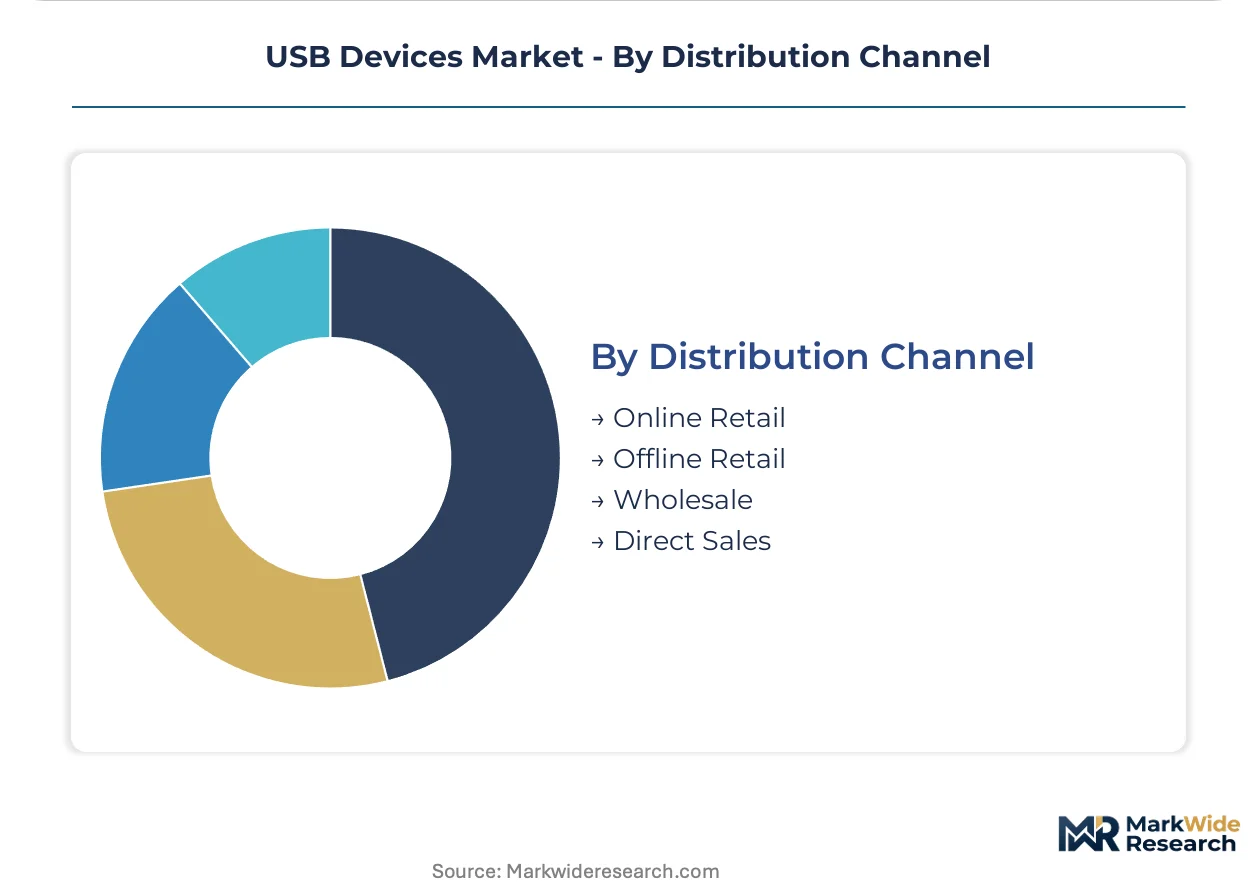
Distribution Channel:
Channel economics diverge sharply between high-velocity e-commerce fulfillment and relationship-driven enterprise direct sales with extended payment terms.
- Online Retail:E-commerce platforms including Amazon, direct-to-consumer brand storefronts, and specialized electronics marketplaces. Consumer-grade cables and chargers flow predominantly through this channel with price-transparent competition.
- Offline Retail:Brick-and-mortar electronics retailers, big-box stores, and carrier-owned storefronts. Immediate availability and physical product inspection sustain this channel for urgent replacement purchases.
- Wholesale:Volume distribution to resellers, system integrators, and regional electronics distributors. Enterprise docking stations and certified flash storage often route through authorized distribution with technical support attachments.
- Direct Sales:Manufacturer-to-enterprise contracts with customized security certifications, centralized device management platforms, and multi-year supply agreements. North American and Western European corporate IT departments concentrate procurement through this channel.
Online Retail captures the highest transaction volume. Direct Sales is where margin expansion concentrates as security requirements and bulk contracts displace commoditized spot purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States, Germany, and China concentrate the highest-value USB device purchasing power, while manufacturing gravity clusters in China's Dongguan-Shenzhen corridor and South Korea's semiconductor belt shape supply availability.
United States
Fortune 500 hybrid work programs drive bulk procurement of USB-C docking stations with 85W+ power delivery. FCC certification requirements filter out uncertified active cable suppliers from enterprise supply chains. Corporate IT departments in California's Silicon Valley and Texas's Austin tech corridor standardize on FIPS 140-2 certified flash storage with remote kill capabilities.
Germany
Industrial automation OEMs source ruggedized USB storage for field equipment connectivity in manufacturing plants. REACH and RoHS compliance mandates restrict hazardous substance content in connector plating and cable sheathing. Bavaria's automotive supplier ecosystem around Munich integrates USB-C power delivery into next-generation vehicle infotainment architectures.
China
MIIT enforces GB/T national standards for connector durability and electromagnetic compatibility across export manufacturing. The Dongguan-Shenzhen electronics manufacturing corridor supplies the majority of global USB cable and connector volumes with cost-efficient scaling. Domestic smartphone OEMs in Beijing and Shanghai accelerate USB-C port standardization ahead of regulatory deadlines.
South Korea
Samsung Electronics anchors high-volume production of USB-C controller silicon for global OEM supply chains. MFDS certification frameworks shape medical device connectivity requirements that propagate through industrial USB applications. Seoul's Pangyo Techno Valley hosts fabless semiconductor design houses specializing in USB4 retimer and redriver chip architectures.
India
BIS certification expansion to consumer electronics is replicating EU standardization pressure across South Asian supply chains. Educational institutions in Karnataka and Maharashtra bulk-procure multi-port USB-C charging infrastructure for Chromebook and tablet deployments. Tamil Nadu's electronics manufacturing zones attract cable and connector assembly investments serving domestic and export markets.
USB Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. Memory-integrated suppliers with captive NAND flash supply command margin insulation unavailable to spot-market assemblers. Three strategic archetypes dominate: semiconductor-integrated conglomerates, security-certified enterprise specialists, and scaled contract manufacturers. Competitive moves concentrate on backward integration into controller silicon and geographic expansion into India's emerging certification regime.
Within the memory-integrated tier, Kingston Technology and Samsung Electronics exemplify archetypes combining upstream supply control with downstream brand presence. ADATA Technology occupies a position among ruggedized industrial-grade specialists serving field applications. SanDisk represents the brand-anchored consumer storage segment. These three companies illustrate how supply chain configuration and certification capabilities stratify competitive positioning across enterprise and consumer demand pools.
| Leading Market Players |
|---|
| Kingston Technology |
| SanDisk |
| Samsung Electronics |
| Transcend Information |
| Toshiba Corporation |
| Corsair Gaming |
| ADATA Technology |
| Dell Technologies |
| HP |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Samsung Electronics for USB-C controller silicon determines both pricing tier spreads and supply chain shape, compressing margins for tier-two assemblers while rewarding memory-integrated suppliers with captive NAND flash supply.
Pricing Analysis
Cost-plus contracts with NAND flash indexation dominate USB flash drive procurement, with Kingston Technology's captive supply insulating against spot-market volatility that erodes assembler margins. Pricing stratifies across FIPS 140-2 certified enterprise tiers, uncertified commercial grades, and unbranded economy channels, with certification premiums widening as financial services and healthcare verticals consolidate procurement. Cost compression in consumer-grade cables intensifies because China's Dongguan-Shenzhen corridor enables rapid capacity scaling. Educational institutions exhibit highest price sensitivity through bulk tender processes, while enterprise security-certified buyers prioritize remote kill capabilities and centralized management over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Pegatron, and Luxshare Precision for cable and connector assembly, with semiconductor foundry capacity tethered to Samsung Electronics and TSMC for controller silicon. Geographic supply concentration centers on China, South Korea, and Taiwan, with raw material dependencies spanning copper cathodes, LCP resin for high-speed cable sheathing, and 3D NAND flash wafers. Single-source vulnerability in USB-C controller silicon creates supply chain risk for tier-two hub and docking station manufacturers. Distribution runs through authorized wholesale channels for enterprise docking infrastructure, while consumer cables flow predominantly through Amazon and direct-to-consumer storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USB Devices Market sits in a cyclical recovery phase driven by enterprise IT refresh cycles accelerating replacement demand for USB-C docking infrastructure.
For Market Incumbents: Harden supply security through backward integration into controller silicon or exclusive foundry partnerships with Samsung Electronics and TSMC. Fortify enterprise channel control by embedding FIPS 140-2 certification and remote device management platforms into multi-year supply agreements, displacing open-market flash drive purchases in financial services and healthcare verticals. For New Entrants and Emerging Players: Establish a beachhead in ruggedized industrial-grade USB storage for field applications in energy and construction verticals, where ADATA Technology's specialization has left white space unaddressed by consumer-grade competitors. Target India's BIS certification expansion as regulatory standardization replicates EU Common Charger Directive pressure across South Asian supply chains, enabling first-mover positioning in educational institution bulk procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors memory-integrated suppliers with captive NAND flash supply and security certification capabilities. Long-term viability over the next decade hinges on backward integration into semiconductor controller design and geographic diversification into India's emerging manufacturing zones. Monitor USB-IF certification backlog resolution as the inflection signal for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controller Silicon | Samsung Electronics' dominance in USB-C controller production creates margin capture opportunity for memory-integrated suppliers. |
| FIPS 140-2 Certification Investment | Financial services and healthcare verticals are consolidating procurement around security-certified flash storage with remote kill capabilities. |
| India Manufacturing Footprint Expansion | Tamil Nadu's electronics manufacturing zones attract cable and connector assembly investments serving BIS-certified domestic and export markets. |
| USB4 Version 2.0 Active Cable Launch | Data center operators and high-resolution display manufacturers are adopting 80 Gbps retimer-embedded cables for workstation connections exceeding two meters. |
| Enterprise Direct Sales Channel Control | Fortune 500 hybrid work programs are driving bulk procurement of docking stations with 85W+ power delivery and dual 4K display support. |
Study Parameters
Operator-level perspectives from USB device procurement managers at Fortune 500 enterprises, contract manufacturing executives in China's Dongguan-Shenzhen corridor, semiconductor foundry planning officers, and USB-IF certification engineers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of memory-integrated suppliers, MIIT GB/T standard documentation, EU Common Charger Directive regulatory texts, and USB Implementers Forum certification databases. Bottom-up unit volume estimates across product categories triangulated against top-down market value reconstructions.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning product type, application, end user, and distribution channel dimensions. CAGRs were derived from replacement cycle analysis calibrated against enterprise IT refresh timelines and consumer upgrade patterns. Forecast inputs incorporated NAND flash price trajectory assumptions and USB-C port standardization penetration rates across smartphone OEM supply chains.
Stress conditions across NAND flash price volatility, USB-IF certification timeline compression, and EU regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise hybrid work permanence and OEM hardware redesign velocity. Quarterly review of USB-IF certification queue depth and BIS certification expansion timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Function Generator Market