
 Global Automotive Drive Shaft Market | 2026-2036
Global Automotive Drive Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Drive Shaft Market Intelligence
A shift from multi-source component procurement toward single-source partnerships for integrated drivetrain systems is realigning the competitive landscape for automotive drive shafts. GKN Automotive leverages its extensive global manufacturing footprint and R&D in eDrive systems to serve major OEMs. Dana Incorporated specializes in complete driveline solutions for both conventional and complex electric powertrains. Schaeffler AG competes through its expertise in high-precision components and integrated bearing solutions for modern axle systems.
An automotive drive shaft is a mechanical component engineered to transmit torque and rotation from the transmission to the vehicle's differential. These shafts are commonly manufactured via steel forging or cold rolling to achieve high torsional strength and fatigue resistance. Their primary function is delivering engine power to the drive wheels. Propeller shafts for commercial vehicles constitute a mature, high-volume product type, while carbon fiber technology is reshaping the materials segment with its superior strength-to-weight ratio.
Vehicle efficiency standards from the US EPA and Europe's EU Green Deal directly influence powertrain component design. Global ISO technical specifications govern material quality and testing protocols, ensuring reliability across the supply chain. These frameworks steer OEM material selection toward lighter, more durable drive shafts. The critical decision for manufacturers now involves balancing investments between optimizing steel shaft production and scaling composite material capabilities.
Market Dynamics
The transition to electric vehicle architectures and stringent global emissions mandates are the central forces shaping drive shaft design. This compels a re-evaluation of material science, favoring lightweight composites over traditional steel for powertrain efficiency and extended vehicle range.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and vehicle efficiency standards from the US EPA compel OEMs to adopt lighter components, including drive shafts, to meet fleet-wide emissions and consumption targets.
- Electric Vehicle Platforms:The rapid expansion of battery electric vehicle (BEV) production requires specifically engineered drive shafts to manage instant torque delivery and novel chassis packaging constraints.
- Geographic Production Focus:China's "dual carbon" goals and substantial state support for its domestic EV industry create sustained, high-volume demand for advanced driveline components.
Market Restraints
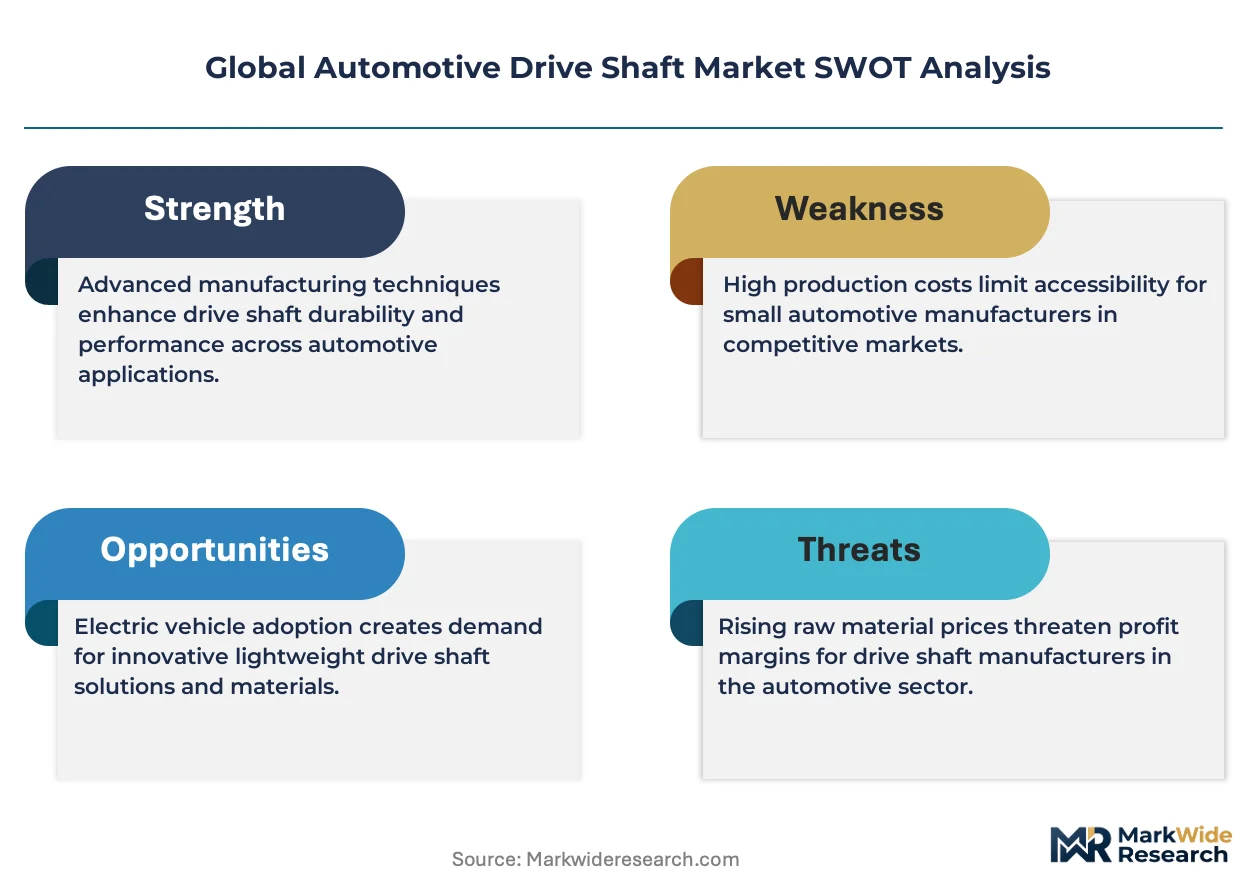
- Material Cost Structure:The high cost of carbon fiber composites and the specialized manufacturing processes required currently limit their application primarily to premium and performance vehicle segments.
- Input Price Volatility:Fluctuations in the prices of specialty steel and aluminum alloys, key inputs for conventional shafts, create margin pressure for suppliers serving high-volume, cost-sensitive vehicle programs.
- Technical Hurdles:Ensuring long-term durability and managing noise, vibration, and harshness (NVH) in hollow composite shafts presents a greater engineering challenge compared to proven forged steel designs.
Strategic Opportunities
- New Vehicle Segments:Development of specialized drive shafts for emerging all-wheel-drive (AWD) electric vehicle configurations and light commercial EVs represents an opportunity to create new product categories.
- Aftermarket Expansion:Penetrating the service and replacement parts sector in markets like India and Brazil, where an aging vehicle parc creates demand for durable and cost-effective driveline components.
- Component Intelligence:Integration of sensor technology directly into drive shafts to provide real-time torque and performance data enables value-added smart components for predictive maintenance systems.
Industry Challenges
- Capital Expenditure:Retooling production lines from manufacturing traditional steel shafts to handling advanced composite materials at scale requires significant capital investment and long lead times.
- Talent Scarcity:A shortage of engineers with expertise in composite material science, advanced bonding techniques, and the simulation of long-term fatigue in non-metallic components persists.
- Standardization Gaps:A lack of universal standards for testing and certifying the crashworthiness and field repairability of composite drive shafts can slow OEM validation and adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Drive Shaft Market |
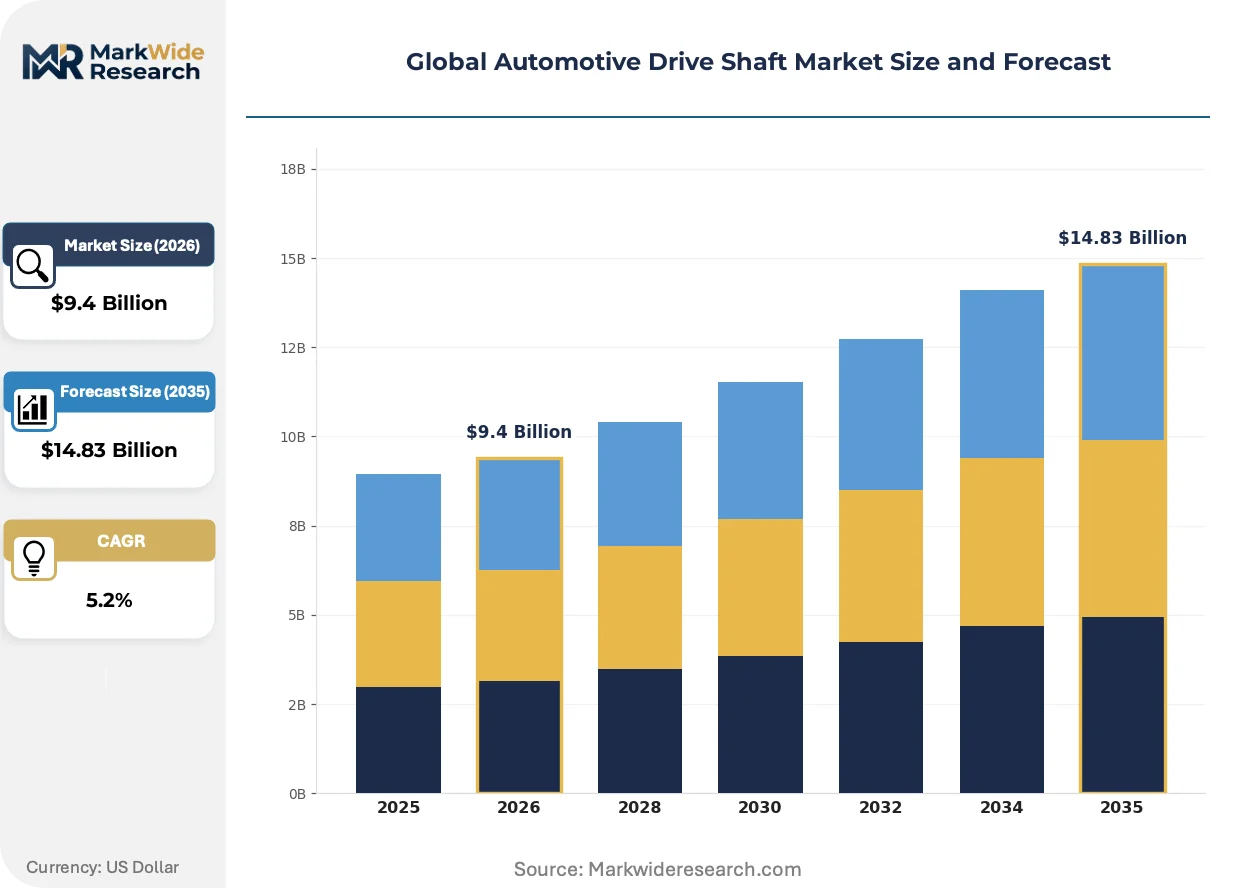
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
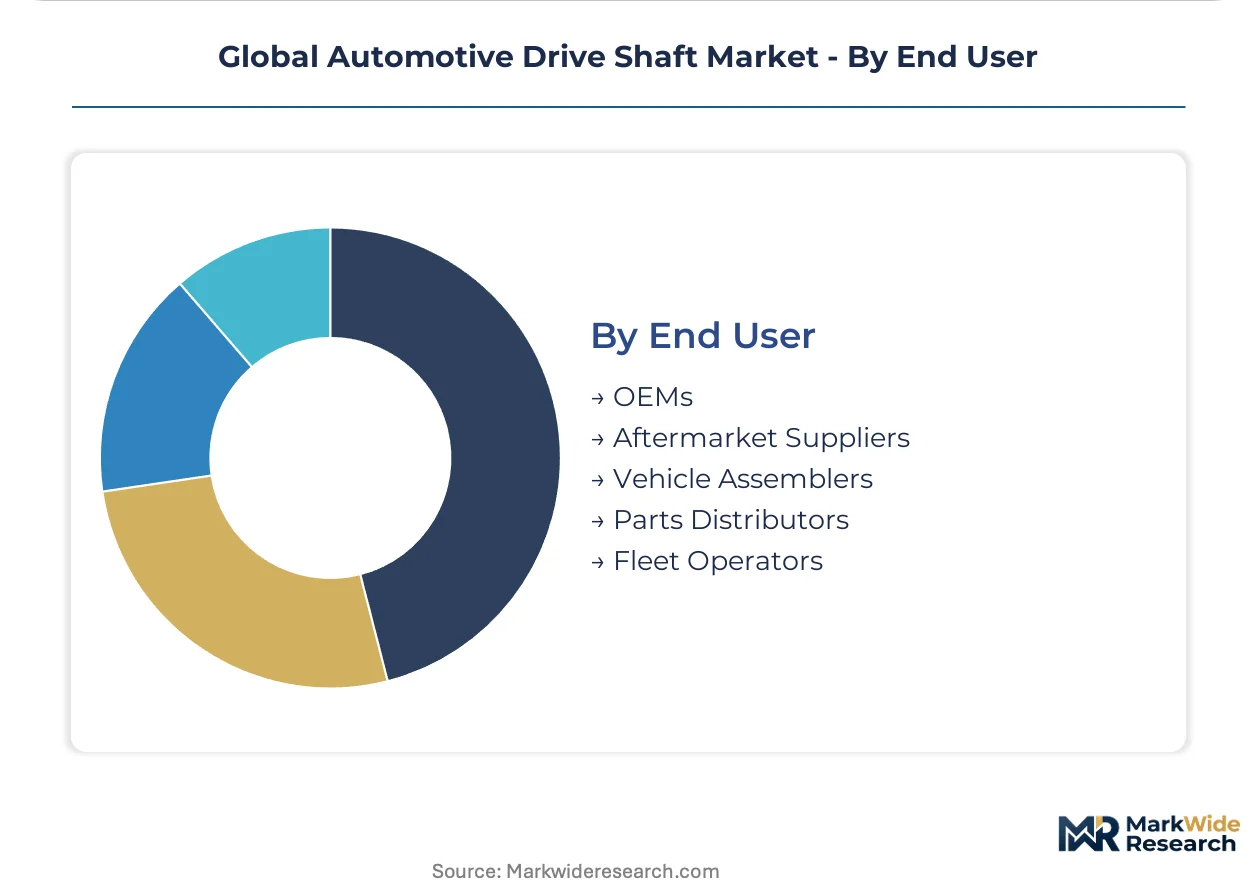
| Segmentation | Product Type: Intermediate Shaft, Propeller Shaft, Axle Shaft, Slip Shaft, Cardan Shaft Technology: Steel Forging, Aluminum Alloy, Carbon Fiber, Composite Materials, Cold Rolling Application: Passenger Cars, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles, Construction Equipment End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Parts Distributors, Fleet Operators |
| Companies Covered | GKN Automotive, Dana Incorporated, American Axle & Manufacturing, Inc., JTEKT Corporation, Hyundai Wia Corporation, Neapco Holdings LLC, Schaeffler AG, NTN Corporation, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Drive Shaft Market Strategic Shifts & Innovations
The evolution of the automotive drive shaft is defined by its deeper integration into the complete powertrain system. Component design is now dictated by system-level efficiency and performance metrics, particularly within electric vehicle architectures.
Hollow carbon fiber composite technology provides a superior strength-to-weight ratio, reducing rotational inertia and improving vehicle responsiveness. High-performance and electric vehicle OEMs are the primary adopters, seeking every advantage in efficiency and range. This material advancement is unifying the previously separate goals of powertrain performance and lightweighting into a single component design strategy.
China's Ministry of Industry and Information Technology (MIIT) enforces stringent corporate average fuel consumption and new energy vehicle credit mandates. These policies create direct financial incentives for automakers to prioritize lightweighting across all vehicle systems, including the driveline. The passenger car segment is most affected, with OEMs accelerating the validation of composite and advanced steel drive shafts to meet compliance targets.
Major automotive OEMs are moving away from multi-vendor component sourcing toward single-source partnerships for complete e-axle and integrated drivetrain systems. This change favors large, Tier-1 suppliers capable of providing a fully engineered and validated system over smaller, component-specific manufacturers. This shift in procurement is most pronounced in Europe and North America among legacy automakers transitioning to EV production.
Global Automotive Drive Shaft Market Segmentation
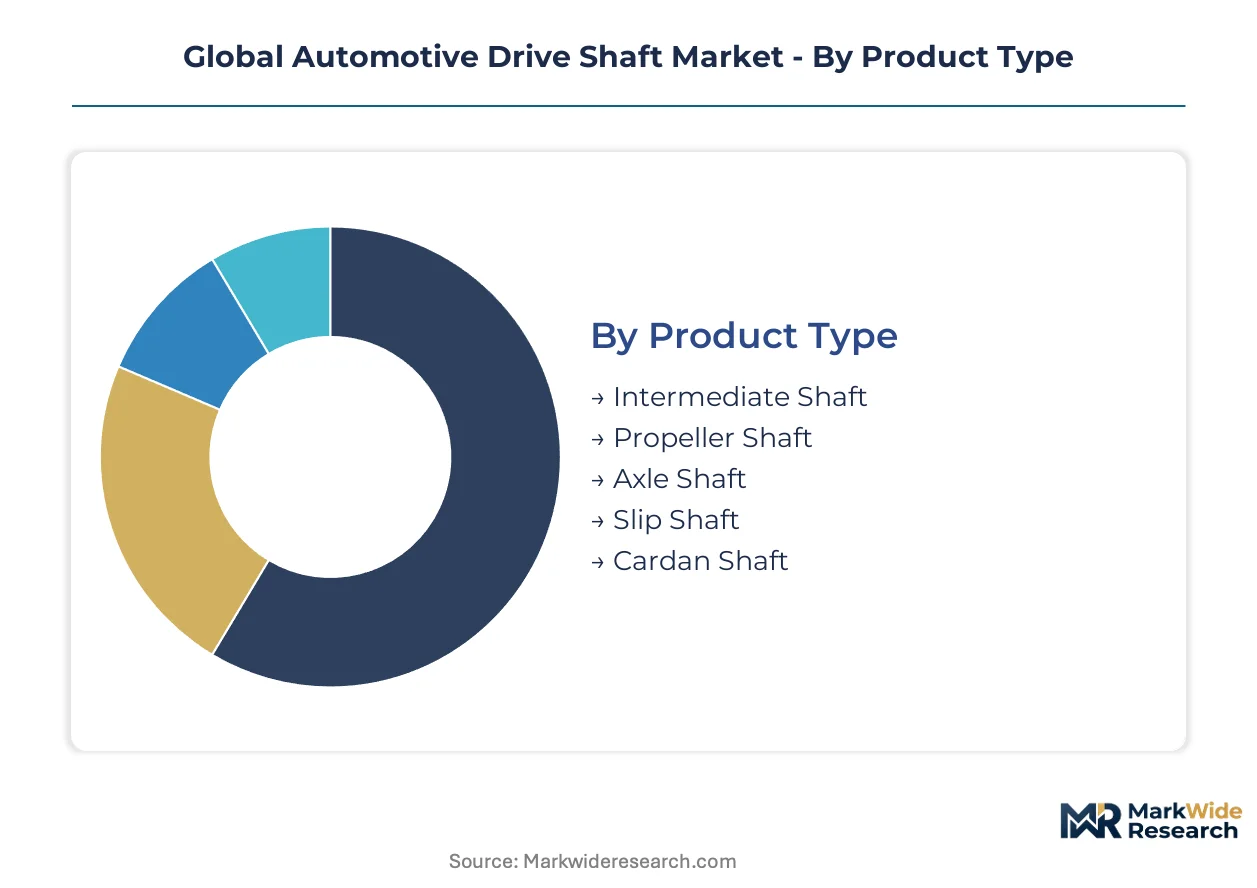
The global automotive drive shaft market is meticulously segmented to reflect the diverse product types, technological advancements, application areas, and end-user demands shaping its evolution. Understanding these distinct segments provides clarity on where innovation is concentrated, how cost structures vary, and which customer groups drive specific component requirements.
Product Type:
The supply chain for automotive drive shafts often concentrates production around specific product types, reflecting specialized manufacturing requirements and material handling expertise.
- Propeller Shaft:This component transmits power between the transmission and the differential, commonly utilized in rear-wheel drive and all-wheel drive vehicles. Demand is particularly high in commercial vehicle manufacturing due to heavy-duty applications and robust power transfer needs.
- Axle Shaft:Connecting the differential to the drive wheels, the axle shaft transfers rotational force to propel the vehicle forward. Global passenger car production drives substantial demand for robust axle shafts, particularly in high-torque electric vehicles.
- Intermediate Shaft:This shaft connects other driveline components, frequently found in front-wheel drive and all-wheel drive systems to bridge distances.
- Slip Shaft:Designed to accommodate changes in length, the slip shaft manages suspension travel and driveline articulation in various vehicle types.
- Cardan Shaft:Utilizing universal joints, the Cardan shaft transmits torque between non-aligned components, commonly employed in commercial and heavy-duty applications.
Propeller Shafts absorb the bulk of installed capacity due to their mature market, while Axle Shafts are expanding most quickly with the rise of electric vehicle platforms.
Technology:
The choice of drive shaft technology directly influences manufacturing cost structures and the performance characteristics delivered to the end vehicle.
- Steel Forging:This process shapes steel through high-pressure operations, yielding drive shafts with high strength and fatigue resistance for conventional powertrains. This method dominates production for cost-sensitive passenger cars and commercial vehicles globally.
- Carbon Fiber:Utilizing lightweight carbon fiber composites, this technology offers superior strength-to-weight ratios and reduced rotational inertia for enhanced vehicle dynamics. High-performance electric vehicle platforms in Europe and China increasingly adopt this technology to improve range.
- Aluminum Alloy:Providing a lighter alternative to steel, aluminum alloy drive shafts balance weight reduction with cost-effectiveness for various vehicle segments.
- Composite Materials:This category encompasses various non-metallic materials engineered for lightweight and specific performance attributes in specialized automotive applications.
- Cold Rolling:A metal forming process that strengthens steel, cold rolling produces drive shafts with improved surface finish and dimensional accuracy for mass production.
Steel Forging remains the foundational technology, while Carbon Fiber is rapidly gaining traction in premium and electric vehicle segments.
Application:
Application segments dictate the volume and design specifications for drive shafts, ranging from high-volume passenger vehicles to specialized industrial equipment.
- Passenger Cars:This segment includes sedans, SUVs, and hatchbacks, requiring drive shafts optimized for efficiency, NVH reduction, and durability in daily use. China's massive automotive manufacturing base drives the largest volume demand for these components.
- Electric Vehicles:Encompassing battery electric vehicles (BEVs) and plug-in hybrids (PHEVs), this application demands drive shafts capable of handling instant torque delivery and novel packaging within e-axle systems. Regulatory mandates in Europe and the US accelerate demand for these specialized components.
- Commercial Vehicles:Covering trucks, buses, and vans, this application requires robust and high-torque drive shafts for heavy-duty operation and prolonged service life.
- Off-Road Vehicles:Including ATVs, UTVs, and specialized utility vehicles, this segment needs durable drive shafts designed for extreme conditions and varied terrain.
- Construction Equipment:Involving heavy machinery like excavators and loaders, this application demands industrial-grade drive shafts for power transmission in demanding work environments.
Passenger Cars represent the largest end-use category, with Electric Vehicles showing the most pronounced expansion.
End User:
End-user segments define distinct procurement patterns and demand profiles for automotive drive shafts, influencing supplier relationships and distribution channels.
- OEMs:Original Equipment Manufacturers integrate drive shafts directly into new vehicle production, demanding high-volume, precision-engineered components that meet specific design and performance criteria. Single-source partnerships are becoming more common among major OEMs in Europe and North America.
- Aftermarket Suppliers:These entities provide replacement drive shafts for vehicle repair and maintenance, focusing on durability, cost-effectiveness, and broad compatibility across various vehicle models. Markets like India and Brazil present significant opportunities due to aging vehicle fleets.
- Vehicle Assemblers:Companies that assemble vehicles from components sourced from various suppliers, often requiring just-in-time delivery of drive shafts.
- Parts Distributors:Wholesalers and retailers that distribute drive shafts to repair shops and individual consumers, managing inventory and logistics.
- Fleet Operators:Businesses managing large numbers of vehicles, procuring drive shafts for maintenance and repair to ensure operational continuity.
OEMs constitute the primary demand segment for new drive shafts, while Aftermarket Suppliers cater to the ongoing service and repair needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for automotive drive shafts is increasingly shaped by electric vehicle architectures and stringent emissions mandates. This shift compels re-evaluation of material science, favoring lightweight composites over traditional steel for powertrain efficiency. Key countries globally are driving this transformation through significant investments and regulatory frameworks.
China
China's substantial state support for its domestic EV industry creates sustained, high-volume demand for advanced driveline components. The MIIT's stringent corporate average fuel consumption and new energy vehicle credit mandates directly incentivize lightweighting. Manufacturing hubs like the Yangtze River Delta are accelerating validation of composite and advanced steel drive shafts.
United States
United States' vehicle efficiency standards from the US EPA compel OEMs to adopt lighter components, including drive shafts, to meet fleet-wide emissions targets. The rapid expansion of battery electric vehicle production requires specifically engineered drive shafts for instant torque delivery. Major automotive manufacturing centers in Michigan are focusing on developing advanced driveline solutions.
Germany
Germany's automotive industry, a global leader in premium vehicles, drives demand for high-performance drive shafts optimized for efficiency. The EU Green Deal mandates accelerate the transition to lighter components across the vehicle fleet. Bavaria and Baden-Württemberg, key automotive regions, are at the forefront of integrating composite materials into powertrain designs.
Japan
Japan's advanced automotive manufacturing base consistently seeks innovation in powertrain components for hybrid and electric vehicles. Policies from METI encourage the development of lightweight materials and efficient vehicle systems. The Kanto region, including Tokyo, remains a central hub for automotive R&D and component manufacturing.
India
India's growing automotive market, coupled with an aging vehicle parc, presents opportunities for both new vehicle components and aftermarket expansion. The PLI scheme for automotive components incentivizes local manufacturing and technological upgrades. Chennai, a prominent automotive manufacturing cluster, is seeing increased activity in driveline component production.
Global Automotive Drive Shaft Market Key Industry Players
Strategic partnerships dominate the current competitive landscape for automotive drive shafts, driven by a pronounced shift towards integrated drivetrain systems. The market exhibits a tiered structure, with large Tier-1 suppliers increasingly providing complete e-axle solutions to major OEMs. Archetypes include global integrated system providers, specialized component manufacturers, and emerging composite material innovators focused on lightweighting. Companies are actively pursuing technology licensing and strategic geographic expansion to secure market share and meet evolving design requirements.
Within the integrated drivetrain systems segment, GKN Automotive exemplifies a global manufacturing footprint with deep R&D in eDrive systems, serving major OEMs. Dana Incorporated occupies a position as a specialist in complete driveline solutions for diverse powertrains, including complex electric architectures for both conventional and new energy vehicles. Schaeffler AG anchors the high-precision components and integrated bearing solutions archetype, providing critical expertise for modern axle systems across various vehicle platforms. These companies represent the shift towards single-source partnerships, where suppliers provide fully engineered and validated systems rather than individual components. Their capabilities align with the increasing demand for integrated solutions in the evolving automotive landscape.
| Leading Market Players |
|---|
| GKN Automotive |
| Dana Incorporated |
| American Axle & Manufacturing, Inc. |
| JTEKT Corporation |
| Hyundai Wia Corporation |
| Neapco Holdings LLC |
| Schaeffler AG |
| NTN Corporation |
| BorgWarner Inc. |
Cost & Logistics Intelligence
Family-owned mid-cap specialists and private equity-backed component manufacturers influence supply behavior, directly impacting pricing discipline across the automotive drive shaft market. Supply concentrations in key manufacturing regions dictate material flow and cost structures for global OEMs.
Pricing Analysis
Volume-driven segments command lower margins, while performance-oriented applications allow for premium pricing in the automotive drive shaft market. The dominant pricing structure remains per-unit transactional, heavily influenced by long-term contract-based offtake agreements with major OEMs. Price differentiation stems from material quality grade, such as carbon fiber composites versus steel, and the level of customization required for specific vehicle platforms. Pricing pressure stems from input price volatility for specialty steel and aluminum alloys, particularly affecting high-volume segments. Passenger car manufacturers exhibit the highest price sensitivity, whereas premium electric vehicle OEMs prioritize performance over marginal cost savings.
Supply Chain Analysis
Workforce availability in manufacturing hubs across China, Germany, and Mexico significantly influences the global automotive drive shaft supply chain. The supply chain draws from critical raw materials including high-strength steel, aluminum alloys, and carbon fiber precursors. A structural risk involves the capital expenditure required to retool production lines from traditional steel manufacturing to advanced composite materials at scale. Distribution runs through a dual model, with direct supply lines to OEMs for new vehicle production and a robust aftermarket channel for replacement parts, particularly in markets like India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race, with players actively pursuing in-house production capabilities for advanced composite materials to secure competitive advantages.
For Market Incumbents:Deepen R&D investment into advanced material science for lightweight composites, particularly for high-torque electric vehicle applications. Expand manufacturing footprints in high-growth EV markets like China to mitigate regional supply chain risks. Secure long-term supply agreements for critical raw materials to counter input price volatility. Focus on integrating sensor technology into drive shafts, transforming them into smart components for predictive maintenance systems, addressing the threat of commoditization.
For New Entrants and Emerging Players:Capture specialized niches by focusing on innovative composite material solutions for emerging electric vehicle segments, such as light commercial EVs and all-wheel-drive configurations. The most penetrable segment remains high-performance electric vehicles, where OEMs prioritize weight reduction and instant torque management. A targeted go-to-market angle involves offering fully validated, pre-engineered e-axle components to smaller, agile EV manufacturers seeking complete drivetrain solutions.
For Investors and Strategic Acquirers:Distressed-cycle entries favor mid-cap specialists with strong intellectual property in composite manufacturing in Europe and North America. The long-term viability of the automotive drive shaft market rests on the ongoing transition to electric vehicles and the demand for lightweight components. An acquisition target archetype includes firms with proven expertise in advanced bonding techniques and NVH management for hollow composite shafts. The signal to watch is the accelerated adoption rate of carbon fiber drive shafts beyond premium segments, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Composite Manufacturing Capacity | This secures proprietary production of lightweight materials critical for EV performance and range, reducing reliance on external suppliers. |
| Expand eDrive System R&D | This enables the development of integrated driveline solutions tailored for electric vehicle architectures, meeting OEM demands for system-level efficiency. |
| Form Strategic Partnerships with OEMs | This ensures long-term supply contracts and co-development opportunities for next-generation drive shaft designs, solidifying market position. |
| Integrate Sensor Technology | This transforms drive shafts into intelligent components, offering value-added data for predictive maintenance and vehicle performance optimization. |
| Target Aftermarket Channels in Emerging Economies | This leverages existing vehicle fleets in regions like India and Brazil, creating new revenue streams for durable and cost-effective replacement components. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational understanding of market sizing and historical trends. Primary research involved interviews with OEM procurement managers, Tier 1 R&D directors, aftermarket distributors, and material science engineers to gather qualitative insights into market dynamics. This study employed a rigorous bottom-up and top-down triangulation approach to validate market figures and ensure data accuracy.
Data-stream reconciliation across various sources informed the analytical framework, projecting market evolution throughout the forecast period. The segmentation dimensions modeled included product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived from a comprehensive analysis of historical growth patterns, regulatory impacts, and projected electric vehicle production targets. Key industry-specific forecast inputs included global EV adoption rates and raw material cost trends for advanced composites.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric vehicle adoption rates and raw material supply disruptions. These forecasts reflect assumptions regarding technological advancements and regulatory stability. Material deviation in global EV production targets or significant shifts in carbon fiber composite pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Reciprocating Engine Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Engine Actuators Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Diesel Engine Management System Market