
 Fuel Cell Powertrain Market | 2026-2036
Fuel Cell Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Powertrain Market Intelligence
ISO 14687 hydrogen fuel quality certification is unwinding competitive access for powertrain suppliers lacking validated fuel compatibility testing. Toyota Motor Corporation leverages its decades of polymer electrolyte membrane R&D to sustain technology leadership in passenger car integrations. Hyundai Motor Company anchors its position through captive production of fuel cell stacks at its dedicated Korean manufacturing complex. Ballard Power Systems specializes in heavy-duty module architectures that dominate North American bus and truck retrofit channels.
A fuel cell powertrain converts hydrogen chemical energy into electrical propulsion through an electrochemical reaction, typically operating at cell voltages of 0.6 to 0.7 volts per cell under load with system efficiencies exceeding 50 percent in optimal conditions. The assembly serves as a zero-emission propulsion alternative for applications where battery weight or recharge duration constrains operational viability. Proton exchange membrane systems lead commercial vehicle deployments due to their cold-start capability and power density advantages, while solid oxide variants occupy stationary and maritime niches where high-grade waste heat recovery improves total system economics. Maritime transport applications represent the fastest-expanding addressable segment as International Maritime Organization decarbonization timelines harden vessel operator procurement criteria.
The EU Green Deal's Alternative Fuels Infrastructure Regulation mandates hydrogen refueling station density targets that directly shape OEM platform rollout schedules across member states. EPA heavy-duty engine certification pathways in the United States now include hydrogen fuel cell provisions that streamline compliance for zero-emission truck portfolios. Japan's METI maintains JIS hydrogen quality standards that gate supply chain qualification for powertrain components destined for domestic vehicle programs. Stakeholders must monitor regulatory synchronization between fuel infrastructure mandates and vehicle certification timelines to avoid deployment mismatches that strand capital in either station networks or idle production capacity.
Market Dynamics
Heavy-duty fleet operators are compressing procurement timelines as EU Green Deal infrastructure mandates harden binding hydrogen station density targets across member states, forcing powertrain suppliers to synchronize stack production capacity with fuel availability curves.
Growth Catalysts
- EU Green Deal AFIR mandates:Binding hydrogen refueling station density targets in Germany, France, and the Netherlands are accelerating OEM platform rollout schedules and validating fleet-scale procurement economics.
- Maritime decarbonization timelines:International Maritime Organization vessel operator criteria are redirecting capital toward fuel cell propulsion for short-sea shipping and port towage applications.
- Platinum loading reduction:Advanced catalyst deposition techniques are compressing membrane electrode assembly costs and extending stack operational life beyond 25,000 hours.
Market Restraints
- Electrolyzer capacity concentration:European alkaline and PEM electrolyzer manufacturing clusters in Germany and Norway are creating hydrogen supply bottlenecks that strand fuel cell vehicle deployments.
- Platinum group metal price volatility:Iridium and platinum spot market fluctuations are destabilizing stack cost forecasts and compressing supplier margins.
- ISO 14687 certification friction:Fuel quality testing validation timelines are gating powertrain supplier qualification and fragmenting procurement pools.
Strategic Opportunities
- India heavy-duty bus procurement:State transport corporation tenders under the National Hydrogen Mission are opening fleet-scale deployment channels without incumbent supplier lock-in.
- Aviation ground support equipment:Airport operator net-zero commitments are creating demand for fuel cell-powered baggage tractors and pushback tugs.
- SOFC-CHP convergence:Solid oxide fuel cell integration with onboard auxiliary power units is enabling waste heat recovery for cabin thermal management in long-haul trucks.
Industry Challenges
- Stack assembly technician scarcity:Precision membrane handling and sealing expertise shortages are constraining manufacturing scale-up across European and Korean production facilities.
- BOP component qualification timelines:Balance of plant subsystem certification under UN ECE R134 is extending vehicle homologation cycles and compressing model-year launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Powertrain Market |
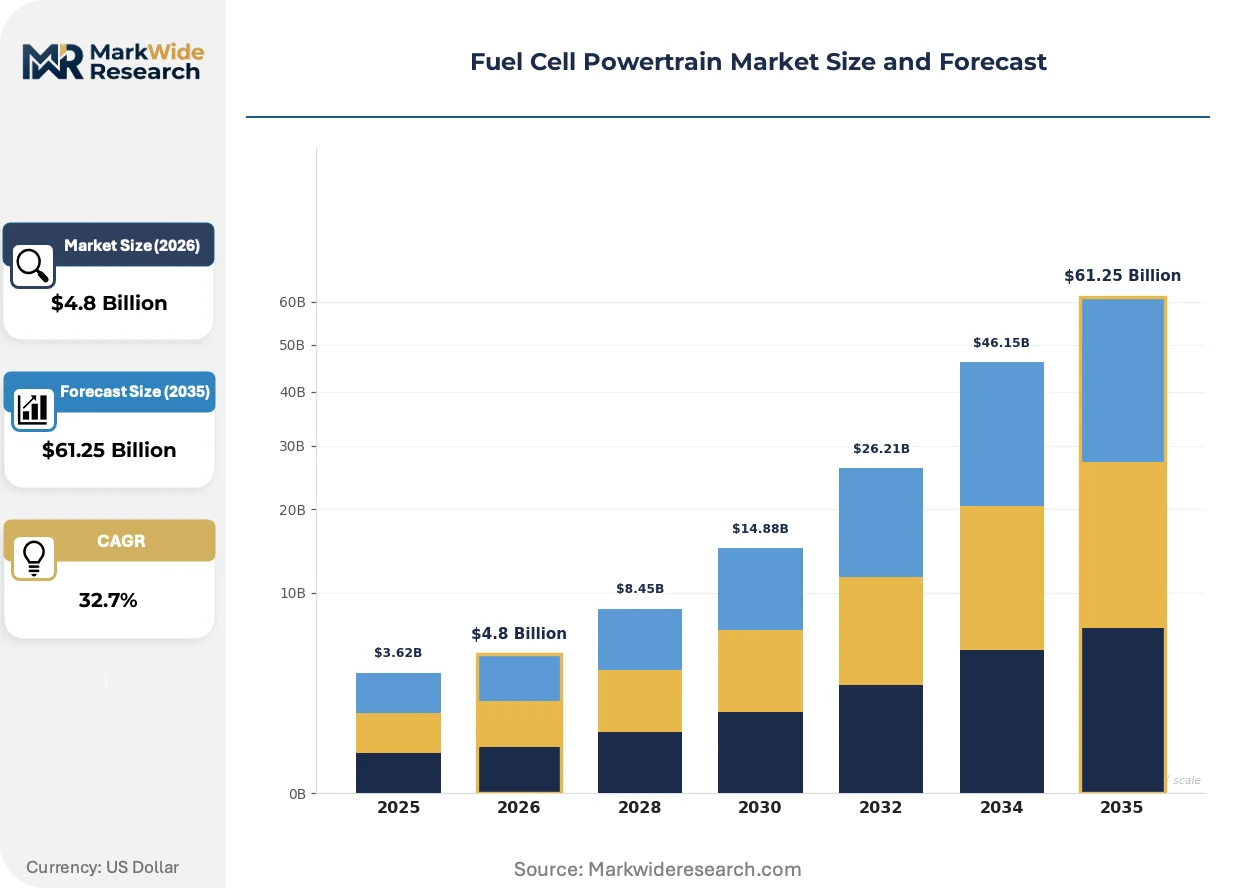
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $61.25 Billion |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid Application: Commercial Vehicles, Passenger Cars, Off-Highway Equipment, Maritime Transport End User: Original Equipment Manufacturers, Fleet Operators, Leasing Companies, Vehicle Assemblers Deployment: Onboard Systems, Stationary Power, Portable Power, Backup Power Solutions, Distributed Generation |
| Companies Covered | Ballard Power Systems, Cummins Inc., Robert Bosch GmbH, Denso Corporation, Toyota Motor Corporation, Hyundai Motor Company, Plug Power Inc., FEV Group, AVL List GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Powertrain Market Strategic Shifts & Innovations
Powertrain architectures are converging toward modular platform designs that decouple fuel cell stack scaling from balance of plant integration, enabling faster configuration across vehicle weight classes.
High-temperature proton exchange membrane technology is miniaturizing thermal management hardware requirements while maintaining 120°C operational ceilings. Commercial vehicle OEMs in Germany and Japan are adopting these systems for cold-start reliability in Nordic climates. The technology is compressing packaging volume by 40 percent compared to liquid-cooled alternatives, freeing chassis space for hydrogen storage.
EPA heavy-duty engine certification pathways now include hydrogen fuel cell provisions that streamline zero-emission truck compliance documentation. This regulatory accommodation is reducing engineering validation costs for North American Class 8 truck programs. Fleet operators in California and Texas are leveraging this pathway to accelerate CARB Advanced Clean Trucks mandate compliance.
Long-term hydrogen supply agreements are displacing spot procurement for fleet operators with 500-plus vehicle deployments. Logistics operators in the Rhine-Alpine corridor are signing 10-year offtake contracts with electrolyzer developers, locking fuel pricing and securing priority dispensing access. This contracting pattern is most visible among German chemical transport fleets serving BASF and Covestro production sites.
Fuel Cell Powertrain Market Segmentation
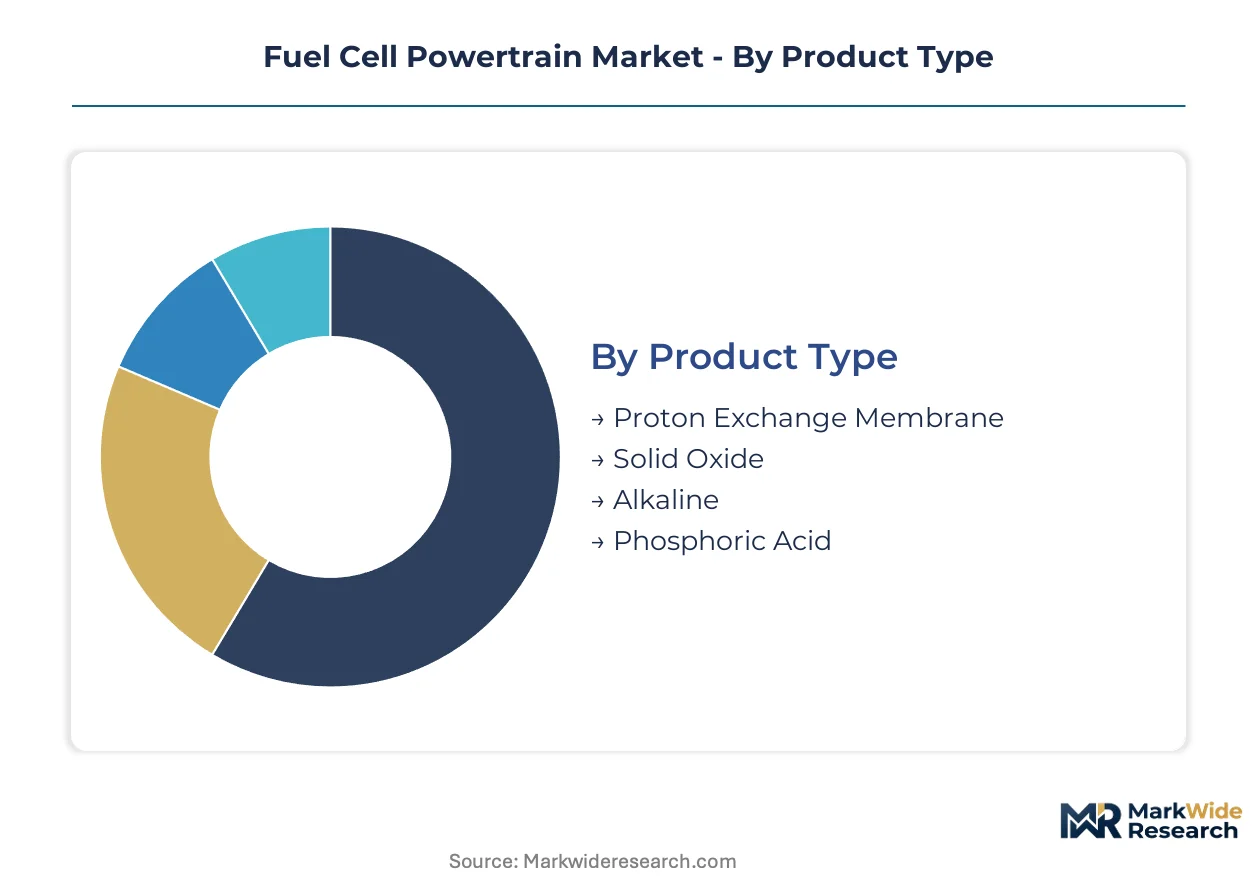
Segmentation in fuel cell powertrains reveals how technology characteristics dictate channel economics. Proton exchange membrane systems flow through OEM direct procurement, while solid oxide variants concentrate in stationary and maritime retrofit channels where waste heat recovery justifies higher capital outlays.
Product Type:
Channel economics diverge sharply across chemistries, with membrane-based systems dominating vehicle OEM supply chains and high-temperature variants capturing industrial energy service contracts.
- Proton Exchange Membrane:Polymer electrolyte architecture operates at 60-80°C with cold-start capability below freezing. Demand concentrates in German and Korean passenger car programs where METI and KBA certification pathways validate fleet deployment. Platinum loading reductions below 0.3g/kW are compressing stack costs for heavy-duty truck integrations.
- Solid Oxide:Ceramic electrolyte systems achieve 600-1000°C operating temperatures enabling combined heat and power output. Maritime operators in the Rhine-Alpine corridor are procuring these for short-sea vessels where exhaust heat drives auxiliary systems. SOFC-CHP convergence in long-haul trucks is recovering waste heat for cabin thermal management.
- Alkaline:Liquid electrolyte configurations use non-precious metal catalysts, lowering material cost exposure to platinum group metal volatility. Stationary power developers in Norway deploy these for grid-scale buffering.
- Phosphoric Acid:Molten phosphoric acid electrolyte delivers 40-45% electrical efficiency with established operational track records exceeding 40,000 hours. Distributed generation operators in Japan leverage these for commercial building baseload power.
By volume, proton exchange membrane leads. By growth pace, solid oxide is expanding most quickly in maritime applications.
Application:
Application mix reflects payload and duty cycle constraints that battery alternatives cannot satisfy, with procurement timelines compressing fastest where regulatory mandates harden first.
- Commercial Vehicles:Class 8 trucks and urban buses dominate North American and European fleet procurement under EPA and EU Green Deal compliance pathways. CARB Advanced Clean Trucks mandates in California are accelerating powertrain validation cycles for regional haul operators.
- Passenger Cars:Light-duty integrations concentrate in Japanese and Korean markets where METI hydrogen station subsidies and domestic OEM captive production sustain deployment. Toyota and Hyundai anchor volume through dedicated manufacturing complexes.
- Off-Highway Equipment:Mining trucks and construction machinery in Australia's Pilbara region are testing fuel cell retrofits where diesel remoteness premiums exceed hydrogen logistics costs.
- Maritime Transport:Port towage and short-sea shipping represent the steepest expansion trajectory as International Maritime Organization decarbonization timelines harden vessel operator procurement criteria. German chemical transport fleets serving BASF and Covestro sites are signing 10-year hydrogen offtake contracts to secure fuel availability.
Commercial vehicles capture current procurement volume. Maritime transport is gaining share fastest as regulatory deadlines approach.
End User:
Customer type determines contract structure, with fleet operators locking long-term hydrogen supply agreements while OEMs concentrate stack production in captive facilities.
- Original Equipment Manufacturers:Hyundai, Toyota, and Daimler Truck maintain in-house fuel cell stack assembly to protect membrane electrode assembly know-how and compress balance of plant integration cycles.
- Fleet Operators:Logistics operators with 500-plus vehicle deployments are displacing spot procurement with 10-year hydrogen offtake contracts. Rhine-Alpine corridor operators prioritize dispensing access through electrolyzer developer partnerships.
- Leasing Companies:Asset financiers are developing residual value models for fuel cell trucks that account for stack degradation curves and second-life stationary applications.
- Vehicle Assemblers:Contract manufacturers without captive fuel cell capability source modular powertrain skids from Ballard and Bosch for chassis integration under UN ECE R134 certification.
Fleet operators drive volume commitment. OEMs concentrate value capture through backward integration into stack production.
Deployment:
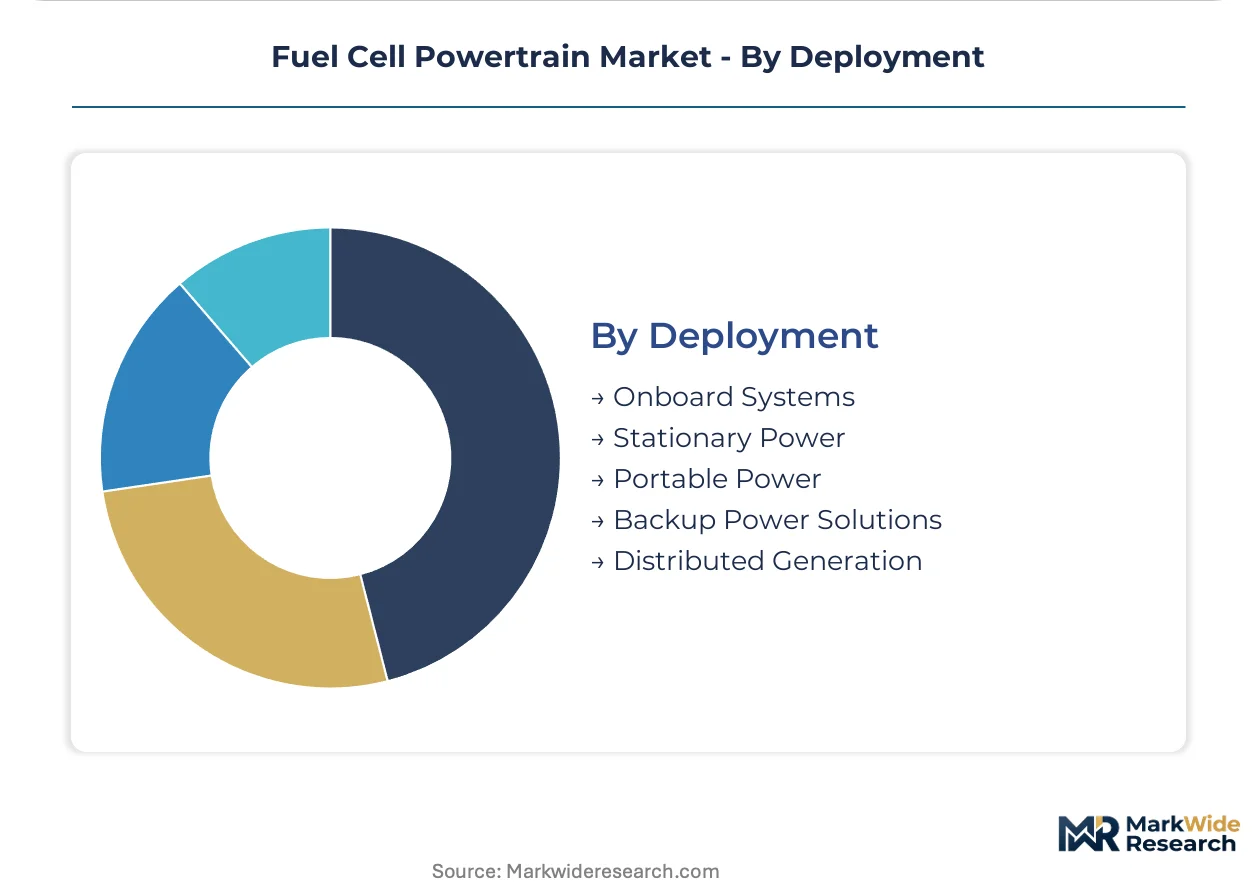
Deployment mode reflects mobility versus stationary tradeoffs, with onboard systems requiring packaging miniaturization and stationary applications optimizing for thermal integration.
- Onboard Systems:Vehicle-integrated powertrains demand 40% packaging volume reduction through high-temperature PEM advances that eliminate liquid cooling hardware. German OEMs are adopting these for Nordic cold-start reliability.
- Stationary Power:Grid-connected fuel cell installations at industrial clusters in Germany's Rhineland co-locate with electrolyzer capacity to minimize hydrogen distribution costs.
- Portable Power:Military and emergency response units deploy containerized systems where diesel supply lines are contested.
- Backup Power Solutions:Data center operators in Japan integrate fuel cells for uninterrupted power supply, leveraging METI subsidies for hydrogen infrastructure.
- Distributed Generation:Building-scale systems in commercial districts combine electricity and heat output, improving total system economics through thermal energy recovery.
Onboard systems dominate capital deployment. Stationary power is climbing the fastest as industrial cluster co-location models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Alpine hydrogen pipeline corridor anchors European fuel cell powertrain deployment, connecting Rotterdam port hydrogen imports to industrial clusters along the Rhine River.
United States
California's CARB Advanced Clean Trucks mandate accelerates Class 8 truck powertrain validation cycles. EPA heavy-duty engine certification pathways now include hydrogen fuel cell provisions that streamline zero-emission compliance documentation. Fleet operators in the Texas triangle leverage these pathways to scale regional haul deployments.
Germany
Heavy-duty commercial vehicle fleets scale hydrogen procurement contracts under EU Green Deal AFIR infrastructure mandates. KBA certification pathways validate stack qualification for domestic OEM programs. The Rhineland industrial cluster co-locates electrolyzer and fuel cell assembly capacity between chemical producers and automotive suppliers.
Japan
METI hydrogen station subsidies sustain light-duty passenger car deployment through dedicated manufacturing complexes. JIS hydrogen quality standards gate supply chain qualification for powertrain components destined for domestic vehicle programs. The Nagoya-Tokyo corridor concentrates membrane electrode assembly R&D and captive stack production.
South Korea
Hyundai Motor Company's dedicated Korean manufacturing complex anchors captive fuel cell stack production for heavy-duty and passenger applications. MFDS regulatory alignment with UN ECE R134 accelerates vehicle homologation cycles. The Ulsan-Busan industrial zone integrates electrolyzer capacity with port hydrogen logistics for maritime transport trials.
China
MIIT dual carbon goals redirect state-owned fleet procurement toward fuel cell buses and trucks in Beijing-Tianjin-Hebei. GB standards for hydrogen fuel quality create certification pathways for domestic powertrain suppliers. The Yangtze River Delta concentrates balance of plant component manufacturing for modular platform exports.
Fuel Cell Powertrain Market Key Industry Players
Listed leaders compete with private specialists across technology integration depth, with publicly traded stack manufacturers facing privately held engineering consultancies and captive OEM production facilities. Market structure tilts toward vertical concentration as automakers with in-house membrane electrode assembly capability capture value upstream. Three archetypes dominate: integrated automotive OEMs with captive fuel cell divisions, independent stack specialists supplying modular skids, and engineering service providers certifying balance of plant integration. Competitive moves center on backward integration into catalyst deposition and strategic partnerships locking long-term hydrogen offtake agreements.
Within the captive production tier, Toyota Motor Corporation and Hyundai Motor Corporation exemplify automakers that have consolidated stack manufacturing within dedicated complexes. Ballard Power Systems occupies a position among independent specialists supplying heavy-duty module architectures. These three anchors illustrate how geographic concentration of electrolyzer capacity in Germany and Korea shapes supplier qualification requirements and procurement pool fragmentation.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Cummins Inc. |
| Robert Bosch GmbH |
| Denso Corporation |
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Plug Power Inc. |
| FEV Group |
| AVL List GmbH |
| Others |
Cost & Logistics Intelligence
Long-term hydrogen offtake contracts between Rhine-Alpine logistics operators and electrolyzer developers lock in both supply access and price visibility, compressing spot market exposure for fleet-scale deployments while binding capital to fuel availability curves under EU Green Deal mandates.
Pricing Analysis
Certification level under ISO 14687 creates the primary spread between qualified and unqualified powertrain suppliers, with validated fuel compatibility testing gating procurement pool access. Three-tier pricing structure across OEM-integrated, modular skid, and retrofit aftermarket channels reflects membrane electrode assembly know-how concentration. Cost compression in heavy-duty modules is intensifying because platinum group metal spot volatility destabilizes stack cost forecasts. Fleet operators with 500-plus vehicle deployments exhibit lowest price sensitivity due to locked offtake contracts, while regional bus tenders show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Platinum and iridium sourcing from South Africa and Russia anchors membrane electrode assembly cost structures, with ceramic electrolyte supply from Japan and Germany feeding solid oxide stack production. The supply chain draws from German and Korean electrolyzer manufacturing clusters for hydrogen feedstock, with balance of plant components concentrated in China's Yangtze River Delta. Single-source vulnerability in iridium refining creates exposure to export restriction shocks. Distribution runs through OEM captive facilities for passenger car programs and modular skid suppliers for heavy-duty retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell powertrain procurement is recovering from electrolyzer capacity bottlenecks as European alkaline and PEM manufacturing clusters scale, with fleet operator contract velocity serving as the cyclical inflection signal.
For Market Incumbents: Consolidate membrane electrode assembly capability through backward integration into catalyst deposition, protecting stack cost structures from platinum group metal volatility. Lock long-term hydrogen offtake partnerships with electrolyzer developers in Germany and Norway to secure priority dispensing access before AFIR station density targets harden procurement timelines. Add precision sealing technician training capacity in Korean and European production facilities to relieve assembly bottlenecks constraining manufacturing scale-up. For New Entrants and Emerging Players: Aftermarket retrofit certification gaps in India's National Hydrogen Mission bus tenders create white-space entry channels without incumbent supplier lock-in. Aviation ground support equipment at European airport operators offers penetrable demand for fuel cell-powered baggage tractors where net-zero commitments outpace OEM platform availability. Pursue modular skid partnerships with established balance of plant component manufacturers to compress UN ECE R134 homologation cycles. For Investors and Strategic Acquirers: Independent stack specialists with heavy-duty module architectures and validated EPA certification pathways represent acquisition targets with defensible positioning in North American truck retrofit channels. Long-term viability over the five-to-ten year horizon rests on hydrogen supply contract duration and electrolyzer developer partnerships. Watch fleet operator procurement acceleration in the Rhine-Alpine corridor as the signal for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Hydrogen Offtake Agreement | Rhine-Alpine logistics operators secure priority dispensing access under EU Green Deal AFIR mandates. |
| Backward Integration into Catalyst Deposition | Stack manufacturers compress platinum loading costs and extend operational life beyond 25,000 hours. |
| High-temperature PEM Platform Adoption | German OEMs eliminate liquid cooling hardware to free chassis space for hydrogen storage. |
| SOFC-CHP Convergence Development | Long-haul truck operators recover waste heat for cabin thermal management in Nordic climates. |
| ISO 14687 Certification Investment | Powertrain suppliers unlock procurement pool access previously gated by fuel quality validation timelines. |
Research Approach
Operator-level perspectives from fleet procurement directors, OEM platform engineers, electrolyzer project developers, and membrane electrode assembly technicians anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from EPA certification filings, EU AFIR implementation reports, METI hydrogen station subsidy disclosures, and customs trade data for platinum group metal flows. Bottom-up stack production capacity estimates and top-down fleet deployment projections were triangulated to reconcile supply and demand trajectories.
Sensitivity analysis across hydrogen price assumptions, platinum spot volatility bands, and electrolyzer capacity buildout schedules shaped the analytical framework. Segmentation dimensions modeled include fuel cell chemistry type, vehicle application class, deployment mode, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs incorporated KBA and MFDS homologation cycle timelines and CARB Advanced Clean Trucks mandate compliance deadlines.
Forecasts assume regulatory continuity in EU Green Deal AFIR implementation, EPA heavy-duty engine certification pathways, and METI hydrogen infrastructure subsidies; material policy shifts would require re-modeling deployment timelines and procurement economics. Scenario risks include electrolyzer supply bottlenecks stranding vehicle deployments and ISO 14687 certification friction fragmenting supplier qualification pools. Practitioners should keep alternative scenarios live as hydrogen station density buildout and platinum group metal supply chain conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Gear Reduction Starter Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Modular Belt Drive Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Reciprocating Engine Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Engine Rocker Arm Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Electric Powertrain Systems Market