
 Asia-Pacific Torque Vectoring Market | 2026-2036
Asia-Pacific Torque Vectoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Torque Vectoring Market Insights
Automotive-grade precision torque allocation is redrawing supplier hierarchies across the Asia-Pacific Torque Vectoring Market. BorgWarner Inc. leverages its clutch-based vectoring portfolio to anchor high-volume programs with Korean and Chinese OEMs. GKN Automotive dominates eDrive integration, while ZF Friedrichshafen AG positions its modular actuator platforms for scalable deployment across multiple vehicle architectures.
Torque vectoring denotes the differential distribution of rotational force across individual wheels to enhance traction, stability, and cornering agility through electromechanical or hydraulic actuation systems operating at response thresholds below 100 milliseconds. Active Torque Vectoring commands premium positioning due to real-time computational control, whereas Electronic Torque Vectoring scales efficiently for mass-market electric vehicle platforms. All-Wheel Drive technology leads volume deployment, though Hybrid Drive configurations are gaining fastest as electrified powertrains proliferate across Japanese and Chinese assembly lines.
China's MIIT enforces GB standards for electric vehicle stability control that implicitly mandate torque vectoring capability on premium battery-electric platforms. Japan's METI coordinates with JIS standards bodies to validate next-generation chassis dynamics systems for export certification. India's BIS is drafting automotive safety protocols that will require yaw-moment intervention on vehicles above specified gross weight thresholds. Stakeholders must calibrate R&D roadmaps against divergent national homologation timelines rather than assuming regulatory convergence.
Market Dynamics
Electrification of automotive platforms across China, Japan, and South Korea is forcing a wholesale redesign of chassis control architectures, with torque vectoring systems migrating from mechanical differentials to software-defined electromechanical actuators.
Growth Catalysts
- China MIIT GB Standards:Implicit stability control mandates on premium battery-electric platforms require active torque vectoring capability, creating pull-through demand for electromechanical actuator systems.
- India BIS Safety Mandates:Draft automotive safety protocols will require yaw-moment intervention on vehicles above specified gross weight thresholds, expanding addressable market for vectoring hardware.
- Hybrid Drive Proliferation:Electrified powertrains across Japanese and Chinese assembly lines demand integrated torque management solutions that mechanical systems cannot provide.
Market Restraints
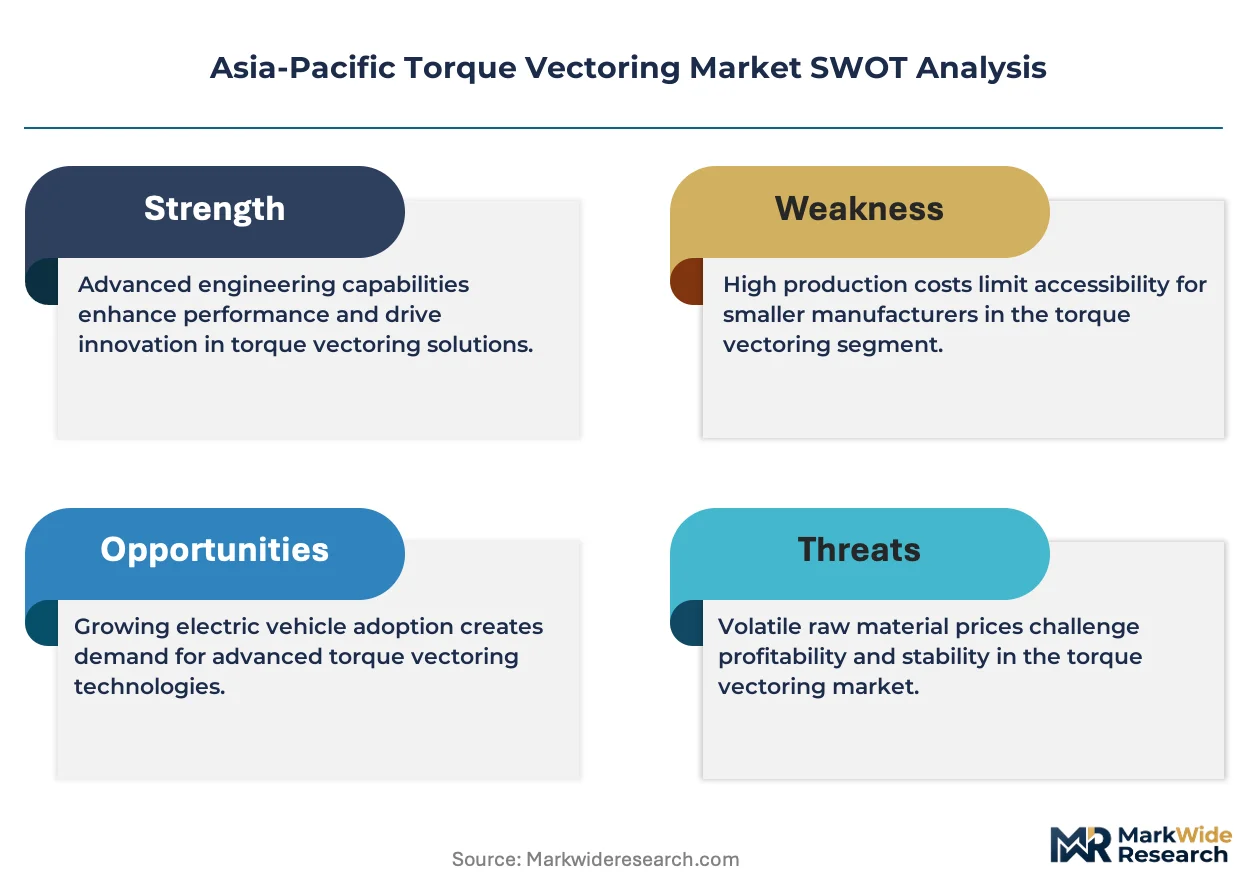
- Rare Earth Magnet Volatility:Neodymium and dysprosium price instability constrains permanent magnet motor production for eDrive-integrated vectoring modules.
- Supplier Concentration in Jiangsu-Zhejiang:Over 60% of precision actuator manufacturing clusters in eastern China create single-region vulnerability for OEM supply security.
- Thermal Management Limitations:Current silicon-based power electronics face sustained load degradation in tropical climates, limiting deployment latitude.
Strategic Opportunities
- India Commercial Vehicle Segment:Underpenetrated heavy-duty truck and bus categories present first-mover advantage for yaw-control retrofit systems ahead of BIS enforcement.
- Software-Defined Vehicle Convergence:Integration of torque vectoring algorithms with central compute platforms enables over-the-air calibration updates and feature monetization.
- Japan METI Export Certification:Coordinated JIS validation protocols for chassis dynamics systems streamline homologation for suppliers targeting ASEAN markets.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of engineers proficient in real-time control algorithms and functional safety (ISO 26262) extends development timelines.
- Homologation Timeline Fragmentation:Divergent national certification schedules across China, Japan, India, and South Korea force redundant testing cycles.
- Legacy Powertrain Integration Complexity:Retrofitting active vectoring to internal combustion platforms requires fundamental suspension geometry redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Torque Vectoring Market |
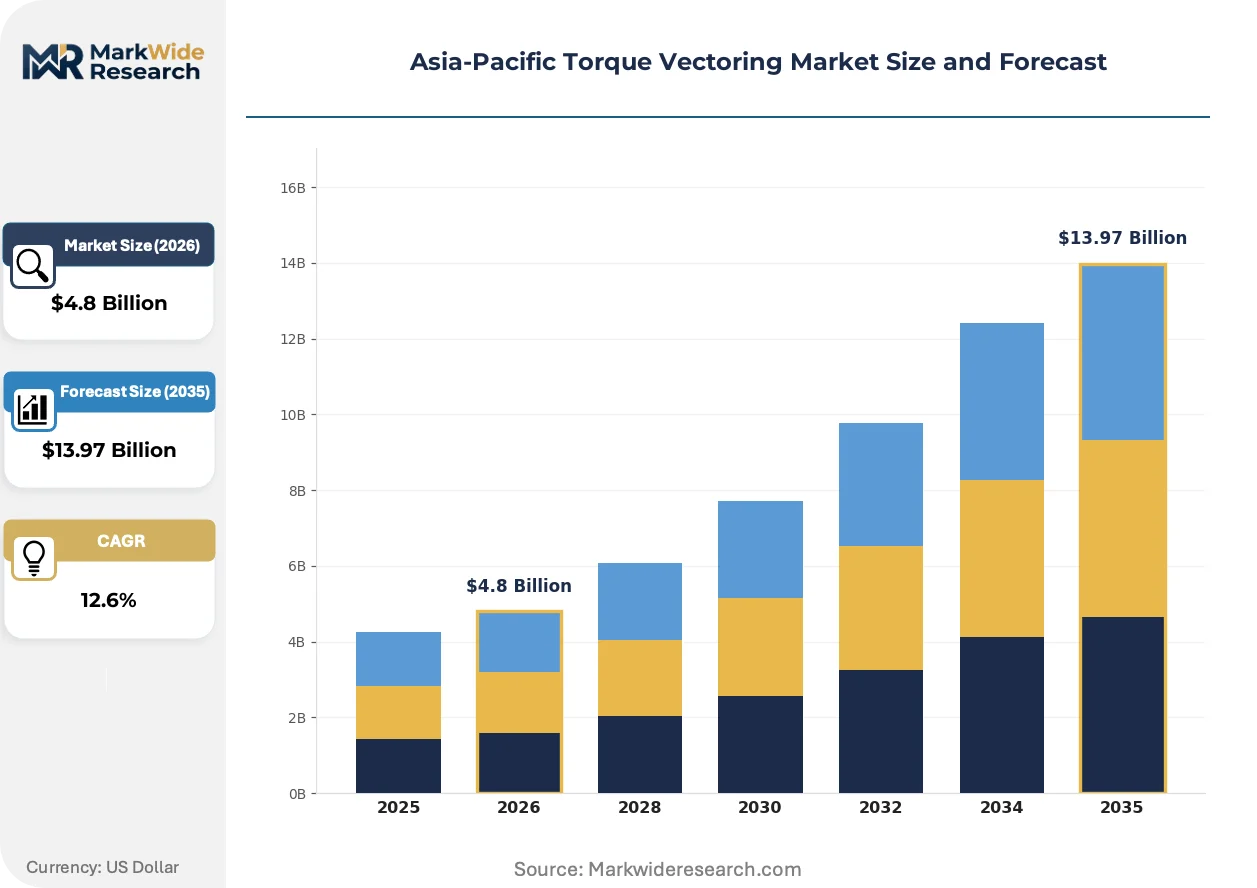
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Torque Vectoring, Passive Torque Vectoring, Electronic Torque Vectoring, Mechanical Torque Vectoring Technology: All-Wheel Drive, Front-Wheel Drive, Rear-Wheel Drive, Hybrid Drive End User: Passenger Vehicles, Commercial Vehicles, Performance Vehicles, Electric Vehicles Application: Off-Road Applications, On-Road Applications, Racing Applications, Fleet Management |
| Companies Covered | BorgWarner Inc., GKN Automotive, ZF Friedrichshafen AG, Aisin Corporation, JTEKT Corporation, Magna International Inc., Dana Incorporated, Hyundai Mobis, Hitachi Astemo, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Torque Vectoring Market Trends and Innovations
Software-defined chassis control is redrawing competitive boundaries in the Asia-Pacific Torque Vectoring Market, with algorithmic differentiation displacing hardware supremacy as the primary value driver.
Electromechanical actuator architectures are decomposing the traditional mechanical differential into modular motor-inverter-gearbox units. Chinese battery-electric OEMs are adopting these systems at production scale for 2026-2027 model year platforms. This decomposition enables suppliers to decouple hardware from control logic, compressing development cycles and allowing tier-one electronics manufacturers to enter chassis systems previously dominated by driveline specialists.
METI's coordination with JIS standards bodies is accelerating validation protocols for next-generation chassis dynamics systems. The industrial consequence is shortened export certification timelines for Japanese suppliers targeting ASEAN markets. Premium battery-electric platforms are responding by front-loading vectoring system integration into platform architecture decisions rather than treating it as a tier-two component selection.
Fleet procurement managers are consolidating chassis system sourcing decisions at the platform level rather than the component level. This concentrates specification authority with a smaller cohort of vehicle architecture engineers and displaces traditional tier-two supplier relationships. The shift is most visible in China's Jiangsu and Zhejiang manufacturing clusters, where vertical OEM integration into torque management software is accelerating.
Asia-Pacific Torque Vectoring Market Segmentation
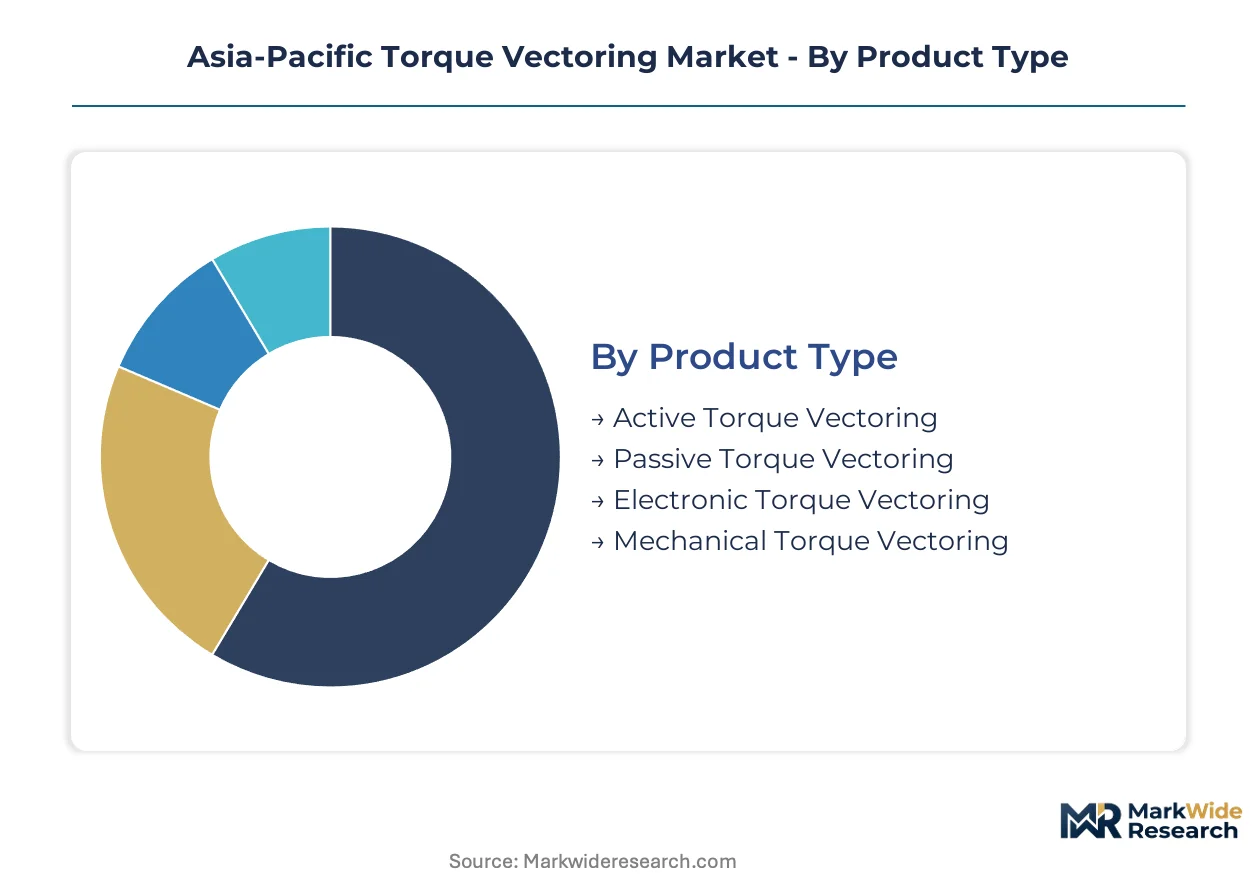
Asia-Pacific torque vectoring architectures fragment across electromechanical sophistication levels, drivetrain configurations, and regulatory compliance tiers. Segment boundaries increasingly blur as Chinese EV platforms integrate software-defined control modules that span multiple traditional categories.
Product Type:
China's MIIT GB standards enforce stability control thresholds that privilege real-time computational systems over passive mechanical differentials, reshaping procurement specifications across the region.
- Active Torque Vectoring:Electromechanical actuators distribute rotational force across individual wheels through sub-100-millisecond response protocols. Premium battery-electric platforms from Jiangsu and Zhejiang manufacturing clusters specify these systems to satisfy implicit MIIT mandates for yaw-moment intervention.
- Electronic Torque Vectoring:Brake-based torque redistribution leverages existing ESC hardware without dedicated differentials, enabling cost-efficient deployment across mass-market Chinese EV platforms where hardware minimization drives platform economics.
- Passive Torque Vectoring:Mechanical limited-slip differentials operate without electronic oversight, retaining relevance in India's commercial vehicle retrofit market ahead of BIS enforcement timelines.
- Mechanical Torque Vectoring:Traditional clutch-pack or Torsen differentials persist in legacy internal combustion platforms across Southeast Asian assembly lines with limited electrification penetration.
Established volume favors Electronic Torque Vectoring; emerging adoption favors Active Torque Vectoring.
Technology:
Cost tier stratification separates hardware-intensive AWD systems from software-leveraged hybrid configurations that exploit electrified powertrain architectures.
- All-Wheel Drive:Full-time torque distribution across four wheels dominates volume deployment in Japanese and Korean premium SUVs, though silicon-based power electronics face thermal degradation thresholds in tropical ASEAN climates.
- Hybrid Drive:Dual-motor electrified architectures enable software-defined torque allocation without mechanical differentials, climbing the fastest as Chinese OEMs front-load vectoring integration into platform decisions.
- Front-Wheel Drive:Brake-based vectoring solutions address traction limitations in compact passenger vehicles across India's cost-sensitive market segments.
- Rear-Wheel Drive:Performance-oriented configurations concentrate in Japan's domestic sports car segment and Chinese premium EV coupes targeting METI export certification pathways.
Volume concentration anchors All-Wheel Drive; technology transition accelerates Hybrid Drive.
End User:
Application maturity separates saturated passenger vehicle specifications from underpenetrated commercial vehicle categories where retrofit demand precedes regulatory deadlines.
- Passenger Vehicles:Mid-size SUVs and sedans across China, Japan, and South Korea specify torque vectoring as standard equipment on platforms above defined price thresholds, with feature penetration expanding downward through model line refreshes.
- Electric Vehicles:Battery-electric platforms mandate integrated torque management to optimize dual-motor efficiency and regenerative braking coordination, with Chinese OEMs driving specification intensity through vertical software integration.
- Commercial Vehicles:Heavy-duty trucks and buses in India present first-mover retrofit opportunities ahead of BIS yaw-control mandates for vehicles above gross weight thresholds.
- Performance Vehicles:Domestic Japanese sports cars and Chinese premium EV coupes specify high-bandwidth active systems for track-capable dynamics certification.
Current specification density peaks in Passenger Vehicles; regulatory pressure builds fastest in Commercial Vehicles.
Application:
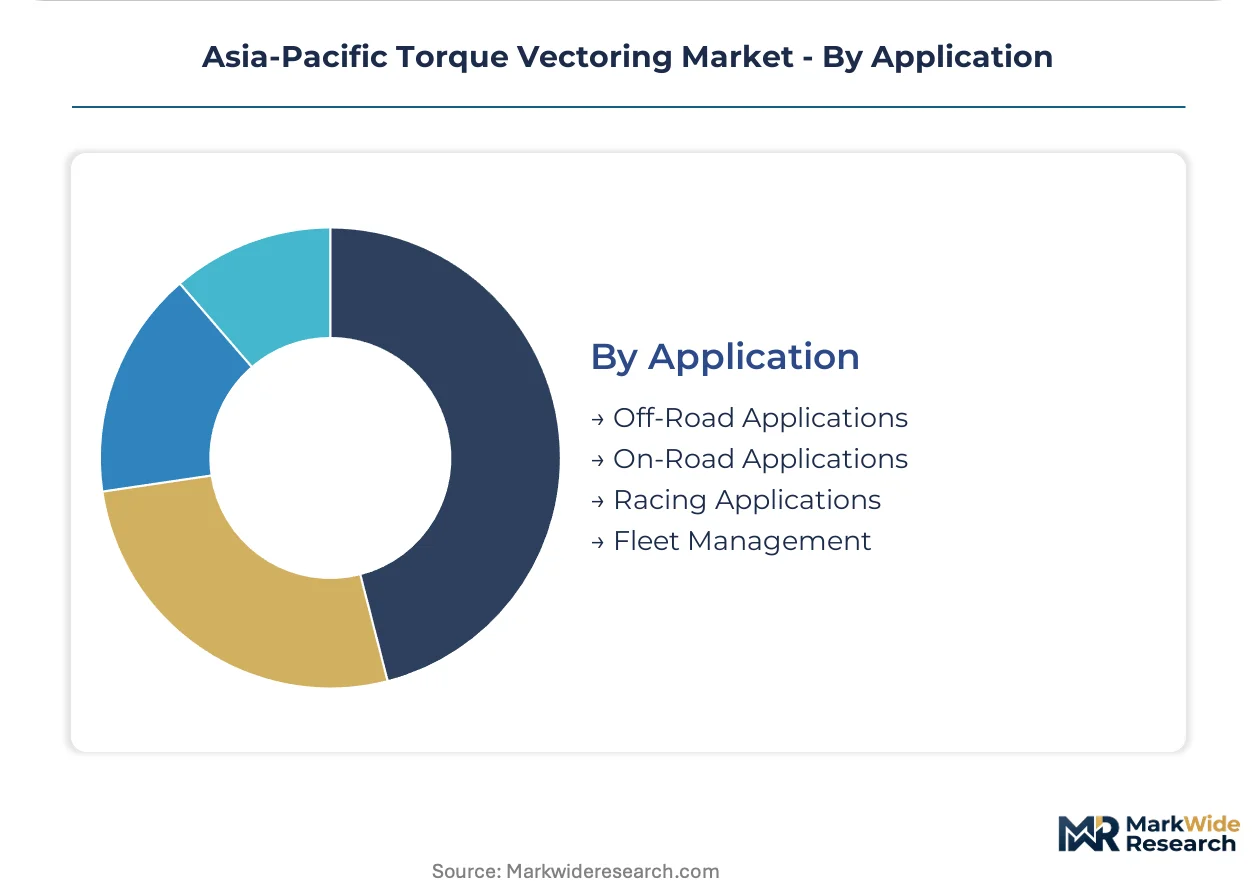
Customer type fragmentation separates fleet procurement consolidation from individual owner performance preferences, with fleet managers increasingly specifying chassis systems at platform level rather than component tier.
- On-Road Applications:Highway stability and lane-change confidence drive specification in Chinese premium sedans and Korean executive vehicles, with urban congestion algorithms optimizing low-speed maneuverability.
- Fleet Management:Logistics operators across China's Jiangsu-Zhejiang corridor consolidate chassis sourcing decisions to reduce maintenance variance and standardize driver training protocols across mixed vehicle pools.
- Off-Road Applications:Agricultural and construction vehicles in India's hinterland specify mechanical differentials pending BIS electrification timelines.
- Racing Applications:Domestic Japanese motorsport series validate prototype systems for subsequent METI-coordinated export certification to ASEAN markets.
Procurement rationalization concentrates in Fleet Management; technology validation concentrates in Racing Applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across the Asia-Pacific Torque Vectoring Market. Indian commercial vehicle buyers demand yaw-control retrofit systems at minimal hardware cost, while Chinese premium EV platforms absorb full active vectoring suites without margin compression.
China
MIIT GB standards implicitly mandate stability control capability on battery-electric platforms above defined price thresholds. The Yangtze River Delta manufacturing corridor concentrates over sixty percent of precision actuator production, with Jiangsu and Zhejiang provinces hosting integrated motor-inverter-gearbox assembly for 2026-2027 model year vehicles.
Japan
METI coordinates with JIS standards bodies to validate chassis dynamics systems for ASEAN export certification. Kanto region engineering centers prototype high-bandwidth active systems for domestic sports car programs, while Osaka-based suppliers streamline homologation timelines for Thai and Indonesian assembly integration.
India
BIS safety protocols will require yaw-moment intervention on heavy-duty vehicles above specified gross weight thresholds. Maharashtra and Gujarat commercial vehicle retrofit markets remain underpenetrated, creating first-mover positioning for electromechanical actuator suppliers ahead of enforcement deadlines.
South Korea
Seoul Capital Area OEMs specify clutch-based vectoring for high-volume SUV programs. Busan-Ulsan automotive clusters source modular actuator platforms from regional tier-one suppliers, with domestic content requirements favoring local electromechanical integration over imported mechanical differentials.
Australia
Tropical climate thermal degradation constrains silicon-based power electronics deployment in Queensland and Northern Territory mining vehicle applications. Victoria and New South Wales fleet operators consolidate chassis sourcing decisions at platform level, standardizing torque management specifications across mixed passenger and light commercial pools.
Asia-Pacific Torque Vectoring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Torque Vectoring Market. The supplier base organizes into three functional tiers: driveline heritage specialists with mechanical differential expertise, electronics-originated entrants exploiting software-defined chassis control, and battery-electric-native integrators with vertical software capability. Competitive maneuvering concentrates on strategic partnerships for eDrive integration and geographic expansion into underpenetrated commercial vehicle segments.
Among heritage driveline suppliers, BorgWarner Inc. and GKN Automotive occupy anchor positions representing mechanical-to-electromechanical transition archetypes. ZF Friedrichshafen AG exemplifies the modular platform strategy, with its actuator architectures scaling across multiple OEM vehicle programs. These three entities collectively illustrate the competitive tension between hardware supremacy and software-defined differentiation reshaping procurement specifications.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| GKN Automotive |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| JTEKT Corporation |
| Magna International Inc. |
| Dana Incorporated |
| Hyundai Mobis |
| Hitachi Astemo |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week lead times for electromechanical actuators in the Jiangsu-Zhejiang corridor concentrate procurement leverage among vertically integrated Chinese OEMs while compressing margin buffers for tier-two mechanical differential suppliers. This inventory-to-pricing dynamic rewards platform-level sourcing consolidation and penalizes component-level vendors lacking captive motor-inverter production.
Pricing Analysis
After-sales service contracts and over-the-air calibration subscriptions now generate lifetime value multiples exceeding hardware margins across active torque vectoring deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by actuator bandwidth and software feature unlocks, with Chinese battery-electric OEMs absorbing premium tier costs while Indian commercial vehicle buyers demand economy-tier hardware-only solutions. Cost compression in brake-based electronic systems is intensifying because ESC hardware commoditization eliminates differential premiums. Fleet procurement managers in Australia's eastern states exhibit lowest price sensitivity due to platform-standardization mandates, whereas Maharashtra truck retrofitters face acute budget constraints ahead of BIS enforcement.
Supply Chain Analysis
Strategic stockpiling of neodymium and dysprosium concentrates among Japanese magnet processors contrasts with just-in-time inventory preferences at Korean clutch-pack assembly plants. Precision actuator manufacturing draws from China, Japan, and South Korea, with rare earth magnet supply resting on Mongolian and Burmese ore dependencies. Single-source vulnerability in Jiangsu permanent-motor winding creates exposure to regional power rationing. Distribution runs through tier-one electronics channels rather than traditional driveline distributors as software-defined chassis control displaces mechanical hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific torque vectoring market is emerging from a cyclical trough as electrified platform launches accelerate replacement demand for legacy mechanical differentials. OEM capital allocation to eDrive integration programs provides the cyclical lift.
For Market Incumbents: Compound defensive positioning through backward integration into permanent-magnet motor production and captive software stack development to counter electronics-originated entrants. BorgWarner-class clutch-based portfolios face displacement from modular actuator platforms; anchor capacity expansion in Busan-Ulsan clusters to satisfy Korean domestic content requirements. Certification investment in METI-coordinated JIS validation protocols preserves ASEAN export access against homologation fragmentation. For New Entrants and Emerging Players: METI fast-track certification for chassis dynamics systems enables shortened homologation timelines for Japanese suppliers targeting Thai and Indonesian assembly integration. India's underpenetrated heavy-duty commercial vehicle retrofit market presents the most penetrable white-space opportunity ahead of BIS yaw-moment mandates. Lead with yaw-control hardware-software bundles priced below incumbent electromechanical suites to capture fleet procurement trials. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant automotive chassis divisions lacking electrification roadmaps. Five-to-ten-year viability hinges on software-defined vehicle convergence accelerating algorithmic differentiation over hardware supremacy. Monitor MIIT GB standard enforcement intensity as the inflection signal—accelerated mandate timelines would compress valuation windows for mechanical-differential-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation of chassis sourcing at vehicle architecture level displaces tier-two supplier relationships. |
| Battery Supply Agreement | Dual-motor electrified powertrain contracts secure actuator integration slots ahead of competitor lock-in. |
| Software-Defined Vehicle Investment | Central compute platform integration enables over-the-air torque calibration updates and recurring revenue streams. |
| Geographic Manufacturing Footprint | Jiangsu-Zhejiang production proximity reduces logistics costs for Chinese premium EV platform launches. |
| Charging Infrastructure Partnership | Regenerative braking coordination with charging networks optimizes dual-motor efficiency algorithms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, JIS standards documentation, vehicle production databases, and customs trade records across the Asia-Pacific region. Primary inputs combined OEM platform engineering directors, tier-one supplier procurement leads, aftermarket distributor operations heads, and BIS regulatory affairs specialists with secondary validation from IHS Markit registration data and ASEAN automotive assembly statistics. Bottom-up actuator shipment tallies triangulated against top-down EV platform penetration rates.
Segmentation dimensions modeled span propulsion architecture, vehicle class, actuator technology tier, and regional production cluster across the analysis window. CAGRs derived from curve-fitting historical adoption patterns against regulatory mandate enforcement schedules and OEM platform refresh cycles. Forecast inputs incorporated rare earth magnet price volatility indices and silicon carbide power electronics penetration assumptions.
Decision-makers should treat outputs as directional under stable MIIT enforcement timelines and intact China-Japan-Korea trade corridors; material deviation in rare earth supply availability or BIS mandate acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Transmission Fluids Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Clutch Market
Powertrain
Transmission Repair Market
Powertrain
Engine Support Bar Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Steering Damper Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market