
 United States Maritime Information Market | 2026-2036
United States Maritime Information Market Size, Share, and Industry Trends Forecast 2026-2036
United States Maritime Information Market Intelligence
The convergence of satellite-based AIS feeds with cloud analytics platforms is narrowing the gap between raw vessel tracking and predictive maritime intelligence. Spire Global leverages its constellation of radio-occultation satellites to deliver proprietary weather-maritime fusion data that commercial shippers cannot replicate. L3 Harris Technologies, Inc. anchors its position through classified government contracts for port security sensor networks. Windward Limited differentiates via AI-driven behavioral risk scoring that flags vessel identity spoofing for insurers and flag states.
United States Maritime Information encompasses the collection, processing, and distribution of vessel position data, meteorological forecasts, port status feeds, and regulatory compliance records through terrestrial and space-based sensor networks operating on L-band, VHF, and Ku-band frequencies. The primary purpose is to reduce collision risk, optimize bunker consumption, and enforce Exclusive Economic Zone sovereignty. Satellite Systems currently capture the largest revenue share due to capital-intensive orbital infrastructure and recurring subscription models, while AIS Technology is expanding fastest as low-cost receivers proliferate on fishing fleets and coastal barges. Fleet Management services concentrate margin pools around integrated platform providers that bundle route optimization with regulatory filing automation.
The U.S. Coast Guard enforces AIS carriage requirements under 33 CFR 164.46, while the Federal Communications Commission governs spectrum allocation for maritime VHF and satellite links; both frameworks directly determine equipment certification costs and market access timelines for new entrants. The National Oceanic and Atmospheric Administration shapes demand through its Next-Generation Radar upgrade program, which feeds higher-resolution precipitation data into port closure prediction models. Stakeholders must monitor whether pending FCC spectrum reallocation proceedings compress channel availability for legacy maritime communication networks.
Market Dynamics
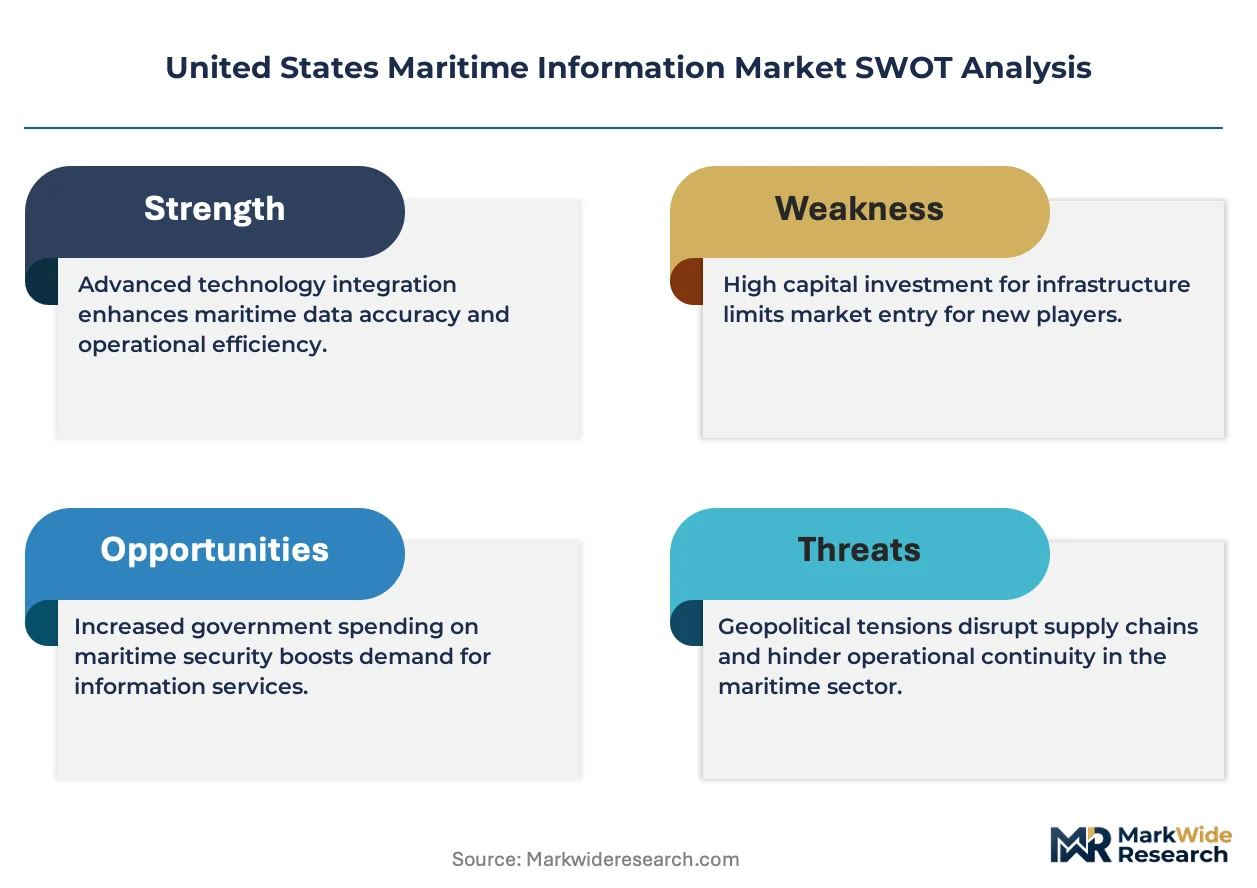
The United States Maritime Information Market pivots on the Coast Guard's cybersecurity mandate cascade, which forces port operators and vessel owners to replace legacy AIS transponders with encrypted, satellite-linked units before the 2028 equipment sunset.
Growth Catalysts
- 33 CFR 164.46 Mandate:The Coast Guard's automatic identification system carriage requirement compels commercial fishing fleets and inland towboats to install certified transceivers, expanding the addressable hardware base across the Gulf Coast and Pacific Northwest.
- Bunker Optimization Algorithms:Container lines operating Houston-Singapore routes deploy real-time current and weather fusion data to cut fuel consumption, directly tying information subscriptions to operating cost reduction.
- Port Authority Consolidation:The Port of Corpus Christi's integration with neighboring Texas maritime districts creates unified procurement pools for vessel traffic services, concentrating demand for integrated information platforms.
Market Restraints
- Orbital Slot Scarcity:Ku-band spectrum congestion over the continental shelf limits new satellite constellation entrants, leaving incumbent L-band providers with pricing leverage over Gulf Coast shippers.
- Terrestrial AIS Receiver Saturation:Dense coastal receiver networks in Florida and California create signal collision zones where vessel position reports drop out, degrading service reliability for harbor pilots.
- NOAA Data Licensing Friction:Restrictions on commercial redistribution of Next-Generation Radar precipitation feeds force information providers to build parallel meteorological sensor networks, duplicating capital deployment.
Strategic Opportunities
- Great Lakes Underpenetration:Seasonal ice navigation and restricted bridge clearances on Lake Superior routes lack real-time structural load and ice thickness data, opening white space for specialized information services.
- Cyber Insurance Underwriting:P&I clubs writing hull and machinery coverage for Jones Act fleets seek vessel behavioral data to price cyber-attack exposure, creating a new subscription revenue stream.
- FCC Spectrum Reallocation Tailwind:Pending proceedings to reserve VHF channels for autonomous vessel coordination could mandate new radio equipment across the inland waterway system, bundling information service contracts with hardware refresh cycles.
Industry Challenges
- Maritime Cybersecurity Certification Bottleneck:The Coast Guard's limited Type Approval capacity for encrypted AIS units stretches equipment qualification timelines to fourteen months, delaying fleet-wide compliance.
- Legacy VTS Integration Complexity:Port authorities in New Orleans and Mobile operate 1990s-era radar processors that resist API connectivity to cloud analytics platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Maritime Information Market |
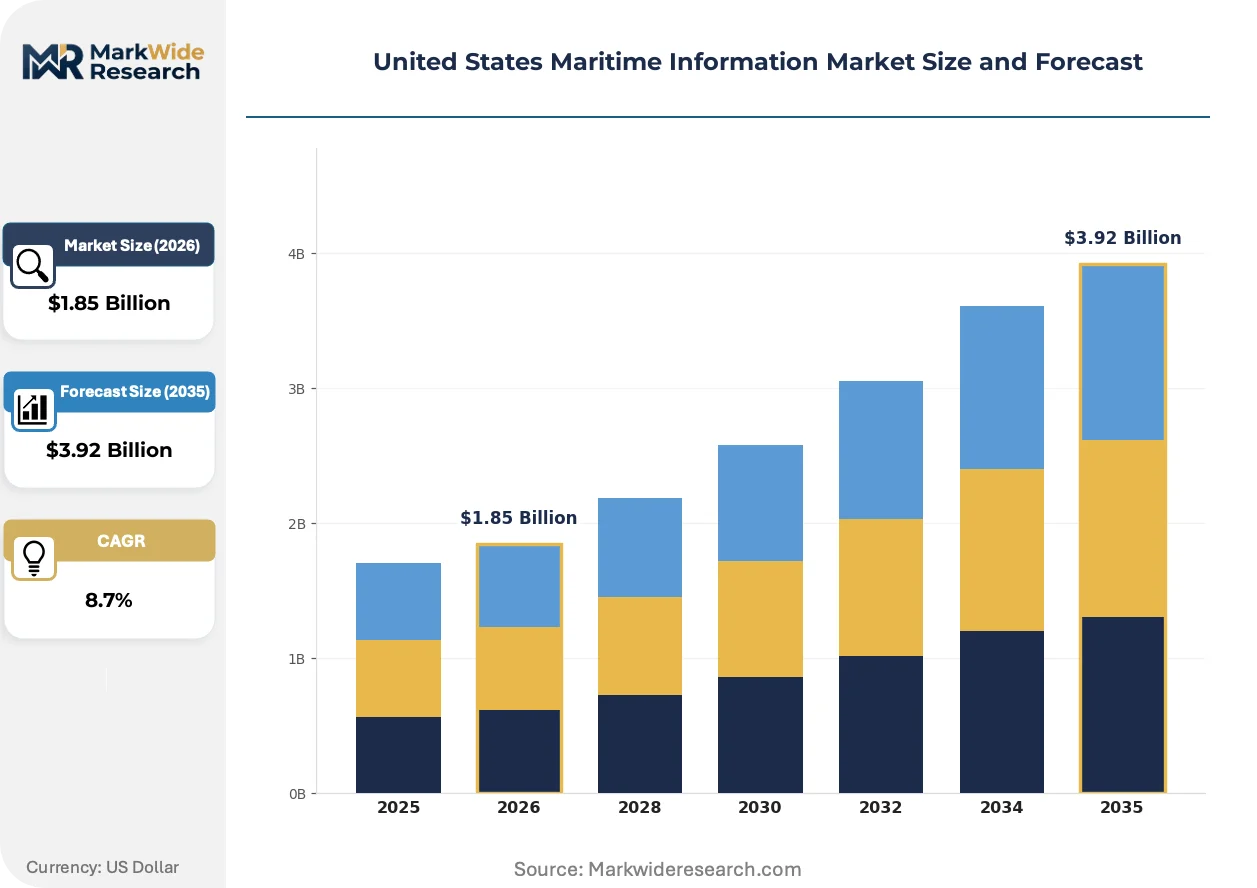
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigational Data, Weather Forecasting, Fleet Management, Port Operations Technology: Satellite Systems, AIS Technology, Radar Systems, Communication Networks End User: Commercial Shipping, Government Agencies, Research Institutions, Logistics Providers Application: Marine Safety, Trade Operations, Environmental Monitoring, Traffic Management |
| Companies Covered | Windward Limited, SAAB Group, Thales Group, Northrop Grumman Corporation, ORBCOMM Inc., Spire Global, L3 Harris Technologies, Inc., BAE Systems, Iridium Communications Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Maritime Information Market Strategic Shifts & Innovations
Cloud-native vessel data architectures are compressing the latency between satellite downlink and actionable fleet intelligence, collapsing the traditional boundary between raw tracking feeds and predictive analytics.
Synthetic aperture radar (SAR) satellite constellations are digitizing dark vessel detection for Coast Guard counter-narcotics operations. Maritime patrol aircraft crews now receive automated tip-offs on ships that have disabled AIS transponders, compressing interdiction response windows from hours to minutes. The technology is digitizing how Exclusive Economic Zone enforcement allocates scarce cutter and aircraft assets across the Caribbean transit zone.
The Federal Communications Commission's maritime VHF reallocation proceeding is forcing equipment manufacturers to design software-defined radios capable of channel agility. Shipboard electronics suppliers must now engineer transceivers that reconfigure via over-the-air updates rather than hardware swaps, raising firmware security certification costs but eliminating physical retrofit expenses. The Gulf Coast towboat sector faces the steepest compliance curve due to its fragmented owner-operator structure.
Container line procurement departments are unbundling route optimization from regulatory filing automation, treating these as separate vendor relationships rather than integrated platform subscriptions. Maersk and CMA CGM have established distinct RFP processes for weather routing intelligence versus EPA ballast water reporting compliance, fragmenting what had been bundled information service contracts. This pattern is most visible among carriers operating the Asia-US West Coast lane, where specialized boutique providers now win point-solution contracts against incumbent integrated platforms.
United States Maritime Information Market Segmentation
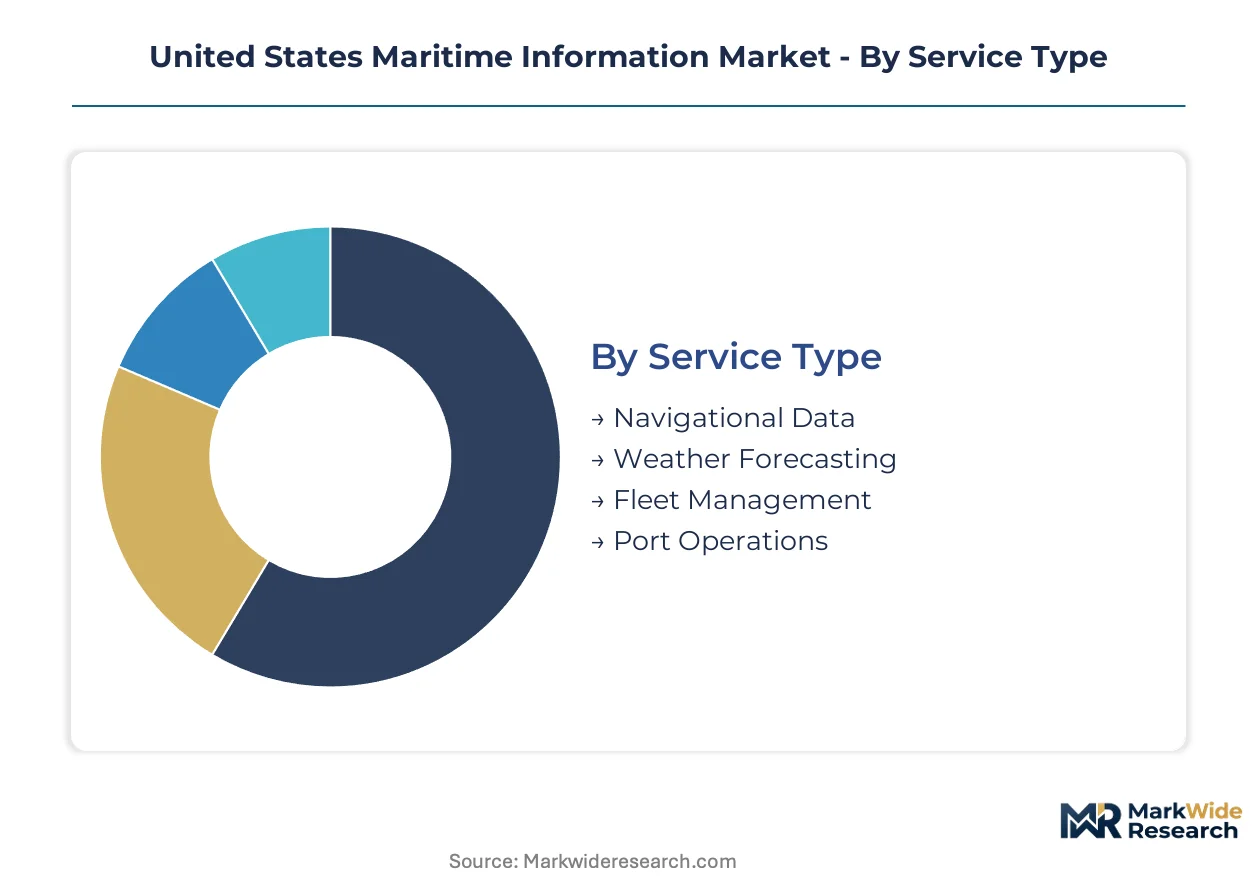
Maritime information providers structure offerings around distinct operational workflows, from bridge-level navigation support to shore-side fleet coordination. Each segment carries unique technical specifications, regulatory compliance burdens, and procurement cycles that shape vendor competitive positioning.
Service Type:
Use-case spectrum spans bridge officers requiring real-time positioning data to port dispatchers optimizing berth allocation across multi-vessel arrivals.
- Navigational Data:Electronic chart corrections, Notice to Mariner updates, and dynamic depth sounding feeds ensure safe passage through shifting channel conditions. Demand concentrates among Gulf Coast tanker operators navigating the Houston Ship Channel's dredge-dependent draft restrictions, where outdated sounding data triggers costly lightering operations.
- Weather Forecasting:High-resolution precipitation, sea state, and current vector predictions enable route optimization and cargo securing decisions. The Pacific Northwest fishing fleet and Alaska crude tanker trades drive subscription intensity, with operators requiring 72-hour wave height precision to avoid weather delays at Valdez terminal approaches.
- Fleet Management:Integrated platforms combining vessel tracking, maintenance scheduling, and regulatory filing automation. Container lines operating Asia-US West Coast services deploy these systems to coordinate multi-port rotations.
- Port Operations:Vessel traffic services, berth window management, and pilot dispatch coordination. Texas port authorities leverage these tools to synchronize Corpus Christi energy export terminals with inbound VLCC schedules.
The dominant share belongs to Navigational Data, while Fleet Management is closing the gap fastest.
Technology:
Cost tier differentiation separates capital-intensive orbital infrastructure from terrestrial receiver networks with lower deployment barriers.
- Satellite Systems:L-band, Ku-band, and emerging low-earth orbit constellations deliver global coverage independent of coastal infrastructure. Gulf Coast shippers depend on these feeds for beyond-AIS-range tracking in the western Gulf of Mexico, though Ku-band congestion limits new entrant pricing pressure.
- AIS Technology:VHF-based automatic identification system transceivers and shore-side receiver networks provide standardized vessel position reporting. The Coast Guard's 33 CFR 164.46 mandate continues expanding carriage requirements to smaller fishing fleets and inland towboats, broadening the installed base fastest.
- Radar Systems:X-band and S-band coastal surveillance supporting vessel traffic services in restricted visibility. Port authorities in New Orleans maintain legacy processors requiring expensive middleware to integrate with modern analytics platforms.
- Communication Networks:Maritime broadband, VHF voice, and satellite messaging infrastructure. FCC spectrum reallocation proceedings may force equipment refreshes across the inland waterway system.
Satellite Systems command the largest revenue pool, though AIS Technology is expanding most quickly as carriage mandates broaden.
End User:
Customer type determines procurement sophistication, from integrated carrier fleet operations to fragmented owner-operator structures.
- Commercial Shipping:Container lines, tanker operators, and bulk carriers purchasing fleet-wide subscriptions. Houston-Singapore route operators tie information spend directly to bunker cost reduction, creating measurable ROI justification.
- Government Agencies:Coast Guard, NOAA, and port authorities procuring surveillance and enforcement capabilities. Counter-narcotics operations drive synthetic aperture radar tipping-and-cueing demand for dark vessel detection.
- Research Institutions:Academic and government laboratories accessing historical vessel track databases and oceanographic fusion products. Climate pattern studies and maritime economics research constitute primary use cases.
- Logistics Providers:Freight forwarders, terminal operators, and supply chain visibility platforms integrating maritime arrival data with inland distribution planning.
Commercial Shipping retains the dominant procurement volume, while Government Agencies are accelerating investment fastest under cybersecurity mandate cascades.
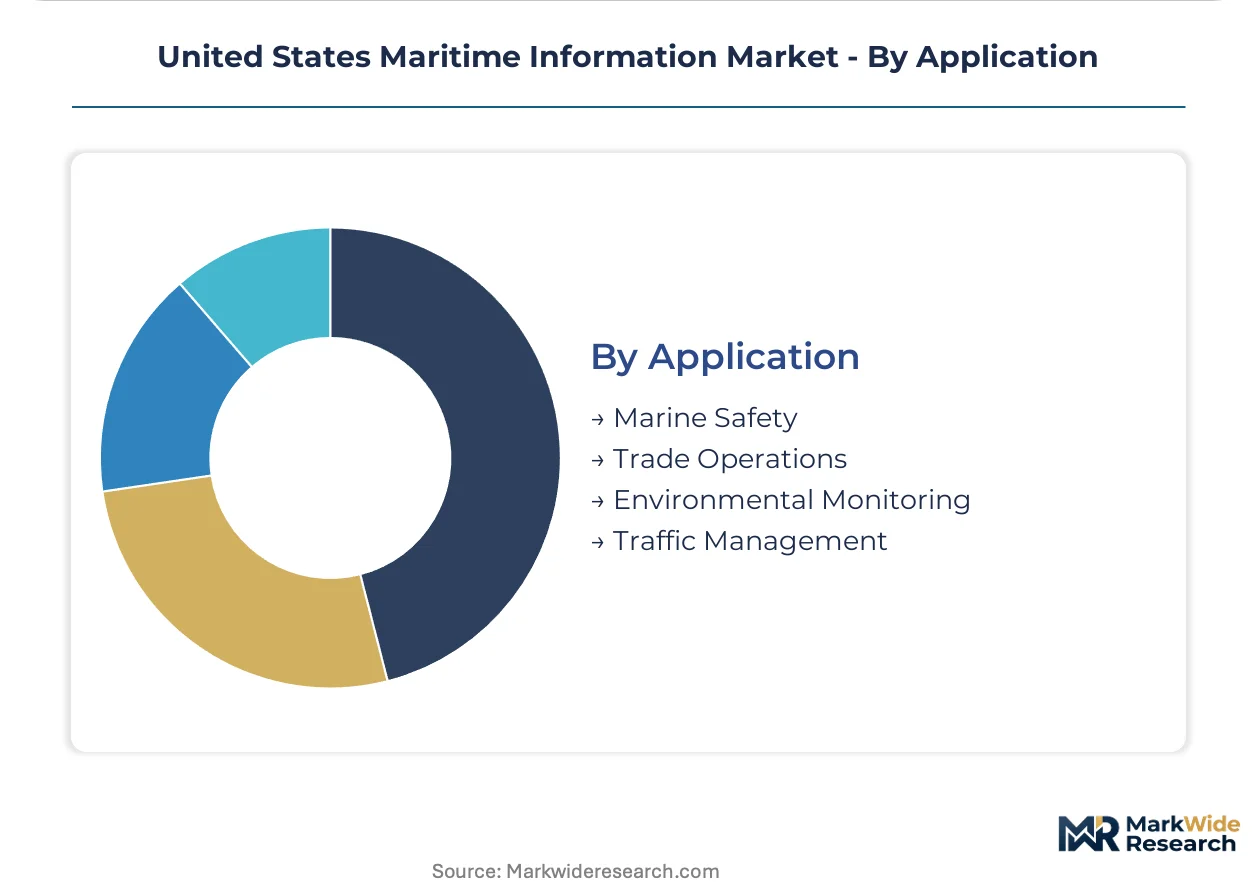
Application:
Margin concentration varies by application maturity, with established safety compliance segments facing price pressure versus emerging environmental monitoring opportunities.
- Marine Safety:Collision avoidance, search-and-rescue coordination, and distress alerting. Harbor pilots in Florida dense receiver zones experience signal collision degradation, creating service reliability tension.
- Trade Operations:Cargo tracking, customs documentation, and supply chain visibility. Energy export terminals at Corpus Christi require precise vessel scheduling to optimize dock utilization.
- Environmental Monitoring:Ballast water compliance, emissions tracking, and marine protected area enforcement. EPA reporting requirements and emerging carbon accounting standards are expanding data collection scope.
- Traffic Management:Vessel traffic service coordination, port congestion management, and waterway capacity optimization. The Port of New Orleans integrates radar, AIS, and pilot dispatch into unified control.
Marine Safety captures the largest installed base, though Environmental Monitoring is gaining share fastest under expanding regulatory reporting obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Singapore energy corridor drives maritime information demand as Gulf Coast LNG exporters track VLCC fleets through the Strait of Malacca. Shippers require fused weather-current data to optimize bunker consumption on this route.
Gulf Coast Corridor
Energy export terminals at Corpus Christi and Houston generate dense vessel traffic requiring real-time berth coordination. The Coast Guard's 33 CFR 164.46 mandate compels towboat operators to install certified AIS transceivers. Port authorities in New Orleans integrate legacy radar processors with cloud analytics platforms for pilot dispatch optimization.
Pacific Northwest
Alaska crude tanker trades and Pacific fishing fleets demand 72-hour wave height precision for Valdez terminal approaches. NOAA's Next-Generation Radar upgrade feeds higher-resolution precipitation data into port closure prediction models. Seattle-based maritime analytics providers serve container lines operating Asia-US West Coast services.
Great Lakes Region
Seasonal ice navigation on Lake Superior routes lacks real-time structural load and ice thickness data. The Coast Guard's icebreaking operations coordinate with vessel traffic services in Sault Ste. Marie. Specialized information services target the restricted bridge clearances and winter closure windows that disrupt iron ore and grain movements.
Southeast Atlantic
Dense terrestrial AIS receiver networks in Florida create signal collision zones degrading harbor pilot reliability. Counter-narcotics operations drive synthetic aperture radar tipping-and-cueing demand for dark vessel detection in Caribbean transit zones. Miami-based logistics providers integrate maritime arrival data with inland distribution planning.
Inland Waterway System
Pending FCC spectrum reallocation proceedings may mandate new radio equipment across Mississippi River barge fleets. The fragmented owner-operator structure of Gulf Coast towboat sectors complicates coordinated procurement. Louisville and St. Louis river terminals seek integrated platforms combining vessel tracking with regulatory filing automation.
United States Maritime Information Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform providers that bundle satellite infrastructure with analytics software. Tiered competition separates capital-intensive orbital operators from specialized AI-driven risk scoring boutiques. Three archetypes dominate: constellation owners with proprietary weather-maritime fusion data, government contractors anchoring classified port security networks, and behavioral analytics specialists serving insurers. Dominant competitive moves include strategic partnerships between satellite operators and cloud analytics platforms, plus vertical integration into encrypted AIS hardware manufacturing.
Within the satellite-constellation tier, Spire Global leverages radio-occultation satellites to deliver proprietary weather-maritime fusion data. L3 Harris Technologies, Inc. anchors its position through classified government contracts. Windward Limited exemplifies the AI-driven behavioral risk scoring archetype, occupying a position that flags vessel identity anomalies for flag states and P&I clubs.
| Leading Market Players |
|---|
| Windward Limited |
| SAAB Group |
| Thales Group |
| Northrop Grumman Corporation |
| ORBCOMM Inc. |
| Spire Global |
| L3 Harris Technologies, Inc. |
| BAE Systems |
| Iridium Communications Inc. |
| Others |
Cost & Logistics Intelligence
Orbital infrastructure ownership in the United States, United Kingdom, and Luxembourg concentrates upstream supply for satellite-based maritime data feeds, directing margin capture toward constellation operators with proprietary radio-occultation weather fusion capabilities while terrestrial AIS receiver manufacturers compete on hardware certification speed.
Pricing Analysis
Legacy L-band satellite services, emerging low-earth orbit constellations, and next-generation software-defined radio platforms stratify across premium, standard, and economy tiers. Subscription models dominate for integrated fleet management platforms, while per-vessel transactional pricing persists for standalone AIS transceiver hardware. Price differentiation rests on encryption certification grade under Coast Guard Type Approval and volume scale across multi-vessel fleet contracts. Cost compression in terrestrial AIS receiver tiers is intensifying because of manufacturing commoditization in Asian electronics hubs. Coastal fishing cooperatives exhibit the highest price sensitivity, whereas Jones Act container lines prioritize compliance reliability over unit cost.
Supply Chain Analysis
Radio-frequency component fabrication draws from semiconductor foundries in Taiwan, specialized antenna manufacturers in Germany, and final assembly operations in Mexico and Vietnam. Critical inputs include gallium nitride power amplifiers, software-defined radio chipsets, and marine-grade corrosion-resistant housings. Single-source vulnerability concentrates in Ku-band transceiver modules from limited qualified suppliers. Distribution runs through maritime electronics integrators serving Gulf Coast and Pacific Northwest port clusters, with direct OEM relationships dominating government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime information platforms are consolidating around API-first architectures that reward ecosystem interoperability, as container lines unbundle route optimization from regulatory filing automation and demand modular data feeds.
For Market Incumbents: Entrench position through captive control over encrypted AIS hardware manufacturing and accelerated Coast Guard Type Approval capacity. The fragmentation of container line procurement into point-solution RFPs threatens bundled platform margins. Priority investment should center on middleware development for legacy VTS radar processor integration at New Orleans and Mobile port authorities. For New Entrants and Emerging Players: Build out specialized ice-navigation data services for Lake Superior routes, where real-time structural load and ice thickness information remains underpenetrated. The Great Lakes region offers the most penetrable geography due to seasonal navigation windows and restricted bridge clearance complexity. Go-to-market execution should target iron ore and grain operator associations with pilot subscription programs. For Investors and Strategic Acquirers: Capital is best deployed toward AI-driven behavioral analytics boutiques with established P&I club relationships, given the emerging cyber insurance underwriting revenue stream. Long-term viability across the analysis window favors providers with proprietary dark vessel detection capabilities using synthetic aperture radar tipping-and-cueing. The signal to monitor is FCC spectrum reallocation proceedings for autonomous vessel coordination channels.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity to legacy VTS radar processors at Gulf Coast port authorities collapses middleware development costs for cloud analytics adoption. |
| Strategic Partnership | Coalitions between radio-occultation satellite operators and container line procurement departments secure multi-year weather-maritime fusion data contracts. |
| Acquisition of Specialist Firm | Consolidation of AI-driven behavioral risk scoring boutiques strengthens dark vessel detection offerings for Coast Guard counter-narcotics operations. |
| Product Launch | Encrypted AIS transceiver lines with over-the-air firmware update capability address Coast Guard cybersecurity mandate compliance before equipment sunset deadlines. |
| Geographic Expansion | Entry into Great Lakes ice-navigation data services captures unmet demand from Lake Superior iron ore and grain operators facing seasonal closure windows. |
Research Approach
Findings reconcile primary fieldwork against secondary review of Coast Guard regulatory filings, FCC spectrum allocation proceedings, NOAA Next-Generation Radar upgrade documentation, and container line procurement disclosures. Primary inputs drew from fleet operations managers at Houston-Singapore route operators, maritime electronics procurement leads at Gulf Coast port authorities, Coast Guard cybersecurity compliance officers, and P&I club underwriting directors. Bottom-up vessel traffic service demand modeling and top-down satellite constellation revenue aggregation were cross-validated through triangulation.
Forecast inputs considered service type segmentation across navigational data, weather forecasting, fleet management, and port operations alongside technology tiers spanning satellite systems, AIS infrastructure, radar networks, and communication equipment. Deployment models, fleet size categories, and regional regulatory cluster intensity shaped the analytical framework across the projection horizon. CAGRs were derived from equipment refresh cycle timing, mandate compliance deadlines, and bunker cost reduction ROI thresholds specific to Asia-US West Coast and Houston-Singapore trade lanes.
Stress conditions across FCC spectrum reallocation timing, Coast Guard Type Approval queue duration, and Ku-band orbital slot availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mandate enforcement consistency and satellite launch schedule execution. Cross-checking against NOAA precipitation data licensing terms and container line disclosed information technology spending is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Singapore Maritime Market