
 Commercial Truck Trailer Market | 2026-2036
Commercial Truck Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Truck Trailer Market Analytics
North American trailer manufacturers are recalibrating production schedules after two years of order backlogs and supply chain realignment. Wabash leverages its composite panel technology to reduce dry van weight and improve freight efficiency. Great Dane anchors its position through extensive dealer networks across the Midwest and Southeast. Hyundai Translead competes aggressively on the West Coast with standardized refrigerated configurations for produce and cold-chain logistics.
A commercial truck trailer is a non-powered vehicle unit designed for cargo transport, typically constructed with steel or aluminum framing, composite sidewalls, and axle assemblies rated for gross vehicle weight combinations exceeding 80,000 pounds; its primary purpose is to extend tractor-truck payload capacity across long-haul, regional, and last-mile freight operations. Dry van configurations remain the largest volume category but face margin compression from commoditization, while refrigerated trailers command premium pricing due to insulation complexity and temperature-control integration. Flatbed trailers serve construction firms and industrial shippers with specialized load requirements, and aluminum-intensive builds are gaining share as fleet operators pursue fuel economy compliance.
The EPA Phase 3 standards and NHTSA fuel efficiency rules jointly constrain trailer design choices, compelling manufacturers to certify aerodynamic devices and lightweight material combinations. The EU Green Deal and F-Gas Regulation similarly affect refrigerated trailer imports and cold-chain equipment specifications in European markets. Stakeholders must monitor how carbon-border adjustments and state-level zero-emission freight corridors reshape capital allocation between conventional and alternative-material trailer platforms.
Market Dynamics
EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules are compressing trailer design cycles, forcing manufacturers to certify lightweight material combinations and aerodynamic devices ahead of traditional replacement timelines.
Growth Catalysts
- Cold-chain pharmaceutical distribution:Temperature-controlled trailers serve biologics and vaccine logistics networks with validated thermal performance.
- EPA Phase 3 compliance:Fleet operators replace aging dry van fleets to meet federal greenhouse gas thresholds and avoid penalty structures.
- Aluminum-intensive construction:Composite sidewalls and bonded panel systems reduce tare weight and improve freight efficiency per dispatched mile.
Market Restraints
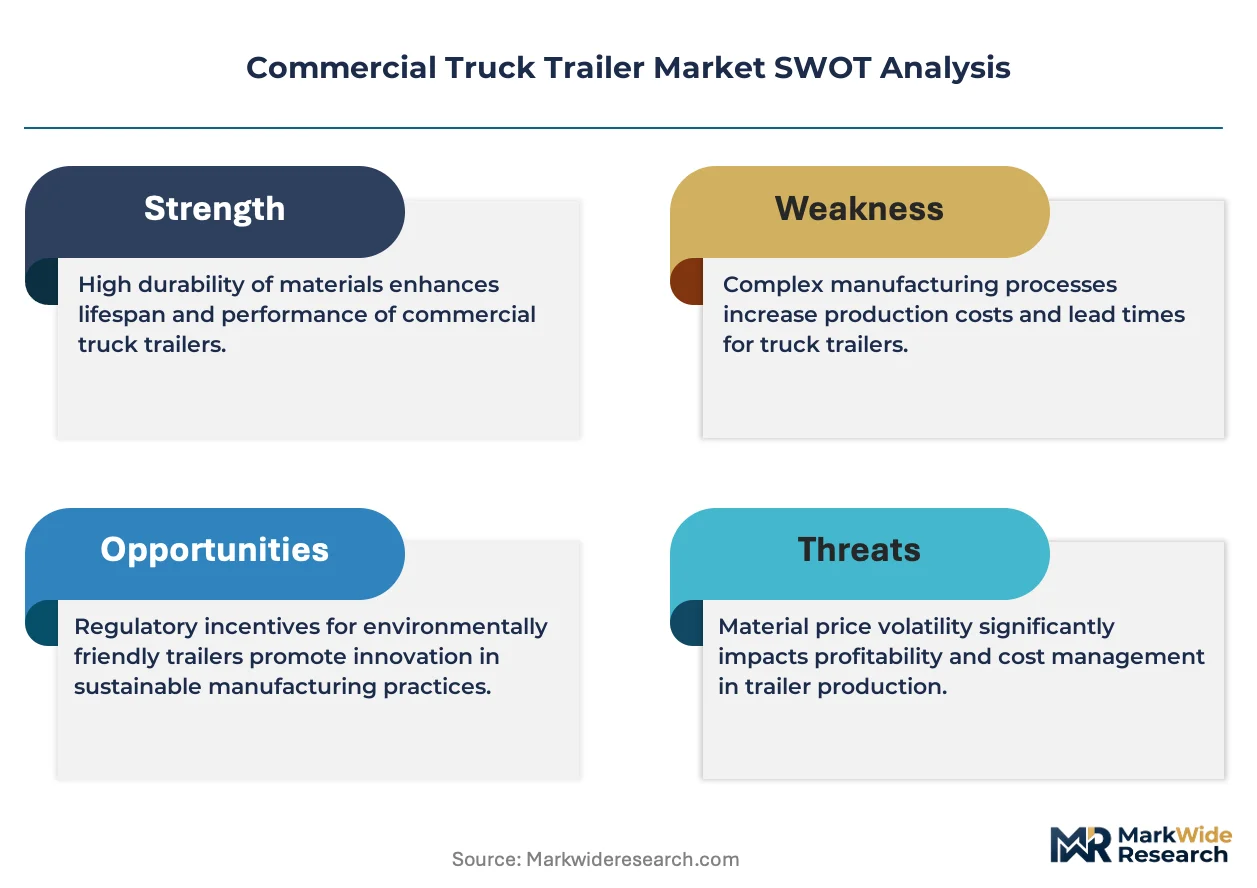
- Steel and aluminum input volatility:Raw material price swings compress manufacturing margins and destabilize fleet procurement budgets.
- Axle and suspension supply concentration:Component sourcing clusters in Midwest manufacturing corridors, creating geographic vulnerability.
- Refrigeration unit F-Gas restrictions:EU F-Gas Regulation limits refrigerant options for cross-border trailer imports.
Strategic Opportunities
- Intermodal freight corridors:Rail-compatible trailer designs capture modal shift demand along Texas-to-California and Chicago-to-Seattle lanes.
- Telematics integration:Sensor-enabled reefers and dry vans converge with fleet management platforms for predictive maintenance.
- State zero-emission freight zones:California's Advanced Clean Trucks regulation creates early-adopter incentives for electric refrigeration units.
Industry Challenges
- Welding and composites technician scarcity:Aluminum fabrication and bonded panel assembly require specialized labor pools concentrated in legacy manufacturing regions.
- Type certification timeline compression:EPA and NHTSA concurrent rulemaking forces simultaneous engineering validation across aerodynamic, material, and refrigeration subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Truck Trailer Market |
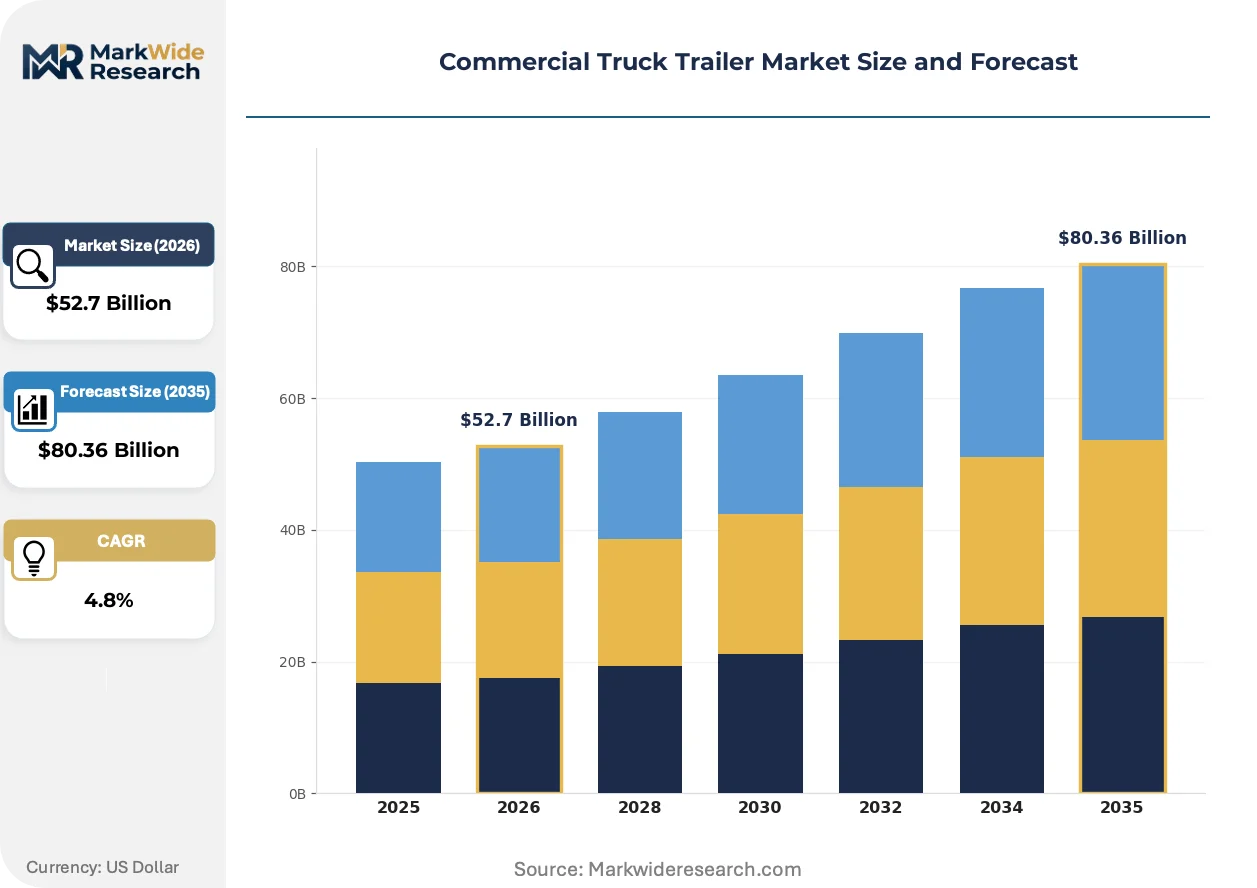
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Refrigerated, Dry Van, Tanker End User: Logistics Companies, Retailers, Construction Firms, Freight Carriers Material: Aluminum, Steel, Composite, Magnesium Size: Single Axle, Tandem Axle, Triaxle, Heavy-Duty |
| Companies Covered | Great Dane, Vanguard National, Hyundai Translead, Hillsboro Industries, Fontaine Trailer, Wabash, Stoughton, EnTrans, Utility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Truck Trailer Market Evolving Landscape
Material substitution and regulatory compliance are rewriting competitive advantage in trailer manufacturing, with lightweight construction and connected cold-chain systems displacing conventional specifications.
Composite sandwich panels with fiberglass-reinforced skins and thermoplastic cores are rewriting dry van weight benchmarks. Large fleet operators spec these builds for dedicated e-commerce lanes where payload maximization drives unit economics. The technology is compressing steel-intensive legacy configurations into niche construction and industrial segments.
EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules jointly constrain trailer aerodynamics and material certification. Manufacturers must validate roof fairings, side skirts, and boat tails through standardized test cycles before fleet deployment. Refrigerated trailer segments face compounded compliance burdens from refrigeration unit efficiency mandates.
Asset-light logistics providers now specify trailers through usage-based arrangements rather than capital purchase. Third-party leasing channels displace direct manufacturer relationships for mid-size regional carriers. This pattern concentrates most visibly in California and Texas freight corridors where fleet flexibility outweighs ownership economics.
Commercial Truck Trailer Market Segmentation
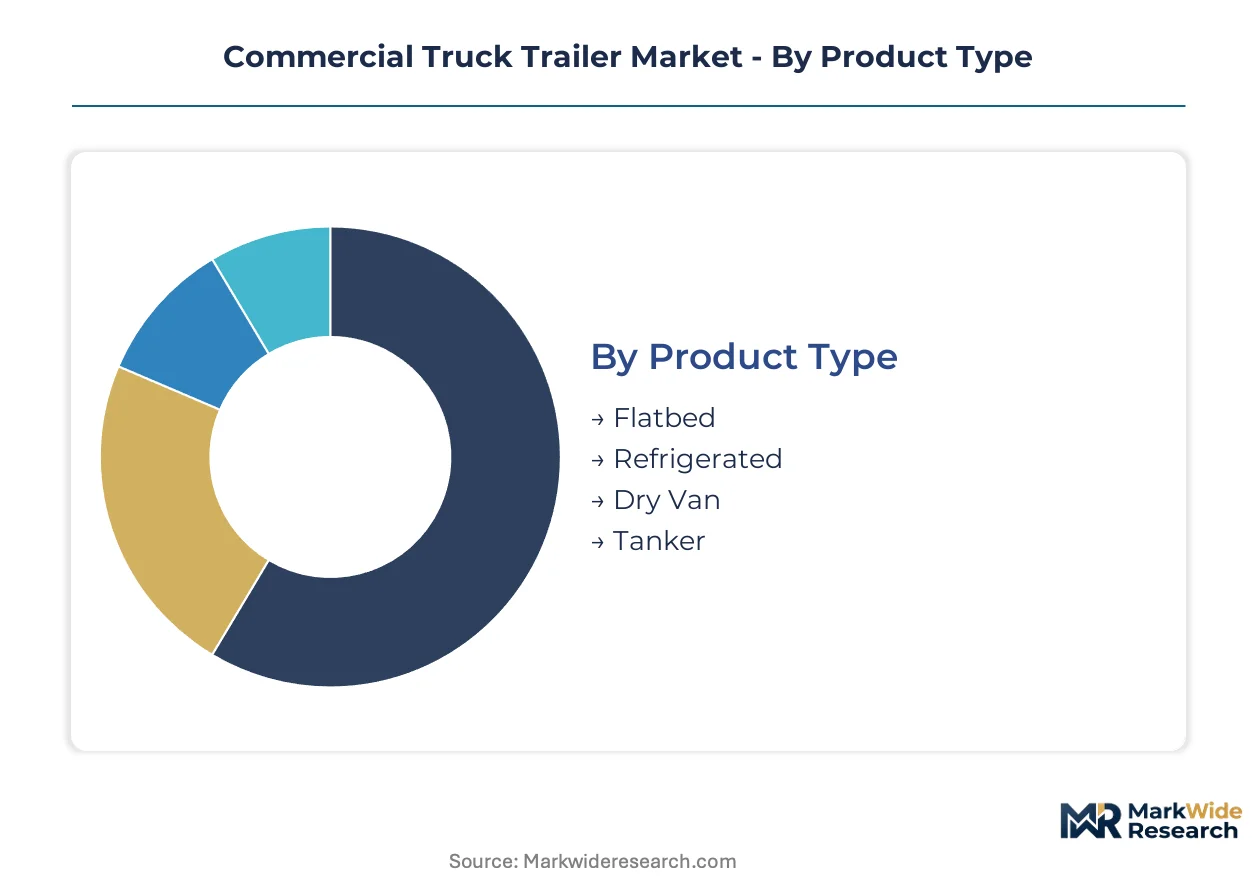
Trailer procurement decisions cascade across four interconnected dimensions. Fleet operators weigh payload efficiency against regulatory compliance, while end-use applications dictate durability specifications and cold-chain requirements.
Product Type:
Fleet operators select configurations based on cargo protection needs and lane economics.
- Dry Van:Enclosed box construction with composite or plywood interior lining serves general freight and e-commerce parcel networks. Demand concentrates in Midwest distribution corridors where dedicated retail lanes maximize cube utilization.
- Refrigerated:Insulated composite panels with integrated refrigeration units maintain temperature bands for produce, dairy, and pharmaceutical distribution. California's Central Valley and Florida's produce belts drive replacement cycles as cold-chain validation requirements tighten.
- Flatbed:Open-deck steel construction with stake pockets and tie-down points accommodates oversized construction materials and industrial machinery.
- Tanker:Cylindrical aluminum or stainless-steel vessels designed for liquid bulk transport including food-grade, chemical, and petroleum products.
Dry Van leads on scale; Refrigerated leads on momentum.
End User:
Procurement authority varies by fleet scale and ownership structure across customer categories.
- Freight Carriers:Asset-heavy trucking companies operating 500+ units dominate volume procurement through direct manufacturer relationships and multi-year fleet replacement programs.
- Logistics Companies:Third-party providers and freight brokers specify trailers through operating leases and revenue-sharing arrangements to preserve capital flexibility.
- Retailers:Private fleet operators at big-box and grocery chains configure dedicated specifications for store-door delivery and cross-dock efficiency.
- Construction Firms:Project-based operators acquire flatbed and specialized trailers through equipment financing tied to contract duration.
Freight Carriers anchor procurement volume; Logistics Companies are expanding most quickly through asset-light models.
Material:
Weight reduction and corrosion resistance now dominate material selection criteria.
- Aluminum:Extruded framing and sheet construction deliver 40% weight savings over steel equivalents, enabling additional payload capacity per dispatch.
- Composite:Fiberglass-reinforced thermoplastic sandwich panels reduce tare weight while improving thermal insulation performance for refrigerated applications.
- Steel:High-tensile framing remains standard for flatbed and heavy-haul configurations where impact resistance outweighs weight considerations.
- Magnesium:Cast and extruded components appear in select lightweight assemblies for premium dry van specifications.
Aluminum dominates current production; Composite is gaining share fastest on regulatory pressure.
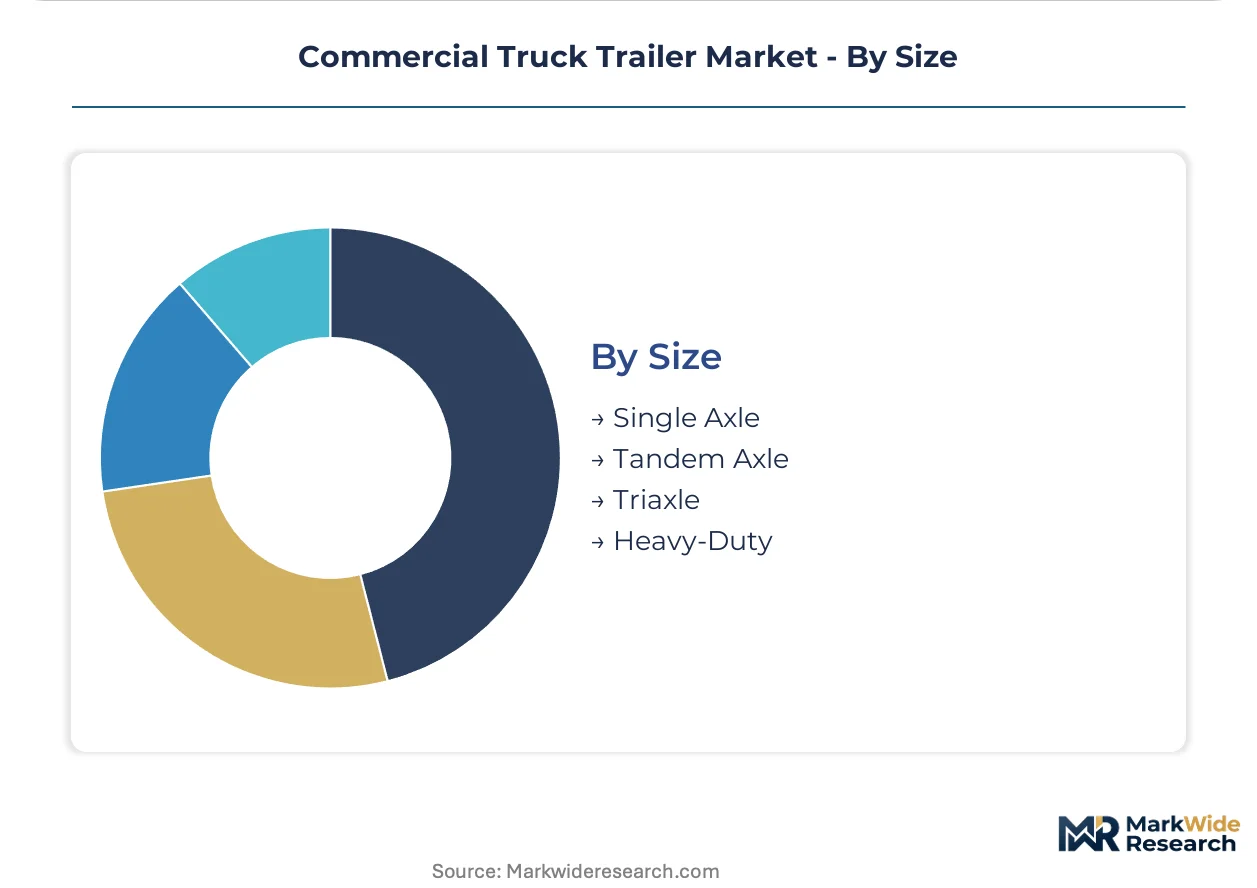
Size:
Axle configuration determines regulatory weight limits and bridge law compliance.
- Tandem Axle:Dual-axle bogies rated at 34,000 pounds constitute the standard configuration for 53-foot dry van and refrigerated trailers operating interstate corridors.
- Triaxle:Triple-axle spreads distribute heavier loads across more wheel positions, serving flatbed and tanker segments in states with higher gross weight allowances.
- Single Axle:Lightweight two-wheel configurations serve urban delivery and pup trailer applications where maneuverability exceeds capacity requirements.
- Heavy-Duty:Reinforced suspensions and multiple axle groups accommodate specialized permits for oversized and overweight cargo.
Tandem Axle commands production volume; Triaxle shows steepest expansion trajectory on specialized freight demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting capital toward production zones with favorable compliance cost structures. Manufacturers are relocating fabrication capacity to exploit gaps between EPA Phase 3 stringency and less demanding foreign standards. This arbitrage dynamic is reshaping where aluminum-intensive and composite-panel trailers enter production.
United States
Domestic fleet operators drive replacement demand through dedicated e-commerce fulfillment lanes and intermodal freight corridors. EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules compel accelerated dry van turnover. Manufacturing clusters in Indiana and Ohio concentrate composite-panel fabrication and aluminum extrusion capacity for lightweight refrigerated configurations.
Germany
Industrial shippers and chemical producers sustain demand for specialized tanker and flatbed specifications. EU Green Deal carbon-border adjustments and F-Gas Regulation constrain refrigerated trailer imports and refrigerant selection. The Baden-Württemberg and North Rhine-Westphalia industrial corridors host engineering centers developing bonded-panel assemblies for weight-sensitive pharmaceutical logistics.
China
Domestic cold-chain expansion and express delivery networks generate volume procurement for standardized dry van and refrigerated platforms. MIIT fuel consumption standards and dual carbon goals pressure manufacturers toward aluminum substitution in trailer framing. Yangtze River Delta manufacturing zones around Shanghai concentrate axle assembly and suspension component production serving both domestic and export markets.
Mexico
Cross-border freight growth and nearshoring manufacturing relocations expand demand for 53-foot dry van configurations serving US-Mexico trade lanes. NOM environmental standards and USMCA rules-of-origin requirements shape material sourcing decisions. The Nuevo León and Bajío Region industrial corridors attract trailer assembly investment seeking duty-advantaged access to US fleet operators.
India
Agricultural produce distribution and pharmaceutical cold-chain development drive refrigerated trailer adoption across state highway networks. BIS automotive standards and state-level axle load regulations govern trailer dimension and weight compliance. Manufacturing activity in Maharashtra and Gujarat concentrates steel-intensive fabrication for construction and bulk cargo segments.
Commercial Truck Trailer Market Competitive Landscape
North American producers anchor one tier; Asian specialists hold cost-competitive positions in standardized configurations. The vendor base separates into consolidated national suppliers with integrated distribution networks and regional fabricators serving niche load requirements. Three archetypes dominate: composite-technology leaders, aluminum-intensive weight optimizers, and steel-framed value producers. Capacity expansion and strategic partnerships constitute the primary competitive vectors as firms seek to secure axle and suspension supply commitments.
Among North American fabricators, Wabash, Great Dane, and Hyundai Translead occupy distinct positioning within the competitive structure. Wabash represents the composite-technology archetype through its bonded-panel systems. Great Dane exemplifies established distribution-network scale across Midwest and Southeast dealer channels. Hyundai Translead anchors the West Coast refrigerated specialization vector. Each entity sits within a definable strategic tier without overlapping positioning claims.
| Leading Market Players |
|---|
| Great Dane |
| Vanguard National |
| Hyundai Translead |
| Hillsboro Industries |
| Fontaine Trailer |
| Wabash |
| Stoughton |
| EnTrans |
| Utility |
| Others |
Value Network & Pricing Analysis
Aluminum sheet and extrusion costs cascade from Midwest smelters through three distinct pricing tiers before reaching fleet procurement desks, with EPA Phase 3 compliance premiums compressing margins at each handoff.
Pricing Analysis
Dealer markup layers differentiate captive fleet pricing from spot market transactions. Three-tier pricing structure across premium, standard, and economy levels separates composite-panel refrigerated specifications from steel-framed dry van commodity builds. Cost compression in standard-tier configurations is intensifying because raw material volatility destabilizes manufacturer quotes. Asset-heavy freight carriers exhibit lowest price sensitivity due to multi-year replacement cycles, while regional logistics brokers operating on operating leases face acute margin pressure.
Supply Chain Analysis
Axle and suspension assembly rests on concentrated production corridors in Indiana, Ohio, and Michigan. High-tensile steel framing, aluminum extrusions, and bonded composite panels constitute the three critical input streams. Single-source vulnerability concentrates in specialized welding equipment and bonded panel curing systems. Distribution runs through manufacturer-direct channels for large fleet operators and independent dealer networks serving mid-size carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 greenhouse gas standards function as a regulatory compounder, accelerating replacement demand as fleets face penalty structures for non-compliant equipment.
For Market Incumbents: Hedge aluminum price exposure through long-term supply agreements with Midwest extrusion facilities. Defensive moves center on backward integration into composite panel fabrication and captive axle assembly capacity. Threat from lightweight material substitution by emerging Asian competitors demands certification investment in bonded-panel thermal performance. For New Entrants and Emerging Players: California's Advanced Clean Trucks regulation opens a window for electric refrigeration unit specialization. White-space targets include telematics-enabled reefers for pharmaceutical cold-chain validation and aluminum-intensive flatbeds for construction equipment haulers. Go-to-market angle emphasizes usage-based leasing arrangements preserving fleet capital flexibility. For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabricators lack EPA certification bandwidth and NHTSA aerodynamic validation capabilities. Long-term viability favors vertically integrated producers controlling composite formulation through final assembly. Acquisition target archetype: mid-size manufacturers with established dealer relationships in underserved freight corridors. Signal to watch: state-level zero-emission freight zone designations triggering refrigerated trailer specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Panel Manufacturing Scale-Up | Captures EPA Phase 3 lightweighting mandates for dry van and refrigerated segments. |
| Axle Assembly Backward Integration | Reduces geographic vulnerability from Midwest component supply concentration. |
| Electric Refrigeration Unit Development | Aligns with California ACT regulation and emerging state zero-emission freight zones. |
| Telematics Platform Partnership | Converges sensor-enabled trailers with fleet management systems for predictive maintenance. |
| Dealer Network Expansion in Southeast | Captures produce belt replacement cycles across Florida and Georgia freight corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed fleet procurement directors, trailer manufacturer engineering leads, axle supplier plant managers, cold-chain logistics operators, and EPA regulatory affairs specialists. Secondary validation drew from NHTSA fuel efficiency filings, EPA certification databases, customs trade records, and SEC 10-K disclosures from publicly traded fleet operators. Bottom-up unit shipment tallies and top-down GDP-correlated demand models underwent iterative reconciliation.
Historical reference periods anchored demand modeling to pre-pandemic baselines and post-supply-chain-realignment trajectories. Segmentation dimensions spanned product type, end-user category, material composition, axle configuration, and regional regulatory cluster. CAGRs emerged from regression analysis against freight ton-mile indices and fleet age distributions. Industry-specific inputs incorporated aluminum price futures curves and EPA rulemaking timeline assumptions.
Revisions become necessary when regulatory implementation delays, raw material price discontinuities, or modal shift accelerations materialize. Forecasts reflect documented assumptions regarding compliance cost pass-through rates and replacement cycle compression. A small set of named triggers warrants ongoing watch: F-Gas Regulation expansion, state-level zero-emission corridor designations, and axle supplier capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Malaysia Box Truck Market