
 EV Drivetrain Systems Market | 2026-2036
EV Drivetrain Systems Market Size, Share, and Industry Trends Forecast 2026-2036
EV Drivetrain Systems Market Foresight
Asset-light leasing models for battery-drivetrain bundles is rewriting competitive entry barriers for commercial fleet suppliers. Bosch leverages its power electronics manufacturing scale to anchor long-term service contracts with European logistics operators. BYD controls vertically integrated motor and inverter production, sustaining cost advantages across passenger and heavy-duty platforms. ZF Friedrichshafen competes through gear reduction specialization, occupying premium torque-density segments where mechanical efficiency thresholds are rising.
EV drivetrain systems integrate electric motors, power inverters, transmissions, and thermal management hardware to convert stored electrical energy into controlled mechanical torque for vehicle propulsion, with silicon carbide inverter switching frequencies now exceeding 20 kHz to minimize energy losses. The assembly serves the core industrial purpose of replacing internal combustion powertrains with electrified alternatives that deliver instantaneous torque response and regenerative braking capability. Battery pack configurations dominate value capture within product type segmentation, as cell-to-pack architectures eliminate module housings and reduce system mass. Direct drive technology leads technology segmentation for urban mobility applications where gear complexity adds unnecessary cost, while thermal management systems represent the fastest-improving margin pool as power density requirements push cooling demands beyond conventional liquid loops.
The EPA tailpipe standards and NHTSA fuel economy mandates in the United States compel OEMs to source higher-efficiency drivetrain architectures or face fleet-wide penalties that erode profitability. EMA efficiency benchmarks and EU Green Deal vehicle CO2 thresholds in Europe similarly restrict market access for powertrain suppliers whose motor-inverter combinations fail certified energy conversion minimums. Stakeholders must monitor how regulatory calibration between EPA, EMA, and China's MIIT evolves, since divergent certification requirements threaten to fragment supplier R&D budgets across incompatible technical standards.
Market Dynamics
Silicon carbide power semiconductors are compressing inverter switching losses below silicon thresholds, forcing incumbent suppliers to retool fabrication lines or surrender margin to vertically integrated automotive OEMs.
Growth Catalysts
- EPA Fleet Emissions Standards:US commercial vehicle mandates compel Class 8 truck operators to electrify powertrains, accelerating procurement of integrated motor-inverter systems for long-haul routes.
- Cell-to-Pack Architecture:Elimination of module housings reduces battery mass and thermal management complexity, enabling higher energy density configurations that extend commercial vehicle range.
- China Heavy-Duty Electrification:MIIT efficiency benchmarks for freight applications concentrate demand for high-torque integrated drivetrains serving mining and port logistics operations.
Market Restraints
- Neodymium Supply Concentration:Rare earth magnet processing concentrates in Chinese refining corridors, exposing permanent magnet motor producers to export quota volatility and price spikes.
- Silicon Carbide Wafer Scarcity:Substrate manufacturing bottlenecks limit inverter production scaling, constraining supply response even where demand for 800V architectures accelerates.
- Legacy Fleet Depreciation Cycles:Diesel truck residual values remain elevated in secondary markets, delaying replacement economics for owner-operators despite total cost of ownership parity.
Strategic Opportunities
- India Commercial Vehicle Electrification:PLI scheme subsidies for automotive component manufacturing create localized assembly opportunities for motor and gearbox integration serving intra-city freight.
- Wireless Charging Infrastructure:Inductive power transfer at depot locations enables opportunity charging for transit buses, reducing battery capacity requirements and drivetrain cost structure.
- EU Battery Passport Mandate:CSRD traceability requirements favor suppliers offering end-to-end carbon accounting, differentiating integrated drivetrain bundles in European fleet tenders.
Industry Challenges
- Power Electronics Talent Scarcity:Shortage of engineers proficient in wide-bandgap semiconductor thermal modeling delays product development cycles for Tier 2 suppliers.
- Multi-Physics Simulation Complexity:Coupled electromagnetic-thermal-mechanical modeling requirements strain computational resources and extend validation timelines for integrated motor-transmission assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Drivetrain Systems Market |
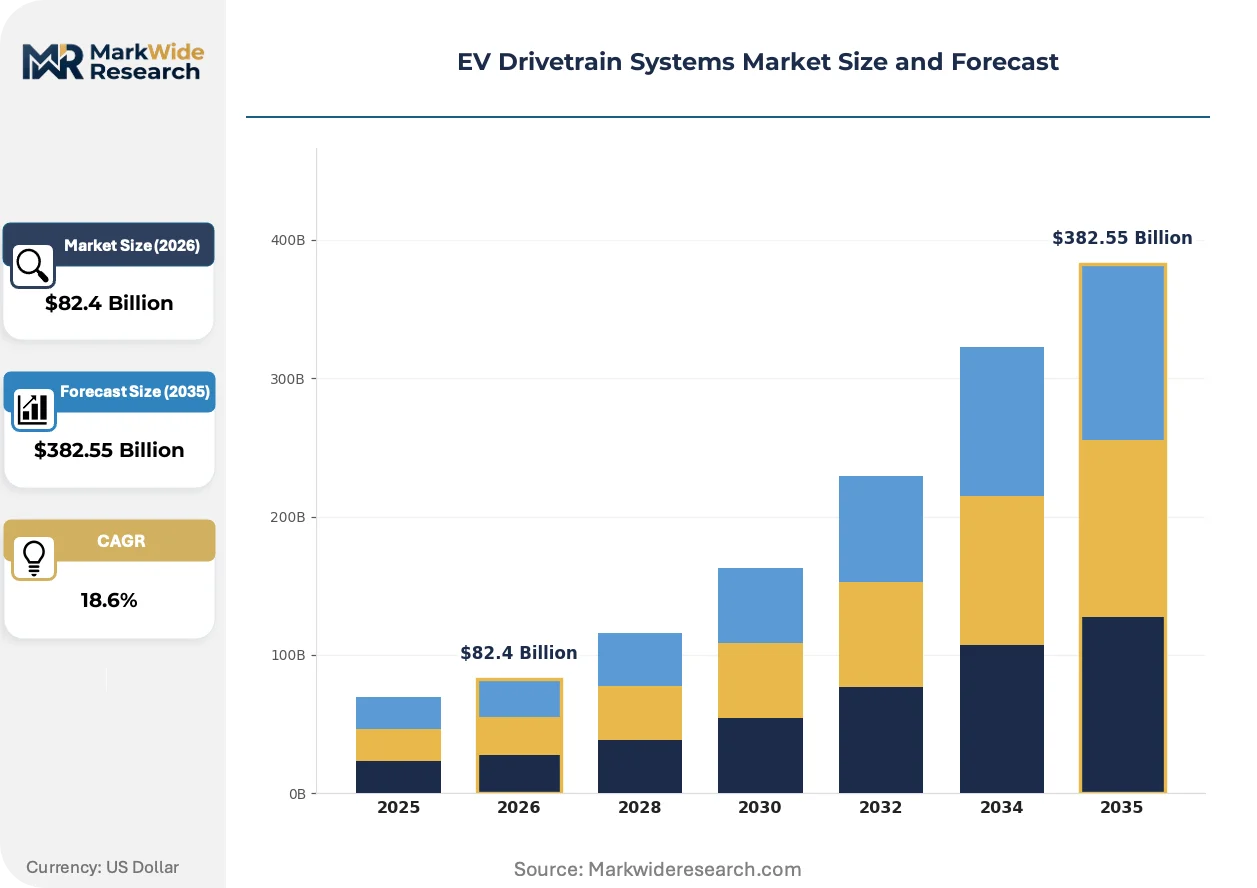
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $382.55 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motor, Transmission, Inverter, Battery Pack Technology: Direct Drive, Gear Reduction, Regenerative Braking, Thermal Management End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Operators Application: Lightweight Vehicles, Heavy-Duty Trucks, Urban Mobility, Robotics |
| Companies Covered | Magna International, Denso, Bosch, Hitachi Astemo, Infineon Technologies, Aptiv, Continental, BYD, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Drivetrain Systems Market Shifts & Advancements
Digital twin integration is compressing development cycles across the supplier base, while regulatory calibration between major automotive markets fragments certification requirements.
Silicon carbide MOSFETs replace insulated-gate bipolar transistors in traction inverters, enabling switching frequencies above 20 kHz. European luxury OEMs deploy these architectures first, accepting premium component costs for efficiency gains. This transition is digitizing thermal management control loops, replacing analog sensing with real-time predictive algorithms that optimize coolant flow.
EU Green Deal vehicle CO2 thresholds tighten annually through 2035, eliminating internal combustion powertrain compliance pathways for passenger car OEMs. Suppliers must certify motor-inverter combinations under WLTP test cycles or forfeit platform access. Heavy-duty segments face parallel pressure from EMA efficiency benchmarks, accelerating integrated e-axle adoption for regional delivery applications.
Fleet operators now unbundle drivetrain service contracts from vehicle acquisition, purchasing powertrain availability per kilometer rather than hardware ownership. Logistics consortia in Germany and the Netherlands pilot this model first, pressuring suppliers to guarantee uptime through predictive maintenance platforms. Urban transit agencies in Scandinavia follow, substituting capital expenditure with operational leasing for electric bus depots.
EV Drivetrain Systems Market Segmentation
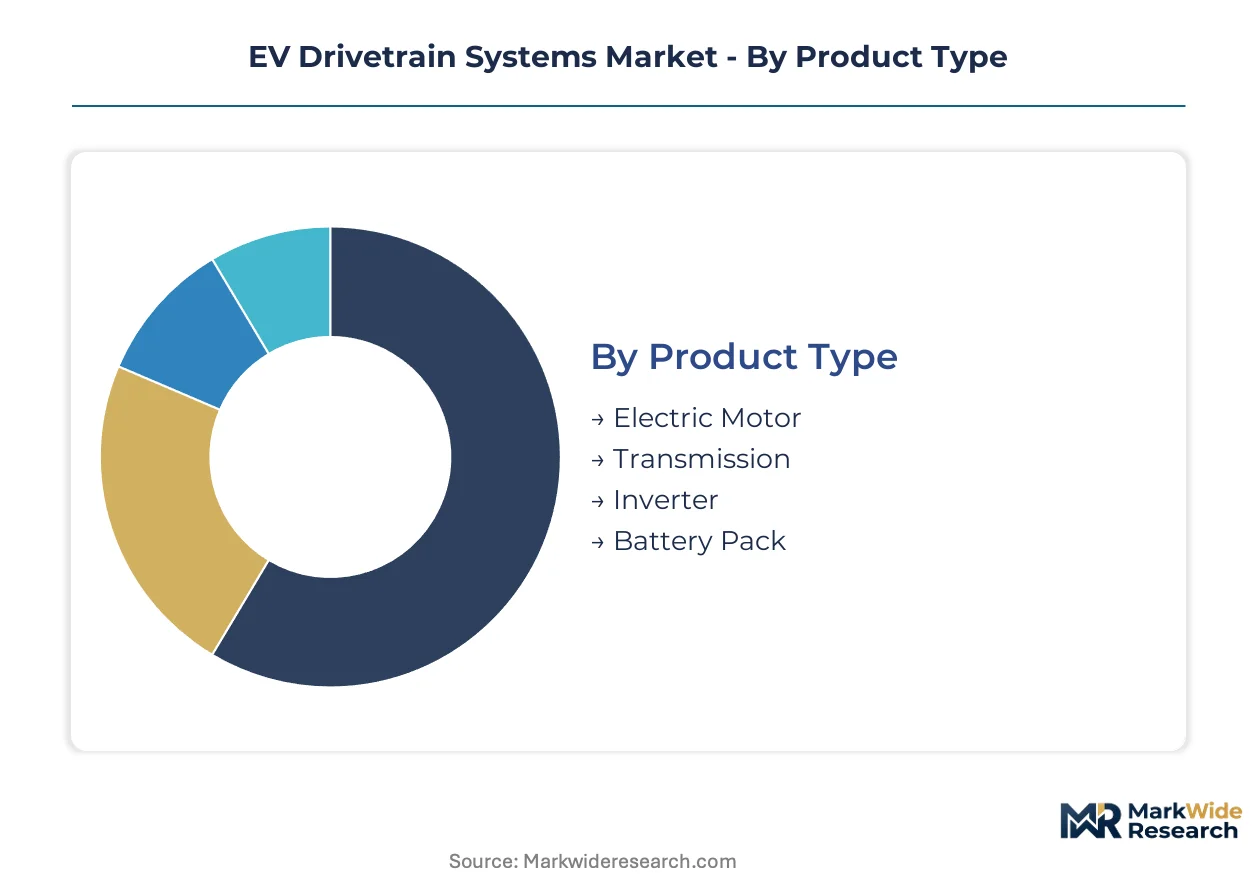
Drivetrain segmentation reveals where value concentrates across hardware hierarchies and which technology combinations command procurement premiums. Understanding these divisions exposes where suppliers can defend margin and where new entrants face the steepest technical barriers.
Product Type:
Mature motor and inverter architectures dominate commercial procurement, while emerging battery pack configurations reshape cost structures through cell-to-pack integration.
- Battery Pack:Cell-to-pack architectures eliminate module housings, reducing mass and thermal management complexity. Demand concentrates in heavy-duty truck applications where range requirements push energy density thresholds, with China's MIIT efficiency benchmarks accelerating adoption of integrated pack designs.
- Inverter:Silicon carbide switching frequencies now exceed 20 kHz, compressing energy losses below silicon thresholds. European logistics operators source these systems under long-term service contracts, prioritizing efficiency gains over upfront premiums.
- Electric Motor:Permanent magnet synchronous designs serve passenger and commercial platforms, though neodymium supply concentration in Chinese refining corridors exposes producers to quota volatility.
- Transmission:Gear reduction units occupy premium torque-density segments where mechanical efficiency thresholds are rising, with ZF Friedrichshafen specializing in this mechanical layer.
Battery Pack handles the majority of throughput; Inverter is the fastest mover on share.
Technology:
Cost tier differentiation separates premium wide-bandgap implementations from standard silicon architectures, with thermal management emerging as the critical margin pool.
- Thermal Management:Predictive algorithms now optimize coolant flow in real-time, replacing analog sensing loops. Power density requirements push cooling demands beyond conventional liquid loops, with European luxury OEMs digitizing control systems first.
- Direct Drive:Elimination of gear complexity reduces cost and maintenance for urban mobility applications. Transit agencies in Scandinavian cities pilot operational leasing models that favor these simplified architectures.
- Regenerative Braking:Energy recovery systems extend range in stop-start urban environments, with fleet operators capturing operational savings through reduced brake wear.
- Gear Reduction:Multi-speed transmissions serve heavy-duty applications where torque multiplication requirements exceed direct drive capabilities.
Direct Drive captures the highest volume deployment; Thermal Management is climbing the fastest on margin contribution.
End User:
Customer type stratification shows fleet operators unbundling service contracts from hardware acquisition, while passenger vehicle OEMs retain integrated sourcing.
- Fleet Operators:Asset-light leasing models for battery-drivetrain bundles rewrite competitive entry barriers, with logistics consortia in Germany and the Netherlands purchasing powertrain availability per kilometer rather than ownership.
- Commercial Vehicles:Class 8 truck electrification accelerates under EPA fleet emissions standards, compelling procurement of integrated motor-inverter systems for long-haul routes.
- Passenger Vehicles:OEMs source complete drivetrain modules from vertically integrated suppliers, with BYD controlling in-house motor and inverter production.
- Two-Wheelers:Cost-optimized direct drive systems serve urban delivery and personal mobility in dense Asian cities.
Commercial Vehicles anchor current revenue; Fleet Operators are expanding most quickly as service models proliferate.
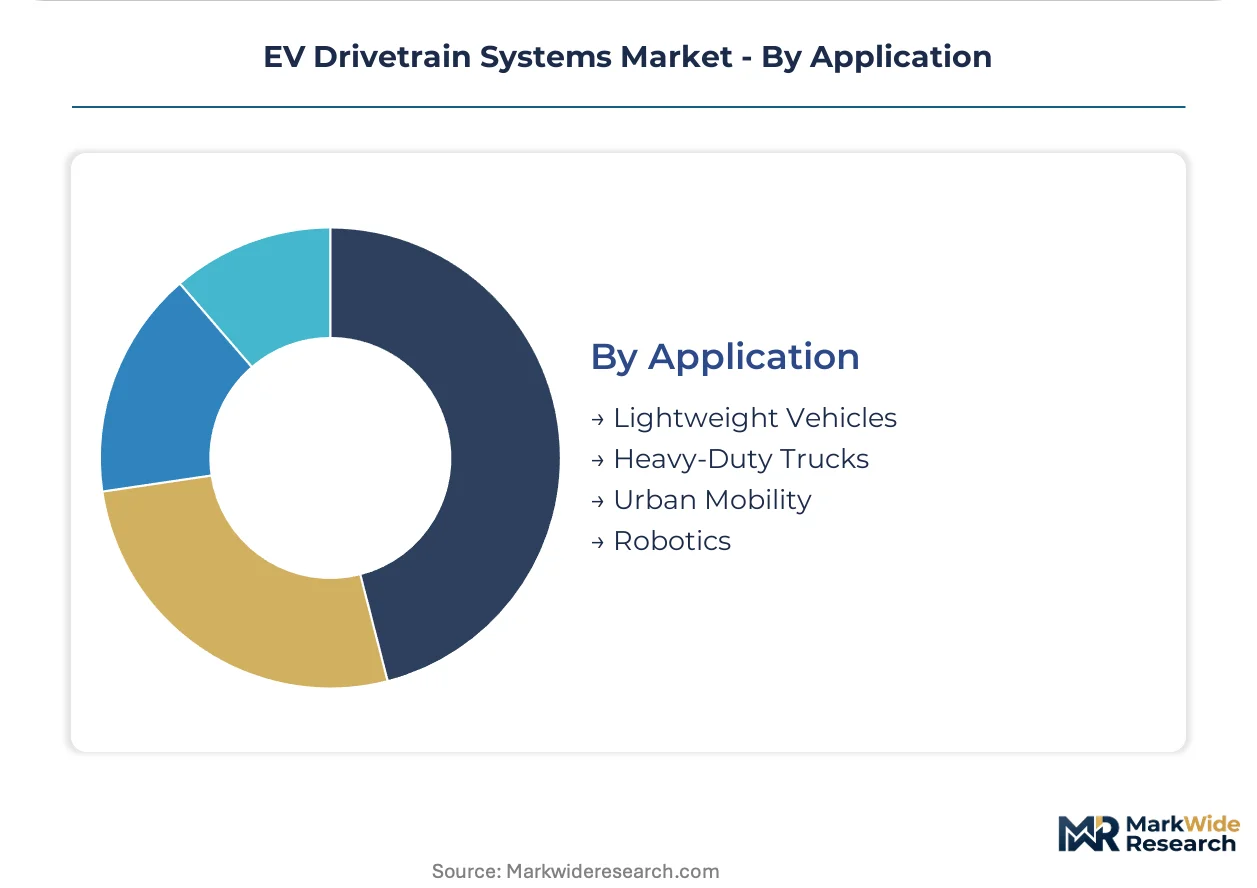
Application:
Geography-application coupling concentrates heavy-duty demand in Chinese mining and port logistics, while urban mobility drives standardization.
- Heavy-Duty Trucks:MIIT efficiency benchmarks for freight applications concentrate demand for high-torque integrated drivetrains. Mining and port logistics operations in China source these systems for electrified bulk transport.
- Urban Mobility:Transit buses and delivery vehicles favor simplified direct drive architectures. Wireless charging infrastructure at depot locations enables opportunity charging, reducing battery capacity requirements.
- Lightweight Vehicles:Passenger cars and small commercial vehicles prioritize energy density and packaging efficiency.
- Robotics:Precision torque control requirements drive adoption of compact integrated motor-inverter units for autonomous mobile platforms.
Heavy-Duty Trucks command the largest contract values; Urban Mobility is gaining share fastest through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade balances in EV drivetrain components tilt toward net exporters with captive silicon carbide wafer capacity and rare earth magnet processing infrastructure. Import-dependent markets face procurement premiums as supply corridors concentrate in specific manufacturing clusters.
United States
EPA fleet emissions standards compel Class 8 truck electrification, driving integrated motor-inverter procurement for long-haul routes. NHTSA fuel economy mandates enforce fleet-wide compliance thresholds. Detroit-Windsor automotive corridor anchors power electronics assembly for commercial vehicle platforms.
Germany
Logistics consortia in Bavaria and Baden-Württemberg pilot asset-light leasing models for battery-drivetrain bundles. EU Green Deal vehicle CO2 thresholds eliminate internal combustion compliance pathways through 2035. Stuttgart industrial cluster specializes in gear reduction systems for premium torque-density applications.
China
MIIT efficiency benchmarks for freight applications concentrate demand for high-torque integrated drivetrains in mining and port logistics. Dual carbon goals accelerate heavy-duty electrification timelines. Yangtze River Delta manufacturing bases dominate motor-inverter system output for domestic and export markets.
Japan
METI industrial policy directs semiconductor supply chain resilience investments toward wide-bandgap substrate production. JIS standards govern power electronics certification for automotive applications. Nagoya-Toyota City corridor integrates silicon carbide inverter fabrication with tiered supplier networks.
India
PLI scheme subsidies for automotive component manufacturing attract localized motor and gearbox assembly for intra-city freight. CEA grid modernization standards enable depot charging infrastructure at commercial vehicle hubs. Tamil Nadu and Gujarat industrial corridors host emerging drivetrain integration facilities.
EV Drivetrain Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power electronics and precision mechanical layers. The vendor base stratifies across three tiers: vertically integrated automotive OEMs, Tier 1 module suppliers, and Tier 2 semiconductor fabricators. Dominant archetypes include captive producers controlling magnet and wafer supply, independent integrators assembling multi-source subsystems, and fabless designers licensing inverter topologies. Competitive moves center on backward integration into silicon carbide substrate production and long-term service contract anchoring with fleet operators.
Among German-based industrial conglomerates, Bosch and ZF Friedrichshafen exemplify divergent specialization paths—one anchoring power electronics manufacturing scale, the other occupying gear reduction mechanical layers. BYD represents the vertically integrated OEM archetype with in-house motor and inverter production. Continental and Denso sit within the Tier 1 module supplier tier, assembling multi-source component streams into certified drivetrain bundles for platform customers.
| Leading Market Players |
|---|
| Magna International |
| Denso |
| Bosch |
| Hitachi Astemo |
| Infineon Technologies |
| Aptiv |
| Continental |
| BYD |
| ZF Friedrichshafen |
| Others |
Supply & Pricing Matrix
Neodymium export quota volatility from Chinese refining corridors compresses margin spreads between permanent magnet motor tiers while forcing buyers toward silicon carbide inverter alternatives that bypass rare earth dependencies. This single-source magnet concentration simultaneously widens pricing gaps between certified and uncertified drivetrain bundles and reshapes procurement geography toward wafer-fabrication clusters in Japan and Germany.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled rebates for Class 8 truck platforms. Price differentiation separates WLTP-certified motor-inverter combinations from uncertified alternatives through efficiency tiering, with European logistics consortia accepting premiums for guaranteed uptime clauses. Cost compression in standard silicon architectures is intensifying because 800V platform adoption accelerates obsolescence risk. Fleet operators exhibit highest price sensitivity on upfront hardware, while luxury passenger OEMs prioritize efficiency metrics over capital outlay.
Supply Chain Analysis
TSMC and Infineon's Dresden facility anchor silicon carbide wafer fabrication capacity, with substrate bottlenecks concentrating output in Taiwan, Germany, and Japan. The drivetrain ecosystem draws from neodymium magnet processing in China's Yangtze River Delta, copper winding supplies from Chilean mining corridors, and epoxy resin feedstocks from South Korean petrochemical complexes. Single-source vulnerability in rare earth refining exposes motor producers to quota-driven price spikes. Distribution runs through Tier 1 module assemblers who bundle multi-source components into platform-certified systems for OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator unbundling of hardware ownership from service contracts fragments procurement authority, creating specialist niches for predictive maintenance platforms and localized assembly operations.
For Market Incumbents: Entrench silicon carbide fabrication scale through captive wafer supply agreements with Japanese substrate producers, insulating margin from supply bottlenecks that constrain Tier 2 competitors. Deepen backward integration into thermal management control software, converting hardware sales into recurring service revenue streams that lock out modular assemblers lacking predictive algorithm capabilities. For New Entrants and Emerging Players: Pursue wireless charging infrastructure integration for urban transit depots, where Scandinavian municipalities pilot opportunity-charging architectures that reduce battery capacity requirements. Target India's intra-city freight segment, where PLI scheme subsidies lower capital barriers for localized motor-gearbox assembly. Lead with operational leasing propositions that substitute per-kilometer availability guarantees for capital equipment sales. For Investors and Strategic Acquirers: EPA fleet emissions standards reshapes the acquisition landscape toward suppliers with certified 800V platform access and long-haul trucking service contract anchoring. Five-to-ten year viability favors fabless inverter designers licensing topologies to manufacturers with captive silicon carbide capacity, rather than capital-intensive fabricators facing substrate scarcity. Monitor MIIT efficiency benchmark calibration for heavy-duty applications as the signal indicating Chinese demand inflection for integrated mining and port logistics drivetrains.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Wafer Supply Agreement | Captive substrate access from Japanese producers secures inverter production scaling ahead of 800V platform adoption. |
| Predictive Maintenance Platform Launch | Real-time thermal algorithm deployment converts German logistics consortia from transactional buyers to service subscribers. |
| Wireless Charging Infrastructure Partnership | Inductive depot integration with Scandinavian transit agencies reduces battery capacity requirements and drivetrain cost structure. |
| Localized Assembly Facility in India | PLI scheme qualification for Tamil Nadu motor-gearbox integration captures intra-city freight electrification subsidies. |
| EU Battery Passport Compliance Investment | CSRD traceability certification differentiates integrated drivetrain bundles in European fleet tenders requiring carbon accounting. |
Research Methodology
Desk research of SEC automotive supplier filings, MIIT efficiency benchmark documentation, and EU Green Deal regulatory texts preceded structured interviews with Tier 1 procurement directors, OEM platform engineers, fleet operations managers, and power electronics R&D leads. Bottom-up triangulation of component-level production data with top-down validation against vehicle registration databases anchored volume estimates across the analysis window.
Assumptions held EPA fleet emissions standards and EU CO2 thresholds fixed at announced calibration levels, while varying silicon carbide wafer supply elasticity and neodymium export quota stringency across sensitivity scenarios. Segmentation modeling incorporated vehicle class, propulsion architecture, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion curves fitted to historical electrification adoption patterns, with inputs from charging infrastructure buildout trajectories and battery cell cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration into silicon carbide substrate production by automotive OEMs would shift outcomes toward captive supply and margin compression for independent inverter suppliers. Quarterly review of MIIT benchmark updates, EPA enforcement discretion, and silicon carbide wafer spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive PTC Heaters Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
LNG Engine Market
Powertrain
Crate Engines Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Iridium Spark Plug Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Engine Rocker Arm Market
Powertrain
United States Automotive Engine Oils Market