
 North America Automotive Foams Market | 2026-2036
North America Automotive Foams Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Foams Market Intelligence
Midwest chemical producers is repositioning capacity toward low-VOC polyurethane systems for EV interior programs. BASF SE leverages its integrated polyol supply chain to serve Detroit-area OEMs directly. Huntsman Corporation sustains technical leadership in MDI-based formulations for noise-critical applications. Woodbridge Foam Corporation anchors regional supply through its Ontario manufacturing base and captive seating assembly operations.
North America automotive foams comprise cellular polymer structures—primarily polyurethane, polyethylene, and polypropylene variants—engineered to densities between 20-80 kg/m³ for energy absorption, acoustic damping, and thermal management in vehicle cabins and powertrain compartments. Polyurethane formulations dominate value contribution due to their tunable hardness ranges and established molding compatibility with just-in-time seating production. Flexible foam configurations lead volume demand from OEM seating contracts, while laminated structures capture expanding share in battery pack thermal barriers where multi-layer insulation properties command specification premiums.
EPA tailpipe emission targets and NHTSA crashworthiness standards jointly elevate foam density and flame-retardancy requirements, forcing reformulation cycles every three to five years. California Air Resources Board low-emission vehicle rules extend these mandates to interior air quality, restricting volatile organic compound release from dashboard and door panel substrates. Stakeholders must monitor pending revisions to Federal Motor Vehicle Safety Standard 302 and corresponding state-level adoption timelines to align R&D pipelines with compliance windows.
Market Dynamics
EPA fuel economy mandates and NHTSA crashworthiness standards are compressing foam density specifications while simultaneously demanding enhanced flame-retardancy, forcing simultaneous lightweighting and safety upgrades across seating and battery thermal barrier applications.
Growth Catalysts
- EV Seating Programs:Electric vehicle platforms require redesigned interior architectures with integrated thermal management, expanding foam specification volumes beyond traditional internal combustion vehicle programs.
- Federal Motor Vehicle Safety Standard 302:Pending revisions to this NHTSA regulation accelerate reformulation investments toward low-emission, high-ignition-resistant polyurethane systems.
- Michigan-Ontario Assembly Corridor:Concentrated OEM final assembly capacity within this 400-mile manufacturing belt sustains just-in-time foam delivery requirements and captive molding operations.
Market Restraints
- Polyol Feedstock Volatility:Propylene oxide and toluene diisocyanate pricing fluctuations compress margin stability for formulation specialists serving Detroit-area Tier 1 suppliers.
- Supplier Concentration Risk:MDI supply chains concentrate among three global chemical producers, exposing regional foam molders to allocation constraints during upstream petrochemical disruptions.
- Technical Limitation:Current bio-based polyol alternatives fail to meet simultaneous low-VOC and high-durability specifications required for 10-year/150,000-mile seating warranties.
Strategic Opportunities
- Mexico Assembly Expansion:Greenfield EV production facilities in Nuevo León and Guanajuato create demand for localized foam compounding and just-in-sequence seating module supply.
- Battery Pack Thermal Barriers:Multi-layer laminated foam structures command specification premiums in electric vehicle powertrains where cell-to-pack architectures require compression-resistant insulation.
- California Air Resources Board Credits:Low-emission vehicle scoring systems incentivize OEMs to specify interior foams meeting sub-50 microgram/m³ VOC thresholds, creating tiered supplier qualification advantages.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Regional universities produce insufficient polyurethane systems engineers to staff R&D labs serving simultaneous EPA, NHTSA, and CARB compliance cycles.
- Dual Certification Timelines:Parallel validation of foam systems against FMVSS 302 and SAE J1756 interior air quality standards extends product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Foams Market |
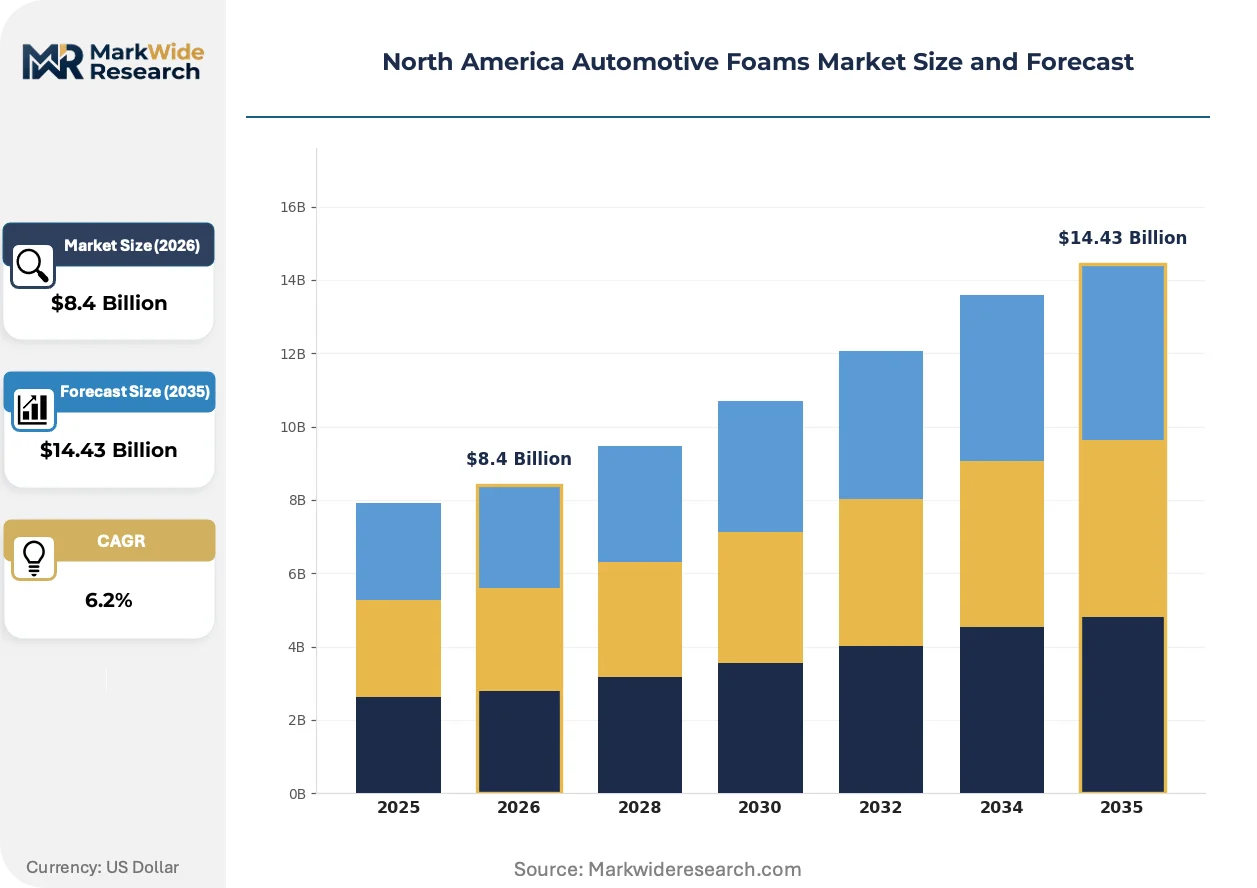
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyethylene, Polypropylene, Melamine Form: Flexible, Rigid, Spray Foam, Laminated Feature: Noise Reduction, Thermal Insulation, Lightweight, Durability End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Rogers Corporation, Bridgestone Corporation, BASF SE, Huntsman Corporation, Covestro AG, Dow Inc., Saint-Gobain, Recticel, Woodbridge Foam Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Foams Market Strategic Shifts & Innovations
Formulation chemistry and manufacturing process control are converging to enable density-graded foam structures that satisfy conflicting lightweighting and acoustic performance targets without material stacking.
Water-blown polyurethane systems with tunable cell morphology are unifying previously separate comfort and structural functions within single molded seating components. Tier 1 suppliers serving Detroit OEMs are adopting these platforms at accelerated qualification paces. This convergence is compressing part counts and assembly labor content while expanding design freedom for interior space optimization.
NHTSA's pending updates to Federal Motor Vehicle Safety Standard 302 are mandating self-extinguishing foam behavior within shorter ignition exposure windows. The regulation forces abandonment of legacy halogenated flame retardants in favor of phosphorus-nitrogen synergist packages. Seating programs for full-size pickup trucks face the steepest compliance gradients given their higher foam volumes and extended cabin exposure scenarios.
Fleet procurement departments at rental car operators and commercial vehicle lessors are consolidating supplier relationships around foam systems offering documented recyclability pathways. Long-term lease residuals now incorporate end-of-life material recovery values, displacing lowest-first-cost sourcing logic. This behavioral pivot is most pronounced among California-based fleet managers responding to state landfill diversion mandates.
North America Automotive Foams Market Segmentation
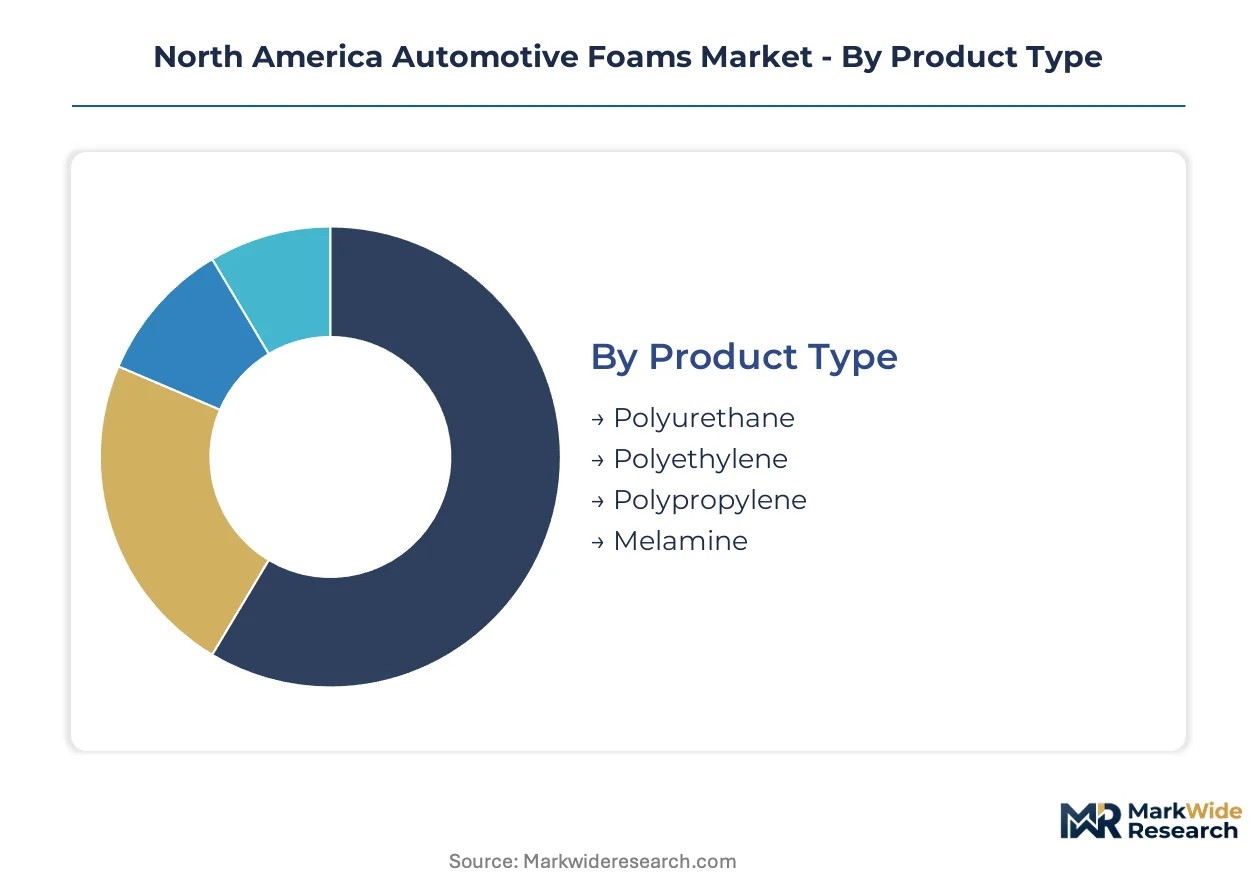
Segmentation in North American automotive foams reflects divergent technical requirements across powertrain architectures and regulatory compliance tiers. Buyers prioritize density specifications, flame-retardancy ratings, and VOC emission profiles when selecting formulations for seating versus battery thermal management applications.
Product Type:
Material selection hinges on load-bearing requirements and molding process compatibility with just-in-time assembly schedules.
- Polyurethane:Tunable hardness ranges between 20-80 kg/m³ enable simultaneous comfort and structural integration in molded seating components. Michigan and Ontario OEMs specify these systems for EV interior programs where thermal management integration demands multi-functional substrates.
- Polyethylene:Closed-cell structures deliver compression resistance for battery pack insulation layers where cell-to-pack architectures require dimensional stability under thermal cycling. Nuevo León assembly facilities are expanding specification volumes for this segment.
- Polypropylene:Lightweight thermoplastic foams serve bumper core and interior trim applications with established recycling pathways meeting California landfill diversion mandates.
- Melamine:Open-cell acoustic foams address NHTSA noise regulations in engine bay and cabin applications with superior fire resistance characteristics.
Polyurethane leads on scale; polyethylene leads on momentum.
Form:
Physical configuration determines manufacturing integration depth and labor content in final assembly operations.
- Flexible:Compression-molded seating cushions dominate volume demand from Detroit-area Tier 1 suppliers serving full-size pickup and SUV platforms. Water-blown cell morphology advancements are unifying comfort and structural functions within single components.
- Laminated:Multi-layer structures capture specification premiums in battery thermal barriers where compression-resistant insulation properties command qualification advantages. Guanajuato EV facilities are accelerating adoption.
- Rigid:Structural foam cores support interior trim panels and load floors with reduced part counts versus traditional multi-piece assemblies.
- Spray Foam:In-situ application methods serve aftermarket repair and niche OEM applications requiring cavity-filling precision.
Flexible foam commands installed base; laminated structures are climbing the fastest.
Feature:
Performance attributes align with concurrent EPA fuel economy and NHTSA safety mandates that compress specification windows.
- Lightweight:Density reduction targets of 15-30% versus legacy formulations address CAFE compliance without sacrificing structural integrity. Seating programs for electric vehicles prioritize mass reduction to offset battery weight penalties.
- Thermal Insulation:Multi-layer foam barriers manage cell-to-pack thermal propagation risks in battery architectures. OEMs specify these systems for 10-year/150,000-mile warranty alignment.
- Noise Reduction:Acoustic damping specifications intensify as cabin architectures eliminate internal combustion masking effects. Full-size pickup trucks face steepest compliance gradients given extended cabin exposure scenarios.
- Durability:Long-cycle fatigue resistance supports fleet procurement requirements where lease residuals incorporate end-of-life material recovery values.
Lightweight leads on scale; thermal insulation leads on momentum.
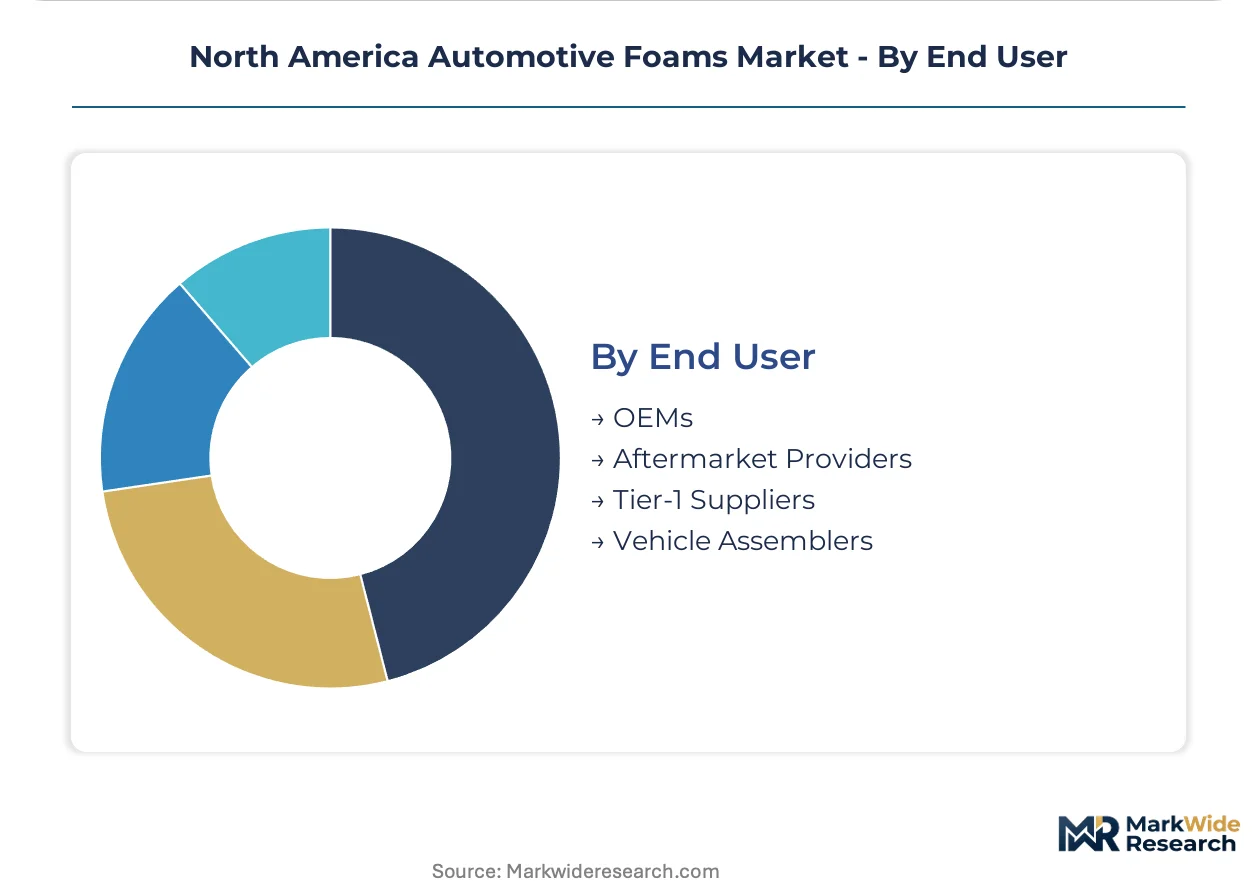
End User:
Procurement authority concentration shapes supplier qualification timelines and contract structures across the value chain.
- OEMs:Direct material specification authority at Ford, General Motors, and Stellantis facilities drives formulation standardization and volume commitments. These buyers mandate simultaneous FMVSS 302 and SAE J1756 compliance extending qualification windows.
- Tier-1 Suppliers:Woodbridge Foam Corporation and similar specialists manage captive molding operations with just-in-sequence delivery obligations to Michigan-Ontario assembly corridors.
- Vehicle Assemblers:Contract manufacturing operations in Mexico consolidate demand for localized compounding capacity serving Nuevo León and Guanajuato greenfield facilities.
- Aftermarket Providers:Independent distributors serve collision repair and refurbishment channels with less stringent certification requirements than OEM programs.
OEMs lead on scale; Tier-1 suppliers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography across North America as OEMs migrate assembly toward jurisdictions with streamlined environmental permitting and lower labor-cost structures for foam-intensive seating and battery thermal barrier programs.
United States
Michigan anchors domestic polyurethane demand through Detroit-area OEM final assembly corridors where just-in-time foam delivery requirements sustain captive molding operations. EPA fuel economy mandates and NHTSA crashworthiness standards compress specification windows for seating programs. The Ohio-Indiana manufacturing belt is expanding water-blown polyurethane capacity to serve full-size pickup and SUV platforms with unified comfort-structural components.
Canada
Ontario's automotive assembly corridor sustains integrated foam supply chains through direct pipeline connections to Michigan OEM facilities. Health Canada and Environment and Climate Change Canada regulations on volatile organic compound emissions align with California Air Resources Board thresholds, qualifying Canadian-produced foams for cross-border OEM programs. Woodbridge Foam Corporation anchors regional supply through its Ontario manufacturing base and captive seating assembly operations serving Detroit-area customers.
Mexico
Nuevo León and Guanajuato greenfield EV facilities are consolidating demand for localized polyethylene foam compounding and just-in-sequence seating module supply. Mexico's federal environmental regulator SEMARNAT maintains streamlined permitting timelines for low-VOC polyurethane systems compared to US state-level approval processes. The Bajío Region is attracting Tier-1 foam molders seeking proximity to Stellantis and BMW assembly operations with reduced logistics costs versus Michigan-Ontario supply routes.
California
California Air Resources Board low-emission vehicle rules restrict volatile organic compound release from dashboard and door panel substrates, creating specification premiums for sub-50 microgram/m³ foam systems. Fleet procurement departments at rental car operators and commercial vehicle lessors headquartered in the state are consolidating supplier relationships around documented recyclability pathways. The Los Angeles-Inland Empire logistics corridor channels compliant foam imports to West Coast OEM distribution centers.
North America Automotive Foams Market Key Industry Players
Michigan-Ontario producers anchor one tier; Germany-based chemical conglomerates and Belgian specialists hold formulation technology leadership through integrated polyol supply chains and MDI-based systems engineering. The market structure concentrates around three global chemical producers supplying MDI feedstock to regional foam molders, with captive molding operations at Tier-1 suppliers compressing independent converter margins. Strategic archetypes include integrated chemical producers with backward polyol control, regional foam specialists with just-in-sequence assembly capabilities, and diversified materials conglomerates with cross-sector technology transfer. Dominant competitive moves center on capacity repositioning toward low-VOC polyurethane systems and qualification investments for battery pack thermal barrier specifications.
Within the integrated chemical producer tier, BASF SE and Huntsman Corporation exemplify divergent strategic positions. BASF SE leverages its integrated polyol supply chain to serve Detroit-area OEMs directly, occupying a position that bridges feedstock security and formulation proximity. Huntsman Corporation sustains technical leadership in MDI-based formulations, representing the specialist archetype focused on noise-critical applications. Woodbridge Foam Corporation anchors regional supply through its Ontario manufacturing base, sitting within the captive molding tier that controls just-in-time delivery obligations to Michigan-Ontario assembly corridors.
| Leading Market Players |
|---|
| Rogers Corporation |
| Bridgestone Corporation |
| BASF SE |
| Huntsman Corporation |
| Covestro AG |
| Dow Inc. |
| Saint-Gobain |
| Recticel |
| Woodbridge Foam Corporation |
| Others |
Cost & Logistics Intelligence
Propylene oxide pricing indices cascade through North American automotive foam supply chains, compressing margins at formulation specialists while concentrating pricing power among integrated polyol producers serving Detroit-area OEMs directly.
Pricing Analysis
Distributor markups of 12-18% separate captive Tier 1 molders from independent converters lacking backward integration into polyol production. Pricing stratifies across premium low-VOC certification tiers, standard FMVSS 302-compliant formulations, and economy-grade aftermarket replacements. Cost compression in standard-grade seating foams is intensifying because MDI feedstock allocations favor high-volume contract customers. Fleet procurement departments exhibit the highest price sensitivity, while OEM platform engineering teams prioritize qualification speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Belgian chemical conglomerates controlling MDI isocyanate supply to regional foam molders. Feedstock dependencies center on propylene oxide, toluene diisocyanate, and specialty flame-retardant packages sourced from Texas and Louisiana petrochemical corridors. Tariff exposure on European isocyanate imports threatens margin stability for Ontario-based converters. Distribution runs through just-in-sequence pipelines linking captive molding operations to Michigan-Ontario assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America automotive foams function as a stable compounder where regulatory compliance cycles create recurring reformulation demand that locks in supplier relationships across decade-long OEM platform lifecycles.
For Market Incumbents: Acquire captive seating assembly operations in Guanajuato to defend against Mexico-based EV production shifts. BASF SE and Huntsman Corporation should deepen backward integration into bio-based polyol R&D before 10-year seating warranties force specification switches. Priority rests on securing MDI allocation agreements with European feedstock suppliers during upstream petrochemical disruptions. For New Entrants and Emerging Players: Digital direct channels to aftermarket collision repair networks bypass OEM qualification barriers that extend 18-24 months. White-space concentration sits with battery pack thermal barrier laminates for Nuevo León EV facilities where localized compounding capacity remains underdeveloped. Target California-based fleet lessors demanding documented recyclability pathways with sub-50 microgram/m³ VOC certification. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap foam specialists possessing simultaneous FMVSS 302 and SAE J1756 dual certification capabilities. Long-term viability over a 5-10 year horizon favors Ontario-based molders with integrated pipeline connections to Michigan OEM corridors. Watch pending NHTSA flame-retardancy standard revisions as the inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Greenfield polyurethane compounding in Guanajuato serves BMW and Stellantis EV platforms with reduced logistics costs. |
| Backward Integration | In-house polyol production shields Detroit-area molders from propylene oxide price volatility and allocation constraints. |
| Green Manufacturing Transition | Water-blown systems eliminate halogenated flame retardants ahead of NHTSA standard revisions. |
| Long-term Supply Agreement | MDI offtake contracts with European isocyanate producers secure feedstock during petrochemical disruptions. |
| Joint Venture | Battery thermal barrier partnerships with cell-to-pack architecture specialists capture specification premiums. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and polyurethane formulation chemists with secondary validation against EPA emission filings, NHTSA safety standard dockets, ACC industry reports, and vehicle production databases. Bottom-up segment sizing triangulated against top-down market value estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-recovery normalization trends. Segmentation dimensions modeled include foam chemistry type, physical form configuration, performance feature tier, and end-user procurement authority across regional production clusters. CAGRs derived from fitted growth curves incorporating EV penetration rates, regulatory compliance cycle timing, and OEM platform launch schedules.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyol substitution would alter the outlook if durability specifications shift ahead of warranty alignment. Forecasts embed assumptions regarding NHTSA rulemaking timelines and CARB threshold stringency that regulatory delays could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Oil Filter Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Tow Bar Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market