
 South Korea Automotive Parts Aluminium Die Casting Market | 2026-2036
South Korea Automotive Parts Aluminium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Parts Aluminium Die Casting Market Analytics
The premium-commodity split in South Korean aluminium die casting is shifting toward structural differentiation. Tier-1 suppliers now face divergent tooling investments for EV-optimized thin-wall components versus conventional internal-combustion engine blocks. Dynacast International Inc. leverages its global tooling expertise to serve Korean OEM electrification programs, while NEMAK anchors regional supply through dedicated high-pressure die casting capacity in Chungnam province. Georg Fischer Ltd. competes on vacuum-assisted process control for porosity-critical battery housing applications.
South Korea Automotive Parts Aluminium Die Casting refers to the pressure-driven metal forming process wherein molten aluminium alloys—typically A380, ADC12, or Silafont-36 grades—are injected into hardened steel molds to produce net-shape automotive components with wall thicknesses below 3 millimeters. This process yields parts with tensile strengths exceeding 310 MPa while achieving weight reductions of thirty to fifty percent versus equivalent steel stampings, serving the primary purpose of vehicle lightweighting for fuel efficiency and electric range extension. High-Pressure Die Casting dominates current Korean output volume due to cycle-time advantages in mass-production environments, though Low-Pressure Die Casting is gaining structural share for complex EV battery tray geometries requiring minimal porosity. Engine Components retains the largest installed base but faces maturity pressure as powertrain electrification advances, while Transmission Housings experiences accelerated demand from multi-speed e-axle architectures in premium electric vehicles.
MFDS material certification protocols and KGS industrial safety standards govern alloy composition verification and workplace emissions in Korean die casting facilities, with MFDS traceability requirements now extending to recycled aluminium feedstock documentation. The Korea Automotive Testing and Research Institute enforces durability validation protocols that effectively gate market access for non-compliant foreign suppliers. Stakeholders must monitor evolving K-EV100 procurement mandates and battery enclosure crash-test criteria as these regulatory vectors increasingly determine which casting technologies and alloy specifications secure long-term platform awards from domestic OEMs.
Market Dynamics
Hyundai Motor Group's accelerated EV platform rollout is compressing die casting supplier qualification timelines while forcing simultaneous retooling for thin-wall structural components and legacy powertrain parts.
Growth Catalysts
- K-EV100 procurement mandates:Government-backed fleet electrification targets are locking in multi-year aluminium component contracts for domestic OEMs.
- Gyeonggi-Inchean corridor concentration:Proximity to Hyundai's Ulsan and Asan assembly plants reduces logistics costs for just-in-sequence die casting delivery.
- Silafont-36 alloy adoption:High-ductility grades enable single-piece battery tray designs that eliminate welded joints.
Market Restraints
- Primary aluminium price volatility:LME-linked ingot costs swing casting margins unpredictably for fixed-price OEM contracts.
- Tooling lead time bottleneck:H13 steel mold fabrication stretches 18-24 weeks, gating capacity expansion for new EV platform awards.
- MFDS traceability documentation:Recycled feedstock certification requirements add administrative overhead without direct price recovery mechanisms.
Strategic Opportunities
- Busan-Ulsan port expansion:New container terminal capacity positions Korean casters for ASEAN EV supply chain integration.
- Vacuum-assisted high-pressure die casting:Porosity reduction below 1% opens heat-treatable structural applications previously reserved for extrusions.
- KGS weight-reduction mandates:Stricter commercial vehicle axle load limits create pull for hollow-casting techniques in truck transmission housings.
Industry Challenges
- Process engineer scarcity:Vacancy rates exceed 15% for technicians qualified in both conventional HPDC and emerging rheocasting methods.
- Dual-certification timelines:Suppliers must simultaneously secure MFDS material approval and OEM-specific crash-test validation, stretching product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Parts Aluminium Die Casting Market |
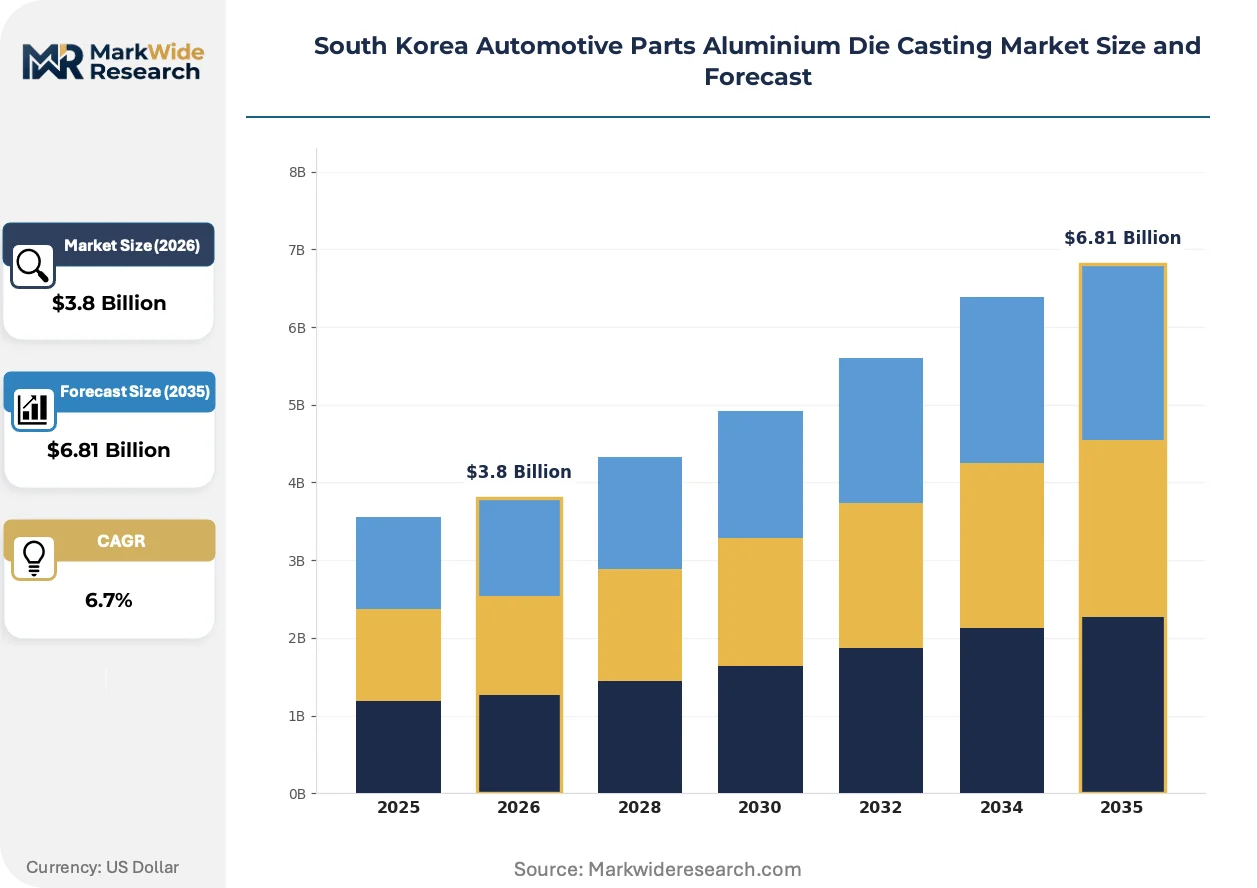
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Chassis Parts, Decorative Trim End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Dealerships Manufacturing Stage: Tooling, Production, Assembly, Finishing Technology: Low-Pressure Die Casting, High-Pressure Die Casting, Sand Casting, Permanent Mold Casting |
| Companies Covered | GIBBS, Dynacast International Inc., NEMAK, Jaya Hind Industries Ltd., Sipra Engineers Pvt. Ltd., Linamar Corporation, Endurance Technologies Limited, Sandhar Technologies Ltd., Georg Fischer Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Parts Aluminium Die Casting Market Evolving Landscape
Process control automation and alloy formulation advances are redefining quality thresholds for safety-critical EV structural castings, compressing the gap between prototype approval and mass production ramp.
Vacuum-assisted high-pressure die casting is overtaking conventional gravity and low-pressure methods for battery enclosure production. Hyundai and Kia's EV9 platform teams specify vacuum-drawn molds to achieve Class 1 porosity ratings required for liquid-cooled battery trays. This process shift is compressing the addressable market for traditional sand-casting suppliers while expanding tooling spend per vehicle.
MFDS recycled aluminium documentation rules are tightening alloy provenance requirements. Casters must now maintain batch-level traceability from smelter to finished component, with third-party verification mandatory for government fleet contracts. Tier-1 suppliers serving Hyundai's commercial vehicle division report 12-18 month compliance preparation periods.
Buyer concentration around Hyundai Motor Group is consolidating procurement leverage. Smaller Tier-2 casters face compressed payment terms and exclusive supply commitments that favor dedicated high-volume facilities over flexible job shops. This pattern is most visible in Chungnam province, where new capacity investments cluster within 50 kilometers of Kia's Hwasung plant.
South Korea Automotive Parts Aluminium Die Casting Market Segmentation
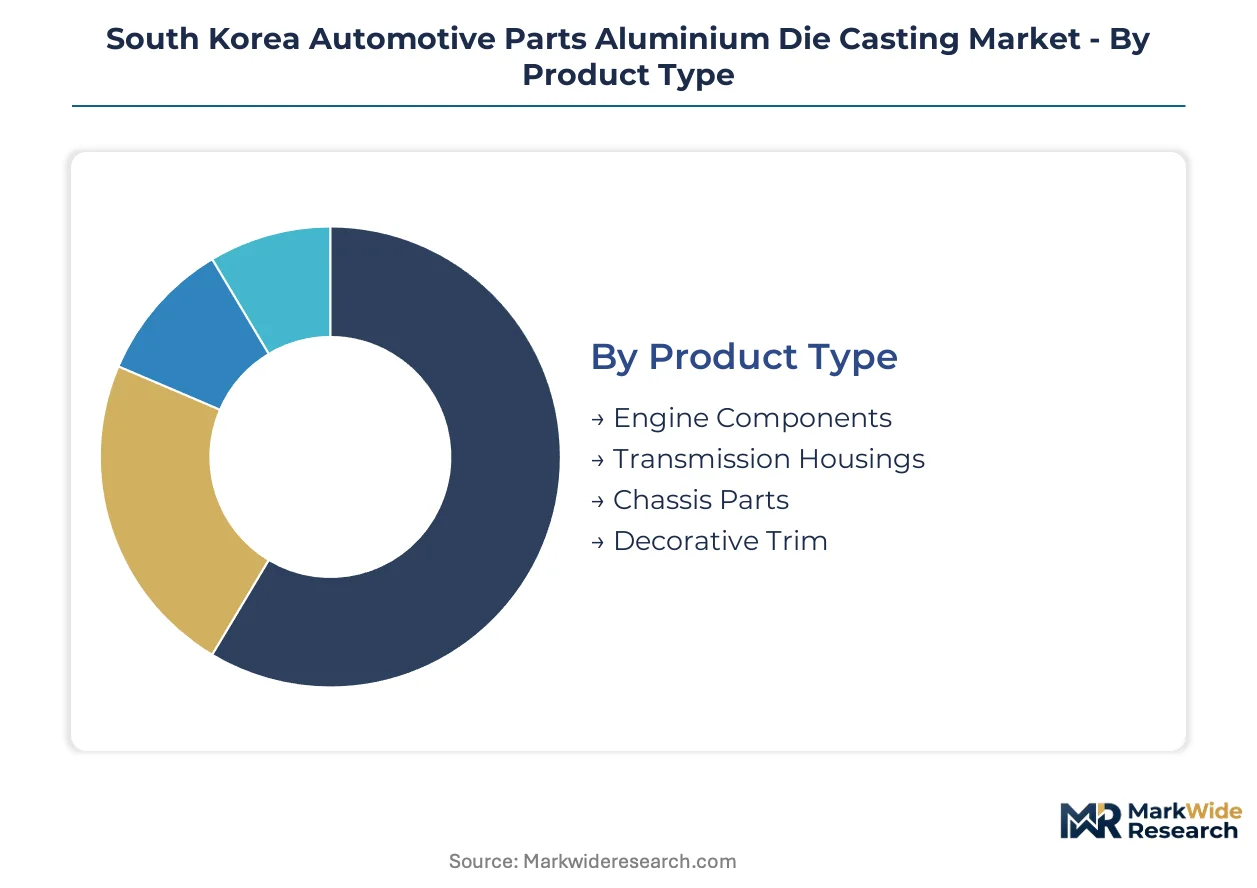
Die casting suppliers in South Korea navigate divergent tooling investments and qualification timelines across product architectures and customer tiers. Segment boundaries increasingly blur as EV platforms force simultaneous production of legacy internal-combustion components and thin-wall structural castings.
Product Type:
Technical specifications vary sharply between powertrain-anchored segments and emerging structural applications, with wall thickness and alloy ductility requirements driving process selection.
- Engine Components:Cylinder heads, engine blocks, and oil pans utilize ADC12 and A380 alloys with tensile strengths exceeding 310 MPa. Demand concentrates in Ulsan and Asan assembly corridors serving Hyundai Motor Group's remaining internal-combustion platforms. MFDS material certification timelines stretch 12-18 months for new alloy formulations.
- Transmission Housings:Multi-speed e-axle architectures in premium electric vehicles require complex geometries with integrated cooling channels. Kia's EV9 platform specifications favor vacuum-assisted high-pressure die casting to achieve Class 1 porosity ratings for liquid-cooled variants.
- Chassis Parts:Control arms and subframe nodes leverage Silafont-36 high-ductility grades for crash-energy absorption.
- Decorative Trim:Mirror housings and grille surrounds prioritize surface finish quality over mechanical loading.
Mature deployment sits with Engine Components. Newer deployment is concentrated in Chassis Parts.
End User:
Procurement leverage concentrates sharply around domestic OEMs, compressing margins for intermediary tiers while opening specialized niches for certified direct suppliers.
- OEMs:Hyundai Motor Group and Kia Corporation exercise consolidated purchasing power through dedicated high-volume platform awards. K-EV100 fleet mandates lock in multi-year aluminium component contracts with strict MFDS traceability requirements extending to recycled feedstock documentation.
- Tier-1 Suppliers:NEMAK and Dynacast International bridge OEM specifications with captive die casting capacity, absorbing tooling lead time bottlenecks of 18-24 weeks for H13 steel molds.
- Aftermarket Suppliers:Replacement engine blocks and transmission cases serve aging vehicle parc outside warranty coverage.
- Dealerships:Cosmetic trim replacements and collision repair components move through authorized service networks.
Volume concentrates with OEMs. Margin protection concentrates with Tier-1 Suppliers.
Manufacturing Stage:
Capital intensity escalates nonlinearly from design validation through mass production, with tooling fabrication representing the critical path for new platform awards.
- Tooling:H13 steel mold design and fabrication stretches 18-24 weeks, gating capacity expansion for EV-optimized thin-wall components. Vacuum-assisted process control adds 15-20% to per-cavity tooling costs.
- Production:High-pressure die casting dominates Korean output volume due to cycle-time advantages, achieving wall thicknesses below 3 millimeters for weight-critical applications.
- Assembly:Insert molding and mechanical joining integrate cast components with steel stampings and polymer subassemblies.
- Finishing:CNC machining, shot blasting, and anodizing prepare surfaces for sealing interfaces and cosmetic exposure.
Cycle time risk sits with Tooling. Quality yield risk sits with Finishing.
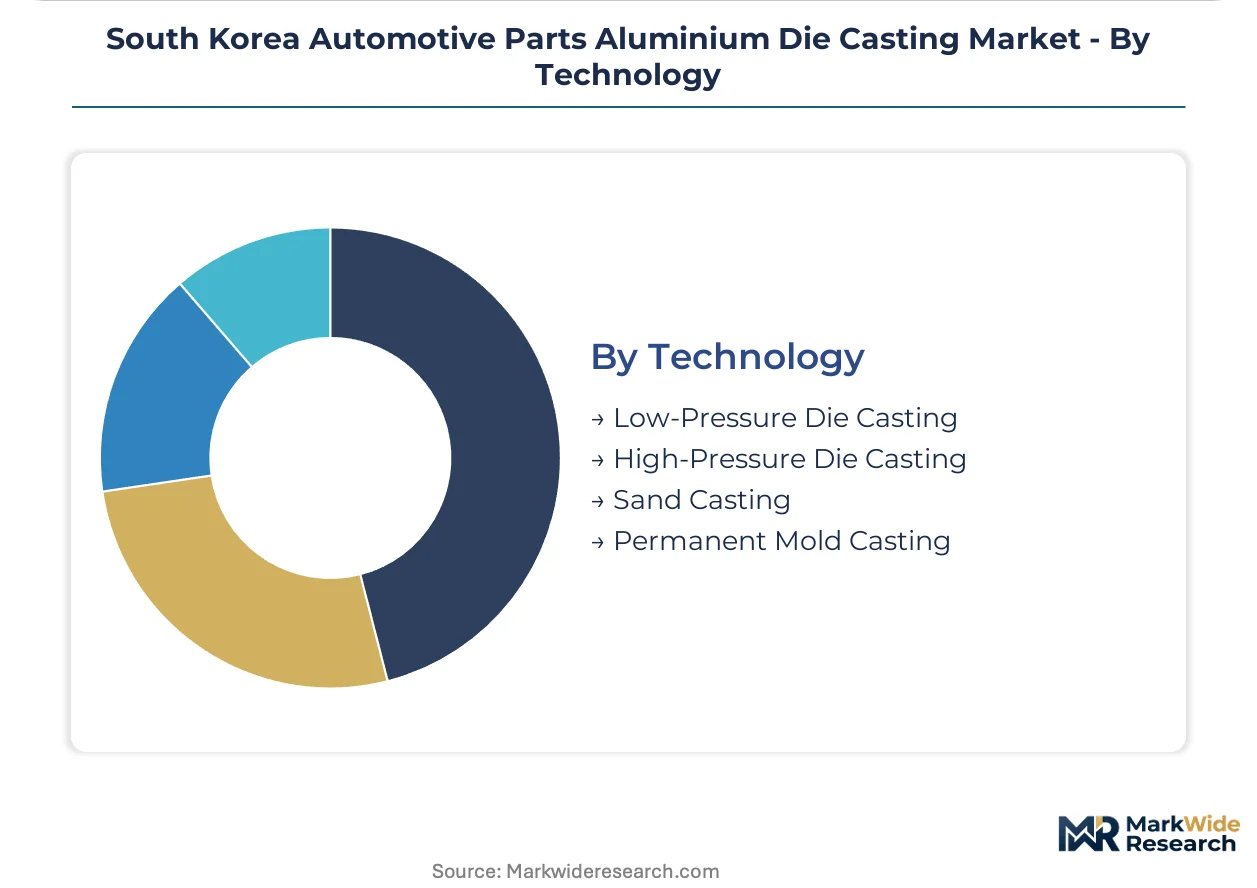
Technology:
Process selection pivots on porosity tolerance, with vacuum-assisted methods displacing conventional approaches for safety-critical battery and structural applications.
- High-Pressure Die Casting:Molten aluminium injection at pressures exceeding 1,000 bar achieves net-shape forming with 30-50% weight reduction versus steel equivalents. Hyundai and Kia EV9 platform teams specify vacuum-drawn mold variants to eliminate gas porosity in liquid-cooled battery trays.
- Low-Pressure Die Casting:Controlled fill rates minimize turbulence for complex EV battery tray geometries requiring weldable, heat-treatable microstructures. Chungnam province capacity investments cluster within 50 kilometers of Kia's Hwasung plant.
- Sand Casting:Prototype and low-volume production for legacy engine components with relaxed dimensional tolerances.
- Permanent Mold Casting:Gravity-fed processes for decorative trim with polished surface requirements.
Volume leadership sits with High-Pressure Die Casting. Fastest technology transition sits with Low-Pressure Die Casting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gyeonggi-Incheon manufacturing corridor anchors South Korean aluminium die casting activity, clustering high-pressure die casting capacity within 50 kilometers of Hyundai Motor Group's assembly complexes in Ulsan and Asan.
Seoul Capital Area
Hyundai Motor Group's headquarters procurement teams consolidate multi-year aluminium component contracts under K-EV100 fleet mandates. MFDS material certification requirements extend to recycled feedstock documentation for government fleet awards. Incheon's port infrastructure enables just-in-sequence die casting delivery to Asan assembly plants.
Busan-Ulsan
The Ulsan automotive complex generates concentrated demand for engine blocks and transmission housings on remaining internal-combustion platforms. KGS industrial safety standards govern workplace emissions in die casting facilities across the region. New container terminal capacity at Busan port positions regional casters for ASEAN EV supply chain integration.
Daejeon-Sejong
Chungnam province hosts dedicated high-pressure die casting investments clustering within 50 kilometers of Kia's Hwasung plant. Vacuum-assisted process control capacity expands for EV9 platform battery tray specifications. Korea Automotive Testing and Research Institute validation protocols gate market access for non-compliant suppliers.
Daegu-Gyeongbuk
Process engineer scarcity exceeds 15% vacancy rates for technicians qualified in both conventional HPDC and emerging rheocasting methods. Regional technical institutes struggle to match training output with Hyundai's compressed EV platform qualification timelines. Tooling lead time bottlenecks of 18-24 weeks for H13 steel molds constrain capacity expansion.
Gwangju-Honam
Smaller Tier-2 casters face compressed payment terms and exclusive supply commitments from Hyundai Motor Group procurement. Flexible job shops lose share to dedicated high-volume facilities capable of MFDS traceability compliance. Hollow-casting technique investments target KGS commercial vehicle axle load limit mandates.
South Korea Automotive Parts Aluminium Die Casting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and tooling investment thresholds. The supplier base stratifies between integrated Tier-1 systems providers and specialized die casting job shops. Three archetypes dominate: global tooling specialists with Korean electrification programs, regional high-volume capacity anchors, and vacuum-process control leaders for battery applications. Competitive moves concentrate on dedicated facility investments near Hyundai assembly clusters and dual-certification capability building for MFDS and OEM-specific validation.
Among global specialists serving Korean OEMs, Dynacast International Inc. and Georg Fischer Ltd. occupy positions in the premium-process tier, while NEMAK anchors regional supply through dedicated capacity investments. These three exemplify the tooling expertise and vacuum-assisted process control capabilities required for EV-optimized thin-wall structural components and porosity-critical battery housing applications.
| Leading Market Players |
|---|
| GIBBS |
| Dynacast International Inc. |
| NEMAK |
| Jaya Hind Industries Ltd. |
| Sipra Engineers Pvt. Ltd. |
| Linamar Corporation |
| Endurance Technologies Limited |
| Sandhar Technologies Ltd. |
| Georg Fischer Ltd. |
| Others |
Value Network & Pricing Analysis
K-EV100 fleet electrification mandates gate qualified supplier access and premium-tier contract awards for South Korean die casters. MFDS recycled aluminium documentation requirements filter Tier-2 job shops from government procurement pools, compressing margin recovery for non-compliant producers while consolidating pricing power among certified high-volume facilities.
Pricing Analysis
Yield-guaranteed tooling contracts anchor value-based pricing for vacuum-assisted high-pressure die casting capacity serving Hyundai Motor Group EV platforms. Three-tier pricing structure across MFDS-certified premium, OEM-validated standard, and uncertified economy levels separates battery tray suppliers from engine block casters from decorative trim job shops. Cost compression in economy-tier legacy powertrain components intensifies as domestic OEMs shift procurement toward thin-wall structural castings. Tier-1 systems suppliers exercise least price sensitivity due to exclusive platform awards, while flexible job shops face acute margin pressure from compressed payment terms.
Supply Chain Analysis
Process engineer vacancy rates exceeding fifteen percent across Gyeonggi-Incheon and Chungnam province constrain H13 steel mold fabrication capacity expansion. Primary aluminium ingot supply draws from Australian bauxite smelters and domestic Korean secondary refineries, with LME-linked pricing tethering casting margins to commodity volatility. Single-source vulnerability concentrates in vacuum-assisted tooling imports from German and Japanese specialist manufacturers. Distribution runs through just-in-sequence delivery corridors radiating from Hyundai's Ulsan and Asan assembly complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea automotive parts aluminium die casting market is a vertical-integration race where captive alloy recycling and in-house vacuum tooling fabrication determine long-term platform access. Control over upstream Silafont-36 formulation and downstream MFDS certification timelines separates sustainable margin positions from commodity-exposed suppliers.
For Market Incumbents: Deepen backward integration into secondary aluminium smelting to secure MFDS traceability compliance and insulate margins from LME price swings. Expand dedicated vacuum-assisted high-pressure die casting capacity within fifty kilometers of Kia's Hwasung plant to capture EV9 platform volume commitments. Lock in exclusive multi-year tooling partnerships with H13 steel mold fabricators to defend against eighteen-to-twenty-four week lead time bottlenecks gating competitor capacity additions. For New Entrants and Emerging Players: Enter via hollow-casting technique specialization targeting KGS commercial vehicle axle load mandates, where incumbent capacity concentration remains lowest. Focus initial qualification efforts on aftermarket transmission housing replacement demand outside Hyundai Motor Group procurement leverage. Pursue direct OEM engagement through Korea Automotive Testing and Research Institute pre-validation rather than Tier-1 supplier sub-contracting channels. For Investors and Strategic Acquirers: Hyundai Motor Group's announcement of dedicated EV platform annual production targets is the leading indicator that certified vacuum-process capacity will command scarcity premiums across the analysis window. Acquisition targets should prioritize mid-cap casters with existing MFDS material approval and unfilled land positions in Chungnam province for expansion. Monitor Busan port container terminal utilization rates as the leading signal for ASEAN supply chain integration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Aluminium Smelting | MFDS traceability compliance secures government fleet contract eligibility against commodity price volatility. |
| Vacuum-Assisted HPDC Capacity Expansion | Class 1 porosity ratings unlock EV9 battery tray specifications from Hyundai and Kia platform teams. |
| H13 Steel Mold Fabrication Partnership | Eighteen-to-twenty-four week tooling lead times gate competitor capacity additions for new platform awards. |
| Geographic Consolidation in Chungnam Province | Proximity to Kia's Hwasung plant enables just-in-sequence delivery with logistics cost advantages. |
| Rheocasting Process Engineer Training Program | Fifteen percent vacancy rates for qualified technicians constrain industry-wide capacity expansion timelines. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and MFDS regulatory affairs specialists underwrites the qualitative findings in this study. Primary fieldwork with die casting plant managers, H13 steel mold fabricators, and Korea Automotive Testing and Research Institute validation officers combined with secondary analysis of K-EV100 procurement mandate filings, customs aluminium ingot import records, and Hyundai Motor Group supplier qualification documents. Bottom-up capacity assessments across Gyeonggi-Incheon and Chungnam province facilities triangulated against top-down OEM platform production schedules.
Rate-of-change decomposition across the projection horizon separates volume growth from alloy mix shifts and process technology transitions. Segmentation modeling incorporates product type, end user tier, manufacturing stage capital intensity, and vacuum-assisted versus conventional high-pressure die casting technology splits. CAGRs derive from production-weighted average content per vehicle trajectories under electrification scenarios, with Silafont-36 adoption curves and hollow-casting penetration rates serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under primary aluminium price spike conditions or Hyundai Motor Group platform timeline acceleration. Material deviation in MFDS certification timeline extensions, K-EV100 mandate enforcement intensity, or ASEAN EV export quota allocations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Car Rack Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Automotive Piston Engine System Market