
 Passenger Car Wiper Blade Market | 2026-2036
Passenger Car Wiper Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Car Wiper Blade Market Insights
Smart connectivity integration is tilting wiper blade design toward sensor-compatible profiles and heated elements. Robert Bosch GmbH leverages its OE channel depth to sustain factory-fit contracts with premium European marques. Valeo SA anchors its position through aerodynamic beam technology leadership, while DENSO Corporation competes on thermal management features for electric vehicle platforms. Trico Products Corporation differentiates through aftermarket distribution density in North America.
Passenger car wiper blades are precision-engineered clearing devices comprising a rubber or silicone wiping element bonded to a metal or composite carrier structure, typically measuring 12 to 28 inches in length and operating through oscillating arm kinematics to maintain optical clarity on laminated windscreens. Beam blades with integrated spoiler geometry command margin premiums due to uniform pressure distribution and ice-shedding performance, while conventional hinged-frame designs retain volume dominance in price-sensitive replacement channels. Silicone formulations are capturing share from natural rubber in corrosion-prone coastal markets, and aftermarket retailers represent the fastest-growing end-user channel as do-it-yourself maintenance persists among aging vehicle parc owners.
Federal-Mogul Motorparts LLC and HELLA GmbH & Co. KGaA navigate ECE R43 windscreen safety standards and NHTSA FMVSS 103 visibility regulations that mandate minimum swept area and material durability thresholds. Japan's METI enforces JIS D 5702 wiper performance benchmarks that influence export specifications for Mitsuba Corporation and Magneti Marelli S.p.A. Stakeholders must monitor evolving OEM platform electrification timelines, as thermal load requirements and aerodynamic drag coefficients redefine blade architecture priorities for next-generation passenger vehicles.
Market Dynamics
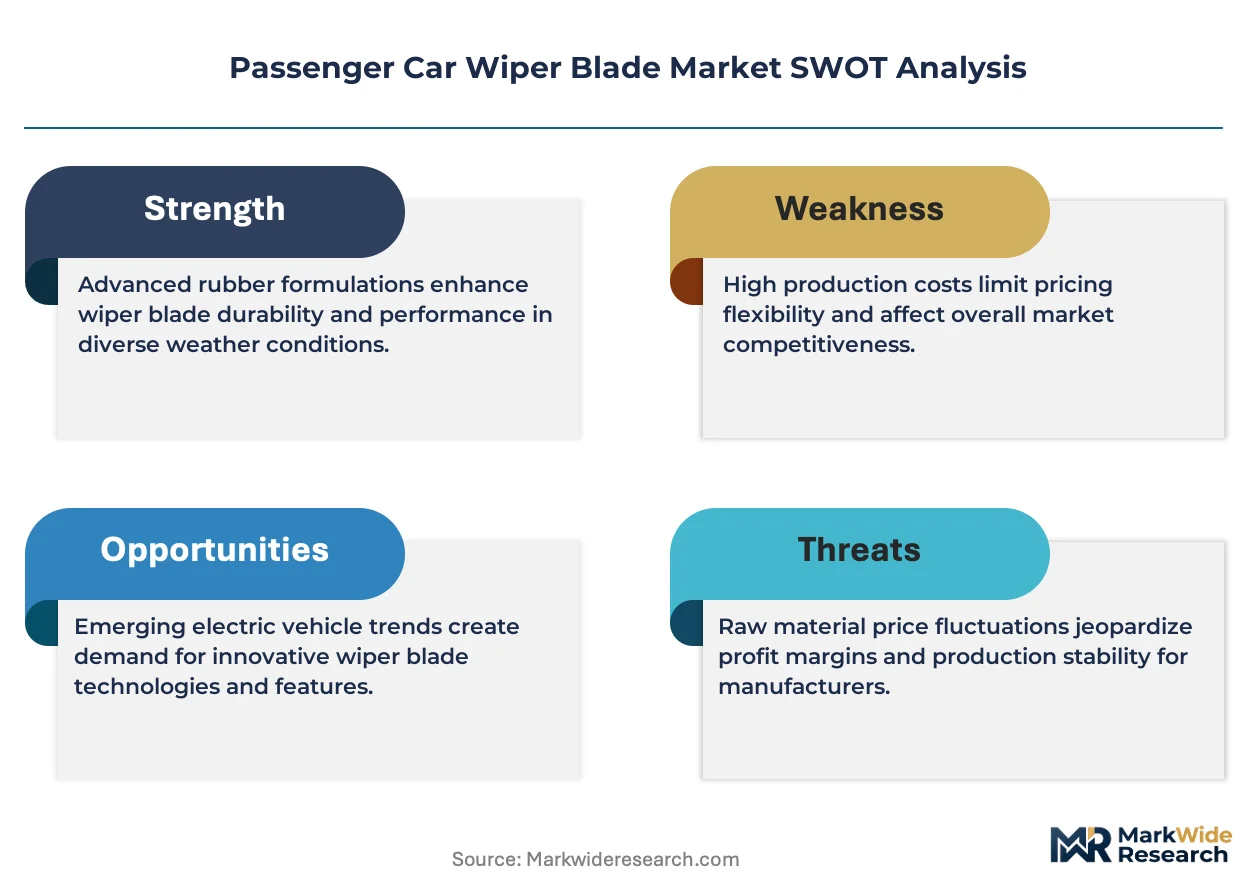
The wiper blade market faces structural pressure from electrification mandates that demand aerodynamic optimization and thermal load management incompatible with legacy hinged-frame architectures. OEM specification tightening for electric vehicle platforms is compressing replacement cycle flexibility while elevating performance thresholds for beam and hybrid configurations.
Growth Catalysts
- Silicone compound adoption:Coastal corrosion exposure in Florida and California accelerates displacement of natural rubber by silicone-infused wiping elements that resist UV degradation and salt pitting.
- NHTSA FMVSS 103 visibility mandates:Swept-area requirements and material durability thresholds force specification upgrades during routine replacement cycles, elevating minimum performance baselines.
- Extreme weather exposure:Shortened replacement intervals in Texas, Arizona, and Michigan create recurring revenue density for aftermarket retailers stocking premium beam configurations.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to input cost swings that compress margin buffers on economy-tier hinged-frame products.
- Technical limitation in cold climates:Silicone formulations exhibit reduced ice-shedding performance below minus twenty degrees Celsius, preserving natural rubber demand in Minnesota, North Dakota, and Alaska.
- Supply concentration risk:Chinese metal carrier and spoiler component manufacturing creates single-source vulnerability for North American blade assemblers during ocean freight disruptions.
Strategic Opportunities
- Sensor-compatible blade profiles:Integration with rain-sensing and ADAS camera systems opens specification windows for heated elements and reduced-obscuration designs in premium European marque service channels.
- Do-it-yourself channel expansion:Aging vehicle parc ownership in Rust Belt states sustains aftermarket retailer shelf-space negotiations for hybrid configurations with tool-free installation features.
- IRA clean vehicle incentives:Electric vehicle platform proliferation accelerates demand for thermally managed blade architectures that reduce HVAC load and extend range.
Industry Challenges
- Adhesive bonding chemistry expertise:Silicone-to-metal carrier attachment requires process engineering capabilities scarce among legacy natural rubber compounders.
- JIS D 5702 certification timelines:Japanese export specifications demand extended validation cycles that delay product launches for Mitsuba Corporation and Magneti Marelli S.p.A. supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Car Wiper Blade Market |
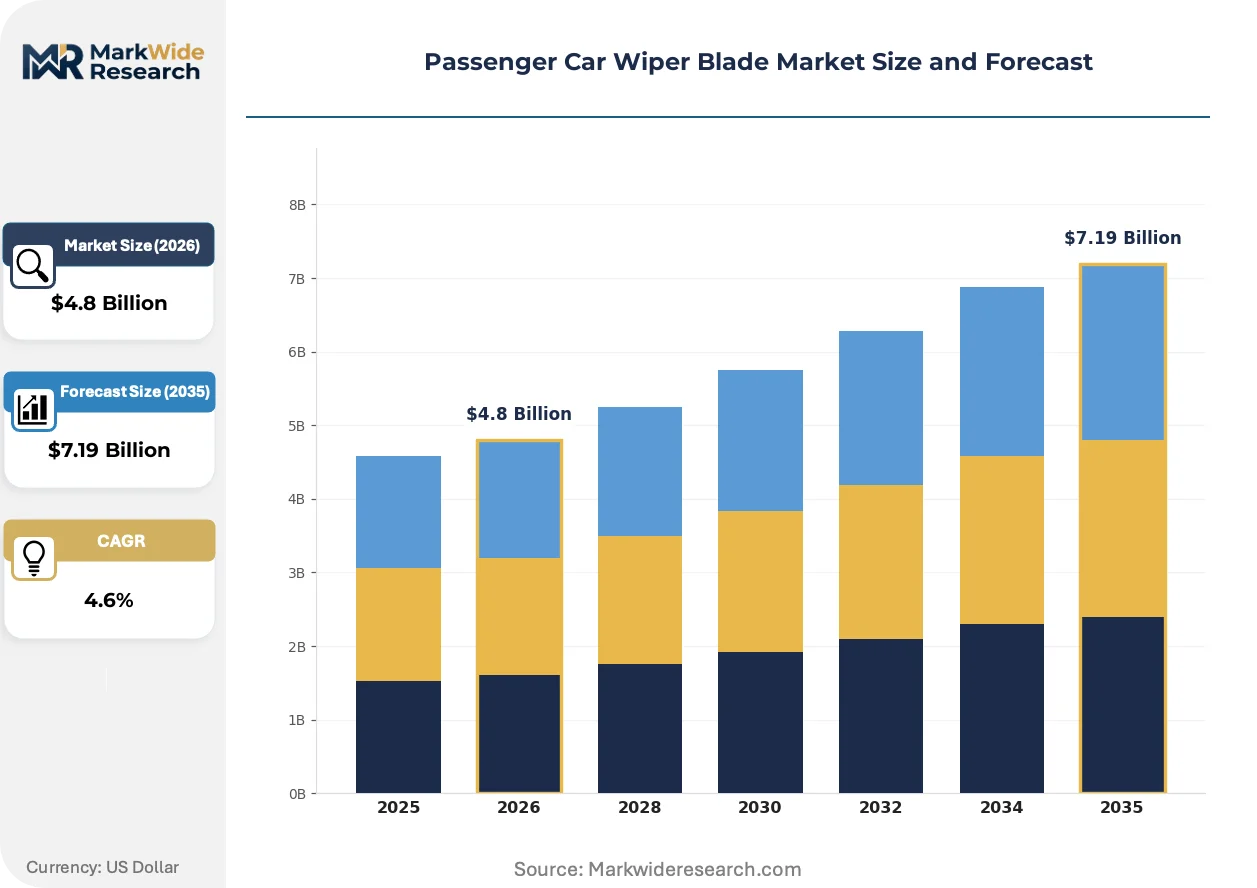
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Blades, Beam Blades, Hybrid Blades, Winter Blades Material: Rubber, Silicone, Graphite, Plastic End User: Automobile Manufacturers, Aftermarket Retailers, Vehicle Owners, Fleet Operators Installation Type: Direct Fit, Universal Fit, Custom Fit, Quick Clip |
| Companies Covered | Robert Bosch GmbH, Valeo SA, DENSO Corporation, Trico Products Corporation, HELLA GmbH & Co. KGaA, Mitsuba Corporation, Continental AG, Federal-Mogul Motorparts LLC, Magneti Marelli S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Car Wiper Blade Market Trends and Innovations
Material science advances and electrification requirements are converging to redefine blade architecture priorities. Aerodynamic drag coefficients and thermal management specifications now dominate design briefs previously centered on cost minimization.
Beam blade technology with integrated spoiler geometry is migrating from premium OE fitment to mainstream aftermarket replacement. Vehicle owners in coastal corrosion zones and high-speed corridor states adopt these configurations for uniform pressure distribution and ice-shedding performance. The shift compresses volume share for conventional hinged-frame designs while elevating margin structures for compounders with silicone formulation capabilities.
EPA fuel economy standards and NHTSA FMVSS 103 visibility regulations are tightening concurrently, forcing specification convergence. Manufacturers must satisfy swept-area mandates while reducing aerodynamic drag coefficients to meet fleet-average targets. Electric vehicle platforms in California and European export markets experience the strictest dual compliance pressure, accelerating heated element integration and reduced-mass carrier development.
Aftermarket procurement patterns favor premium configurations despite unit price premiums. Do-it-yourself vehicle owners prioritize visibility safety over economy-tier substitution, compressing replacement cycle elasticity. This behavior concentrates in Germany, the United States, and coastal Chinese provinces where extreme weather exposure and OEM specification tightening shorten functional blade lifespans.
Passenger Car Wiper Blade Market Segmentation
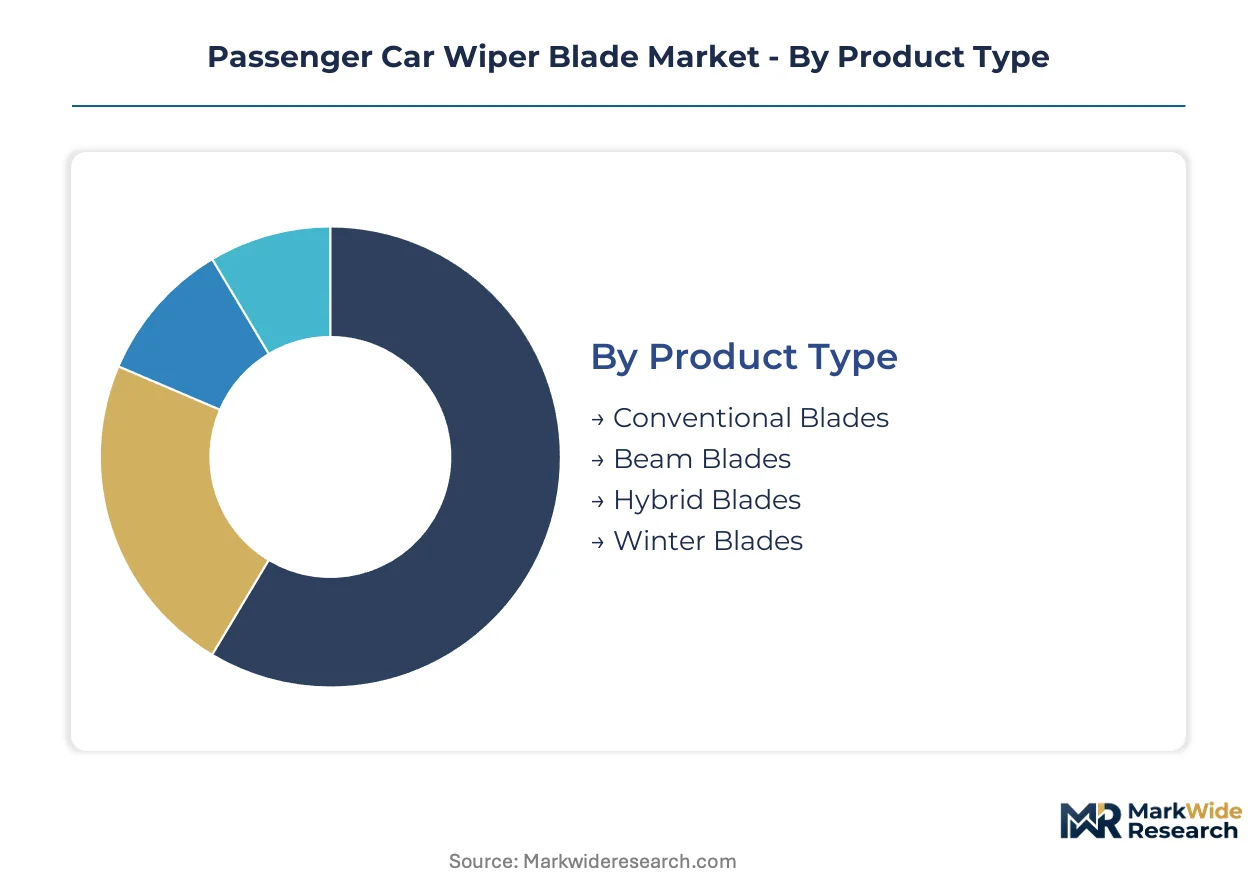
Wiper blade segmentation reflects divergent service intensity across vehicle lifecycles. Aftermarket channels demand tool-free installation and corrosion-resistant materials, while OEM specifications prioritize aerodynamic integration and thermal management for electrified platforms.
Product Type:
After-sales-service intensity varies sharply by blade architecture, with replacement frequency and margin structure tied to weather exposure and vehicle age.
- Conventional Blades:Hinged-frame designs with multiple pressure points dominate price-sensitive replacement channels in aging vehicle parcs. Demand concentrates in Rust Belt states where DIY maintenance persists among owners of vehicles exceeding ten years of service life.
- Beam Blades:Integrated spoiler geometry and uniform pressure distribution command premium positioning in coastal corrosion zones. Florida and California vehicle owners adopt these configurations for UV resistance and salt-pit durability, shortening replacement cycles versus conventional alternatives.
- Hybrid Blades:Aerodynamic shells combined with conventional frame structures bridge performance and cost tiers for mid-market service channels.
- Winter Blades:Enclosed frame designs with heavy-duty rubber compounds serve Minnesota, North Dakota, and Alaska markets where ice accumulation degrades exposed mechanisms.
Conventional blades hold the largest share; momentum sits with beam configurations.
Material:
Cost tier stratification separates compound technologies by climate exposure and vehicle platform requirements.
- Rubber:Natural rubber formulations retain volume dominance in economy-tier replacement channels despite price volatility from Thai and Indonesian supply concentration. Cold-climate performance below minus twenty degrees Celsius preserves demand in northern tier states where silicone ice-shedding falters.
- Silicone:UV-resistant, salt-pit resilient compounds displace natural rubber in coastal markets. California and Florida replacement cycles accelerate as vehicle owners prioritize durability over unit cost in corrosion-prone environments.
- Graphite:Low-friction coatings reduce chatter and extend wiping element lifespan in premium OE specifications.
- Plastic:Composite carrier materials reduce mass for electric vehicle thermal load management requirements.
Rubber compounds retain volume leadership; silicone formulations are climbing the fastest.
End User:
Customer type determines specification authority and procurement rhythm across vehicle lifecycle stages.
- Automobile Manufacturers:Factory-fit contracts demand aerodynamic optimization and sensor compatibility for ADAS integration. NHTSA FMVSS 103 swept-area mandates and EPA fuel economy standards compress design flexibility while elevating performance thresholds for electrified platforms.
- Aftermarket Retailers:Shelf-space negotiations prioritize tool-free installation and corrosion-resistant packaging for DIY vehicle owners. Aging parc ownership in Michigan, Ohio, and Pennsylvania sustains premium hybrid configuration demand despite unit price premiums.
- Vehicle Owners:Direct procurement through e-commerce channels favors visibility safety over economy substitution, compressing replacement cycle elasticity.
- Fleet Operators:Volume procurement contracts emphasize total cost of ownership and standardized maintenance intervals across multi-state operations.
Aftermarket retailers command the largest channel share; fleet operators represent the steepest expansion trajectory.
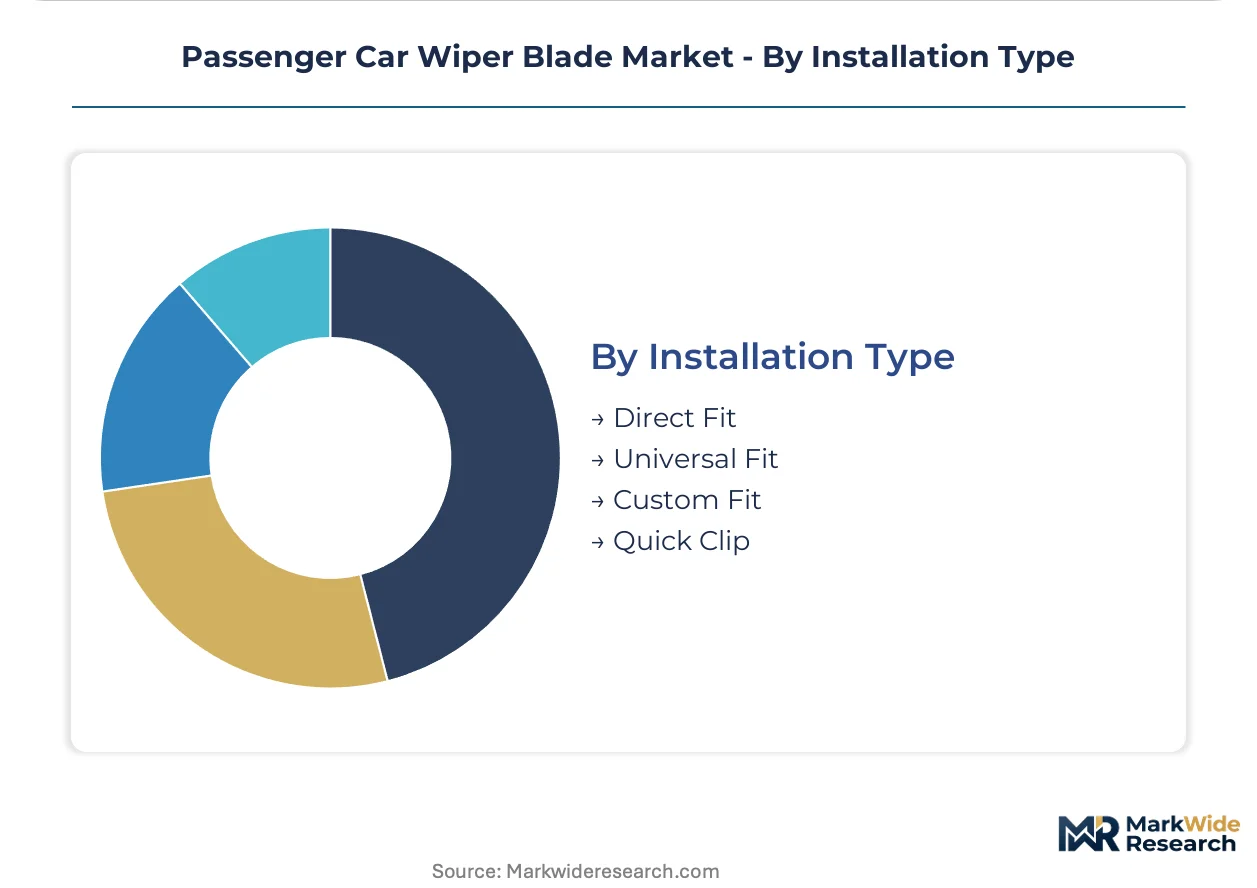
Installation Type:
Volume concentration in retrofit applications shapes attachment mechanism standardization.
- Direct Fit:OEM-specific connectors and pre-assembled arm attachments dominate dealer service channels. Factory-fit specifications from Robert Bosch GmbH and Valeo SA anchor European marque loyalty programs.
- Universal Fit:Multi-adapter systems serve price-sensitive replacement markets with broad vehicle coverage requirements.
- Custom Fit:Specialty configurations address classic vehicle restorations and modified suspension geometries in enthusiast segments.
- Quick Clip:Tool-free attachment mechanisms accelerate DIY adoption in aftermarket retail channels.
Direct fit systems hold the largest share; quick clip mechanisms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wiper blade exports flow predominantly to premium European marque assembly plants in the United States and China, establishing a transatlantic trade corridor that shapes regional specification standards. This export-driven dynamic concentrates advanced beam technology development in Stuttgart and Munich supplier clusters.
United States
Extreme weather exposure across Texas, Arizona, and Michigan compresses replacement cycles below the global average. NHTSA FMVSS 103 visibility mandates enforce minimum swept-area thresholds that elevate baseline performance requirements. Detroit-area automotive suppliers coordinate with domestic aftermarket retailers to stock corrosion-resistant silicone configurations for coastal Florida and California markets.
Germany
Electric vehicle platform proliferation from BMW and Mercedes-Benz accelerates demand for aerodynamically optimized blade architectures. ECE R43 windscreen safety standards from the United Nations Economic Commission for Europe govern factory-fit specifications for export-bound vehicles. Baden-Württemberg engineering clusters specialize in heated element integration for premium marque ADAS compatibility.
China
Domestic vehicle parc expansion and OEM localization requirements concentrate manufacturing capacity in Yangtze River Delta industrial zones. GB standards from the State Administration for Market Regulation establish wiper performance benchmarks for both domestic consumption and export qualification. Shanghai-based suppliers serve regional aftermarket channels while feeding Southeast Asian replacement markets.
Japan
Hybrid and electric vehicle platform leadership from Toyota and Honda drives thermal management feature development in wiper blade specifications. METI enforces JIS D 5702 performance benchmarks that influence export product configurations for Mitsuba Corporation supply contracts. Aichi Prefecture automotive clusters maintain precision manufacturing capabilities for OE sensor-compatible blade profiles.
India
Monsoon intensity and dust exposure across Maharashtra and Tamil Nadu sustain above-average replacement frequency in passenger vehicle fleets. BIS certification requirements for automotive components create compliance barriers for imported blade configurations. Pune and Chennai manufacturing corridors attract joint venture investments targeting domestic aftermarket expansion and Southeast Asian export positioning.
Passenger Car Wiper Blade Market Competitive Landscape
Channel-controlling players compete with product-specialist players across factory-fit and aftermarket procurement streams. The market exhibits moderate consolidation, with tier-one automotive suppliers commanding OE specification authority while independent manufacturers fragment across price-sensitive replacement channels. Two strategic archetypes dominate: vertically integrated compounders with in-house rubber and silicone formulation capabilities, and distribution-heavy assemblers leveraging metal carrier sourcing from East Asian component markets. Competitive moves center on backward integration into wiping element compounding and geographic expansion through regional distributor acquisition.
Among German-based diversified automotive suppliers, Robert Bosch GmbH and Continental AG occupy positions anchored by OE channel depth and factory-fit contract density. Valeo SA exemplifies the aerodynamic technology specialist archetype, while Japanese manufacturers DENSO Corporation and Mitsuba Corporation represent the thermal management feature leadership segment for electrified platforms. These named entities serve as reference points for competitive positioning without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Valeo SA |
| DENSO Corporation |
| Trico Products Corporation |
| HELLA GmbH & Co. KGaA |
| Mitsuba Corporation |
| Continental AG |
| Federal-Mogul Motorparts LLC |
| Magneti Marelli S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Long Beach container lane cost volatility feeds directly into blade assembler margin structures, amplifying price stratification between silicone-compound premium tiers and natural rubber economy offerings while compressing mid-market hybrid positioning.
Pricing Analysis
Beam-to-conventional-to-winter blade pricing gaps separate three distinct technology generations across aftermarket shelves. Three-tier pricing structure across premium, standard, and economy levels stratifies by material compound grade and aerodynamic feature density. Cost compression in hinged-frame tiers is intensifying because Thai rubber price swings erode compounder buffers. Fleet operators exhibit highest price sensitivity due to volume procurement discipline, while coastal DIY owners in Florida and California accept beam blade premiums for salt-pit durability.
Supply Chain Analysis
Natural rubber latex feedstock from Thailand and Indonesia anchors wiping element cost structures for legacy compounders. Metal carrier stamping and spoiler injection molding concentrates in China, South Korea, and Taiwan, creating assembly dependencies for North American blade finishers. Single-source vulnerability in Chinese component supply exposes assemblers to ocean freight disruption cascades. Distribution runs through national auto parts retailers and regional jobber networks serving independent service shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform proliferation constitutes a high-growth disruption, with NHTSA FMVSS 103 visibility mandates and EPA aerodynamic requirements converging to elevate thermal-managed blade specifications across OEM and aftermarket channels.
For Market Incumbents: Harden silicone-to-metal bonding chemistry capabilities through captive formulation assets or exclusive supplier partnerships, defending against Asian compounder vertical integration moves. Secure JIS D 5702 certification ahead of Japanese export contract renewals to lock out second-tier challengers. Prioritize heated element R&D for ADAS-compatible blade profiles as sensor integration tightens factory-fit specifications. For New Entrants and Emerging Players: Rust Belt state aftermarket penetration gaps offer white-space entry through tool-free quick-clip hybrid configurations targeting aging vehicle parc owners in Michigan, Ohio, and Pennsylvania. E-commerce direct-to-vehicle-owner channels bypass incumbent retailer shelf-space barriers. Lead with corrosion-resistant silicone formulations packaged for DIY installation to capture coastal replacement cycle acceleration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive supplier divisions where wiper blade operations represent non-core revenue pools with stranded OE channel relationships. Mid-term viability hinges on electrification-exposed thermal management feature portfolios. Monitor NHTSA rulemaking dockets for visibility standard tightening as inflection signal for specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Compound Backward Integration | Captive rubber formulation secures margin buffers against Thai supply volatility for beam blade producers. |
| Heated Element Platform Development | Thermal management integration addresses electric vehicle HVAC load reduction requirements for European OEMs. |
| Quick-Clip Installation Standardization | Tool-free attachment mechanisms accelerate DIY adoption in aging vehicle parc aftermarket channels. |
| ADAS Sensor-Compatible Profile Launch | Reduced-obscuration designs capture premium service channel specifications for camera-equipped vehicles. |
| Regional Distributor Acquisition | Shelf-space control in coastal corrosion markets secures silicone formulation volume commitments. |
Research Methodology
Operator-level perspectives from OEM platform engineers, aftermarket distributor category managers, Tier 1 supplier procurement leads, and compounder R&D directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against NHTSA FMVSS 103 regulatory filings, EPA fuel economy compliance data, vehicle production databases, and customs trade records for rubber and metal carrier flows. Bottom-up blade volume estimates triangulated against top-down automotive parc replacement cycle models.
Scenario-bracketing framed analytical outputs across conservative, baseline, and aggressive electrification adoption paths throughout the forecast period. Segmentation modeling incorporated product architecture, material compound, end-user channel, and installation mechanism dimensions. CAGRs derived from replacement cycle elasticity functions tied to weather exposure severity indices and OEM specification tightening trajectories. Electric vehicle platform rollout schedules and thermal management content per vehicle served as automotive-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in ocean freight rates, natural rubber commodity indices, or IRA clean vehicle incentive appropriations would shift the trajectory. Forecasts embed assumptions regarding JIS D 5702 certification timeline stability and ECE R43 windscreen standard harmonization. Cross-checking against IHS Markit vehicle registration data and NHTSA recall databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
High Speed Rolling Bearings Market