
 Brazil Automotive Hydraulic Actuators Market | 2026-2036
Brazil Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Hydraulic Actuators Market Outlook
The gap between premium precision actuators and commodity hydraulic units is expanding in Brazil. BorgWarner Inc. leverages its clutch actuator specialization to command position in automated manual transmission systems. Continental AG anchors supply relationships with major OEMs through localized production capacity. Robert Bosch GmbH differentiates via integrated electronic-hydraulic control modules that reduce assembly complexity for vehicle assemblers.
Brazil automotive hydraulic actuators are fluid-powered mechanical devices converting hydraulic pressure into linear or rotary motion, typically operating at pressures between 1,500 and 5,000 psi for chassis, powertrain, and braking applications. These actuators enable precise force transmission with minimal mechanical backlash, serving as critical enablers for automated braking, steering assistance, and transmission control in vehicles assembled domestically. Double acting actuators lead volume demand due to their bidirectional force capability in clutch and brake systems, while rotary configurations represent the fastest-growing category as electric vehicle steering architectures proliferate. OEMs capture the dominant share of direct procurement, though aftermarket providers are building margin pools around rebuild services for aging commercial vehicle fleets operating beyond warranty periods.
ANVISA and the country's national environmental regulator shape product compliance through emission-linked component certification requirements under PROCONVE resolutions, while INMETRO mandates performance verification for safety-critical hydraulic assemblies installed in vehicles sold nationwide. These frameworks force suppliers to maintain dual certification tracks for domestic and export-bound production lines. Stakeholders must monitor how Brazil's evolving carbon neutrality commitments for automotive manufacturing reshape hydraulic actuator specifications and sourcing criteria.
Market Dynamics
PROCONVE emission resolutions from Brazil's national environmental regulator are forcing OEMs to recalibrate hydraulic actuator specifications toward precision-controlled architectures, compressing procurement cycles for legacy mechanical designs across the ABC Paulista corridor and southern automotive clusters.
Growth Catalysts
- PROCONVE Resolution Compliance:Tiered emission standards mandate precision hydraulic controls in heavy-duty braking and transmission systems, pulling actuator demand from commercial fleets operating in São Paulo and Minas Gerais.
- Electrification Infrastructure:Rotary hydraulic actuators are capturing share in electric power steering architectures as domestic EV assembly scales in Gravataí's southern cluster.
- Commercial Fleet Renewal:Aging truck and bus populations beyond warranty periods are generating rebuild service demand for double-acting clutch and brake actuators through aftermarket channels.
Market Restraints
- Import Dependency for Precision Components:Specialized seals and high-pressure valve assemblies concentrate supply with German and Japanese component specialists, exposing assemblers to currency volatility and extended lead times.
- Dual Certification Burden:INMETRO safety verification requirements for domestic sales run parallel to export certification tracks, inflating compliance overhead for suppliers serving both markets.
- Electromechanical Substitution:Pure electric actuators are displacing hydraulic units in light passenger vehicle steering applications below 2,000 psi operating pressure.
Strategic Opportunities
- Rebuild Service Specialization:Aftermarket providers can capture margin pools by developing certified remanufacturing capabilities for commercial vehicle fleets operating beyond OEM warranty periods in Minas Gerais cargo corridors.
- Integrated Electronic-Hydraulic Modules:Convergence of sensor arrays with hydraulic control units offers assembly simplification value to vehicle assemblers seeking reduced wiring complexity.
- Carbon Neutrality Alignment:Brazil's evolving automotive manufacturing decarbonization commitments are reshaping sourcing criteria toward suppliers with verified low-carbon production processes.
Industry Challenges
- Calibration Technician Scarcity:Precision actuator commissioning requires specialized fluid dynamics expertise that outpaces vocational training output in Brazil's technical institutes.
- Legacy System Integration Friction:Electronic-hydraulic control modules face compatibility constraints with existing vehicle CAN bus architectures, extending validation timelines for OEM adoption.
- INMETRO Certification Latency:Safety-critical hydraulic assembly approval cycles average 14-18 months, compressing product launch windows relative to competitor jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Hydraulic Actuators Market |
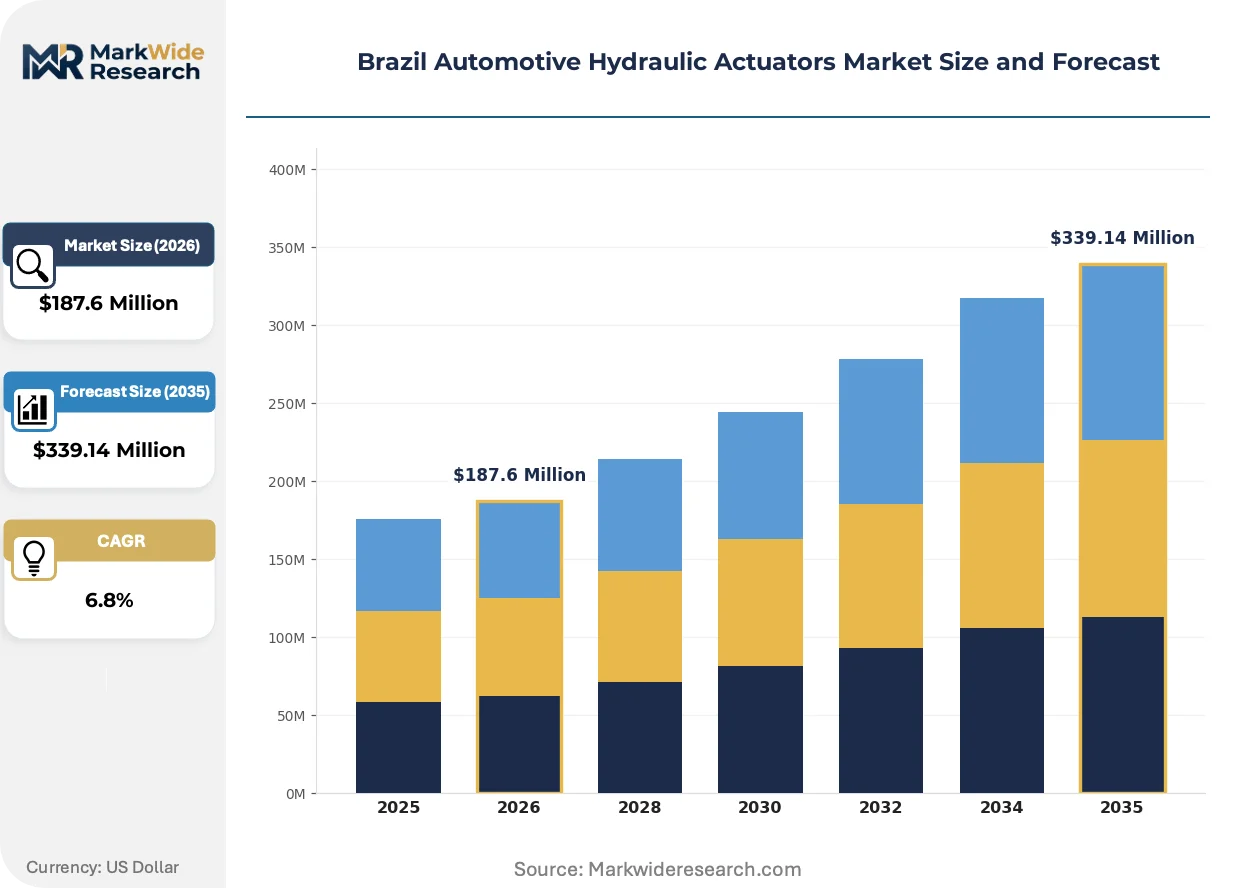
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $339.14 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Rotary, Linear Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Onboard, Offboard, Integrated, Standalone |
| Companies Covered | Wabco Holdings Inc., BorgWarner Inc., Continental AG, CTS Corporation, Johnson Electric, Robert Bosch GmbH, Sonceboz SA, Hella KGaA Hueck & Co., Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Hydraulic Actuators Market Strategic Shifts
Electrification of vehicle architectures is compressing the addressable market for conventional hydraulic actuators while simultaneously opening specialized niches for high-pressure precision units in commercial applications.
Electro-hydraulic brake actuators are expanding into automated manual transmission systems for heavy commercial vehicles. Fleet operators in São Paulo's metropolitan freight networks are specifying these units for their fail-safe redundancy characteristics. This technology is expanding into territory previously served by pure pneumatic braking systems, enabling OEMs to consolidate platform architectures across medium and heavy-duty segments.
ANVISA emission-linked component certification under PROCONVE resolutions is tightening tolerance specifications for hydraulic fluid compatibility and seal degradation rates. Suppliers must now validate actuator performance across Brazil's temperature and altitude extremes, from Amazon basin humidity to southern highland conditions. Aftermarket rebuild specialists are responding by developing region-specific refurbishment protocols that preserve certification integrity.
Direct procurement consolidation among passenger car OEMs is compressing supplier margins while elevating technical partnership requirements. Vehicle assemblers in the ABC Paulista corridor are unbundling after-sales service contracts from initial component supply, creating discrete revenue streams for independent hydraulic service networks. This pattern is most visible in southern Brazil's Gravataí cluster, where OEM captive service operations face competition from specialized rebuild providers.
Brazil Automotive Hydraulic Actuators Market Segmentation
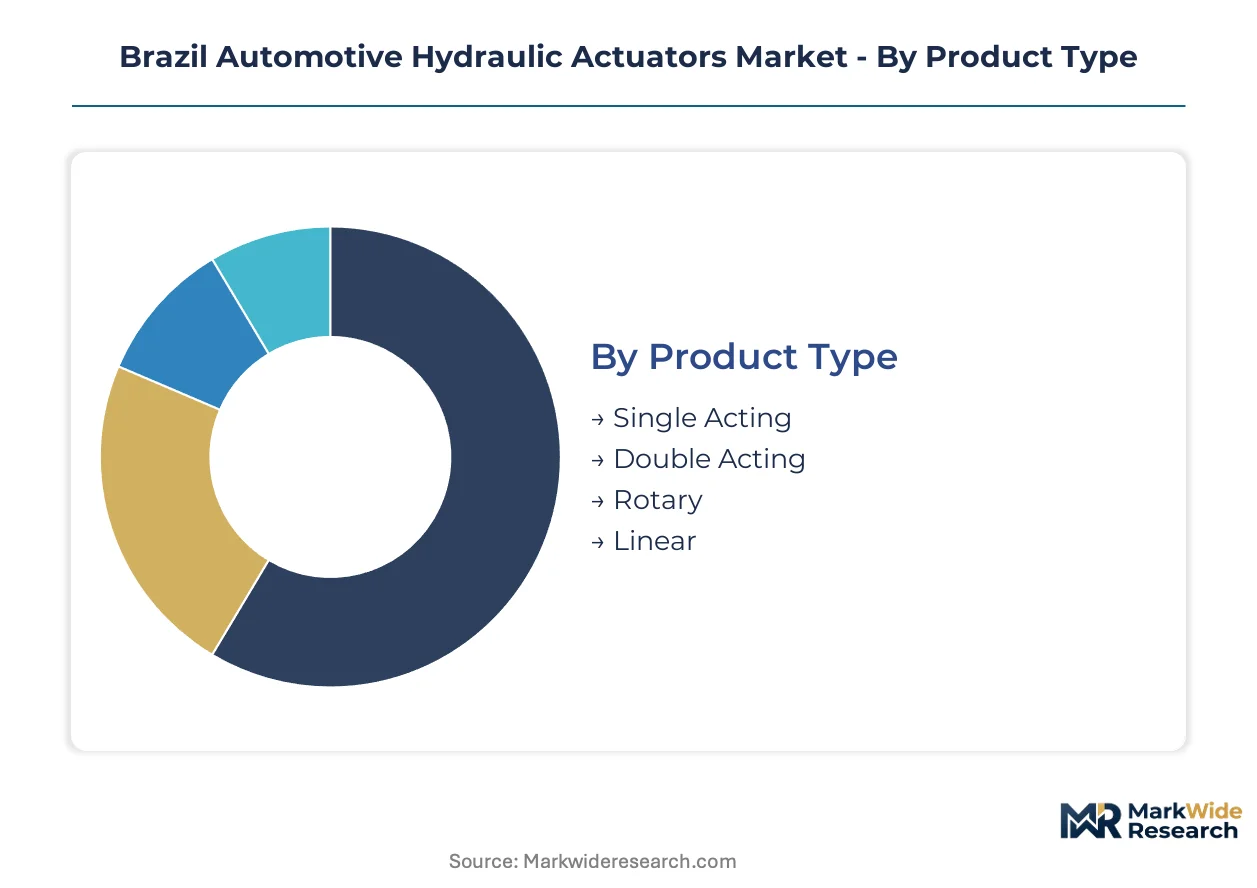
Brazil's automotive hydraulic actuator market fragments across four structural dimensions that determine integration complexity and procurement economics. Product architecture and vehicle electrification status create the deepest fault lines for supplier positioning and margin capture.
Product Type:
Integration depth varies sharply across actuator architectures, with standalone units demanding distinct calibration protocols versus embedded systems that ship pre-integrated with transmission or braking modules.
- Double Acting:Bidirectional force capability enables clutch engagement and brake modulation in heavy commercial vehicles. Fleet operators in Minas Gerais cargo corridors specify these units for transmission systems requiring precise pressure reversal under load.
- Rotary:Torque-output configurations are embedding into electric power steering racks as EV assembly scales in Gravataí's southern cluster, where localized production lines favor compact rotary geometries over linear alternatives.
- Single Acting:Unidirectional pressure application dominates parking brake and hood lift mechanisms in entry-level passenger vehicles assembled across the ABC Paulista corridor.
- Linear:Piston-rod assemblies serve chassis leveling and suspension control functions, with demand concentrating in premium SUV platforms where ride-height adjustment commands specification priority.
Volume placements concentrate in Double Acting configurations for commercial braking and transmission; the faster expansion belongs to Rotary actuators as electric steering architectures proliferate.
Vehicle Type:
Cost tier stratification separates precision-engineered units for premium electrified platforms from commodity hydraulic assemblies serving price-sensitive internal combustion segments.
- Commercial Vehicles:Heavy-duty braking and automated manual transmission systems in São Paulo metropolitan freight networks absorb high-pressure actuators rated above 3,000 psi. PROCONVE emission resolutions mandate precision-controlled architectures that compress procurement cycles for legacy mechanical designs.
- Electric Vehicles:Rotary hydraulic units are gaining specification in steer-by-wire systems where backup mechanical redundancy satisfies ANVISA safety requirements. Domestic EV assembly in southern Brazil's Gravataí cluster favors integrated electronic-hydraulic modules over discrete component sourcing.
- Passenger Cars:Conventional powertrain and chassis applications across the ABC Paulista industrial corridor sustain baseline demand for double-acting clutch and brake actuators in internal combustion platforms.
- Motorcycles:Compact single-acting units for rear brake and suspension damping serve Brazil's two-wheeler fleet, with aftermarket rebuild activity concentrated in urban service networks beyond OEM warranty coverage.
Commercial vehicle procurement commands the highest unit values; electric vehicle specifications are climbing the fastest as domestic battery-electric assembly accelerates.
End User:
Customer type determines whether actuators ship as branded components, anonymous subsystems, or certified rebuild units, with margin structures varying accordingly.
- OEMs:Direct procurement from vehicle manufacturers in the ABC Paulista corridor and Gravataí cluster concentrates volume demand, with assemblers unbundling after-sales contracts from initial supply agreements.
- Aftermarket Providers:Rebuild specialists capture margin pools around aging commercial vehicle fleets operating beyond warranty periods in Minas Gerais, developing region-specific refurbishment protocols that preserve ANVISA certification integrity.
- Tier-1 Suppliers:Subsystem integrators source actuators for bundling into transmission or braking modules, passing through INMETRO safety verification as part of larger assembly certification.
- Vehicle Assemblers:Contract manufacturers without full OEM status procure standard hydraulic units for kit assembly operations serving regional export markets.
Direct OEM procurement dominates current volume; aftermarket provider revenue pools are expanding most quickly as Brazil's commercial fleet ages past warranty thresholds.
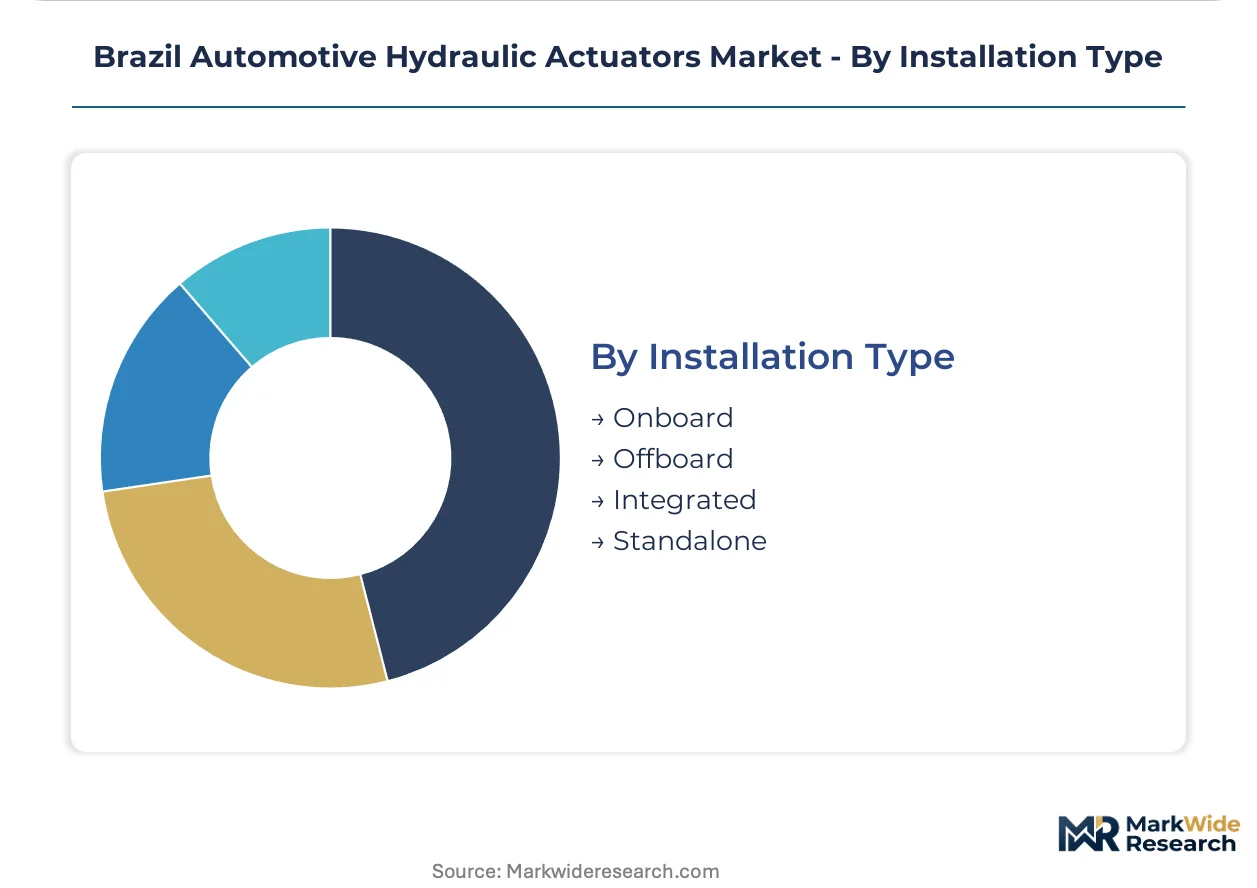
Installation Type:
Supply concentration patterns favor integrated and onboard configurations where Brazilian-based production lines can capture value-added assembly stages.
- Integrated:Actuators pre-assembled into transmission or braking modules reduce wiring complexity for vehicle assemblers. Robert Bosch GmbH anchors this segment through localized electronic-hydraulic control module production.
- Onboard:Direct chassis or powertrain mounting dominates heavy commercial vehicle specifications, with São Paulo and Minas Gerais fleet operators demanding field-serviceable units.
- Standalone:Discrete hydraulic units requiring separate mounting brackets and fluid connections persist in legacy commercial vehicle platforms and aftermarket replacement scenarios.
- Offboard:Service-bay calibration equipment and test benches represent a niche category, with demand tied to INMETRO certification requirements for hydraulic assembly performance verification.
Integrated installations command expanding specification share; standalone configurations retain relevance in aftermarket rebuild channels where modularity supports field replacement economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ABC Paulista industrial corridor anchors Brazil's automotive hydraulic actuator procurement, with São Paulo's metropolitan freight networks and Gravataí's southern cluster generating concentrated demand for precision braking and transmission controls.
São Paulo
Heavy commercial fleets operating São Paulo's metropolitan cargo corridors specify high-pressure actuators above 3,000 psi for automated manual transmission systems. ANVISA emission-linked certification requirements under PROCONVE resolutions mandate precision-controlled hydraulic architectures that displace legacy mechanical designs. The ABC Paulista corridor concentrates OEM assembly lines where direct procurement contracts dominate volume placement.
Minas Gerais
Aging truck populations beyond warranty periods sustain aftermarket rebuild demand for double-acting clutch and brake actuators across Belo Horizonte freight networks. INMETRO safety verification requirements for hydraulic assemblies inflate compliance overhead for suppliers serving domestic certification tracks. Regional rebuild specialists are developing refurbishment protocols that preserve ANVISA certification integrity for commercial vehicle service.
Rio Grande do Sul
Rotary hydraulic actuators are embedding into electric power steering racks as EV assembly scales in Gravataí's automotive cluster. The state's southern highland conditions demand validation across temperature extremes that exceed Amazon basin humidity standards. Localized production lines favor integrated electronic-hydraulic modules over discrete component sourcing for steer-by-wire architectures.
Paraná
Curitiba-based subsystem integrators source actuators for bundling into transmission modules serving export-bound production lines. Dual certification tracks for domestic INMETRO requirements and international standards compress product launch timelines relative to competitor jurisdictions. Component suppliers face currency volatility exposure on specialized seals and high-pressure valve assemblies imported from German and Japanese specialists.
Brazil Automotive Hydraulic Actuators Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and integration depth. The supplier base fragments between integrated module specialists and standalone component fabricators. Three archetypes dominate: German-headquartered diversified technology conglomerates with localized production capacity; Swiss and Japanese precision component specialists controlling specialized valve and seal supply; and aftermarket rebuild operators capturing margin pools around aging commercial fleets. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Among diversified technology conglomerates, Continental AG and Robert Bosch GmbH anchor supply relationships through Brazilian-based electronic-hydraulic module production. BorgWarner Inc. occupies a position within the precision transmission control tier. These three exemplify the structural divide between integrated system suppliers and component-level competitors.
| Leading Market Players |
|---|
| Wabco Holdings Inc. |
| BorgWarner Inc. |
| Continental AG |
| CTS Corporation |
| Johnson Electric |
| Robert Bosch GmbH |
| Sonceboz SA |
| Hella KGaA Hueck & Co. |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialized seals and high-pressure valve assemblies imported from Germany and Japan trace a cost escalation path through currency volatility into tiered actuator pricing, with OEM procurement teams in São Paulo and Gravataí absorbing premium differentials for certified precision units while aftermarket rebuild channels capture residual value from aging commercial fleets.
Pricing Analysis
Uptime-based value anchoring dominates commercial fleet procurement, where brake and transmission actuator contracts tie pricing to vehicle availability guarantees across Minas Gerais cargo corridors. Three-tier pricing structure across premium precision, certified standard, and economy rebuild levels separates OEM direct procurement from aftermarket channels, with certification grade under PROCONVE resolutions commanding the widest spreads. Cost compression in commodity hydraulic units is intensifying because electromechanical substitutes are displacing sub-2,000 psi applications in light passenger vehicles. Aftermarket rebuild specialists exhibit highest price sensitivity; integrated electronic-hydraulic module buyers show lowest.
Supply Chain Analysis
Brazil's local-content mandates under automotive manufacturing regulations are reshaping sourcing patterns, pressuring Tier 1 suppliers to expand captive production of valve bodies and sensor housings within the ABC Paulista corridor. Component supply draws from Germany, Japan, and China for precision seals, high-pressure valves, and electronic control modules. Raw material dependencies center on specialty steel alloys, fluorocarbon elastomers, and rare-earth magnets for position sensing. Single-source vulnerability concentrates in Japanese valve specialists serving rotary actuator architectures. Distribution runs through OEM captive logistics networks for integrated modules and independent aftermarket distributors for standalone replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brazil automotive hydraulic actuators market sits in a technology-transition phase as electro-hydraulic control modules displace legacy mechanical actuation in heavy commercial braking and transmission systems.
For Market Incumbents: Anticipate margin compression in standalone hydraulic units by accelerating backward integration into electronic control module production within Gravataí's southern cluster. Invest in dual-certification capability for INMETRO domestic tracks and export standards to defend position against German and Japanese subsystem specialists. Electromechanical substitution in light passenger steering represents the primary threat vector requiring R&D pivot toward high-pressure commercial applications. For New Entrants and Emerging Players: PROCONVE emission resolutions in Brazil open a window for certified rebuild specialists to capture aftermarket margin pools around aging commercial fleets in Minas Gerais. Target the standalone actuator replacement segment where field-serviceable units dominate heavy truck specifications. Pursue go-to-market partnerships with independent hydraulic service networks unbundled from OEM after-sales contracts in the ABC Paulista corridor. For Investors and Strategic Acquirers: Consolidation of direct procurement contracts among passenger car OEMs is the leading indicator that integrated electronic-hydraulic module suppliers will command premium valuations over standalone component fabricators. Focus acquisition screening on Brazilian-based subsystem integrators with INMETRO certification infrastructure and established supply relationships across São Paulo and Rio Grande do Sul production clusters. Watch for rotary actuator specification acceleration in domestic EV assembly as the inflection signal for technology-transition maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Electronic-Hydraulic Module Production | Reduces wiring complexity for OEM assemblers in Gravataí's EV cluster. |
| Certified Remanufacturing Capability Buildout | Captures margin pools from aging commercial fleets beyond warranty periods. |
| Dual Certification Track Investment | Enables simultaneous INMETRO domestic and export market access. |
| Rotary Actuator R&D Expansion | Positions suppliers for electric power steering architectures in domestic EV assembly. |
| Backward Integration into Valve Production | Mitigates currency exposure on German and Japanese precision component imports. |
Study Parameters
Multi-period observation of PROCONVE resolution implementation timelines, commercial fleet renewal rates, and EV assembly scaling anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers in São Paulo and Gravataí, aftermarket rebuild specialists across Minas Gerais, and INMETRO certification officials. Secondary validation drew from vehicle production databases, customs import records for hydraulic components, ANVISA regulatory filings, and trade association technical bulletins. Bottom-up actuator shipment estimates triangulated against top-down automotive production forecasts.
Input-output matrices mapped hydraulic actuator demand to vehicle assembly volumes across passenger car, commercial, and electric propulsion architectures over the projection horizon. Segmentation dimensions modeled included product architecture, vehicle electrification status, end-user procurement channel, and installation integration depth. CAGRs derived from regression analysis of historical procurement cycles and technology substitution elasticities. Industry-specific forecast inputs incorporated PROCONVE compliance phase-in schedules and commercial fleet age distribution data.
Caveats apply where PROCONVE resolution amendments, currency volatility on precision component imports, or accelerated electromechanical substitution in light vehicles could materially shift the outlook. Forecasts reflect assumptions about certification timeline stability and OEM sourcing consolidation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Air Springs Market
Automotive Parts
Tow Bar Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Brake Pad Market
Automotive Parts
Global Automotive Engine Valves Market