
 South Korea Automotive Airfilters Market | 2026-2036
South Korea Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Airfilters Market Analytics
HEPA-grade cabin filtration specification is collapsing the gap between aftermarket commodity filters and OEM-installed systems. Mann+Hummel leverages its captive membrane technology to sustain premium positioning in Hyundai-Kia supply agreements. K&N Engineering differentiates through performance-oriented engine air intake designs for South Korea's modified vehicle segment. Allena Group anchors its position with localized manufacturing serving domestic aftermarket distributors.
Automotive airfilters are engineered porous media assemblies typically constructed from pleated cellulose, synthetic nonwoven blends, or multi-layer electrostatic meltblown composites, designed to remove particulate matter from intake air streams while maintaining specified pressure drop thresholds below engine or HVAC system limits. Cabin filters and engine air filters command the dominant volume positions, with cabin filtration experiencing accelerated specification upgrades as South Korean consumers prioritize interior air quality metrics. Electric vehicle filter demand is outpacing internal combustion equivalents due to distinct thermal management and battery compartment ventilation requirements that favor specialized media formats.
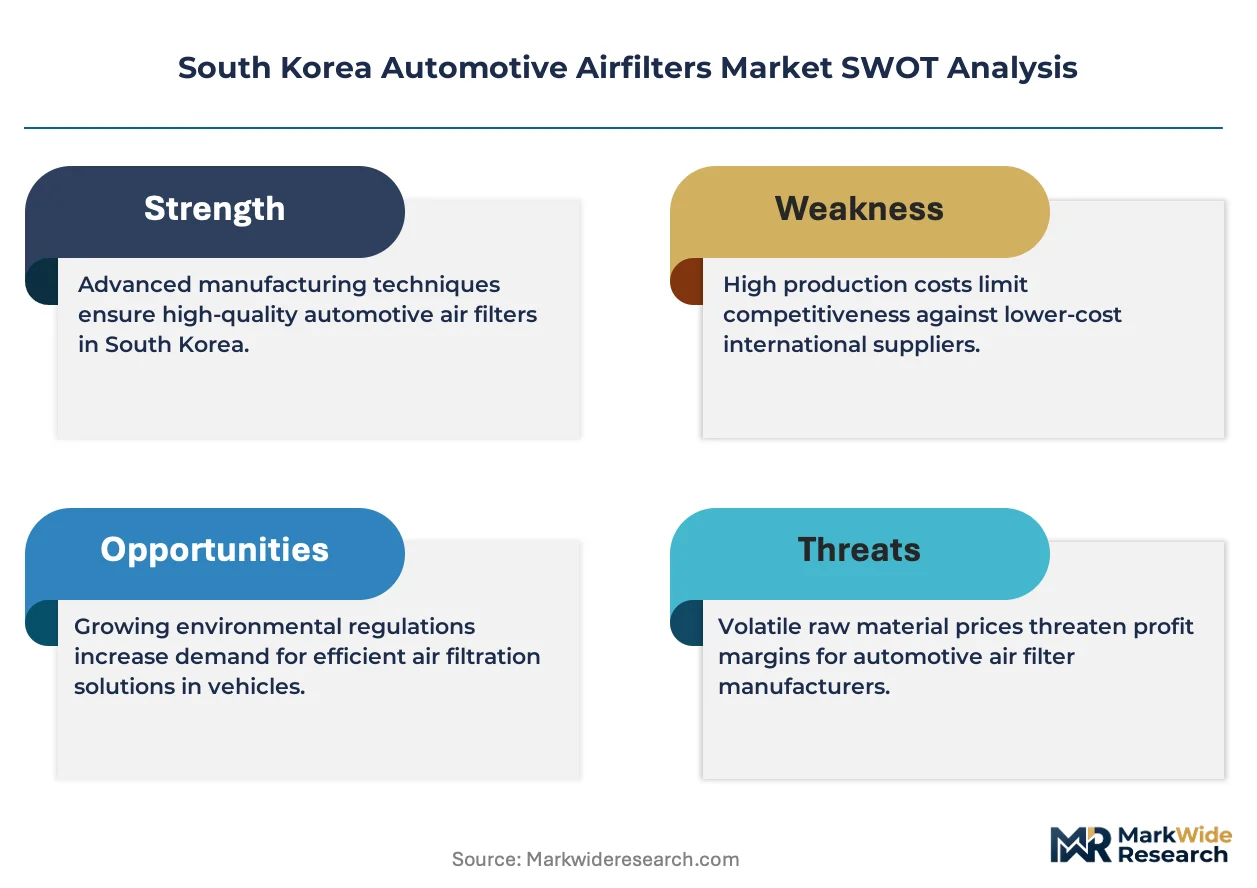
MFDS material safety standards, K-REACH chemical substance controls, and Ministry of Environment air quality directives collectively tighten compliance thresholds for filter media composition and end-of-life disposal protocols. These frameworks compel manufacturers to reformulate adhesive binders and validate recycled content ratios before securing type approval for domestic sale. Stakeholders must weigh the capital requirements of in-house meltblown capacity against the risk of supply interruption from imported media substrates.
Market Dynamics
HEPA-grade cabin filtration specifications are collapsing the traditional performance gap between aftermarket commodity filters and OEM-installed systems, forcing suppliers to reformulate media compositions or surrender premium positioning. This structural compression is accelerating as South Korean consumers elevate interior air quality metrics alongside vehicle purchase decisions.
Growth Catalysts
- MFDS material safety standards:Stricter cabin air material certifications under K-REACH chemical compliance rules compel filter manufacturers to upgrade adhesive formulations and recycled content ratios, creating upgrade cycles across installed base.
- Electric vehicle thermal management:Battery compartment ventilation and specialized HVAC architectures favor electrostatic meltblown composites with distinct pressure-drop profiles, expanding addressable media formats beyond legacy engine intake applications.
- Gyeonggi Province supplier concentration:Proximity to Hyundai Motor Group manufacturing complexes generates dense aftermarket demand clusters and just-in-time procurement relationships for domestic distributors.
Market Restraints
- Polypropylene resin cost volatility:Synthetic nonwoven substrate prices fluctuate with petrochemical feedstock indices, compressing gross margins for manufacturers lacking captive meltblown capacity.
- Imported media substrate dependency:Domestic producers rely on foreign suppliers for specialized electrostatic layers, exposing procurement schedules to shipping lane disruptions and currency exchange pressures.
- K-REACH registration timelines:Chemical substance notification protocols extend product validation cycles by 12-18 months, delaying new formulation commercialization against faster-moving competitors.
Strategic Opportunities
- Busan-Ulsan port logistics corridor:Underdeveloped aftermarket distribution infrastructure in southeastern industrial zones offers first-mover positioning for specialized filter distributors targeting commercial vehicle fleets.
- Carbon nanofiber composite convergence:Integration of activated carbon layers with HEPA-grade mechanical filtration enables single-filter solutions for particulate and gaseous contaminant removal, commanding premium positioning in luxury vehicle segments.
- Ministry of Environment air quality directives:Tightening ambient PM2.5 thresholds accelerate cabin filter replacement frequency recommendations, expanding recurring revenue pools for service channel partners.
Industry Challenges
- Electrostatic charging technician scarcity:Specialized meltblown production requires operators trained in corona treatment calibration and fiber diameter consistency protocols, constraining domestic capacity expansion.
- End-of-life disposal certification:Validating recycled content ratios and adhesive binder environmental profiles for MFDS type approval demands capital-intensive testing infrastructure that smaller manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Airfilters Market |
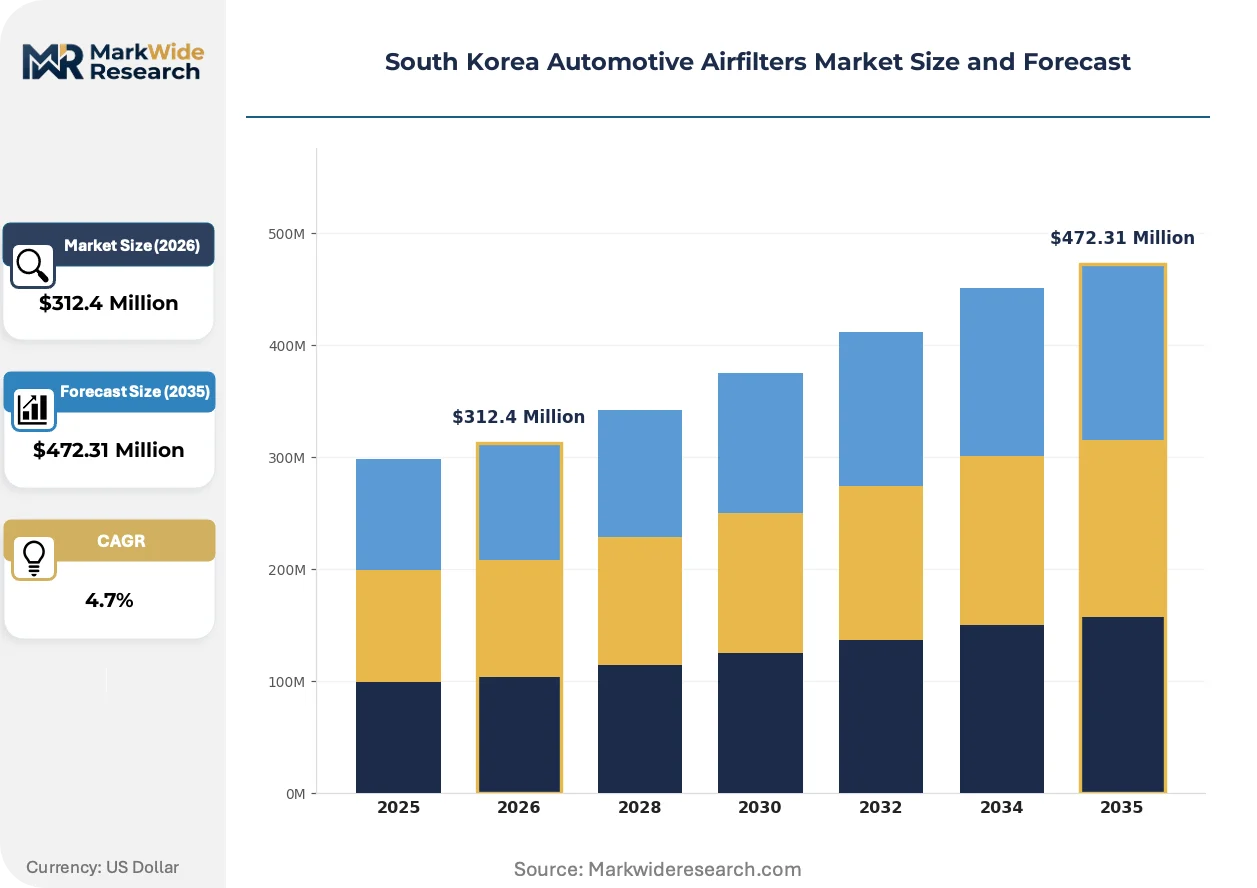
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
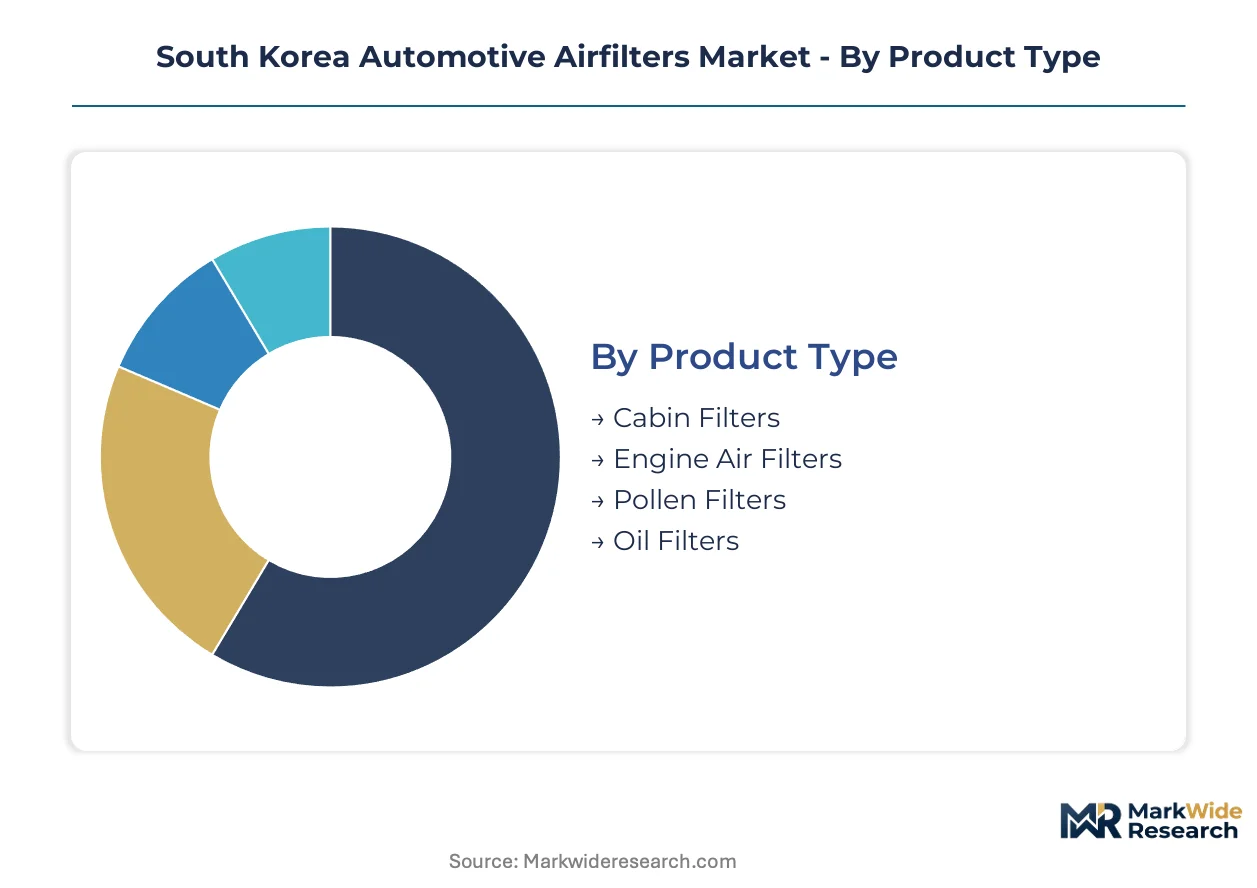
| Segmentation | Product Type: Cabin Filters, Engine Air Filters, Pollen Filters, Oil Filters Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Distribution Channel: Online Retail, Direct Sales, Auto Parts Stores, Service Centers End User: Fleet Owners, Individual Consumers, Workshops, Automotive Manufacturers |
| Companies Covered | Mann+Hummel, K&N Engineering, Allena Group, Purolator Filters LLC, S&B Filters Inc, Advanced Flow Engineering Inc, JS Automobiles, AL Filters, AIRAID, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Airfilters Market Evolving Landscape
Multi-layer electrostatic meltblown composites are actively displacing traditional pleated cellulose architectures across both cabin and engine air filtration segments. This material transition is compressing established supply relationships while opening procurement pathways for synthetic media specialists.
Activated carbon impregnation is decomposing the historical separation between particulate filtration and cabin odor control functions. Premium vehicle OEMs now specify combined-media assemblies as standard equipment, forcing aftermarket suppliers to source dual-capability layers or cede replacement business to authorized dealer networks. The technology is decomposing single-function filter categories into unified air quality management modules.
K-REACH chemical substance controls are tightening compliance thresholds for adhesive binders and flame retardant additives used in automotive filter media. Manufacturers must reformulate polymer compositions and submit extensive toxicological dossiers to the Ministry of Environment before securing domestic market authorization. Cabin filtration applications face the most stringent material safety validations due to direct occupant exposure pathways.
Fleet operators and large-scale dealership groups are consolidating filter procurement through centralized tender processes rather than fragmented distributor relationships. This volume aggregation is compressing margin structures for smaller aftermarket players while rewarding manufacturers with scale economies and direct OEM supply credentials. The behavior shift is most visible in Seoul metropolitan area commercial vehicle servicing networks.
South Korea Automotive Airfilters Market Segmentation
Filter specification divergence across propulsion architectures and procurement channels is fragmenting addressable demand into discrete performance tiers. Manufacturers must align media formulations and distribution investments to specific segment velocity rather than treating automotive filtration as a homogeneous replacement cycle business.
Product Type:
Electrostatic meltblown composites are displacing legacy cellulose architectures fastest in segments where cabin air quality metrics drive purchase decisions, while commodity pleated paper faces intensifying price compression from private-label imports.
- Cabin Filters:Multi-layer synthetic nonwoven assemblies with activated carbon impregnation now dominate OEM specifications for Hyundai-Kia vehicle platforms. Gyeonggi Province aftermarket distributors report accelerated upgrade cycles as MFDS material safety standards under K-REACH rules invalidate legacy adhesive formulations.
- Engine Air Filters:Pleated cellulose remains the cost-optimized baseline for internal combustion vehicle parc maintenance, though synthetic blends gain share in performance-oriented modified vehicle segments. Busan-Ulsan corridor commercial fleets prioritize durability-rated media to extend service intervals.
- Pollen Filters:Basic mechanical filtration layers without electrostatic charging serve economy-tier replacement demand.
- Oil Filters:Spin-on and cartridge formats follow distinct procurement patterns tied to lube service bundling.
Cabin Filters retain volume leadership; Engine Air Filters hold the steepest expansion curve as thermal management complexity in electrified powertrains multiplies filter count per vehicle.
Vehicle Type:
Propulsion architecture determines media specification intensity more than vehicle size class, with battery electric platforms requiring specialized thermal management filtration that legacy suppliers struggle to provision.
- Electric Vehicles:Battery compartment ventilation and HVAC system architectures demand electrostatic meltblown composites with distinct pressure-drop profiles calibrated for thermal runaway prevention protocols. Gyeonggi Province supplier belt concentration near Hyundai Motor Group complexes accelerates localized procurement relationships for these specialized formats.
- Passenger Cars:HEPA-grade cabin filtration specifications are collapsing the gap between aftermarket commodity filters and OEM-installed systems, forcing tier-2 suppliers to reformulate media compositions or surrender premium positioning in Seoul metropolitan area service networks.
- Commercial Vehicles:Fleet operators consolidate procurement through centralized tender processes rather than fragmented distributor relationships.
- Motorcycles:Compact engine air intake designs favor low-resistance pleated media with minimal packaging volume.
Passenger Cars dominate current revenue pools; Electric Vehicles are climbing the fastest as OEM procurement volumes scale with domestic BEV production targets.
Distribution Channel:
Channel selection determines margin capture and brand positioning simultaneously, with direct OEM supply relationships offering volume stability at compressed yields while aftermarket pathways preserve pricing power for certified premium products.
- Auto Parts Stores:Dense aftermarket demand clusters in Gyeonggi Province sustain specialized distributor networks serving independent workshops. These outlets capture replacement cycle revenue from consumers prioritizing immediate availability over online price comparison.
- Service Centers:Authorized dealer networks leverage OEM supply credentials to bundle cabin filter replacement with scheduled maintenance intervals, capturing premium positioning as K-REACH compliance validates specialized media formulations.
- Online Retail:Price-transparent platforms compress margins for commodity-grade products while enabling direct-to-consumer access for performance-oriented brands.
- Direct Sales:Fleet operators and large-scale dealership groups consolidate procurement through centralized tender processes.
Service Centers command the highest attachment rates; Online Retail is gaining share fastest among individual consumer segments.
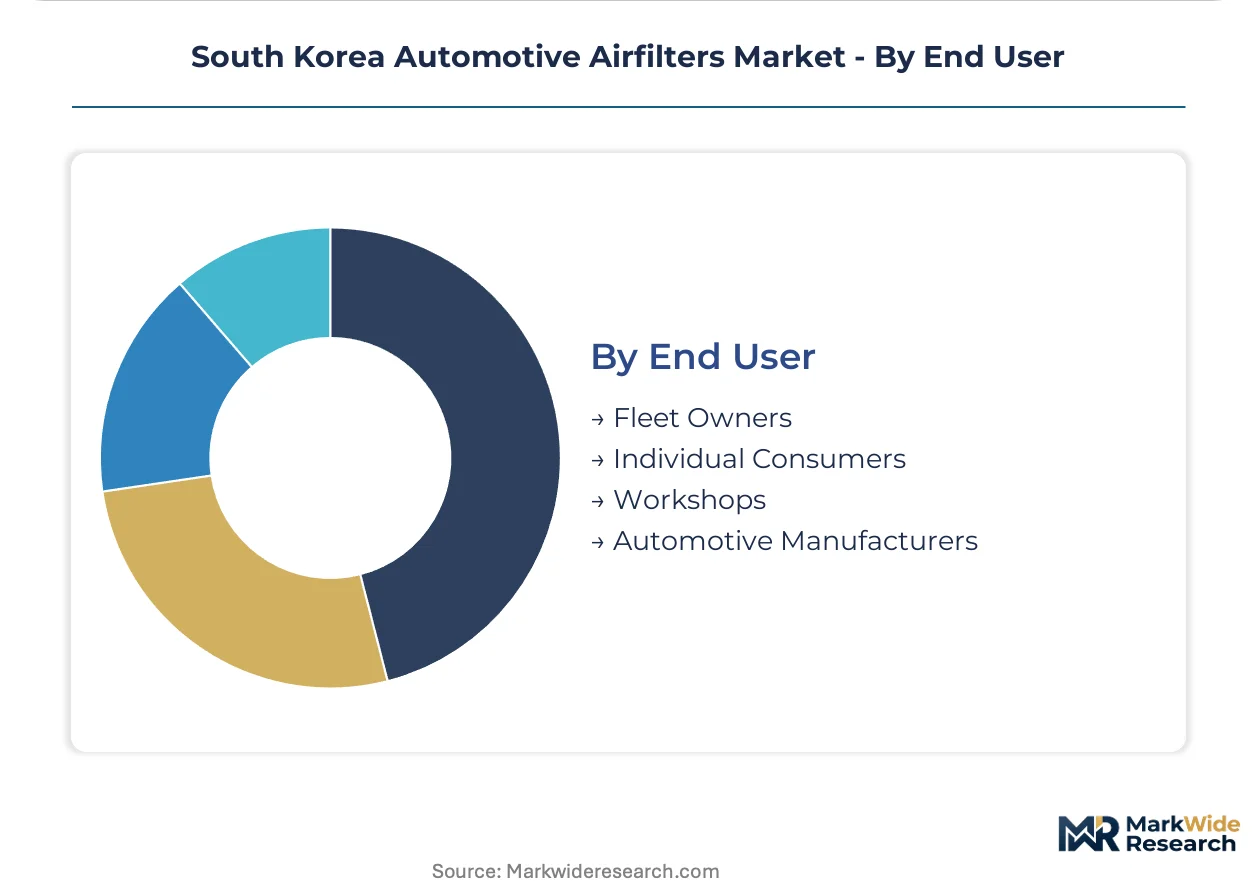
End User:
Procurement sophistication varies sharply across user categories, with fleet operators deploying total-cost-of-ownership analytics while individual consumers respond to visible contamination indicators and replacement interval reminders.
- Automotive Manufacturers:Hyundai Motor Group and Kia specify HEPA-grade cabin filtration as standard equipment across premium vehicle segments, forcing aftermarket suppliers to source dual-capability layers or cede replacement business to authorized networks. K-REACH chemical substance controls extend validation timelines for new adhesive formulations.
- Fleet Owners:Commercial vehicle operators in Busan-Ulsan industrial zones prioritize durability-rated media and consolidated procurement through tender processes, rewarding manufacturers with scale economies and direct supply credentials.
- Individual Consumers:Purchase decisions respond to visible contamination and interval reminders.
- Workshops:Independent service providers balance part availability against margin retention.
Automotive Manufacturers anchor procurement volume; Fleet Owners are expanding their addressable spend fastest as commercial vehicle parc renewal accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filter manufacturing clusters concentrate heavily around Gyeonggi Province's automotive supplier belt, where proximity to Hyundai Motor Group complexes shapes procurement patterns and just-in-time logistics. Sub-regional demand intensity varies sharply across South Korea's industrial geography, driven by vehicle production concentration, commercial fleet density, and aftermarket service infrastructure maturity.
Seoul Capital Area
Metropolitan Seoul generates the densest aftermarket demand for cabin filtration upgrades as consumer awareness of interior air quality metrics intensifies. MFDS material safety standards under K-REACH chemical compliance rules compel local distributors to validate adhesive formulations before stocking replacement inventory. Service networks in Seoul metropolitan area commercial vehicle servicing clusters report accelerated HEPA-grade specification adoption among fleet operators.
Busan-Ulsan
Southeastern industrial zones anchor heavy commercial vehicle parc maintenance with durability-rated media priorities extending service intervals. The Busan-Ulsan port logistics corridor remains underdeveloped for specialized filter distribution, creating first-mover positioning opportunities for aftermarket distributors targeting fleet procurement consolidation. Local Ministry of Environment air quality directives tighten PM2.5 thresholds faster than national baselines, accelerating replacement frequency recommendations.
Daegu-Gyeongbuk
Textile and machinery manufacturing heritage in this region supports emerging electrostatic meltblown composite fabrication capabilities. Daegu-Gyeongbuk technical training institutes struggle to produce sufficient corona treatment calibration specialists, constraining domestic capacity expansion for advanced media production. Regional suppliers increasingly source specialized substrate layers from imported channels, exposing procurement to shipping lane disruption risks.
Daejeon-Sejong
Administrative capital functions concentrate regulatory compliance expertise and MFDS type approval testing infrastructure. Daejeon-Sejong laboratories validate recycled content ratios and adhesive binder environmental profiles for manufacturers seeking domestic market authorization. Government procurement vehicles operating from this region specify premium cabin filtration as standard equipment, creating reference demand for adjacent consumer markets.
Gwangju-Honam
Southwestern agricultural and light industrial vehicle fleets generate steady baseline demand for pleated cellulose engine air filters. Gwangju-Honam aftermarket channels remain fragmented across independent workshops with limited access to synthetic nonwoven inventory. K-REACH chemical substance notification protocols extend product validation cycles for regional distributors attempting to upgrade beyond commodity paper formats.
South Korea Automotive Airfilters Market Competitive Landscape
Concentration sits with multinational filtration specialists and domestic aftermarket distributors serving distinct procurement channels. The supplier base fragments across three functional tiers: membrane technology owners commanding OEM supply relationships, performance-oriented specialists capturing modified vehicle segments, and localized fabricators anchoring aftermarket distribution networks. Competitive dynamics revolve around K-REACH compliance validation speed and captive meltblown capacity investments rather than price alone.
Among the named participants, Mann+Hummel and K&N Engineering exemplify contrasting strategic archetypes within this structure. Mann+Hummel represents the membrane technology tier with established OEM supply credentials, while K&N Engineering occupies the performance-specialist position targeting modified vehicle demand. Allena Group anchors the domestic fabrication tier with localized production serving regional aftermarket distributors. These three patterns illustrate how competitive positioning in South Korea's automotive airfilters market depends on technology ownership depth, channel access, and regulatory compliance infrastructure rather than scale economies alone.
| Leading Market Players |
|---|
| Mann+Hummel |
| K&N Engineering |
| Allena Group |
| Purolator Filters LLC |
| S&B Filters Inc |
| Advanced Flow Engineering Inc |
| JS Automobiles |
| AL Filters |
| AIRAID |
| Others |
Value Network & Pricing Analysis
K-REACH chemical compliance rules gate both supplier qualification and price differentiation simultaneously, compelling manufacturers to fund capital-intensive testing infrastructure that separates certified premium tiers from commodity alternatives while MFDS material safety standards invalidate legacy formulations across the installed base.
Pricing Analysis
K-REACH dictates the pricing tier structure across South Korea's automotive airfilters market, with three-tier pricing stratifying across OEM-certified premium, aftermarket standard, and economy private-label levels. Price differentiation hinges on certification grade and volume scale, with authorized dealer networks capturing premium positioning through bundled service intervals. Cost compression in commodity pleated cellulose intensifies because of private-label import competition, while fleet operators deploying total-cost-of-ownership analytics prove least price-sensitive among buyer segments.
Supply Chain Analysis
Container availability fluctuations on Busan-Ulsan port lanes expose domestic manufacturers to shipping schedule disruptions and currency exchange pressures. Synthetic nonwoven substrate supply concentrates in China, Germany, and Japan, with electrostatic meltblown composites and activated carbon layers drawing from specialized foreign fabricators. Single-source vulnerability for corona-treated media creates procurement risk. Distribution runs through Gyeonggi Province's dense aftermarket clusters serving Hyundai Motor Group supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as propulsion architecture divergence creates distinct performance tiers, with battery electric vehicle thermal management requirements opening niches beyond legacy engine intake applications.
For Market Incumbents: Shield premium positioning by deepening backward integration into captive meltblown capacity, insulating gross margins from polypropylene resin cost volatility while accelerating K-REACH validation timelines to outpace reformulation cycles threatened by emerging synthetic media specialists.
For New Entrants and Emerging Players: Anchor in the Busan-Ulsan port logistics corridor where underdeveloped aftermarket infrastructure serves commercial fleet consolidation, targeting durability-rated media procurement through tender processes rather than fragmented distributor relationships.
For Investors and Strategic Acquirers: MFDS type approval infrastructure reshapes the acquisition landscape, favoring targets with in-house testing capabilities and established OEM supply credentials over pure-play distributors. Long-term viability centers on electrification content expansion. Watch electrostatic charging technician scarcity as inflection signal for capacity-constrained premium tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Meltblown Capacity Expansion | Insulates margin structures from petrochemical feedstock volatility and import dependency. |
| K-REACH Compliance Infrastructure Investment | Accelerates product validation timelines against 12-18 month notification protocols. |
| Carbon Nanofiber Composite Development | Captures luxury vehicle segment demand for unified particulate and gaseous filtration. |
| Busan-Ulsan Distribution Network Buildout | Secures first-mover positioning in underdeveloped commercial fleet servicing corridors. |
| Electrostatic Charging Technician Training Programs | Alleviates corona treatment calibration scarcity constraining domestic capacity expansion. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership service managers anchored the qualitative base, triangulated with secondary validation from vehicle production databases, customs import records, MFDS type approval filings, and K-REACH notification registries across bottom-up and top-down approaches.
Sensitivity analysis framed the quantitative modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions over the projection horizon. CAGRs derived from segment-level buildups incorporating battery electric vehicle thermal management filter counts, replacement cycle elongation effects, and cabin air quality specification upgrade velocities.
Material uncertainties — polypropylene resin price shocks, shipping lane disruptions, and K-REACH registration delays — sit outside the modeled envelope, with forecasts reflecting assumptions about regulatory stability and feedstock availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
External Combustion Engine Market