
 Automotive Stabilizer Bar Link Market | 2026-2036
Automotive Stabilizer Bar Link Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Stabilizer Bar Link Market Outlook
Lightweight composite manufacturing is reconfiguring how stabilizer bar links achieve strength-to-weight targets for modern suspension systems. ZF Friedrichshafen AG leverages its integrated chassis systems portfolio to anchor European OEM supply chains. Tenneco Inc. competes through aftermarket channel density across North America. Mubea Group specializes in high-performance spring and stabilizer technologies for premium vehicle architectures.
An automotive stabilizer bar link is a suspension component that mechanically connects the stabilizer bar to the control arm or strut, typically manufactured from forged steel or aluminum alloy with elastomer bushings, and functions to transfer torsional load and reduce body roll during cornering maneuvers. Standard links still occupy the largest volume share across mass-market vehicle programs, while adjustable links are gaining traction in performance and off-road segments where ride-height customization commands premium positioning. Aluminum material grades are displacing conventional steel in electric vehicle platforms where unsprung mass reduction directly extends driving range.
NHTSA crashworthiness standards and EPA fuel economy mandates in the United States, alongside REACH material compliance and CE marking requirements in Europe, collectively push suppliers toward validated lightweight designs with full material traceability. China's GB standards and MIIT vehicle certification protocols enforce domestic testing regimes that filter non-compliant imports. Stakeholders must monitor how regional decarbonization timelines rewrite material qualification roadmaps and procurement specifications.
Market Dynamics
Electric vehicle platform architectures are reconfiguring material specifications across the automotive stabilizer bar link supply base, with unsprung mass reduction emerging as the decisive engineering priority for OEM sourcing teams.
Growth Catalysts
- NHTSA lightweighting mandates:Federal fuel economy standards compel automakers to specify aluminum alloy grades over forged steel in suspension subassemblies, expanding addressable volume for advanced material suppliers.
- China's MIIT vehicle certification:Domestic production quotas for new energy vehicles accelerate demand for mass-optimized chassis components that preserve battery range.
- Hollow-bar manufacturing:Advanced tube-forming processes enable 30-40% mass reduction without torsional stiffness loss, positioning suppliers with thermal processing expertise for platform wins.
Market Restraints
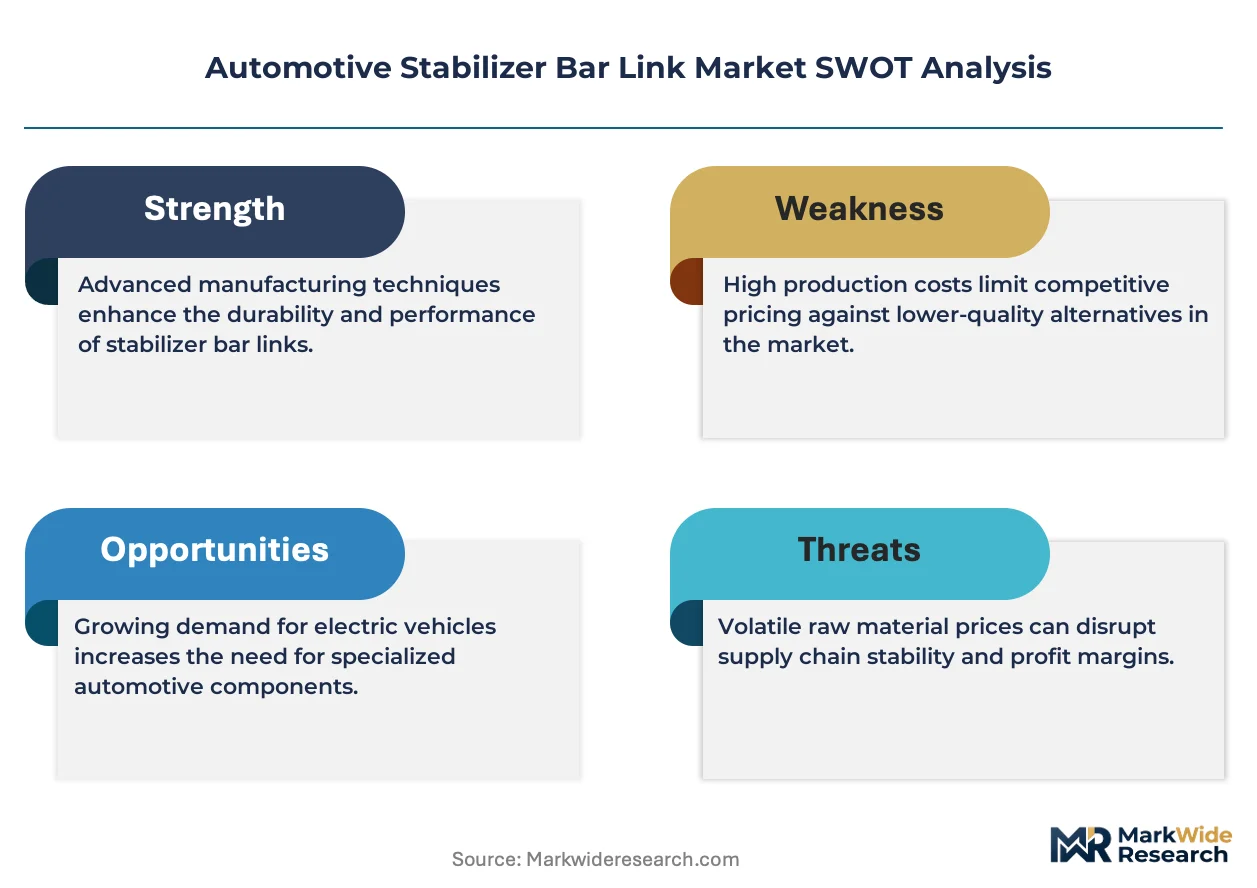
- Aluminum price volatility:LME aluminum contract swings compress margin predictability for extrusion-dependent manufacturers locked into annual OEM pricing agreements.
- Tooling concentration in Germany:High-volume forging die production clusters around KBA-regulated supplier parks, creating single-source vulnerability for Tier 2 stampers.
- REACH substance restrictions:ECHA candidate list expansions for elastomer bushings force reformulation cycles that extend qualification timelines by 18-24 months.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic value-add thresholds create first-mover advantage for suppliers establishing forging and heat-treatment capacity in Tamil Nadu or Gujarat.
- Adjustable link aftermarket:Performance tuning shops and off-road retrofitters seek ride-height-variable hardware, opening channel diversification beyond OEM captive supply.
- Closed-loop aluminum recycling:Press-to-powder metallurgy convergence with OEM circularity targets enables certified low-carbon material positioning for EU Green Deal procurement.
Industry Challenges
- Multi-axis CNC programming:Complex hollow-bar geometries require simultaneous five-axis machining capabilities scarce in traditional stamping shops, constraining supplier base expansion.
- GB standard homologation:China's MIIT testing protocols demand in-country crash simulation validation, forcing duplicate certification investment for export-focused manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Stabilizer Bar Link Market |
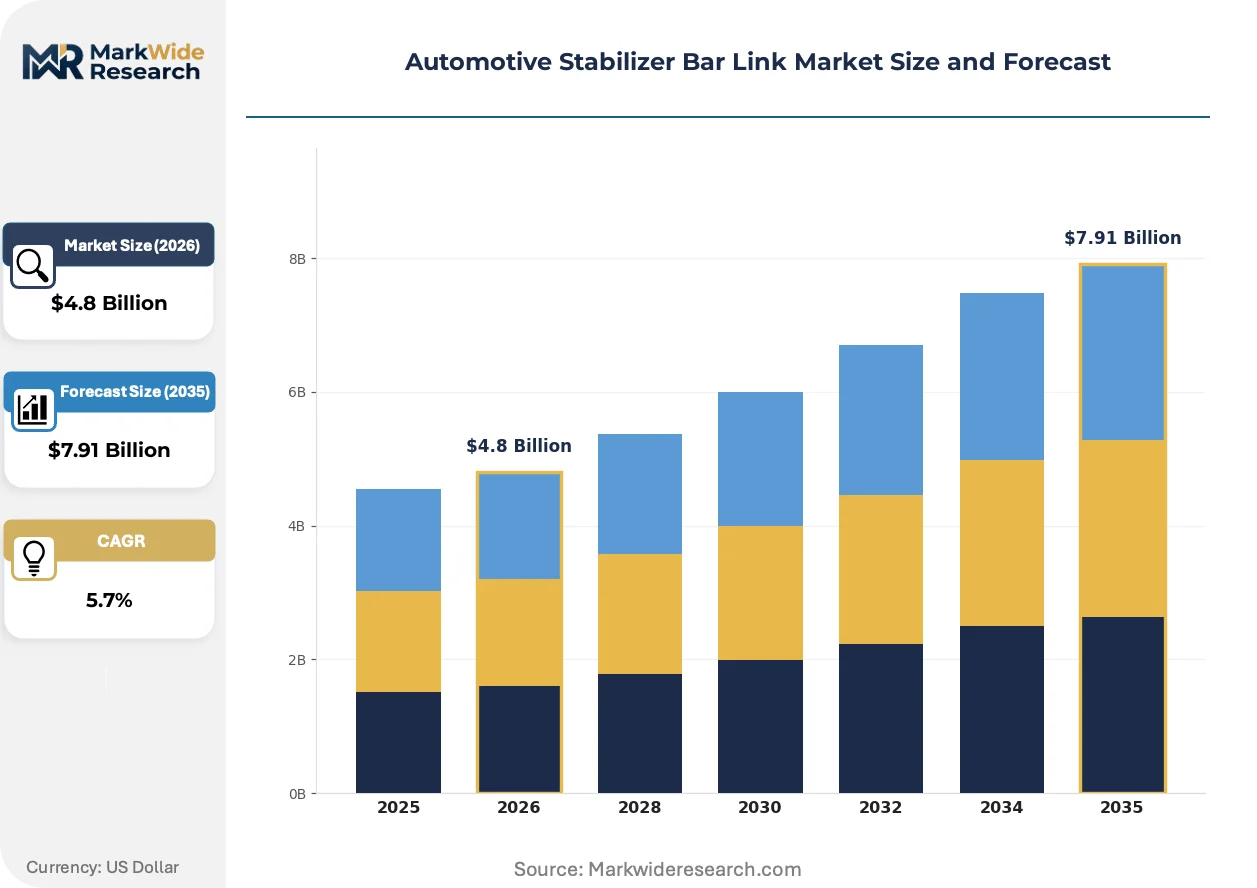
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Link, Adjustable Link, Heavy-Duty Link, Specialty Link Material: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Front, Rear, Independent Suspension, Solid Axle |
| Companies Covered | ZF Friedrichshafen AG, Tenneco Inc., Sogefi Group, Mubea Group, AB SKF, NHK International Corporation, Teknorot, Synergy Manufacturing, Ruian Wuhuan Auto Parts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Stabilizer Bar Link Market Strategic Shifts
Sensor integration and predictive maintenance architectures are embedding intelligence into chassis hardware, transforming stabilizer bar links from passive mechanical elements into data-generating suspension nodes.
Digital twin simulation is digitizing how forged and extruded links undergo fatigue validation before physical prototyping. Tier 1 suppliers with captive CAE teams compress development cycles by 40% versus benchmark timelines. This capability is digitizing competitive sorting between integrated chassis specialists and component-only vendors.
REACH SCIP database obligations now mandate full material disclosure for elastomer bushings and corrosion coatings entering European vehicle assembly plants. Suppliers without automated substance tracking face manual documentation burdens that erode quote competitiveness. Battery electric vehicle programs absorb the strictest enforcement attention from ECHA national enforcement bodies.
Fleet operators and leasing companies now specify component-level traceability as a procurement precondition, displacing anonymous bulk purchasing. Digital product passports linked to individual VIN records enable residual value optimization and warranty claim defensibility. This behavioral shift concentrates in German and Dutch commercial vehicle parcs where total cost of ownership contracting dominates sourcing decisions.
Automotive Stabilizer Bar Link Market Segmentation
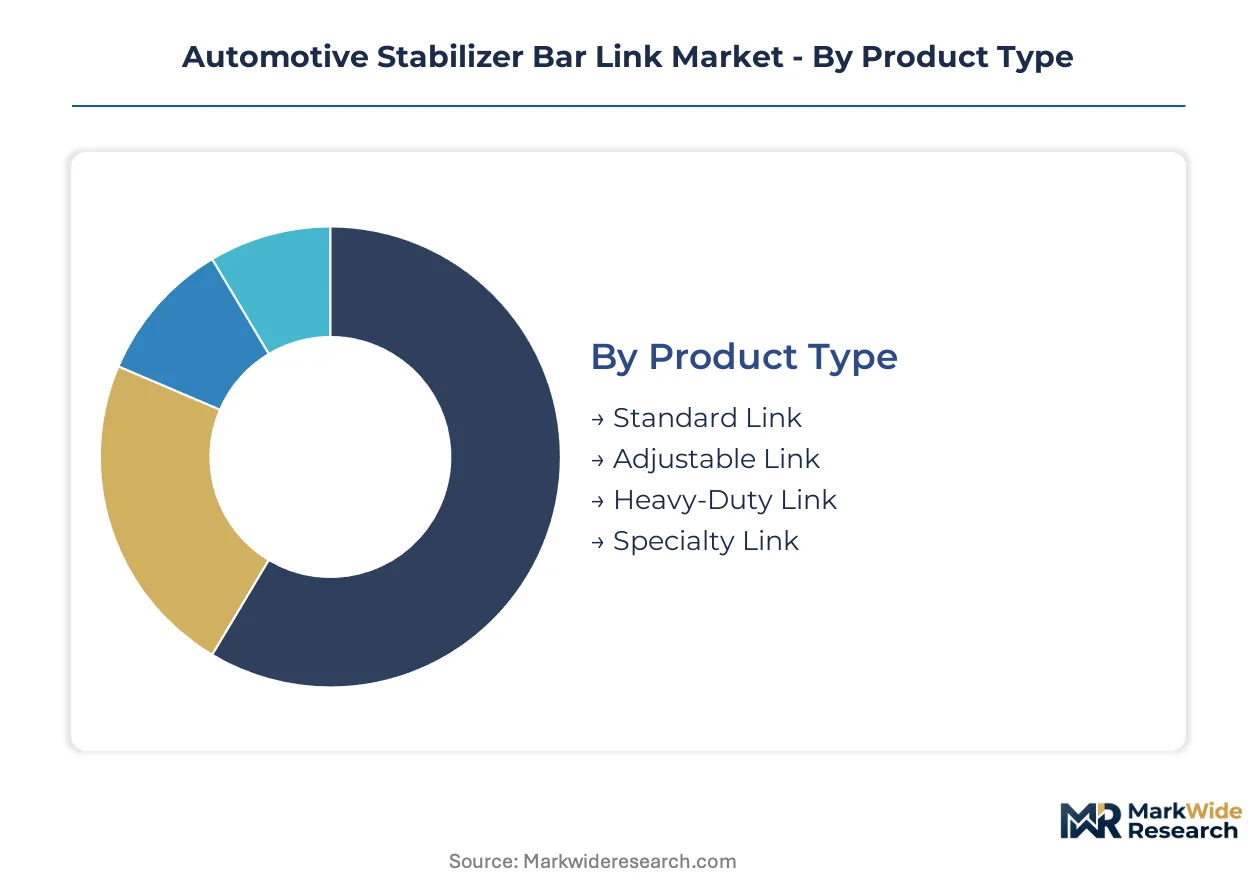
Segmentation in the automotive stabilizer bar link market reveals how after-sales service intensity varies dramatically across product tiers. Material specifications and installation positions determine warranty exposure, replacement frequency, and technical support requirements for distributors and service networks.
Product Type:
After-sales service intensity diverges sharply between fixed-configuration hardware and adjustable variants that demand ongoing technical support.
- Standard Link:Forged steel or aluminum construction with fixed-length geometry dominates mass-market vehicle programs. Replacement demand concentrates in North American and European aftermarket channels where aging vehicle parcs drive steady part turnover, though margin compression limits service bundling opportunities.
- Adjustable Link:Threaded or heim-joint designs enable ride-height customization for performance and off-road applications. Demand clusters with specialty retailers and tuning shops in Germany and the United States where installation support and alignment services command premium pricing.
- Heavy-Duty Link:Reinforced construction for commercial vehicle and fleet applications.
- Specialty Link:Custom geometries for motorsport and limited-production vehicle architectures.
Standard Link holds the largest share; momentum sits with Adjustable Link.
Material:
Cost tier stratification separates commodity metal supply from advanced material positioning that captures OEM lightweighting budgets.
- Steel:Conventional forged or stamped grades remain the volume baseline across internal combustion vehicle platforms. Procurement concentrates with Chinese and Indian domestic OEMs where per-unit cost minimization outweighs mass reduction targets.
- Aluminum:Extruded and forged alloys displace steel in electric vehicle architectures. Specification intensity runs highest with Tesla, BYD, and European premium OEMs where unsprung mass reduction directly extends battery range.
- Composite:Carbon fiber-reinforced polymer links for motorsport and ultra-premium segments.
- Plastic:Glass-filled nylon bushings and isolation components in cost-optimized assemblies.
Steel retains dominant volume; Aluminum climbs the fastest on EV platform penetration.
End User:
Customer type determines contract structure, with captive OEM supply demanding validation investment versus aftermarket spot purchasing.
- OEMs:Original equipment manufacturers specify platform-validated designs with multi-year supply agreements.
- Aftermarket Providers:Independent distributors and retailers serve vehicle replacement demand.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations sourcing locally.
- Tier-1 Suppliers:Chassis system integrators procuring links as subcomponents within larger suspension modules.
OEMs anchor procurement volume; Aftermarket Providers offer the steepest margin expansion path.
Installation Type:
Vehicle architecture geometry dictates link specification, with independent suspension complexity multiplying part variety.
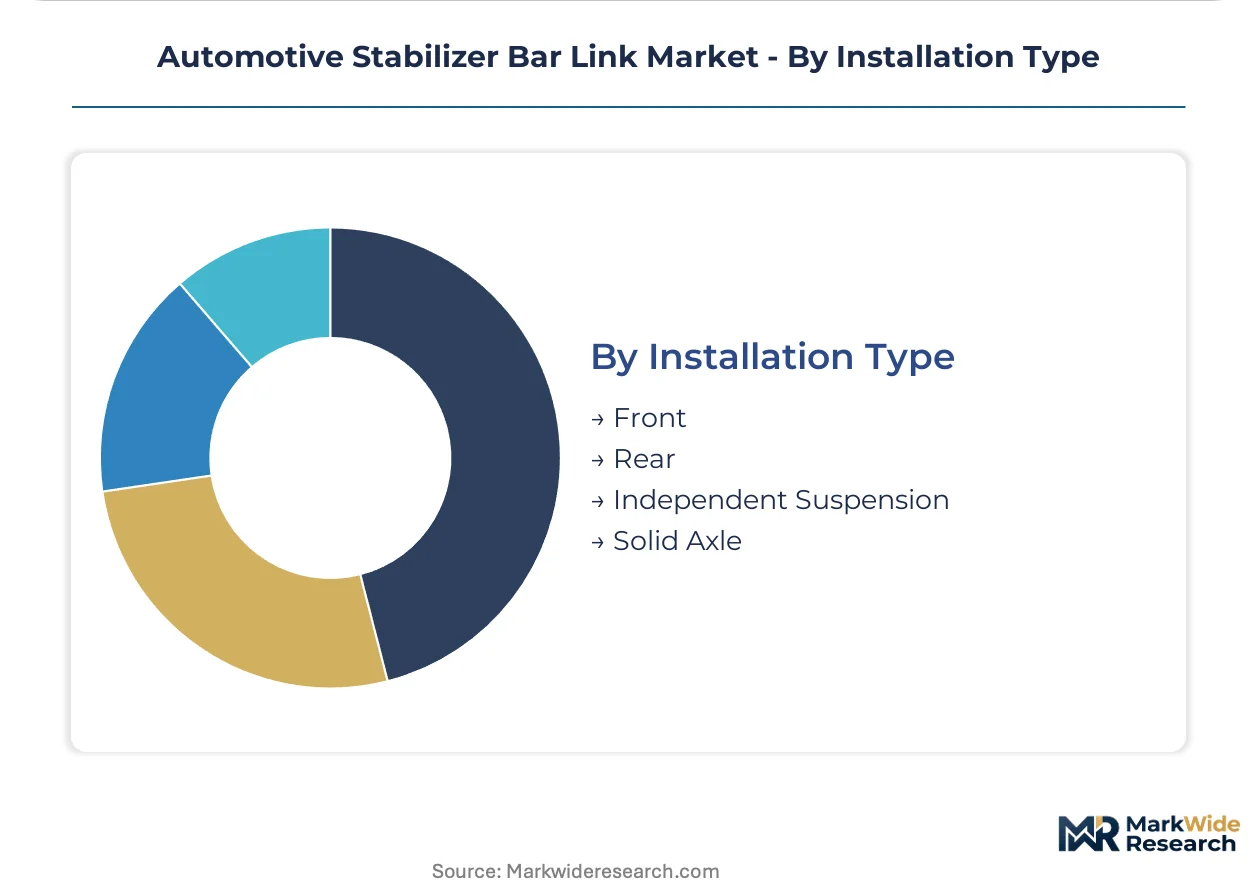
- Front:Higher load-bearing requirements and steering geometry integration.
- Rear:Multi-link and twist-beam configurations driving specification diversity.
- Independent Suspension:Double wishbone and multi-link architectures requiring paired left-right links with precise length tolerance.
- Solid Axle:Simplified single-link designs for commercial and heavy-duty applications.
Front installation commands the largest installed base; Independent Suspension generates the richest product mix diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier 1 suppliers export precision-forged stabilizer bar links to Chinese EV manufacturers, establishing the dominant trade-flow corridor in this component category.
China
Domestic EV production scales from BYD, NIO, and XPeng absorb aluminum-link volumes at rates unmatched elsewhere. MIIT certification protocols enforce GB-standard crash testing that filters non-compliant imports. Yangtze River Delta clusters around Shanghai and Ningbo concentrate forging and heat-treatment capacity for battery-electric platform supply.
Germany
Premium OEM sourcing from BMW, Mercedes-Benz, and Porsche demands hollow-bar geometries with mass-optimized torsional stiffness. KBA-regulated supplier parks in Baden-Württemberg and Lower Saxony mandate full material traceability under REACH SCIP obligations. Stuttgart and Wolfsburg anchor chassis system integration where Tier 1s bundle links with control arm modules.
United States
Detroit Three electrification programs specify aluminum grades for light truck and SUV platforms where unsprung mass reduction preserves battery range. NHTSA fuel economy standards compel lightweighting investments across suspension subassemblies. Michigan and Ohio supplier corridors maintain forging die production clusters vulnerable to single-source concentration.
India
Domestic OEMs Maruti Suzuki and Tata Motors expand aluminum-link adoption as local EV production ramps under PLI scheme incentives. BIS certification and Automotive Mission Plan targets accelerate component localization mandates. Tamil Nadu and Gujarat industrial corridors attract first-mover forging capacity from export-focused manufacturers.
Japan
Toyota and Honda hybrid architectures sustain demand for steel-link baselines alongside incremental aluminum penetration in pure-electric models. METI carbon-neutrality roadmaps pressure suppliers toward closed-loop material sourcing. Aichi Prefecture and Kanto region chassis specialists integrate links with proprietary suspension module designs for captive OEM supply.
Automotive Stabilizer Bar Link Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates volume among integrated chassis system houses while fragmenting the long tail of component-only vendors. Consolidation pressure runs highest in Europe where KBA-regulated supplier parks favor Tier 1s with captive CAE and forging capabilities. Three archetypes dominate: integrated chassis specialists with full suspension module portfolios, aluminum extrusion-focused lightweighting pure-plays, and aftermarket channel operators with distribution density in North America. M&A activity targets hollow-bar manufacturing expertise, while capacity expansion concentrates in China's Yangtze River Delta to serve domestic EV platform demand.
Within the integrated chassis specialist tier, ZF Friedrichshafen AG and Tenneco Inc. exemplify platform-scale positioning where suspension module bundling captures OEM multi-year supply agreements. Mubea Group occupies a specialist position in high-performance spring and stabilizer technologies for premium vehicle architectures. Among Chinese fabricators, Ruian Wuhuan Auto Parts represents the cost-optimized volume tier supplying domestic OEMs with steel-link baselines, while Teknorot anchors Turkish-based aftermarket channel density across European and Middle Eastern replacement markets.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Tenneco Inc. |
| Sogefi Group |
| Mubea Group |
| AB SKF |
| NHK International Corporation |
| Teknorot |
| Synergy Manufacturing |
| Ruian Wuhuan Auto Parts |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta forging clusters around Shanghai and Ningbo concentrate hollow-bar heat-treatment capacity for electric vehicle platforms, translating upstream aluminum extrusion scale into downstream pricing leverage for Tier 1 chassis integrators serving BYD and NIO.
Pricing Analysis
Steel-forged legacy links, aluminum extrusion current-generation hardware, and carbon-reinforced next-generation prototypes occupy distinct pricing strata. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under GB standards and REACH SCIP obligations. Pricing pressure stems from LME aluminum contract volatility compressing margin predictability for extrusion-dependent manufacturers locked into annual OEM agreements. Chinese domestic OEMs exhibit highest price sensitivity, while German premium OEMs prioritize mass-optimized torsional stiffness over per-unit cost.
Supply Chain Analysis
Foxconn and BYD's component divisions hold substantial contract manufacturing capacity for aluminum link forging and CNC finishing. Raw material flows draw from Chinese aluminum smelters, German forging die producers, and Japanese elastomer compounders. Single-source vulnerability concentrates in KBA-regulated German supplier parks where high-volume die production clusters. Distribution runs through captive OEM supply agreements for platform-validated designs, with aftermarket channels fragmenting across independent distributors and specialty tuning retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation intensifies as electric vehicle platform proliferation multiplies material specification variants, creating specialized niches for hollow-bar specialists, adjustable link retrofitters, and closed-loop aluminum recyclers.
For Market Incumbents: Entrench platform-scale positioning by acquiring hollow-bar manufacturing expertise to defend against aluminum extrusion pure-plays capturing EV lightweighting budgets. Expand heat-treatment capacity in China's Yangtze River Delta to anchor BYD and NIO supply agreements. Deepen backward integration into forging die production to mitigate KBA-regulated supplier park concentration risk.
For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat industrial corridors under PLI scheme incentives represent the most penetrable entry point for first-mover forging and heat-treatment investment. Adjustable link aftermarket channels in Germany and the United States offer ride-height-variable hardware specialization beyond OEM captive supply. Target performance tuning shops with installation support and alignment service bundling.
For Investors and Strategic Acquirers: Long-term, this sits as a circularity-enabling infrastructure play because EU Green Deal procurement mandates and OEM carbon-neutrality roadmaps revalue certified low-carbon material positioning. Acquisition targets should exhibit press-to-powder metallurgy convergence with closed-loop aluminum recycling capabilities. Monitor ECHA enforcement intensity on battery electric vehicle programs as inflection indicator for material traceability premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Hollow-Bar Manufacturing Scale-Up | Thirty-to-forty percent mass reduction without torsional stiffness loss captures Tesla and European premium OEM platform wins. |
| Closed-Loop Aluminum Recycling | Press-to-powder metallurgy convergence with OEM circularity targets enables EU Green Deal procurement positioning. |
| Adjustable Link Aftermarket Expansion | Ride-height-variable hardware opens channel diversification beyond OEM captive supply into German and US tuning shops. |
| India PLI Scheme Capacity Buildout | Domestic value-add thresholds in Tamil Nadu and Gujarat create first-mover advantage for export-focused manufacturers. |
| Digital Product Passport Integration | VIN-linked traceability enables residual value optimization for German and Dutch fleet operator total cost of ownership contracting. |
Study Parameters
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributor operations heads, and chassis system integration specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT certification filings, and REACH SCIP disclosure records. Bottom-up volume modeling triangulated against top-down OEM platform content-per-vehicle estimates.
Scenario bracketing around aluminum price trajectories, EV platform ramp schedules, and regional decarbonization timelines anchored the analytical framework. Segmentation dimensions spanned propulsion architecture, material grade tier, installation position, and end-user contract structure. CAGRs derived from slope-intercept fitting across triangulated demand points, with EV penetration curves and lightweighting mandate compliance schedules as primary forecast inputs.
Stress conditions across LME aluminum volatility bands, GB standard homologation timeline extensions, and REACH substance restriction expansions were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of MIIT new energy vehicle production quotas and ECHA enforcement intensity on battery electric vehicle programs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Europe Automotive Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
North America Automotive Hydraulic Actuators Market