
 Asia-Pacific Automotive Upholstery Market | 2026-2036
Asia-Pacific Automotive Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Upholstery Market Outlook
Modular seat architecture is shifting buyer choice across the Asia-Pacific Automotive Upholstery Market. Toyota Boshoku Corporation leverages its integrated seating systems to anchor supply relationships with Japanese OEMs expanding regionally. Lear Corporation competes through manufacturing scale across multiple ASEAN production bases. Adient PLC differentiates via technology leadership in lightweight foam formulations for electric vehicle platforms.
Automotive upholstery encompasses the textile, leather, synthetic, and foam materials applied to vehicle interior surfaces including seats, headliners, door panels, and floor coverings, typically engineered to meet flame resistance, abrasion durability, and volatile organic compound emission specifications. Its primary commercial purpose is to provide occupant comfort, cabin aesthetics, and brand differentiation while satisfying safety and environmental regulatory thresholds. Seat covers command the largest product type position due to direct occupant contact and replacement frequency, while leather and advanced fabric materials capture expanding margin pools as premium vehicle production rises across the region. Foam substrates represent the fastest-growing material segment, driven by weight reduction mandates and thermal management requirements in battery electric vehicles.
China's SAMR enforces GB standards for interior air quality and material flammability, while Japan's METI oversees JIS standards for automotive textile performance and recycling compliance. India's BIS certification requirements for automotive textiles are tightening import conditions and stimulating domestic supplier qualification programs. Stakeholders must monitor evolving cross-border material certification reciprocity between China, Japan, India, and ASEAN members as regulatory fragmentation threatens supply chain consolidation strategies.
Market Dynamics
Modular seat architecture is compressing supplier tiers across the Asia-Pacific Automotive Upholstery Market as OEMs seek interchangeable interior platforms that reduce tooling costs and accelerate model refresh cycles.
Growth Catalysts
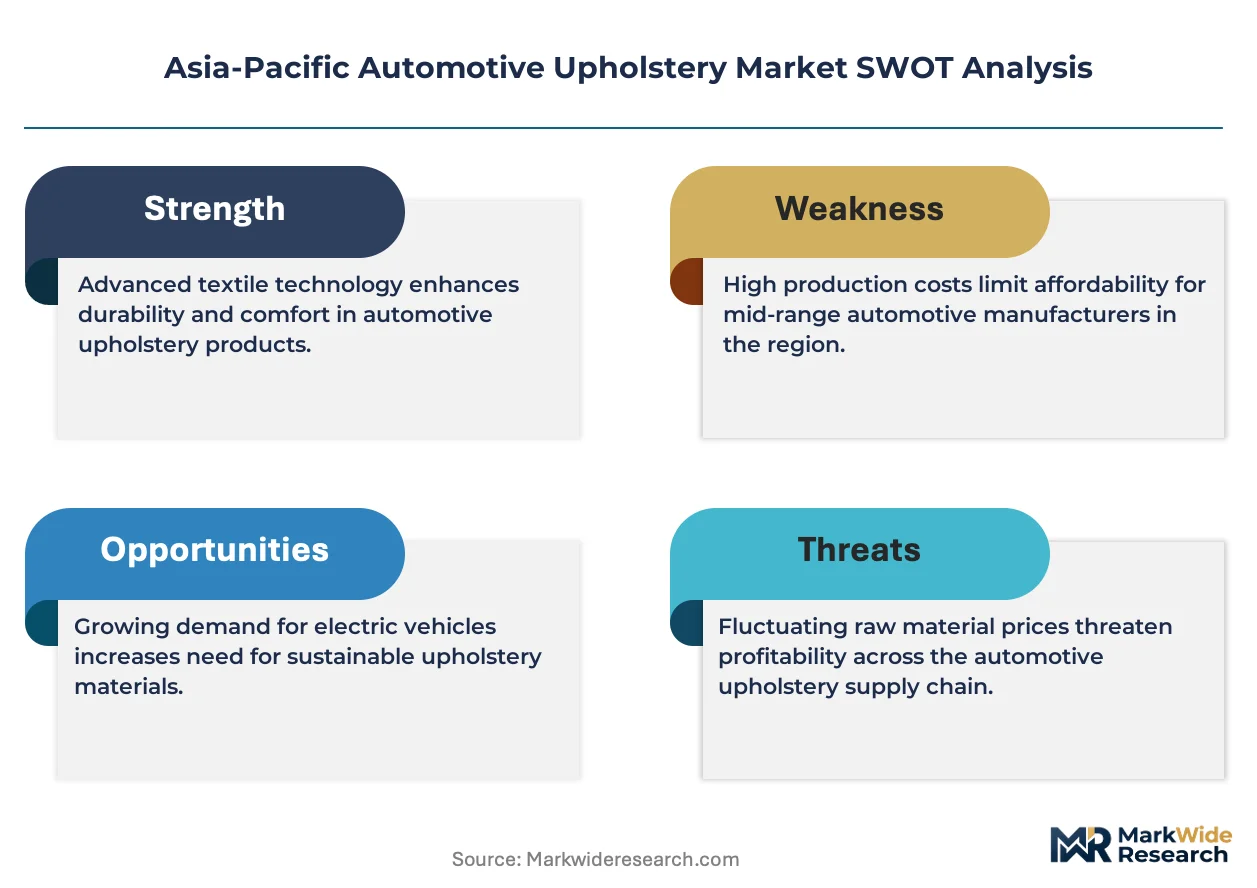
- China's GB standards for cabin air quality:Mandatory VOC emission limits are forcing material upgrades across supplier networks, creating pull-through demand for compliant foam substrates and synthetic leathers in domestic production facilities.
- Battery electric vehicle thermal management:Foam substrates with engineered thermal properties are displacing conventional materials in EV seat construction as manufacturers address battery heat transfer concerns.
- Yangtze River Delta concentration:Tier-1 seating suppliers cluster within 200 kilometers of Shanghai, enabling just-in-sequence delivery to Volkswagen, Tesla, and BYD assembly plants with compressed lead times.
Market Restraints
- Petrochemical input volatility:Polyurethane foam feedstock prices fluctuate with crude oil and propylene oxide markets, compressing margins for mid-tier suppliers locked into annual OEM contracts.
- Japanese supplier dominance:Toyota Boshoku and NHK Spring control premium seating IP and regional patent portfolios, limiting technology access for ASEAN-based competitors.
- Recyclability mandates:Japan's METI end-of-life vehicle regulations impose material separation requirements that increase disassembly costs for multi-layer seat constructions.
Strategic Opportunities
- India's Tamil Nadu automotive corridor:Hyundai, Kia, and Renault-Nissan expansion plans are outpacing qualified domestic upholstery capacity, opening qualification windows for ASEAN suppliers with BIS certification.
- Smart textile integration:Convergence of conductive yarns and pressure-sensing foams enables occupant monitoring systems that OEMs bundle into subscription-based wellness packages.
- Thailand BOI incentives:Board of Investment tax holidays for EV component manufacturing are attracting foam injection molding investments to serve emerging ASEAN electric vehicle assembly.
Industry Challenges
- Cross-border certification reciprocity gaps:BIS, GB, and JIS testing protocols lack mutual recognition, forcing suppliers to maintain parallel qualification labs for multi-country OEM contracts.
- Legacy sewing automation:Pattern recognition and robotic stitching for complex leather geometries require capital deployment that smaller tier-2 suppliers cannot finance without OEM co-investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Upholstery Market |
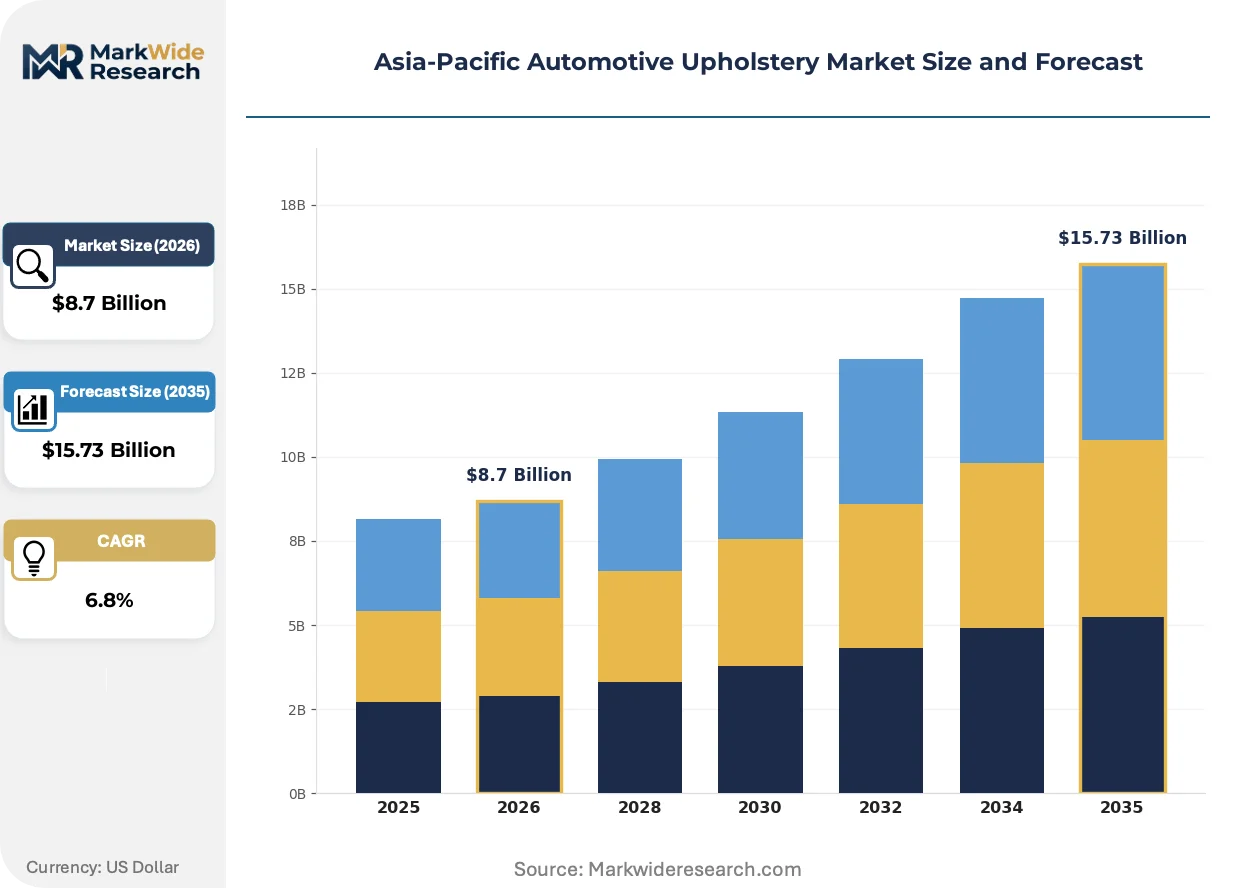
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seat Covers, Headliners, Door Trim, Carpets Material: Leather, Fabric, Vinyl, Foam Vehicle Type: Sedans, SUVs, Trucks, Motorhomes End User: OEMs, Aftermarket Providers, Retailers, Wrapping Services |
| Companies Covered | Suminoe Textile Co. Ltd., Toyota Boshoku Corporation, Lear Corporation, Adient PLC, Faumecia SE, TS Tech Co. Ltd., Hyundai Dymos, Grupo Antolin, Seiren Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Upholstery Market Strategic Shifts
Digital twin simulation of seat comfort performance is compressing physical prototyping cycles while regulatory pressure on material circularity is forcing chemistry innovations across polyurethane and bio-based alternatives.
3D-knitted textile surfaces are modularizing seat cover production by integrating heating elements, ventilation channels, and decorative patterns in single manufacturing steps. Premium EV manufacturers in China are adopting these structures to reduce part counts and assembly labor. The technology is modularizing supplier relationships as knitting equipment suppliers displace traditional cut-and-sew contractors from tier-1 positions.
China's SAMR enforcement of GB/T 27630 cabin air quality standards is accelerating material substitution across foam and adhesive categories. Suppliers must submit third-party VOC test reports for each production batch, increasing documentation overhead. Leather tanneries in Zhejiang province are most affected, retrofitting facilities with closed-loop water systems to meet MEE discharge permits.
Fleet operators and mobility service providers are consolidating upholstery procurement through long-term service contracts that bundle material supply, installation, and refurbishment. This model is displacing spot purchasing of replacement seat covers in commercial vehicle segments. The shift is most visible in India's intercity bus and ride-hailing markets, where Ola and Uber fleet managers negotiate direct supplier relationships.
Asia-Pacific Automotive Upholstery Market Segmentation
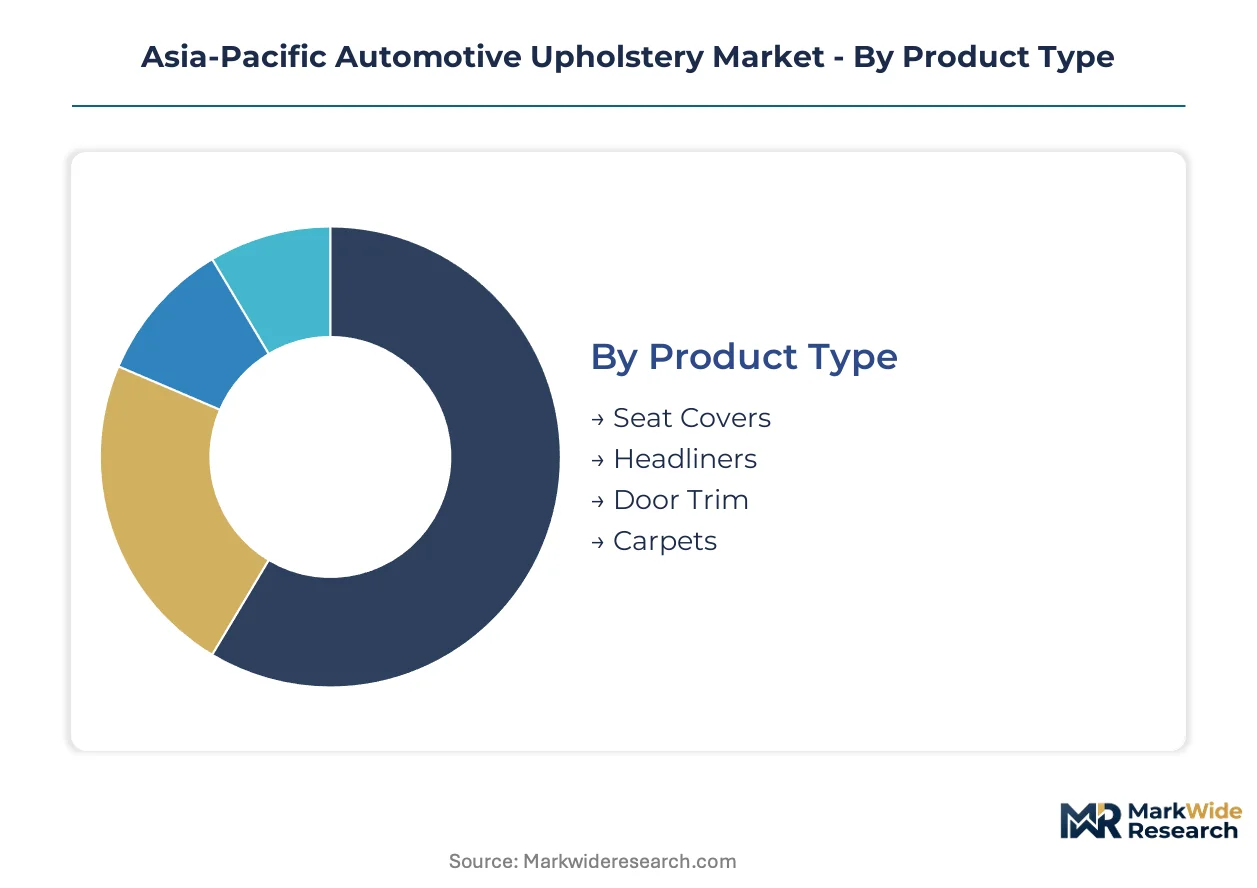
Segmentation in Asia-Pacific automotive upholstery reveals how material specifications, vehicle architecture, and procurement channels fragment supplier strategies. Each dimension carries distinct margin profiles and regulatory exposure across the region's manufacturing clusters.
Product Type:
Seat architecture complexity and replacement frequency separate buyers by tooling investment and aftermarket attachment rates.
- Seat Covers:Direct occupant contact surfaces engineered for abrasion resistance and flame retardancy per GB standards. Demand concentrates in China's Yangtze River Delta for Volkswagen, Tesla, and BYD assembly, driven by just-in-sequence delivery requirements and model refresh acceleration.
- Headliners:Overhead textile or foam-backed panels managing cabin acoustics and overhead console integration. Growth tilts toward India's Tamil Nadu corridor where Hyundai-Kia expansion outpaces qualified domestic capacity, opening qualification windows for ASEAN suppliers with BIS certification.
- Door Trim:Armrest and panel surfacing materials subject to hand-contact wear and side-impact safety integration.
- Carpets:Floor covering systems combining acoustic insulation with stain resistance and pedal interference prevention.
Volume sits with Seat Covers; growth tilts toward Headliners.
Material:
Raw material chemistry and petrochemical exposure divide suppliers by margin volatility and certification burden.
- Foam:Polyurethane substrates engineered for thermal management in battery electric vehicles, displacing conventional materials as manufacturers address heat transfer concerns. China's SAMR VOC enforcement accelerates material substitution across adhesive categories.
- Leather:Natural and synthetic hide materials capturing premium vehicle margin pools as production rises across the region. Zhejiang tanneries retrofit with closed-loop water systems to meet MEE discharge permits under tightening environmental enforcement.
- Fabric:Woven and knitted textiles including 3D-knitted surfaces integrating heating and ventilation channels.
- Vinyl:PVC-based synthetic surfacing materials serving cost-sensitive fleet and commercial vehicle segments.
Foam dominates volume expansion; leather commands premium pricing differentiation.
Vehicle Type:
Platform architecture and interior square footage separate procurement strategies by material yield and customization intensity.
- SUVs:Expanded cabin volumes and third-row configurations multiply upholstery surface area per vehicle. China's BYD and Tesla Shanghai facilities drive specification upgrades across synthetic leather and advanced foam categories.
- Sedans:Standardized seating configurations and high production volumes enable material standardization and scale procurement.
- Trucks:Commercial durability requirements and fleet operator consolidation through long-term service contracts.
- Motorhomes:Residential-grade comfort specifications and low-volume custom fabrication.
SUVs anchor material consumption; motorhomes represent niche customization value.
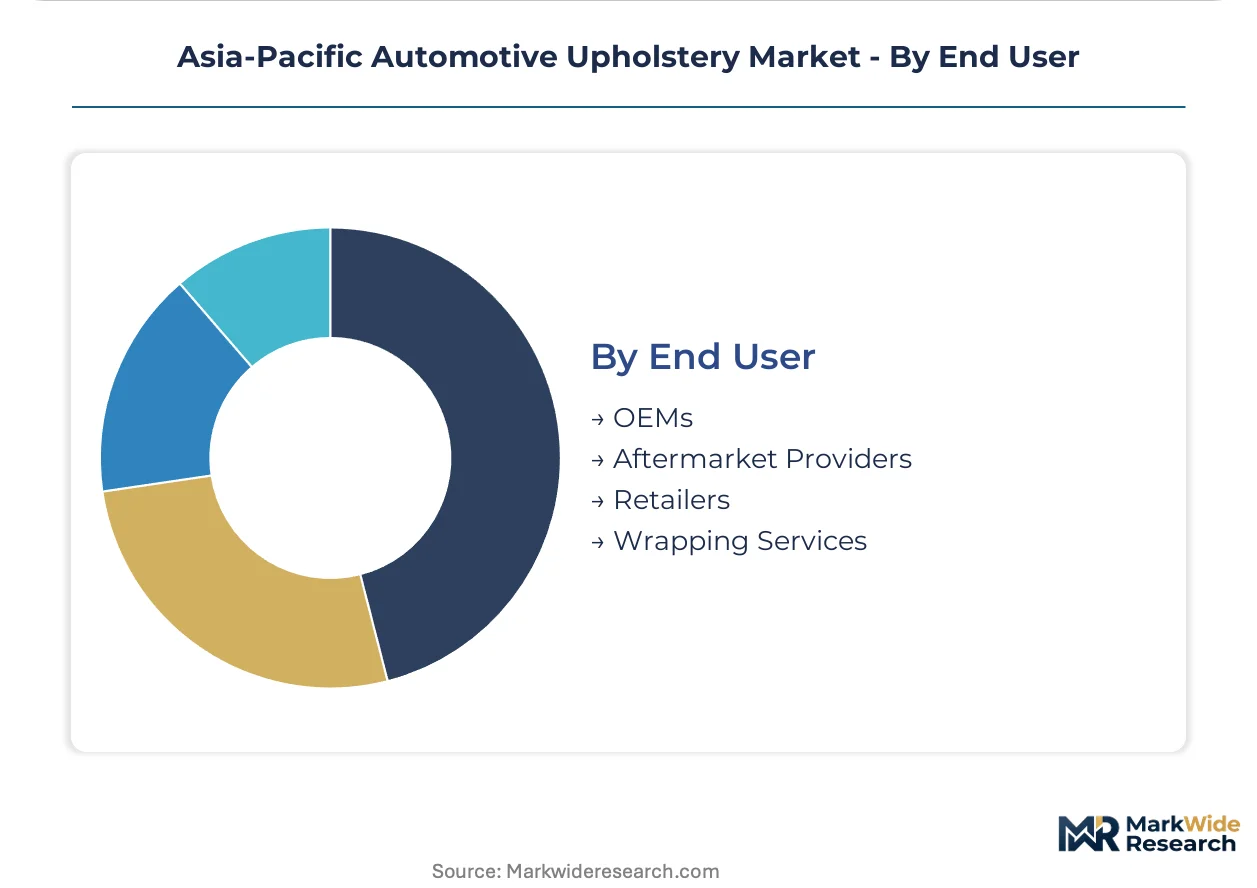
End User:
Contract structure and technical specification authority distinguish procurement channels by margin stability and qualification barriers.
- OEMs:Direct tier-1 supply relationships with Toyota Boshoku, Lear, and Adient governing multi-year platform contracts. Japanese OEMs expanding regionally anchor supply relationships through integrated seating systems.
- Aftermarket Providers:Replacement and refurbishment specialists serving warranty expiration and accident repair channels.
- Retailers:Consumer-direct accessory sales for customization and upgrade markets.
- Wrapping Services:On-demand interior resurfacing for ride-hailing fleets and mobility service providers.
OEMs concentrate volume; wrapping services gain share fastest through fleet operator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment tax holidays for EV component manufacturing are attracting foam injection molding investments to serve emerging ASEAN electric vehicle assembly. This incentive architecture is redistributing supplier capacity across Southeast Asia.
China
BYD and Tesla Shanghai facilities drive specification upgrades across synthetic leather and advanced foam categories. SAMR enforces GB/T 27630 cabin air quality standards that accelerate material substitution across adhesive categories. Yangtze River Delta tier-1 seating suppliers cluster within 200 kilometers of Shanghai, enabling just-in-sequence delivery with compressed lead times.
Japan
Toyota Boshoku and NHK Spring control premium seating IP and regional patent portfolios, limiting technology access for ASEAN-based competitors. METI oversees JIS standards for automotive textile performance and recycling compliance. Kanto region suppliers anchor supply relationships with Japanese OEMs expanding regionally through integrated seating systems.
India
Hyundai, Kia, and Renault-Nissan expansion plans are outpacing qualified domestic upholstery capacity, opening qualification windows for ASEAN suppliers. BIS certification requirements for automotive textiles are tightening import conditions and stimulating domestic supplier qualification programs. Tamil Nadu automotive corridor growth tilts toward headliners where domestic capacity lags.
South Korea
Hyundai Motor Group's EV platform rollout is driving thermal management foam specifications across supplier networks. MFDS-equivalent automotive material standards align with export market requirements for EU and US-bound vehicles. Seoul Capital Area suppliers concentrate R&D functions while Busan-Ulsan handles volume production for export markets.
Thailand
BOI incentives for EV component manufacturing are attracting foam injection molding investments from regional suppliers. Chinese and Japanese OEMs are localizing assembly for ASEAN export markets, pulling upholstery procurement into Thai supplier networks. Eastern Economic Corridor industrial zones concentrate new capacity for battery electric vehicle platforms.
Asia-Pacific Automotive Upholstery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The market structure consolidates around integrated seating system providers with OEM captive relationships, while mid-tier foam and textile suppliers fragment across price-competitive segments. Three archetypes dominate: Japanese keiretsu-affiliated seating integrators, Western multinational component platforms, and emerging Asian material specialists. Competitive intensity centers on M&A for technology access and capacity expansion to serve EV platform qualification windows.
Within the keiretsu-affiliated tier, Toyota Boshoku Corporation exemplifies integrated seating system dominance through OEM supply relationships. Lear Corporation and Adient PLC occupy positions among Western multinational platforms competing through manufacturing scale and technology licensing. These three anchors represent divergent strategic postures: captive supply chain integration versus modular component platform breadth versus lightweight material specialization.
| Leading Market Players |
|---|
| Suminoe Textile Co. Ltd. |
| Toyota Boshoku Corporation |
| Lear Corporation |
| Adient PLC |
| Faumecia SE |
| TS Tech Co. Ltd. |
| Hyundai Dymos |
| Grupo Antolin |
| Seiren Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
OEM just-in-sequence delivery mandates from Volkswagen, Tesla, and BYD assembly plants in the Yangtze River Delta are forcing tier-1 suppliers to absorb logistics coordination costs and compress batch sizes, which elevates pricing for small-lot foam substrate orders while compressing margins on standardized seat cover contracts.
Pricing Analysis
Compressed lead-time premiums dominate contract negotiations as Toyota Boshoku and Lear Corporation extract pricing advantages from OEMs requiring sub-48-hour sequencing flexibility. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC foam substrates from conventional polyurethane and import-dependent synthetic leather categories. Price differentiation hinges on GB/T 27630 compliance documentation and thermal management performance grades. Cost compression in mid-tier synthetic leather runs through petrochemical feedstock volatility and annual contract lock-ins. Fleet operators consolidating procurement through long-term service contracts exhibit highest price sensitivity; premium EV manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Polyurethane foam feedstock supply rests on Chinese propylene oxide producers, Japanese specialty chemical manufacturers, and South Korean petrochemical complexes. Raw material dependencies encompass MDI isocyanates, polyols, and synthetic leather PVC resins. Single-source vulnerability concentrates in MDI supply where three producers control regional capacity. Distribution runs through tier-1 seating integrators with captive OEM relationships, while tier-2 textile and foam specialists fragment across price-competitive aftermarket channels. Cross-border certification reciprocity gaps between BIS, GB, and JIS protocols force parallel qualification labs and elevate compliance costs for multi-country contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over thermal management foam formulations to capture EV platform specification authority and defend against material substitution threats.
For Market Incumbents: To counter ASEAN-based competitors qualifying for India's BIS certification windows, Toyota Boshoku and Lear Corporation should accelerate backward integration into low-VOC polyurethane chemistry and expand foam injection molding capacity within 200 kilometers of Shanghai assembly plants. Captive supply of compliant substrates locks in OEM sequencing relationships and raises rival qualification barriers. For New Entrants and Emerging Players: Digital fleet management platforms offer direct supplier access to Ola and Uber procurement teams bypassing traditional tier-1 gatekeepers. Target India's Tamil Nadu headliner segment where Hyundai-Kia expansion outpaces qualified domestic capacity. Pursue BIS certification reciprocity with Thai BOI-incentivized production bases to qualify for ASEAN supplier networks serving emerging EV assembly. For Investors and Strategic Acquirers: The window for entry favors foam substrate specialists with thermal management IP and established GB certification documentation. Long-term viability centers on battery electric vehicle platform penetration rates across Chinese and ASEAN assembly footprints. Watch for SAMR enforcement actions on VOC compliance as inflection indicators for material substitution velocity and incumbent margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Chemistry | Captive MDI supply secures margin control against petrochemical volatility for tier-1 seating suppliers. |
| GB/T 27630 Certification Investment | Third-party VOC documentation opens just-in-sequence contracts with Tesla and BYD Shanghai facilities. |
| Tamil Nadu Manufacturing Footprint | Proximity to Hyundai-Kia expansion captures headliner demand outpacing qualified domestic Indian capacity. |
| Smart Textile R&D Partnership | Conductive yarn integration enables subscription-based wellness packages for premium EV occupant monitoring. |
| Thai BOI Incentive Utilization | Tax holidays for EV component manufacturing attract foam injection molding serving ASEAN electric vehicle assembly. |
Study Parameters
Independent corroboration across OEM platform engineering directors, tier-1 supplier procurement leads, and aftermarket distribution specialists underwrites the qualitative findings. Primary interviews with seating system integrators, foam substrate technical directors, and BIS certification consultants were validated against vehicle production databases, customs trade records for polyurethane feedstocks, and SAMR regulatory filings. Secondary sources encompassed IHS Markit registration data, China Association of Automobile Manufacturers output statistics, and METI recycling compliance disclosures. Bottom-up segmentation modeling triangulated with top-down macroeconomic demand drivers.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from production ramp schedules, platform lifecycle assumptions, and material substitution elasticity estimates. Industry-specific forecast inputs incorporated battery electric vehicle thermal management foam specifications and BIS certification qualification timelines for Indian market entry.
Inputs from OEM platform engineering contacts and tier-1 supplier procurement leads were available through the study window; gaps in real-time polyurethane feedstock pricing transparency and evolving GB standard enforcement consistency introduce uncertainty bands around margin compression assumptions. Forecasts reflect documented assumptions on EV platform penetration and regulatory reciprocity progress. SAMR VOC enforcement intensity, petrochemical input volatility, and Thai BOI incentive renewal decisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Bushing Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Russia Automotive Electric Actuators Market