
 Global Automotive Selector Lever Market | 2026-2036
Global Automotive Selector Lever Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Selector Lever Market Intelligence
Demand from original equipment manufacturers (OEMs) is bifurcating the automotive selector lever market, favoring suppliers of integrated electronic systems. ZF Friedrichshafen AG leverages its expertise in transmission technologies to offer complete mechatronic solutions. Continental AG differentiates through its focus on human-machine interface (HMI) design and advanced sensor integration. BorgWarner Inc. competes with a portfolio covering both mechanical and electronic shift systems for diverse platforms.
An automotive selector lever is the primary driver interface for choosing a vehicle's transmission gear. Modern systems operate via either a direct mechanical linkage or through electronic signals in shift-by-wire configurations, which require specific actuator and sensor inputs. The transition from manual selector levers to electronic selector levers defines the product evolution. Within the technology segment, push button and rotary dial interfaces are gaining significant share in new passenger vehicle designs.
Functional safety standards, governed by frameworks like ISO 26262, directly impact selector lever design and software validation. National regulators, including the US NHTSA and Germany's KBA, enforce rules on gear selection indication and prevention of unintended vehicle movement. Suppliers must navigate the trade-off between delivering novel user experiences and meeting stringent functional safety requirements.
Market Dynamics
The transition from mechanical linkages to shift-by-wire electronics is the central structural force defining the market. This technological shift decouples the driver's input from the transmission, enabling new design freedoms but also introducing significant software and functional safety complexities.
Growth Catalysts
- Shift-by-Wire Adoption:The proliferation of shift-by-wire systems in mainstream passenger vehicles, particularly in battery electric vehicles (BEVs), directly fuels demand for electronic selector levers and associated control modules.
- Minimalist Cabin Design:Consumer and OEM preference for clean, uncluttered interior aesthetics favors the adoption of compact push-button and rotary dial shifters, which replace bulky traditional mechanical levers.
- EV Mandates:Government regulations in Europe and China mandating transitions to electric vehicles eliminate the need for mechanical transmission linkages, making electronic shifters a default technology for all new EV platforms.
Market Restraints
- High Development Costs:The significant upfront investment required for software development, validation, and hardware integration for shift-by-wire systems creates a high barrier to entry for smaller suppliers.
- Functional Safety Compliance:Adherence to stringent standards like ISO 26262 adds considerable time and expense to the product development lifecycle, requiring extensive risk analysis and fault-tolerant design.
- Semiconductor Dependency:The reliance on a concentrated base of suppliers for critical components like microcontrollers and Hall-effect sensors creates supply chain vulnerabilities and pricing pressures for lever manufacturers.
Strategic Opportunities
- Haptic Feedback Integration:Incorporating advanced haptic feedback and smart surface technologies into selector levers offers a clear path for differentiation in the premium and luxury vehicle segments.
- Commercial Vehicle Systems:Developing standardized, modular electronic shifter solutions for heavy-duty trucks and buses represents a significant opportunity in a segment still dominated by mechanical systems.
- Aftermarket Conversion Kits:There is a niche market for creating aftermarket electronic shifter kits that allow classic and luxury car enthusiasts to upgrade older vehicles with modern shift-by-wire functionality.
Industry Challenges
- Software Validation Complexity:Ensuring software is free from bugs that could lead to unintended vehicle movement is a major technical and liability challenge, scrutinized by regulators like the US NHTSA.
- Platform Integration:Reconciling bespoke HMI designs desired by OEMs with the need for standardized underlying electronic control units creates significant engineering complexity for suppliers.
- Talent Scarcity:A shortage of software and systems engineers with dual expertise in automotive control systems and ISO 26262 compliance protocols constrains development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Selector Lever Market |
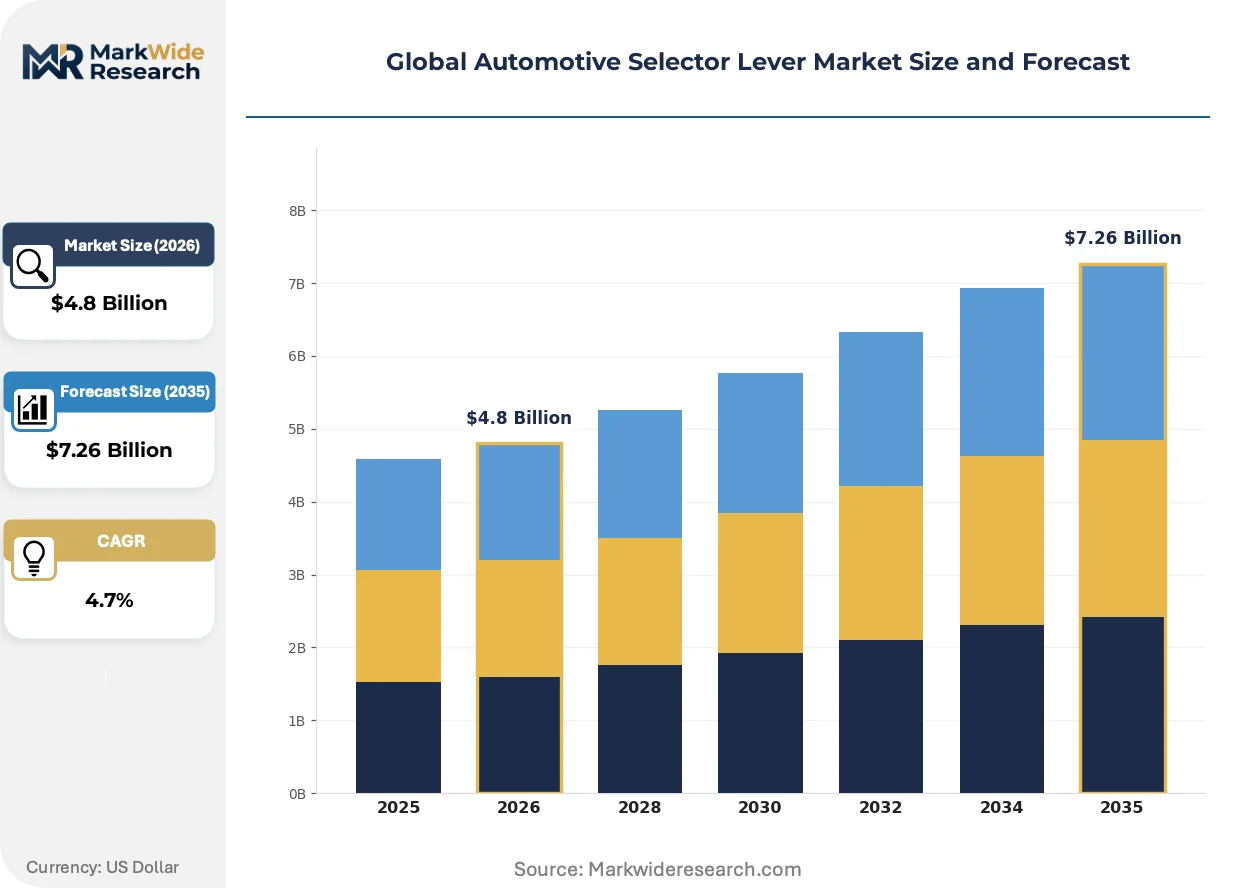
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Selector Lever, Electronic Selector Lever, Hydraulic Selector Lever, Pneumatic Selector Lever Technology: Push Button, Rotary Dial, Touch Sensitive, Lever Shift, Paddle Shift Application: Passenger Vehicles, Commercial Trucks, Construction Machinery, Agricultural Equipment, Recreational Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Replacement Parts Vendors |
| Companies Covered | ZF Friedrichshafen AG, Tokai Rika Co., Ltd, Continental AG, BorgWarner Inc., Leopold Kostal GmbH & Co. KG, Kongsberg Automotive ASA, Magna International Inc., Stoneridge Inc., Lumax Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Selector Lever Market Strategic Shifts & Innovations
Product innovation focuses on the convergence of human-machine interface (HMI) design with stringent functional safety requirements. This balance drives the evolution from simple mechanical devices to sophisticated mechatronic modules that define a vehicle's interior character and safety profile.
Hall-effect sensors and compact electromechanical actuators form the core of modern shift-by-wire technology. Automakers are rapidly adopting these components in new battery-electric and premium vehicle platforms to replace traditional mechanical linkages. This technology is miniaturizing the entire shifter assembly, freeing up valuable center console real estate for designers to use for storage or new control interfaces.
Functional safety standards, particularly ISO 26262, are now a non-negotiable aspect of electronic shifter design. The standard imposes a rigorous framework for hazard analysis, risk assessment, and validation to prevent system failures. This directly impacts component suppliers, who must invest in fault-tolerant hardware and exhaustive software testing to meet specific Automotive Safety Integrity Levels (ASIL).
A clear OEM preference is emerging for unique, brand-specific shifter designs as a point of interior differentiation. This is causing a shift away from commoditized levers toward bespoke solutions like crystal-topped rotary dials or minimalist electronic stalks. This demand-side trend is most pronounced in the luxury vehicle segment, with design decisions heavily influenced by studios in Germany and South Korea.
Global Automotive Selector Lever Market Segmentation
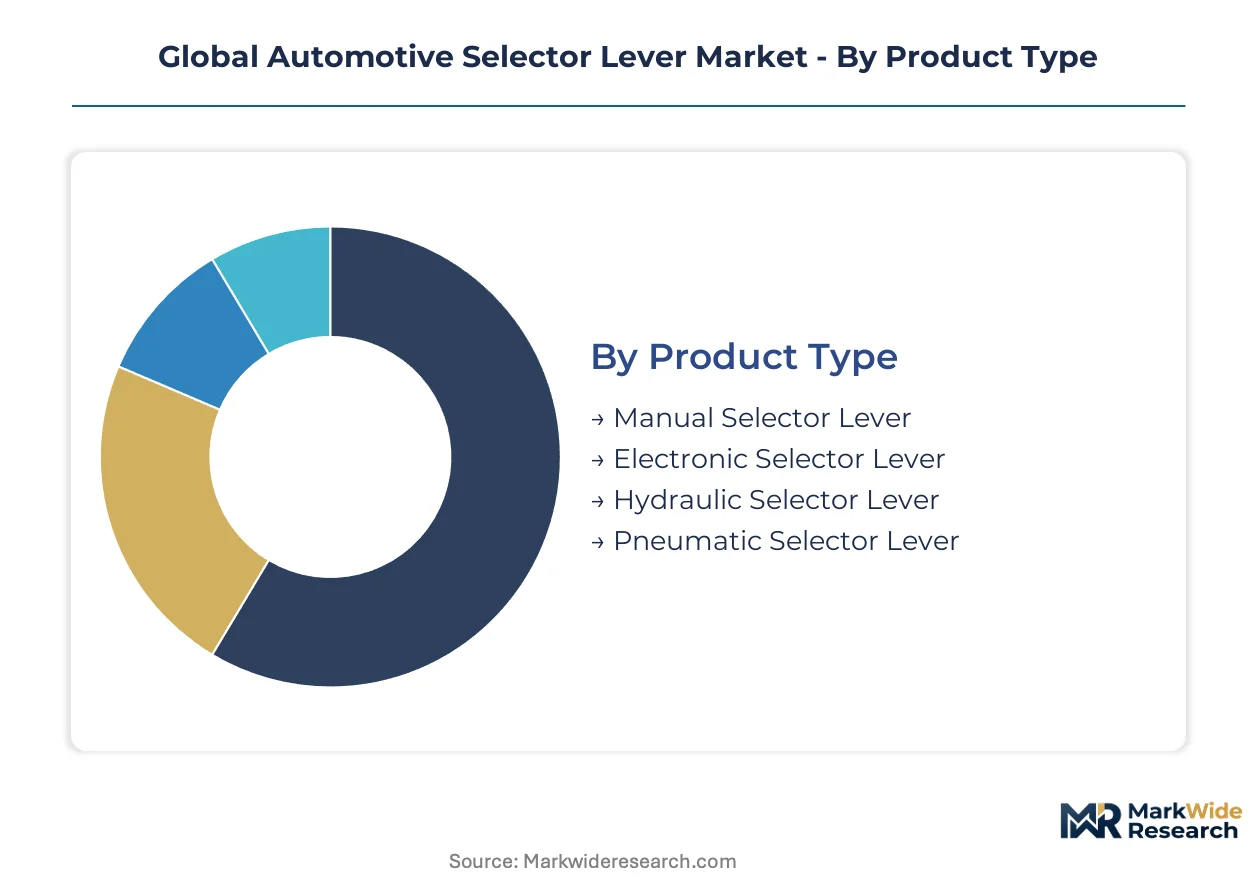
The global automotive selector lever market segments reflect distinct technological pathways and end-use requirements. Understanding these divisions allows suppliers to tailor product development and market strategies. Each segment presents unique challenges and opportunities for innovation and growth within the automotive industry.
Product Type:
The distribution of selector lever product types often correlates with vehicle production channels, distinguishing between traditional and modern manufacturing lines.
- Electronic Selector Lever:These systems operate via electronic signals, decoupling the driver's input from the transmission. Demand concentrates in battery electric vehicles (BEVs) and premium passenger cars, driven by shift-by-wire technology and minimalist cabin aesthetics.
- Manual Selector Lever:Traditional mechanical systems provide a direct physical linkage between the driver and the transmission. This segment still holds significant volume in economy passenger vehicles and some commercial applications, particularly in developing automotive markets.
- Hydraulic Selector Lever:These levers utilize hydraulic pressure to actuate gear changes, often found in heavy-duty commercial vehicles and specialized machinery. Their robustness suits demanding operational environments.
- Pneumatic Selector Lever:Pneumatic systems use compressed air for gear selection, commonly employed in large commercial trucks and buses where air brake systems are already integrated.
By volume, Manual Selector Lever leads. By growth pace, Electronic Selector Lever is ahead.
Technology:
The cost tier of a vehicle platform frequently dictates the type of selector lever technology employed, with premium models favoring advanced interfaces.
- Push Button:This technology employs individual buttons for gear selection, freeing up console space and supporting minimalist interior designs. New passenger vehicle designs, especially electric models, show a strong preference for this compact interface.
- Rotary Dial:A circular interface allows drivers to select gears by rotating a dial, offering an intuitive and space-efficient solution. Luxury and mid-range passenger vehicles are increasingly adopting rotary dials for their ergonomic and aesthetic appeal.
- Touch Sensitive:These interfaces integrate gear selection into touchscreens or haptic surfaces, providing a futuristic and highly customizable user experience. Advanced concept vehicles and high-end luxury models are exploring this technology.
- Lever Shift:Traditional lever-style shifters, whether mechanical or electronic, remain prevalent across a broad range of vehicle types. They offer a familiar tactile experience for many drivers.
- Paddle Shift:Steering wheel-mounted paddles allow for quick manual gear changes, primarily found in performance-oriented passenger vehicles and sports cars.
Supply concentration for Push Button and Rotary Dial technologies is strongest in vehicle production hubs in China and Germany.
Application:
Customer type, whether individual consumers or industrial operators, largely determines the functional requirements and durability standards for selector levers.
- Passenger Vehicles:This segment encompasses cars, SUVs, and light trucks, driving demand for sophisticated electronic levers and HMI integration. Growth in passenger vehicles is primarily fueled by consumer preference for advanced cabin electronics and shift-by-wire systems.
- Commercial Trucks:Heavy-duty and medium-duty trucks require robust, durable selector levers capable of enduring demanding operational cycles. The segment is gradually transitioning towards electronic solutions for improved efficiency and driver comfort.
- Construction Machinery:Excavators, loaders, and other heavy equipment utilize selector levers designed for extreme durability and precise control in harsh environments. Mechanical and hydraulic systems remain dominant here.
- Agricultural Equipment:Tractors and harvesting machinery employ selector levers built for ruggedness and ease of use, often integrating with complex hydraulic systems.
- Recreational Vehicles:RVs, motorhomes, and ATVs use selector levers optimized for specific driving experiences, balancing durability with user convenience.
The Passenger Vehicles segment benefits from strong consumer demand for aesthetic and technological upgrades, while Commercial Trucks are driven by efficiency and regulatory compliance.
End User:
The maturity of the supply chain dictates how selector levers reach their final assembly points, distinguishing between initial manufacturing and replacement markets.
- OEMs:Original Equipment Manufacturers integrate selector levers directly into new vehicle production lines. They demand highly customized, functionally safe, and fully integrated electronic solutions from their suppliers.
- Aftermarket Suppliers:These companies provide replacement parts and upgrade kits for vehicles already in service. A niche opportunity exists for electronic shifter conversion kits for older luxury vehicles.
- Vehicle Assemblers:These entities often perform final assembly of vehicles, receiving pre-manufactured selector lever modules from component suppliers. Their focus is on efficient integration and quality control.
- Replacement Parts Vendors:These vendors supply individual selector lever components or full assemblies for vehicle repair and maintenance. Durability and compatibility with existing vehicle architectures are key considerations for these suppliers.
OEMs represent the highest volume segment, while Aftermarket Suppliers and Replacement Parts Vendors offer distinct margin opportunities through specialized products and service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of electronic selector levers from manufacturing hubs in China to global automotive markets highlights regional specialization. Demand for these advanced components is concentrated in key automotive production nations, driven by technological adoption and stringent regulatory frameworks. Each region presents unique market dynamics for selector lever suppliers.
China
Domestic EV mandates and the rapid expansion of passenger vehicle production drive significant demand for electronic selector levers. Chinese regulators enforce GB standards for automotive safety, directly influencing component design and validation. The Yangtze River Delta region, including cities like Shanghai and Nanjing, serves as a major hub for EV manufacturing and electronic component supply chains.
Germany
The premium vehicle segment and a strong focus on luxury human-machine interface differentiation propel demand for sophisticated electronic shifters. Germany's KBA (Kraftfahrt-Bundesamt) actively enforces rules regarding gear selection indication and unintended vehicle movement. Bavaria, with its automotive R&D centers in Munich and manufacturing facilities in Stuttgart, remains a critical area for high-end automotive component innovation.
United States
Consumer preference for advanced cabin electronics and the electrification of SUVs and light trucks accelerate the adoption of shift-by-wire systems. The US NHTSA (National Highway Traffic Safety Administration) sets rigorous safety standards to prevent unintended vehicle movement. Michigan, particularly the Detroit metropolitan area, continues as a central hub for automotive engineering, design, and final assembly.
Japan
The widespread adoption of hybrid vehicles and a focus on compact electronic shifters contribute to market expansion. Japan's METI (Ministry of Economy, Trade and Industry) provides guidelines for automotive component reliability and quality. Aichi Prefecture, anchored by Nagoya, remains a cornerstone for both traditional and advanced automotive manufacturing capabilities.
India
An emerging middle-class demand for modern vehicles and government incentives for local manufacturing spur the integration of electronic components. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for automotive parts. Automotive clusters in Chennai and Pune are increasingly integrating advanced electronic selector levers into new vehicle platforms.
Global Automotive Selector Lever Market Key Industry Players
Player mix skews toward specialized automotive suppliers with deep expertise in mechatronics and software integration. The market exhibits a tiered structure, featuring global Tier 1 suppliers alongside regional specialists focusing on specific vehicle segments. Key strategic archetypes include integrated mechatronics providers, human-machine interface (HMI) focused innovators, and traditional mechanical system manufacturers adapting to new technologies. Competitive moves primarily involve strategic partnerships for software integration and portfolio diversification into advanced electronic systems.
Among the established global automotive component suppliers, ZF Friedrichshafen AG and Continental AG exemplify the push towards integrated electronic solutions. ZF Friedrichshafen AG leverages its expertise in transmission technologies to offer complete mechatronic solutions for sophisticated gear selection. Continental AG differentiates through its strong focus on human-machine interface design and advanced sensor integration, catering to evolving cabin aesthetics. BorgWarner Inc. occupies a position among suppliers offering a broad portfolio covering both traditional mechanical and modern electronic shift systems for diverse vehicle platforms.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Tokai Rika Co., Ltd |
| Continental AG |
| BorgWarner Inc. |
| Leopold Kostal GmbH & Co. KG |
| Kongsberg Automotive ASA |
| Magna International Inc. |
| Stoneridge Inc. |
| Lumax Industries Limited |
| Others |
Cost & Logistics Intelligence
Economies of scale in electronic component manufacturing drive both supply concentration and increasingly competitive price floors for automotive selector levers. This dynamic favors large-volume suppliers capable of amortizing high development costs across extensive production runs.
Pricing Analysis
The technology-generation pricing gap differentiates advanced electronic selector levers from traditional mechanical systems. Transactional pricing dominates, with price differentiation driven by certification level, customization requirements, and brand premium. Pricing pressure stems from the significant upfront investment in software development and validation. The passenger vehicle OEM segment exhibits high price sensitivity due to volume, while luxury vehicle manufacturers prioritize unique HMI design over cost.
Supply Chain Analysis
Inbound logistics costs, particularly for critical semiconductor components, influence the overall cost structure for electronic selector levers. Geographic supply concentration for these components centers on China, Germany, and Japan. The market depends heavily on microcontrollers and Hall-effect sensors. Single-source vulnerability for these specialized inputs represents a structural supply chain risk. Distribution runs directly from Tier 1 suppliers to Original Equipment Manufacturers for integration into new vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive selector lever market faces a capability gap in dual-expertise software and systems engineers, crucial for navigating functional safety requirements and complex HMI integration.
For Market Incumbents:Fortify core competencies in mechatronic integration and functional safety compliance to counter the threat of software-centric entrants. Invest in advanced HMI R&D to differentiate offerings in the premium vehicle segment. Strategic partnerships with specialized software firms can accelerate the development of fault-tolerant systems. Deepen relationships with key semiconductor suppliers to mitigate supply chain risks.
For New Entrants and Emerging Players:Certification fast-tracking for ISO 26262 compliance offers a pathway for market entry. Target the commercial vehicle segment with standardized, modular electronic shifter solutions, as this area remains underpenetrated by advanced systems. A go-to-market angle focused on robust, cost-effective electronic systems for heavy-duty trucks can establish a foothold. Niche opportunities also exist in aftermarket conversion kits for classic luxury vehicles.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among suppliers with embedded software and validation services, offering stable long-term cash flows. Acquisition targets should be specialized mechatronics or software firms possessing deep expertise in automotive functional safety. The long-term viability of this market is anchored by stringent safety regulations and continuous technological evolution. A signal to watch for inflection is the widespread OEM adoption of standardized electronic control unit architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Functional Safety Expertise | Ensures compliance with ISO 26262, critical for electronic shifter market access. |
| Develop Modular Electronic Shifter Platforms | Reduces OEM integration costs and accelerates adoption across diverse vehicle models. |
| Form Strategic Software Partnerships | Accesses specialized talent for complex HMI and control system development. |
| Expand Production Capacity in China | Aligns with global EV manufacturing hubs and local demand for electronic components. |
| Integrate Haptic Feedback Technologies | Differentiates premium selector levers through enhanced user experience and tactile quality. |
Research Approach
Desk research of industry reports, regulatory filings (NHTSA, KBA), and vehicle production databases preceded structured interviews with OEM platform engineers, Tier 1 component procurement, automotive software developers, and functional safety experts. This approach combined primary insights with secondary data for comprehensive market understanding, employing both bottom-up and top-down triangulation.
Variance decomposition informed the analytical framework across the analysis window, modeling market dynamics across product type, technology, application, end user, and regional EV mandates. Compound annual growth rates were derived from historical trends and projected technology adoption, with industry-specific forecast inputs including EV adoption rates and functional safety standard updates.
The analysis sits within stated boundaries; outcomes outside significant semiconductor supply disruptions or rapid shifts in regulatory frameworks would require recalibration. Forecasts reflect assumptions documented through this rigorous process. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automobile Accessories Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Subframe Market
Automotive Components
Global Automotive Gearbox Market