
 Dry Van Container Market | 2026-2036
Dry Van Container Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Van Container Market Analytics
Freight forwarders and third-party logistics providers are rotating toward larger container formats as supply chain consolidation favors intermediaries with multi-modal coordination capabilities. CIMC Group leverages its integrated steel supply and manufacturing scale to dominate standard container output. Singamas Container Holdings Limited anchors regional production through specialized facilities in China. CXIC Group Containers Company Limited competes on cost-engineered designs for emerging-market operators.
A dry van container is a fully enclosed, weatherproof steel box built to ISO 668 dimensional standards, typically constructed from Corten steel with plywood or bamboo flooring and corner castings for crane handling, designed to protect general cargo from moisture and theft during intermodal transit. The container type dimension shows high-cube variants capturing premium positioning as volumetric efficiency gains favor lightweight consumer goods and e-commerce parcels, while standard containers remain the volume baseline for commodity bulk shipments. By end user, shipping lines control the owned-fleet segment through long-dated asset programs, but logistics providers are expanding leased and chartered exposure to preserve balance-sheet flexibility against rate volatility.
China's SAMR enforces GB/T 1413 dimensional compliance and structural testing protocols, while the EU's F-Gas Regulation phases down hydrofluorocarbon refrigerants in temperature-controlled units, forcing reefer manufacturers toward CO2 or ammonia-based systems. The International Maritime Organization's container weight verification rule shapes loading practices and terminal access globally. Stakeholders must monitor how carbon-border adjustments and steel-origin traceability requirements reshape procurement geography and equipment residual values.
Market Dynamics
Steel price volatility and container fleet aging are compressing replacement cycles while port automation investments in India and Vietnam accelerate demand for ISO-certified high-cube formats.
Growth Catalysts
- India's PLI scheme for logistics infrastructure:Government production-linked incentives are subsidizing domestic container manufacturing capacity and accelerating port modernization timelines.
- E-commerce parcel density:Temperature-sensitive pharmaceuticals and oversized retail goods are pulling refrigerated and high-cube container procurement from third-party logistics networks.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in transport refrigeration units is forcing equipment upgrades across European temperature-controlled fleets.
Market Restraints
- Corten steel input costs:Raw material price swings compress manufacturing margins and destabilize long-dated procurement contracts for fleet operators.
- China supply concentration:Integrated steel supply and manufacturing scale in Chinese production clusters creates geographic dependency risk for global equipment sourcing.
- Corner casting fatigue limits:Structural testing protocols under GB/T 1413 reveal durability constraints in repeated crane-handling cycles.
Strategic Opportunities
- Vietnam port expansion:Underpenetrated container penetration relative to throughput growth creates white space for leasing operators.
- CO2 refrigeration convergence:Ammonia-based and transcritical CO2 systems intersect with IoT monitoring to enable predictive maintenance models.
- Carbon-border adjustment mechanisms:EU steel-origin traceability requirements favor regional manufacturing investments with verified emission profiles.
Industry Challenges
- Welding certification bottlenecks:ISO 668 structural compliance testing faces inspector capacity constraints and extended approval timelines.
- Fleet management system integration:Legacy telematics platforms resist interoperability with new container-mounted sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Van Container Market |
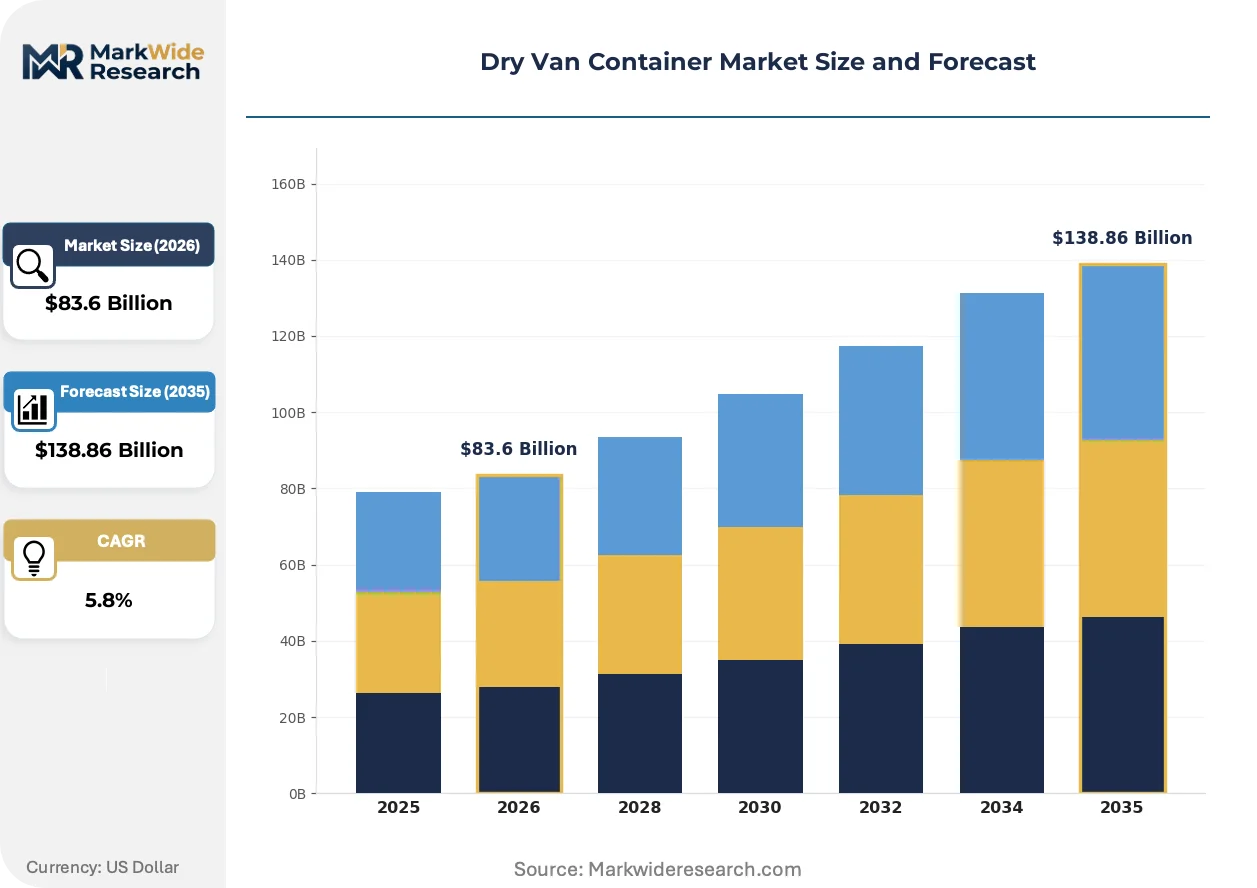
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $138.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Standard Container, High Cube Container, Refrigerated Container, Open Top Container End User: Shipping Lines, Freight Forwarders, Logistics Providers, Warehouse Operators Size: 20 Feet, 40 Feet, 45 Feet, 48 Feet Deployment Mode: Owned, Leased, Charter, Rental |
| Companies Covered | CIMC Group, Singamas Container Holdings Limited, CXIC Group Containers Company Limited, A.P. Moller Maersk A/S, Hapag-Lloyd AG, China Shipping Container Lines Co., Ltd., Charleston Marine Containers, Inc., Sea Box Inc., Alconet Containers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Van Container Market Evolving Landscape
Equipment intelligence and emission-compliant refrigeration are restructuring competitive advantage away from pure manufacturing scale toward integrated service capabilities.
Bamboo-composite flooring is displacing traditional plywood substrates in high-cube variants. E-commerce fulfillment networks are specifying these lighter panels to maximize volumetric payload. The material shift is displacing established Southeast Asian plywood suppliers from premium container specifications.
China's SAMR enforcement of GB/T 1413 dimensional compliance is tightening structural testing protocols. Manufacturers must certify corner casting fatigue resistance under repeated crane-handling cycles. High-cube container lines serving European routes are absorbing the heaviest compliance cost burdens.
Long-term leasing contracts are fragmenting fleet ownership structures. Shipping lines are shedding owned assets to preserve balance-sheet flexibility against freight rate volatility. This pattern concentrates most visibly among logistics providers operating India-Europe corridors.
Dry Van Container Market Segmentation
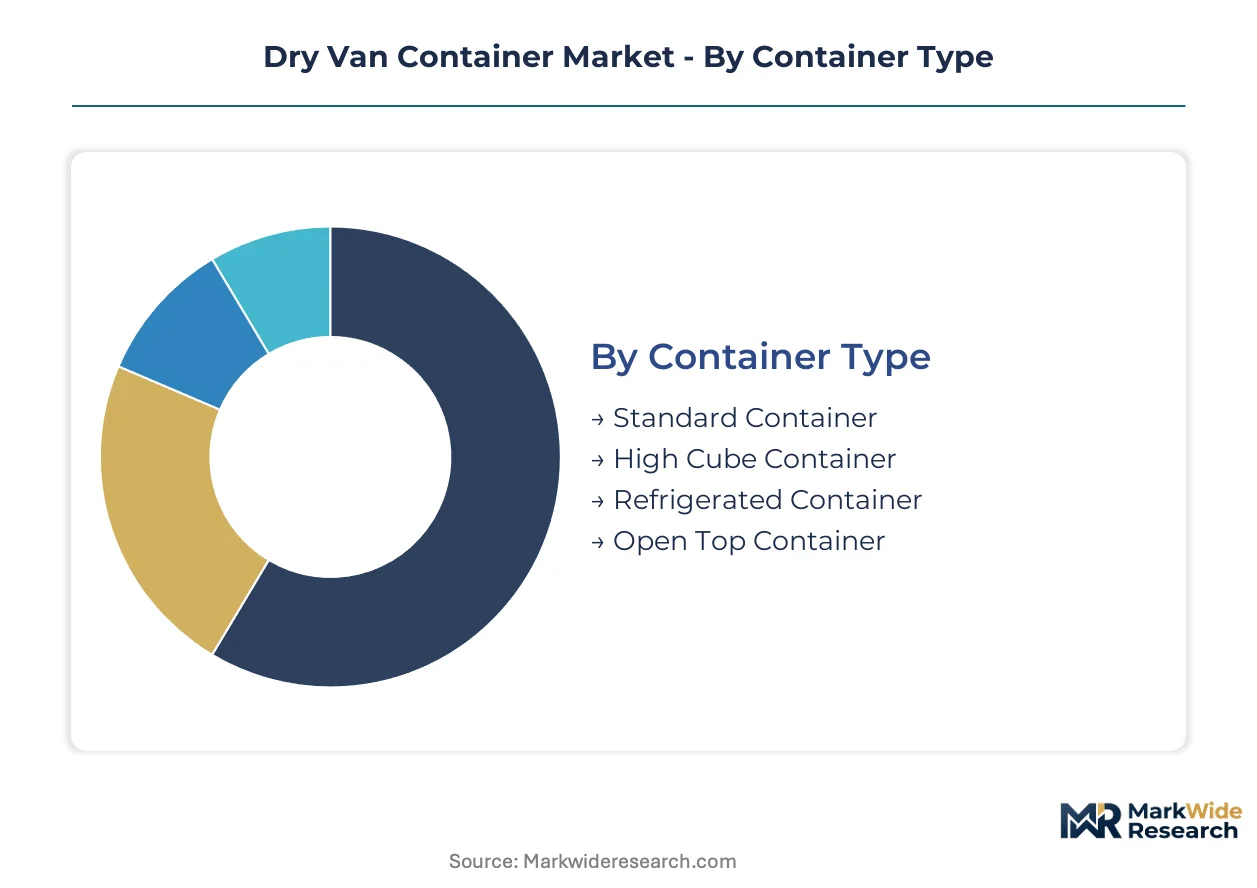
Container specification choices determine compliance burdens, residual values, and modal flexibility across intermodal networks. Equipment buyers segment procurement by dimensional standards, thermal requirements, and ownership structures to balance capital efficiency against operational control.
Container Type:
GB/T 1413 structural testing protocols and EU F-Gas refrigerant phase-downs create divergent compliance cost profiles across container formats. SAMR enforcement in China and ECHA refrigerant rules in Europe force manufacturers to maintain parallel certification tracks.
- Standard Container:Corten steel construction with plywood or bamboo flooring and ISO 668 corner castings for crane handling. Shipping lines in India deploy these for commodity bulk shipments under PLI-subsidized fleet replacement programs, though corner casting fatigue limits under repeated handling cycles constrain durability expectations.
- High Cube Container:Extended 9'6" height profile with bamboo-composite flooring displacing traditional plywood substrates. E-commerce fulfillment networks in Vietnam and India specify these lighter panels to maximize volumetric payload density for consumer goods and parcel freight.
- Refrigerated Container:Temperature-controlled units facing EU F-Gas Regulation compliance costs.
- Open Top Container:Specialized format for oversized cargo with tarpaulin roof systems.
Standard containers handle the majority of throughput; high-cube variants are gaining share fastest on e-commerce parcel density requirements.
End User:
Balance-sheet strategy separates owned-fleet operators from asset-light intermediaries seeking flexibility against freight rate volatility.
- Shipping Lines:Long-dated asset programs with integrated steel supply chains dominate owned-fleet procurement. These operators absorb GB/T 1413 certification costs directly but face margin compression from Corten steel price swings.
- Freight Forwarders:Multi-modal coordination capabilities favor larger container formats as supply chain consolidation progresses. Forwarders on India-Europe corridors are expanding leased exposure to preserve liquidity.
- Logistics Providers:Third-party networks accelerating refrigerated and high-cube procurement.
- Warehouse Operators:Terminal and storage facility managers with container handling requirements.
Shipping lines retain volume leadership in owned assets; logistics providers are expanding most quickly through leased and chartered structures.
Size:
Dimensional choice reflects port infrastructure constraints and vessel slot optimization across trade lanes.
- 20 Feet:Compact format for dense cargo and last-mile distribution.
- 40 Feet:The baseline intermodal unit with maximum vessel slot efficiency. Port automation investments in India and Vietnam accelerate ISO-certified procurement of this format for high-throughput terminals.
- 45 Feet:Extended length for domestic North American and European road-rail intermodal.
- 48 Feet:Regional specialty format with limited international standardization.
40-foot units dominate ocean freight deployment; 45-foot formats show steepest expansion trajectory on regional intermodal corridors.
Deployment Mode:
Capital structure preferences reshape fleet ownership concentration and equipment residual risk allocation.
- Owned:Direct asset ownership with full residual value exposure. Shipping lines are shedding owned units to preserve balance-sheet flexibility, concentrating this mode among operators with captive cargo bases.
- Leased:Operating lease structures transfer residual risk to lessors. Logistics providers favor this mode for India-Europe corridor exposure against rate volatility.
- Charter:Short-term vessel-slot arrangements with equipment included.
- Rental:Spot-market access for surge capacity and project cargo.
Owned fleets retain structural volume; leased deployment is climbing the fastest as shipping lines prioritize liquidity over asset control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors India's accelerating container throughput, while Shanghai's Yangshan Deep Water Port underwrites China's manufacturing export dominance. Vietnam's Cai Mep-Thi Vai complex and Germany's Hamburg-Bremen corridor complete the critical infrastructure nodes reshaping procurement geography.
India
Port automation investments at Jawaharlal Nehru Port Trust and Mundra Port are accelerating ISO-certified high-cube container procurement. The PLI scheme for logistics infrastructure subsidizes domestic manufacturing capacity and compresses fleet replacement cycles. Manufacturing clusters in Gujarat and Maharashtra are absorbing GB/T 1413 certification costs to serve India-Europe corridor demand.
China
Integrated steel supply chains and manufacturing scale dominate standard container output from the Yangtze River Delta. SAMR enforcement of GB/T 1413 dimensional compliance tightens structural testing protocols for corner casting fatigue resistance. Production gravity in Jiangsu and Guangdong provinces faces carbon-border adjustment pressure from EU steel-origin traceability requirements.
Vietnam
Cai Mep-Thi Vai deep-water terminals are expanding refrigerated and high-cube container penetration relative to throughput growth. Underpenetrated leasing markets create white space for operators seeking balance-sheet flexibility. Ho Chi Minh City logistics zones are absorbing bamboo-composite flooring specifications from e-commerce fulfillment networks.
Germany
The Hamburg-Bremen port complex handles temperature-sensitive pharmaceutical flows requiring EU F-Gas Regulation compliance for transport refrigeration units. ECHA refrigerant rules force equipment upgrades toward CO2 or ammonia-based systems. Industrial clusters in Lower Saxony are absorbing compliance cost burdens for reefer manufacturers serving European temperature-controlled fleets.
United States
The Ports of Los Angeles and Long Beach intermodal rail links drive 40-foot container deployment for consumer goods distribution. Logistics providers are expanding leased exposure to preserve liquidity against freight rate volatility. Gulf Coast manufacturing zones in Texas are developing regional container assembly capacity to reduce China supply concentration risk.
Dry Van Container Market Competitive Landscape
Concentration sits with integrated steel-to-container manufacturers and shipping lines with captive asset programs. Tiered competitive structure separates scale-driven fabricators from specialized reefer engineers and regional leasing operators. Dominant competitive moves include capacity expansion in India and Vietnam, plus portfolio diversification into IoT-enabled fleet management systems.
Among Chinese integrated manufacturers, CIMC Group and CXIC Group Containers Company Limited exemplify the scale-driven archetype with captive steel supply chains. Singamas Container Holdings Limited occupies a specialist position within regional production networks. Container lines with owned-fleet heritage, including A.P. Moller Maersk A/S and Hapag-Lloyd AG, represent the asset-heavy competitive vector shedding direct ownership for leased structures.
| Leading Market Players |
|---|
| CIMC Group |
| Singamas Container Holdings Limited |
| CXIC Group Containers Company Limited |
| A.P. Moller Maersk A/S |
| Hapag-Lloyd AG |
| China Shipping Container Lines Co., Ltd. |
| Charleston Marine Containers, Inc. |
| Sea Box Inc. |
| Alconet Containers |
| Others |
Value Network & Pricing Analysis
Ninety-day Corten steel inventory cycles at Jiangsu manufacturing clusters concentrate pricing power among integrated producers while compressing margins for non-captive fabricators. This lead-time exposure binds container pricing to steel futures volatility and SAMR certification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified high-cube units with bamboo-composite flooring from basic standard containers and spot-market refurbished equipment. Price differentiation hinges on GB/T 1413 compliance grade and volume scale, with logistics providers commanding steepest discounts above five-hundred-unit annual procurement. Cost compression in standard containers is intensifying because shipping lines shed owned-fleet exposure. Freight forwarders exhibit highest price sensitivity; integrated manufacturers with captive steel supply show least.
Supply Chain Analysis
Malacca Strait transit underwrites ninety percent of Asia-Europe container equipment flows, creating chokepoint vulnerability for Indian and Vietnamese port expansions. Manufacturing gravity centers on China, India, and Vietnam, with production drawing from Malaysian plywood, Australian bamboo fiber, and domestic Corten steel. Single-source vulnerability concentrates in Chinese corner casting suppliers facing GB/T 1413 fatigue-testing bottlenecks. Distribution runs through leasing operators and shipping line procurement desks with long-dated asset programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container fleet intelligence platforms are redefining competitive advantage through IoT sensor interoperability, signaling a platform-economics inflection where data-layer integration supersedes pure manufacturing scale.
For Market Incumbents: Consolidate captive steel supply positions in Gujarat and Maharashtra to offset Corten price volatility from Chinese import dependency. Deepen backward integration into bamboo-composite substrate production to defend margin position against Southeast Asian plywood displacement. Prioritize GB/T 1413 certification investment ahead of SAMR enforcement tightening. For New Entrants and Emerging Players: Reefer fleet retrofit services for EU F-Gas Regulation compliance represent the most penetrable white-space, as incumbent manufacturers under-serve ammonia-based and transcritical CO2 conversion demand. Target Vietnam's Cai Mep-Thi Vai corridor with leased high-cube deployment for e-commerce fulfillment networks. Pursue IoT-enabled predictive maintenance partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from shipping lines divesting owned-fleet assets to preserve balance-sheet flexibility. Long-term viability favors lessors with India-Europe corridor exposure and verified carbon-origin documentation for EU border adjustment readiness. Watch leasing-rate spreads against freight futures as the inflection signal for equipment residual value compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo-Composite Substrates | Displaces Malaysian plywood suppliers from premium high-cube specifications while reducing unit weight. |
| GB/T 1413 Certification Pre-Positioning | Accelerates SAMR approval timelines ahead of structural testing protocol tightening. |
| CO2 Refrigeration Fleet Retrofit Services | Captures EU F-Gas Regulation compliance spending from temperature-controlled logistics providers. |
| India Manufacturing Footprint Expansion | Accesses PLI scheme subsidies while reducing China supply concentration risk. |
| IoT Fleet Management Platform Integration | Enables predictive maintenance revenue streams from sensor-mounted container networks. |
Research Methodology
A spread of perspectives from fleet procurement managers, port terminal operators, leasing contract specialists, and steel supply traders converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SAMR certification registries, and shipping line SEC disclosures. Bottom-up equipment deployment counts triangulated against top-down steel consumption models.
Segmentation dimensions modeled include container type, end-user ownership structure, dimensional format, and deployment mode across the projection horizon. CAGRs derived from equipment replacement cycle analysis, port throughput elasticity, and e-commerce parcel density coefficients. Forecast inputs incorporated PLI scheme subsidy trajectories and EU carbon-border adjustment mechanism implementation pacing.
Forecasts assume regulatory continuity in China's SAMR enforcement and EU F-Gas refrigerant phase-downs; material policy shifts would require re-modeling. Steel price volatility, corner casting certification bottlenecks, and freight rate cyclicality constitute primary revision risks. Practitioners should keep alternative scenarios live as India port automation timelines and Vietnam leasing market penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Last-Mile Delivery Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Digital Logistics Market