
 Automotive Battery Terminals Market | 2026-2036
Automotive Battery Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Terminals Market Insights
China's Jiangsu and Zhejiang provinces is rewriting cost structures for stamped copper terminals as domestic toolmakers automate progressive die lines. East Penn Manufacturing anchors North American supply through captive lead-casting and vertical distribution into aftermarket channels. MTA SpA specializes in compact form-factor terminals for European OEM wire-harness integration, while Schumacher Electric competes in the replacement segment through retail tool-and-terminal bundling.
Automotive battery terminals are electromechanical interface components, typically fabricated from lead alloys, copper, or aluminum with tin or zinc plating, that secure the electrical connection between a battery cell and external circuitry; they must sustain current densities exceeding 300 A/cm² in EV architectures while resisting galvanic corrosion from acid vapor exposure. Post terminals retain dominance in passenger vehicle engine bays due to legacy tool compatibility and established repair protocols, whereas clamp terminals capture expanding share in commercial fleet maintenance where rapid swap-out reduces downtime. Copper material grades command premium positioning as OEMs specify oxygen-free conductivity for 800-volt architectures, while lead formulations face structural decline under environmental substitution mandates.
The EPA governs lead content thresholds in US-manufactured terminals through TSCA Title VI provisions, while REACH and RoHS in Europe restrict cadmium and hexavalent chromium in plating chemistries, effectively filtering non-compliant Asian exporters from tender pools. China's SAMR enforces GB/T 5008 standards for dimensional tolerance and pull-out strength, creating a three-regime compliance landscape that elevates testing costs for multi-market suppliers. Stakeholders must monitor copper price volatility and evolving IEC 61482 arc-flash specifications as terminal geometry becomes inseparable from battery pack thermal management design.
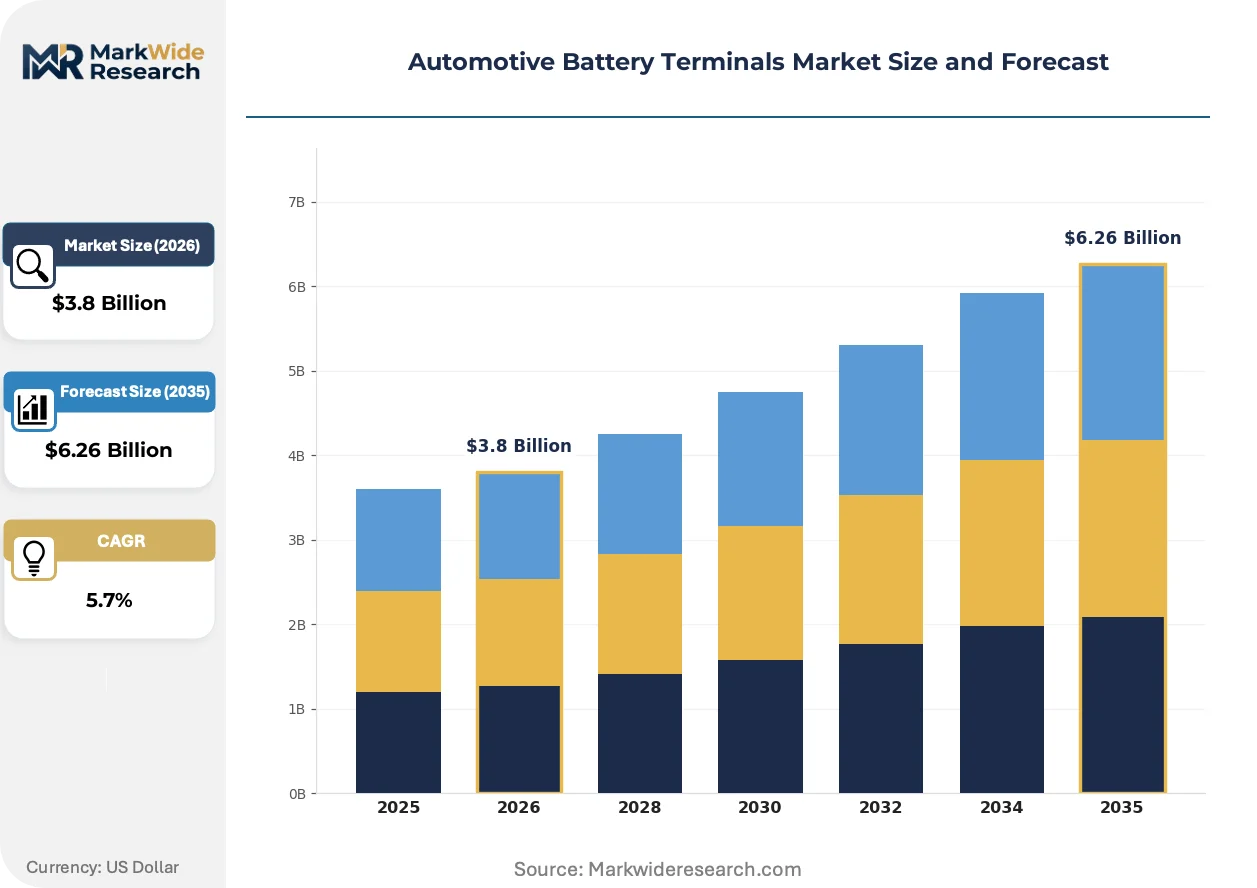
Market Dynamics
Copper terminal specifications for 800-volt EV architectures are compressing design cycles and forcing material upgrades across supplier bases, while REACH and GB/T compliance costs filter marginal producers from tender participation.
Growth Catalysts
- Lead-free mandates:ECHA REACH restrictions and China's GB standards are accelerating substitution toward tin-plated copper terminals in passenger vehicle applications.
- EV platform voltage escalation:800-volt battery systems demand oxygen-free copper grades that sustain current densities above 300 A/cm², pulling premium material procurement.
- Stuttgart-Wolfsburg corridor concentration:Germany's automotive supplier cluster is consolidating specification-setting power for European OEM wire-harness integration.
Market Restraints
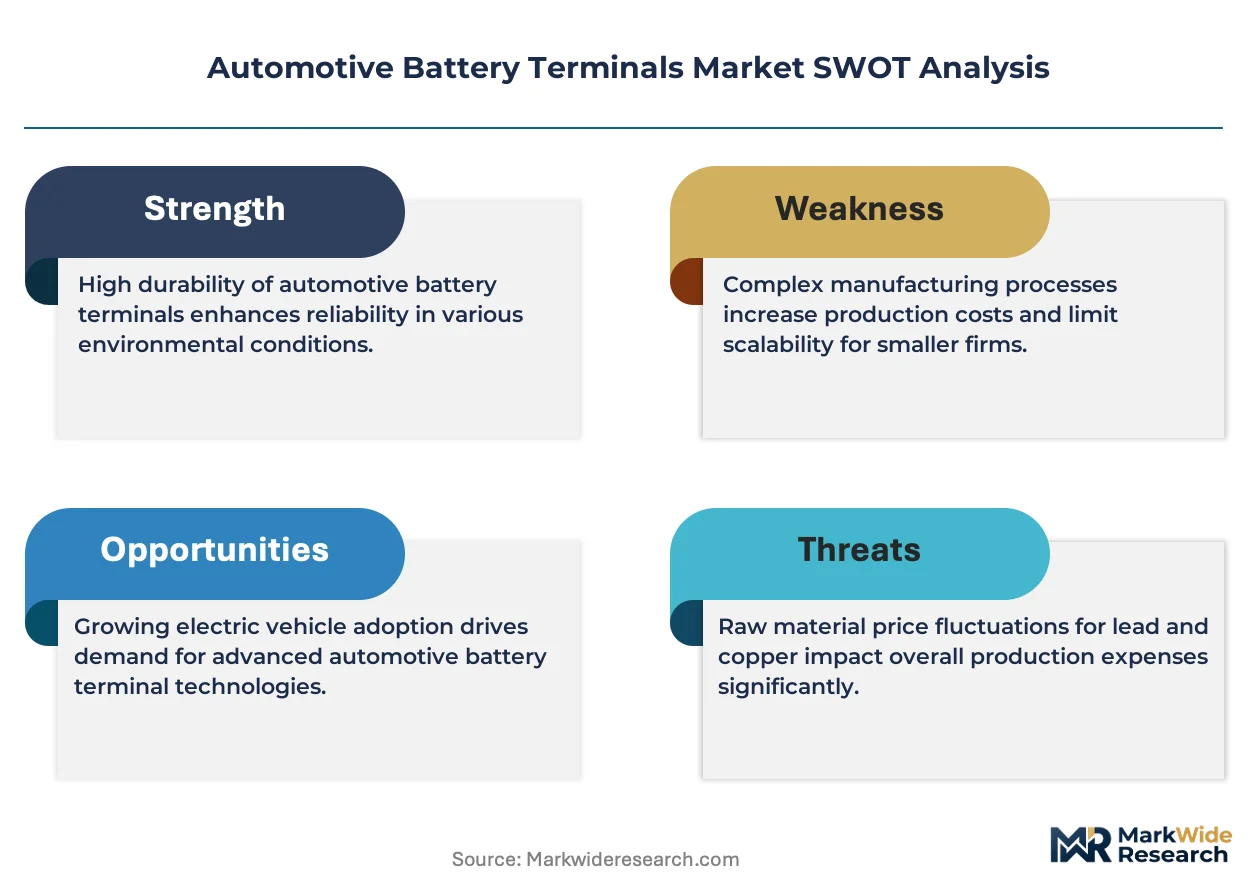
- Copper price volatility:LME copper fluctuations compress margin visibility for stamped terminal producers dependent on spot metal purchasing.
- Progressive die automation concentration:Jiangsu and Zhejiang provinces dominate cost-efficient tooling, creating geographic supply risk for non-integrated buyers.
- Lead alloy phase-out friction:Legacy repair protocols and tool compatibility requirements slow post-terminal displacement in aftermarket channels.
Strategic Opportunities
- Commercial fleet rapid-swap protocols:Clamp terminal formats capture share where downtime reduction outweighs legacy compatibility constraints.
- IEC 61482 arc-flash alignment:Terminal geometry optimization for battery pack thermal management creates specification wedge against commodity suppliers.
- Retail tool-terminal bundling:North American aftermarket channels favor integrated solutions that simplify consumer replacement workflows.
Industry Challenges
- Multi-regime testing burden:TSCA Title VI, REACH, and SAMR GB/T compliance requires parallel certification tracks that extend product launch timelines.
- Galvanic corrosion mitigation:Acid vapor exposure in engine bay environments demands plating chemistry expertise that constrains supplier qualification pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Terminals Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Post Terminals, Bolt Terminals, Clamp Terminals, Stud Terminals Material: Copper, Lead, Aluminum, Zinc Application: Passenger Vehicles, Electric Vehicles, Commercial Vehicles, Heavy Machinery Form Factor: Standard, Custom, Compact, Heavy-Duty |
| Companies Covered | Schumacher Electric, Duralast, General Motors (ACDelco), East Penn Manufacturing, Advance Auto Parts (DieHard), Windy Nation, MTA SpA, Voltage Batteries, Phillips Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Terminals Market Trends and Innovations
Terminal manufacturing is digitizing through sensor-embedded interfaces that enable predictive maintenance, while regulatory chemistry restrictions and procurement consolidation reshape competitive access.
Smart terminal designs incorporating temperature and current sensors are digitizing the electromechanical interface into a data node. EV OEMs specify these for thermal runaway early warning systems. This capability is digitizing supplier selection criteria toward electronics integration competence.
ECHA REACH Annex XVII restrictions on cadmium and hexavalent chromium are forcing plating chemistry transitions across European supply chains. Surface treatment vendors must qualify zinc-nickel and tin-zinc alternatives. Passenger vehicle OEMs are consolidating approved plating specifications to reduce qualification overhead.
Fleet operators are compressing supplier relationships toward single-source terminal specifications that simplify maintenance training and inventory. Commercial vehicle channels favor clamp formats that enable tool-free swap-out. This consolidation is most visible in North American logistics fleet procurement where uptime guarantees dominate total cost calculations.
Automotive Battery Terminals Market Segmentation
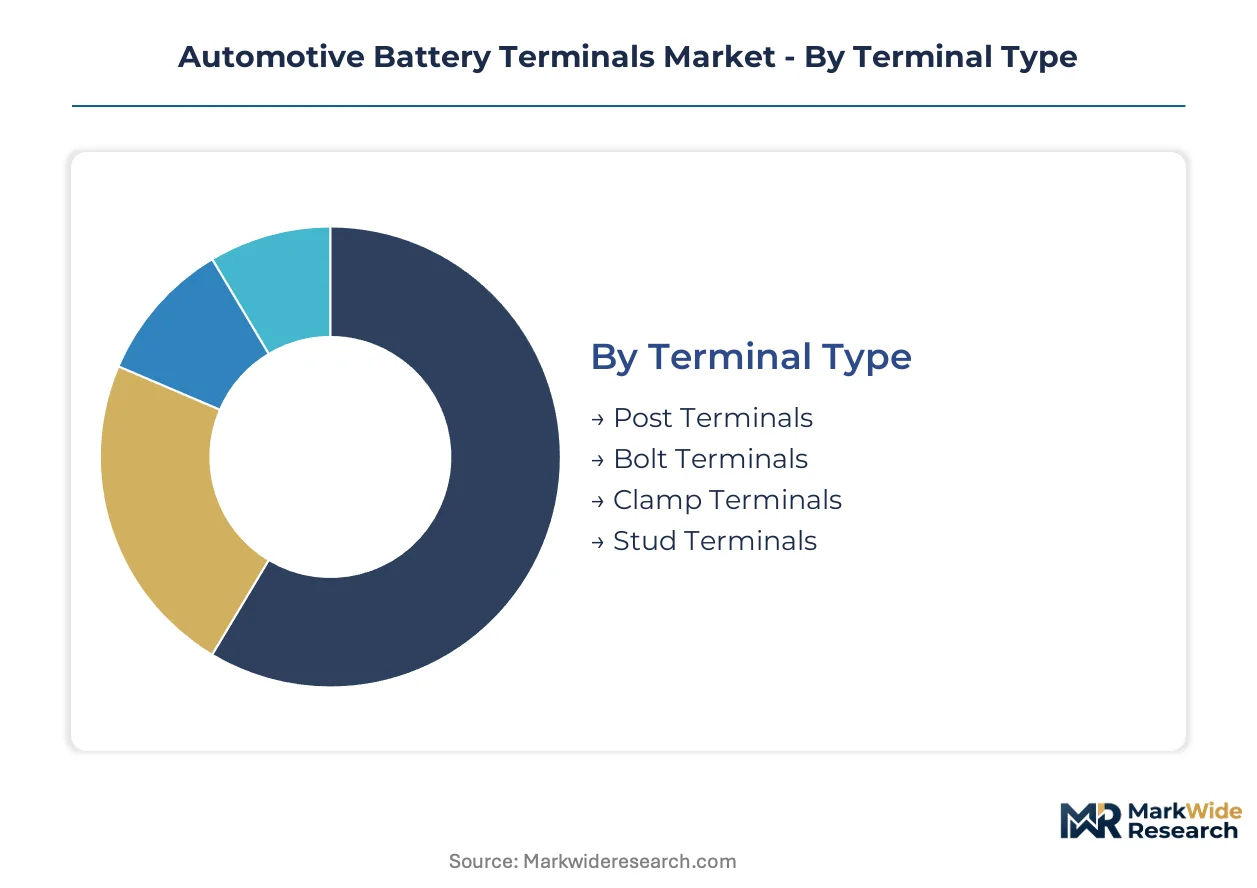
Terminal specification diversity reflects divergent electromechanical demands across voltage architectures and regulatory jurisdictions. Segmentation reveals how material selection and form factor decisions cascade through compliance costs, thermal performance, and aftermarket tooling ecosystems.
Terminal Type:
Post terminals anchor legacy passenger vehicle engine bays through decades of repair protocol entrenchment, while clamp and stud formats capture specialized high-current and rapid-swap applications.
- Post Terminals:These cylindrical lead-alloy or copper-tin interfaces dominate OEM installations in conventional internal combustion architectures. Demand concentrates in Germany's Stuttgart-Wolfsburg supplier corridor where legacy tool compatibility preserves specification inertia despite EV voltage escalation.
- Clamp Terminals:Quick-release mechanical designs enable tool-free battery swap-out for commercial fleet operators. North American logistics procurement favors these formats where downtime reduction overrides initial hardware cost premiums.
- Bolt Terminals:Threaded stud-and-nut configurations secure high-vibration environments in heavy machinery applications. Mining and construction OEMs specify these for pull-out strength under GB/T 5008 testing protocols.
- Stud Terminals:Compact vertical posts optimize space-constrained battery tray layouts in hybrid architectures. Japanese METI efficiency standards drive adoption in kei-car and compact vehicle segments.
The dominant share belongs to Post Terminals, while Clamp Terminals is closing the gap fastest.
Material:
Conductivity requirements and environmental mandates are bifurcating procurement between premium oxygen-free copper and phased lead formulations.
- Copper:Oxygen-free high-conductivity grades sustain current densities above 300 A/cm² in 800-volt EV architectures. Jiangsu and Zhejiang provinces dominate stamped copper terminal production through automated progressive die lines.
- Lead:Traditional lead-antimony and lead-calcium alloys face structural decline under ECHA REACH restrictions and China's GB standards. Aftermarket channels in legacy vehicle fleets sustain residual demand despite environmental substitution pressure.
- Aluminum:Lightweight alternatives emerge in mass-sensitive applications where conductivity trade-offs accept 40% higher resistivity. European OEMs evaluate aluminum for PHEV auxiliary battery connections.
- Zinc:Primarily deployed as protective plating layer rather than bulk terminal material. Tin-zinc surface treatments substitute cadmium and hexavalent chromium under RoHS-compliant specifications.
Copper commands the volume lead, though aluminum is expanding most quickly as OEMs chase mass reduction targets.
Application:
Voltage architecture divergence between propulsion systems creates distinct terminal specification clusters with minimal component commonality.
- Passenger Vehicles:Conventional 12V architectures retain post-terminal dominance with tin-plated copper upgrades replacing legacy lead. EPA TSCA Title VI compliance filters non-compliant suppliers from US tender participation.
- Electric Vehicles:800-volt traction battery packs demand oxygen-free copper terminals with integrated temperature sensing for thermal runaway monitoring. IEC 61482 arc-flash specifications govern geometry optimization.
- Commercial Vehicles:Fleet uptime requirements favor clamp-terminal rapid-swap protocols over legacy compatibility. Single-source consolidation simplifies maintenance training across North American logistics networks.
- Heavy Machinery:Vibration resistance and corrosion protection prioritize bolt-terminal mechanical security. Mining applications specify heavy-duty zinc-nickel plating for acid vapor exposure.
Passenger Vehicles retains the largest installed base, yet Electric Vehicles shows the steepest expansion trajectory.
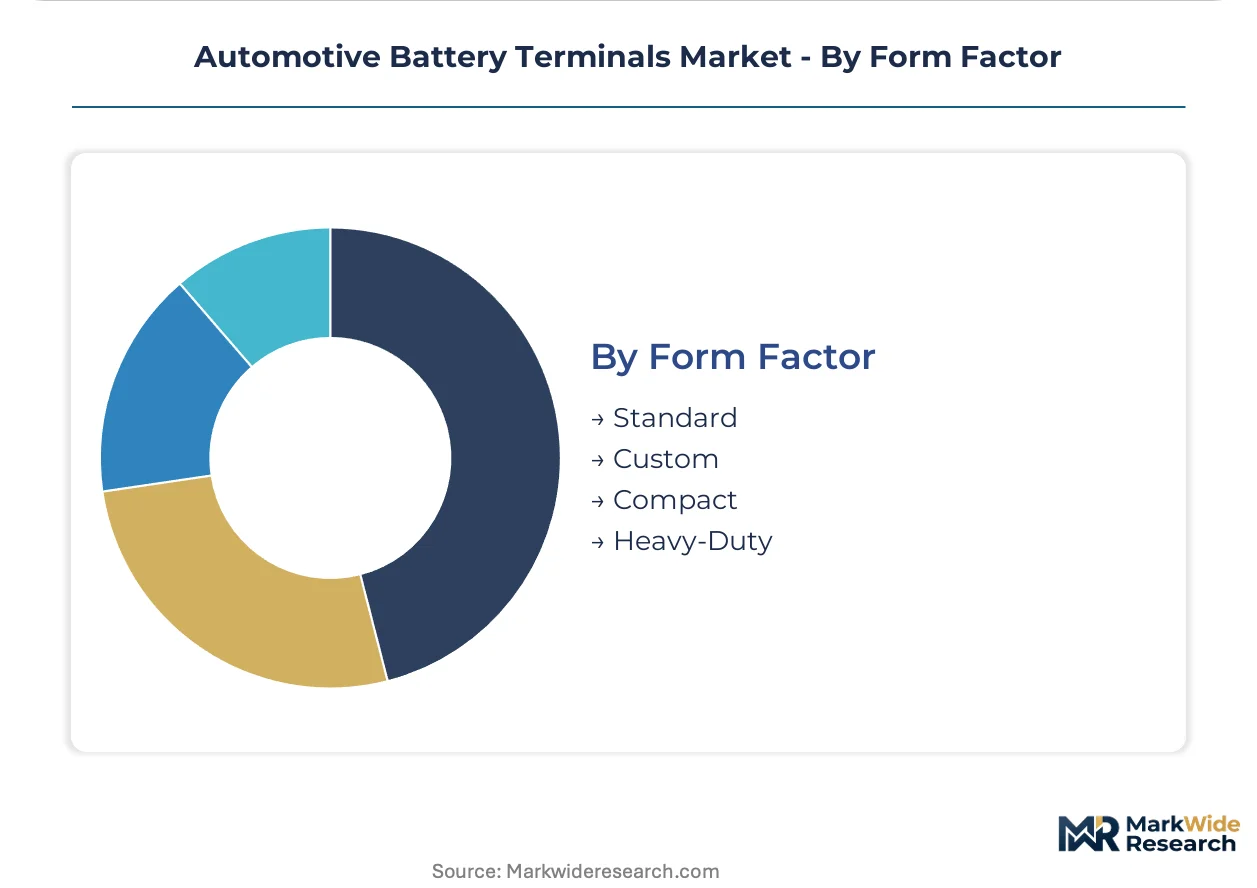
Form Factor:
Packaging constraints and thermal management integration drive differentiation between commodity standard formats and engineered compact solutions.
- Standard:Legacy dimensional specifications ensure aftermarket interchangeability across vehicle generations. Tooling amortization across high volumes sustains margin visibility despite copper price volatility.
- Compact:Space-optimized designs from MTA SpA integrate into European OEM wire-harness architectures with minimal packaging overhead. Miniaturization demands precision stamping expertise that constrains supplier pools.
- Custom:Application-specific geometries align with battery pack thermal management system integration. Bespoke development cycles extend qualification timelines for multi-regime compliance.
- Heavy-Duty:Reinforced cross-sections and enhanced plating thickness serve commercial and industrial current loads. Pull-out strength requirements under SAMR GB/T standards exceed passenger vehicle specifications.
Standard form factors hold the dominant position, while Compact designs are gaining share fastest through OEM wire-harness integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary European gateway for copper terminal imports, while China's Ningbo-Zhoushan port anchors Asia-Pacific material flows for stamped component exports.
United States
EPA TSCA Title VI provisions govern lead content thresholds in domestic terminal manufacturing, filtering non-compliant Asian exporters from federal procurement pools. The Midwest automotive supplier corridor around Detroit and Chicago concentrates stamping capacity for OEM wire-harness integration. East Penn Manufacturing maintains captive lead-casting operations with vertical distribution into aftermarket channels across the region.
Germany
ECHA REACH Annex XVII restrictions on cadmium and hexavalent chromium force plating chemistry transitions across European supply chains. The Stuttgart-Wolfsburg automotive supplier corridor consolidates specification-setting power for OEM wire-harness integration. MTA SpA specializes in compact form-factor terminals designed for European vehicle architectures with minimal packaging overhead.
China
SAMR enforces GB/T 5008 standards for dimensional tolerance and pull-out strength, creating compliance barriers for multi-market suppliers. Jiangsu and Zhejiang provinces dominate cost-efficient progressive die automation for stamped copper terminals. Domestic toolmakers are rewriting cost structures through automated production lines that serve both local EV manufacturers and export markets.
Japan
METI efficiency standards drive adoption of compact stud-terminal designs in kei-car and compact vehicle segments. JIS certification requirements filter supplier participation in domestic OEM tender processes. The Nagoya-Toyota industrial corridor concentrates precision stamping expertise for hybrid architecture battery connections.
India
BIS certification mandates for automotive electrical components extend product launch timelines for imported terminal specifications. The Pune-Chennai automotive belt is emerging as a secondary stamping location for copper terminals serving domestic EV programs. Domestic fleet operators are evaluating clamp-terminal rapid-swap protocols for commercial logistics applications.
Automotive Battery Terminals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper process expertise. The supplier base fragments across three functional layers: captive manufacturers serving single OEM programs, independent stampers competing on tooling amortization, and aftermarket distributors bundling tools with replacement hardware. Two strategic archetypes dominate: vertically integrated metalformers controlling material through distribution, and design-focused specialists capturing specification influence through compact form-factor innovation. Competitive moves concentrate on geographic expansion into regulatory-adjacent markets and portfolio diversification toward sensor-integrated smart terminals.
Among North American aftermarket distributors, Schumacher Electric and DieHard exemplify the retail bundling archetype, while East Penn Manufacturing represents vertically integrated production with captive material supply. MTA SpA anchors the European design-specialist tier, occupying a position defined by wire-harness integration competence rather than commodity volume.
| Leading Market Players |
|---|
| Schumacher Electric |
| Duralast |
| General Motors (ACDelco) |
| East Penn Manufacturing |
| Advance Auto Parts (DieHard) |
| Windy Nation |
| MTA SpA |
| Voltage Batteries |
| Phillips Industries |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Zhejiang provinces anchor global stamped copper terminal capacity, with automated progressive die lines compressing unit economics and transmitting cost advantages downstream to buyers negotiating annual contracts. This concentration amplifies pricing power for integrated producers while forcing spot-market purchasers into margin volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with oxygen-free copper grades commanding spreads over lead-antimony alternatives based on IEC 61482 certification status and 800-volt architecture compatibility. OEM direct contracts favor volume-scaled annual pricing, whereas aftermarket channels absorb spot copper volatility through tool-terminal bundling. Cost compression in economy tiers is intensifying because Jiangsu toolmakers automate die lines faster than European competitors can amortize legacy equipment. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while EV platform engineers prioritize conductivity performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for multi-market terminal suppliers seeking to avoid Section 301 duty impacts on stamped copper components. Raw material flows draw from Chilean copper concentrate, Zambian cathode, and domestic Chinese smelter output, with oxygen-free grades requiring additional refining steps that tether production to specialized metallurgical capacity. Single-source vulnerability concentrates in progressive die tooling, where Jiangsu and Zhejiang provinces control cost-efficient automation that non-integrated buyers cannot replicate. Distribution runs through Hamburg for European OEM integration, Ningbo-Zhoushan for Asia-Pacific export consolidation, and Detroit-Chicago corridor aftermarket warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across voltage architectures and regulatory jurisdictions creates niche entry points for specialists who can navigate multi-regime compliance faster than consolidated incumbents. The divergence between 12V legacy protocols and 800-volt EV specifications splits procurement committees, opening specification influence channels.
For Market Incumbents: Build captive metallurgical capacity as a moat against copper price volatility and Jiangsu cost pressure. East Penn Manufacturing demonstrates this through in-house lead-casting and vertical distribution control. Defensive moves require SAMR GB/T pre-certification for Chinese market access and sensor-embedded smart terminal R&D to capture EV thermal management integration. Threats include aluminum substitution in PHEV auxiliary connections and clamp-format displacement of post-terminal legacy protocols. For New Entrants and Emerging Players: Build out compact form-factor stamping competence to serve European OEM wire-harness integration mandates where MTA SpA currently dominates specification-setting. The most penetrable white space sits in North American commercial fleet clamp-terminal rapid-swap protocols, where downtime reduction premiums override legacy compatibility requirements. A go-to-market angle combining tool-free installation training with single-source fleet contracts bypasses entrenched aftermarket distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-integrated terminal specialists over commodity stampers as battery packs digitize into data nodes. Long-term viability hinges on electronics integration competence rather than pure metallurgical scale. Acquisition targets should display IEC 61482 arc-flash qualification progress and established OEM pilot programs. The signal to watch is EV platform voltage standardization announcements that would concentrate procurement toward 800-volt qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Smart Terminal Development | Positions suppliers as data-node partners for EV thermal runaway monitoring systems. |
| Multi-Regime Compliance Pre-Certification | Accelerates tender participation across EPA TSCA Title VI, ECHA REACH, and SAMR GB/T jurisdictions. |
| Progressive Die Automation Investment | Matches Jiangsu and Zhejiang cost structures for stamped copper terminal production. |
| Fleet Rapid-Swap Protocol Partnership | Captures commercial vehicle uptime premiums through clamp-terminal specification influence. |
| Plating Chemistry Transition Qualification | Secures zinc-nickel and tin-zinc approvals ahead of cadmium and hexavalent chromium phase-outs. |
Research Methodology
A standing panel of Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and plating chemistry specialists provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation through EPA TSCA filings, SAMR GB/T standard publications, ECHA REACH restriction updates, and IHS Markit vehicle production databases. Bottom-up terminal demand modeling triangulated against top-down battery pack production forecasts across the analysis window.
Scenario-bracketing framed low, base, and high cases around copper price volatility bands, EV platform voltage adoption curves, and regulatory enforcement intensity variations. Segmentation dimensions modeled include terminal type, material grade, vehicle propulsion architecture, and regional production cluster. CAGRs derived from unit shipment trajectories indexed to battery pack installation rates and aftermarket replacement cycle assumptions. Forecast inputs incorporated LME copper futures curves and OEM wire-harness integration timelines.
Stress conditions across copper price spikes, REACH restriction acceleration, and Chinese export license tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EV voltage standardization and fleet electrification penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Global Bearings Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Wheel Studs Market