
 Automotive Battery Packs Market | 2026-2036
Automotive Battery Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Packs Market Insights
Battery-as-a-service subscription models and software-defined performance tiers is consolidating how automotive battery packs are monetized beyond hardware sales. CATL leverages its vertical integration into raw material refining to control cell costs across multiple continents. LG Energy Solution anchors its competitive position through R&D intensity in high-nickel cathode chemistries. Samsung SDI differentiates by specializing in prismatic cell architectures favored by premium European automakers.
Automotive battery packs are electrochemical energy storage systems comprising cells, modules, thermal management hardware, and battery management electronics, typically delivering 300-800 volts DC for traction power in electrified vehicles. Their primary purpose is to store and discharge electrical energy to drive electric motors while maintaining safe operating temperatures across charge cycles. Lithium-ion chemistry dominates current production volumes, though solid-state technology attracts the fastest-growing share of venture and OEM investment due to its energy density promise. Electric vehicle applications generate the deepest margin pools, while commercial vehicle segments present the steepest volume growth trajectory as fleet electrification mandates expand.
The EU Green Deal and F-Gas Regulation shape product standards by mandating carbon footprint declarations and restricting fluorinated greenhouse gases in thermal management systems. China's MIIT enforces GB standards for cell safety and recycling traceability that determine market access for domestic and imported packs. The US EPA and NHTSA coordinate tailpipe and fuel economy rules that effectively require automakers to expand battery electric vehicle lineups. Stakeholders must monitor how regulatory divergence between these jurisdictions affects pack design standardization and supply chain routing decisions.
Market Dynamics
Fleet electrification mandates from commercial logistics operators are compressing procurement cycles for high-capacity battery systems faster than manufacturing capacity can expand, creating structural tension between cell supply and vehicle rollout timelines.
Growth Catalysts
- F-Gas Regulation:The EU's restriction on fluorinated greenhouse gases in thermal management systems forces automakers to redesign battery pack cooling architectures, accelerating demand for next-generation thermal hardware.
- Commercial vehicle segments:Fleet electrification mandates from logistics operators in Germany and the Netherlands are driving the steepest volume growth trajectory for heavy-duty battery packs.
- Lithium-ion chemistry scale:Manufacturing concentration in China's Jiangsu and Fujian provinces delivers cost curves that enable price-competitive pack assembly across multiple continents.
Market Restraints
- Cathode material cost volatility:Nickel and cobalt price swings from DRC and Indonesian mining operations compress margin predictability for cell producers.
- Supply concentration risk:Overreliance on China's MIIT-certified cell manufacturers creates geopolitical exposure for European and North American automakers.
- Energy density ceiling:Current liquid electrolyte architectures face fundamental physics limits that constrain range extension without pack weight penalties.
Strategic Opportunities
- Second-life applications:Retired EV packs for stationary energy storage in California and Texas grid installations unlock residual value capture before recycling.
- Battery-as-a-service:Subscription ownership models separate pack asset value from vehicle purchase price, enabling new financing structures for fleet operators.
- Solid-state convergence:Ceramic electrolyte and silicon anode technology maturation promises step-change energy density for premium vehicle segments.
Industry Challenges
- Thermal engineering talent scarcity:Pack manufacturers compete with semiconductor and aerospace sectors for specialists in computational fluid dynamics and heat transfer modeling.
- GB standard certification timelines:China's MIIT approval processes for new cell chemistries extend product launch windows by 12-18 months for foreign suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Packs Market |
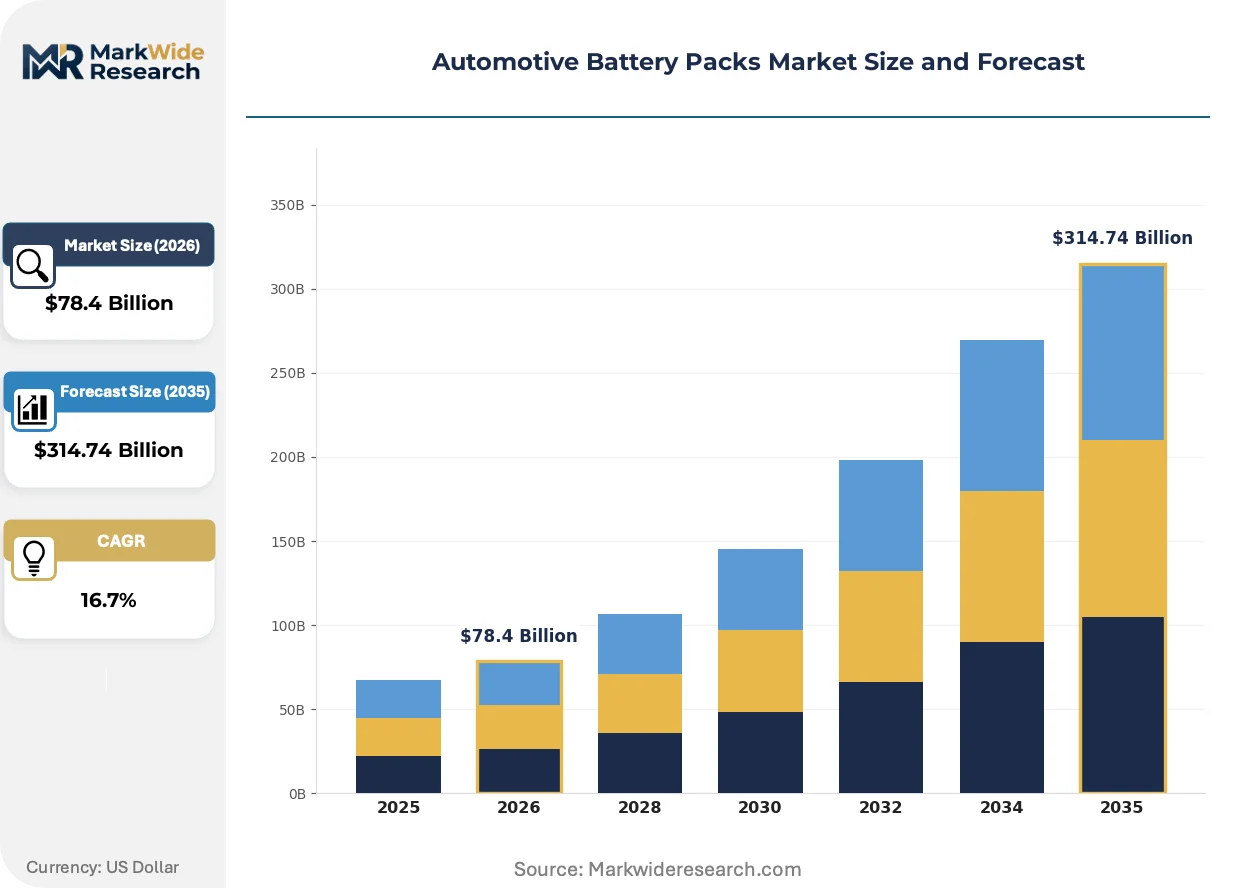
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $314.74 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Solid-State Application: Electric Vehicles, Hybrid Vehicles, Commercial Vehicles, Power Tools End User: Automakers, Aftermarket Providers, Fleet Operators, OEMs Technology: Battery Management Systems, Fast Charging, Thermal Management, Recycling |
| Companies Covered | CATL, LG Energy Solution, Panasonic Corporation, BYD Company Limited, SK On, Samsung SDI, Tesla, AESC, Svolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Packs Market Trends and Innovations
Solid-state cell architectures and software-defined pack management are converging to reshape how energy density, safety, and lifecycle value get engineered into automotive battery systems.
Solid-state batteries replace flammable liquid electrolytes with ceramic or sulfide conductive materials, enabling lithium-metal anodes that boost gravimetric energy density by 40-50% over conventional cells. BMW and Toyota have committed production lines for 2027-2028 vehicle integration, though manufacturing yield rates remain below commercial viability thresholds. This technology is rewriting competitive positioning in the premium EV segment by decoupling range performance from pack mass.
The EU Green Deal's carbon footprint declaration mandates for imported batteries force pack assemblers to document upstream emissions from mining through cell production. Suppliers must now deploy blockchain traceability systems or risk exclusion from European vehicle programs. German automakers are responding fastest, pressuring Korean and Chinese cell partners to retrofit smelters with emissions monitoring infrastructure.
Fleet operators in California and the Netherlands are unbundling battery ownership from vehicle acquisition, shifting capital expenditure to operating lease structures managed by specialized asset companies. This disintermediation compresses manufacturer-customer relationships and concentrates buying power among logistics procurement consortia. The model is spreading fastest where IRA tax credits and EU CO2 fleet targets align to subsidize electrification economics.
Automotive Battery Packs Market Segmentation
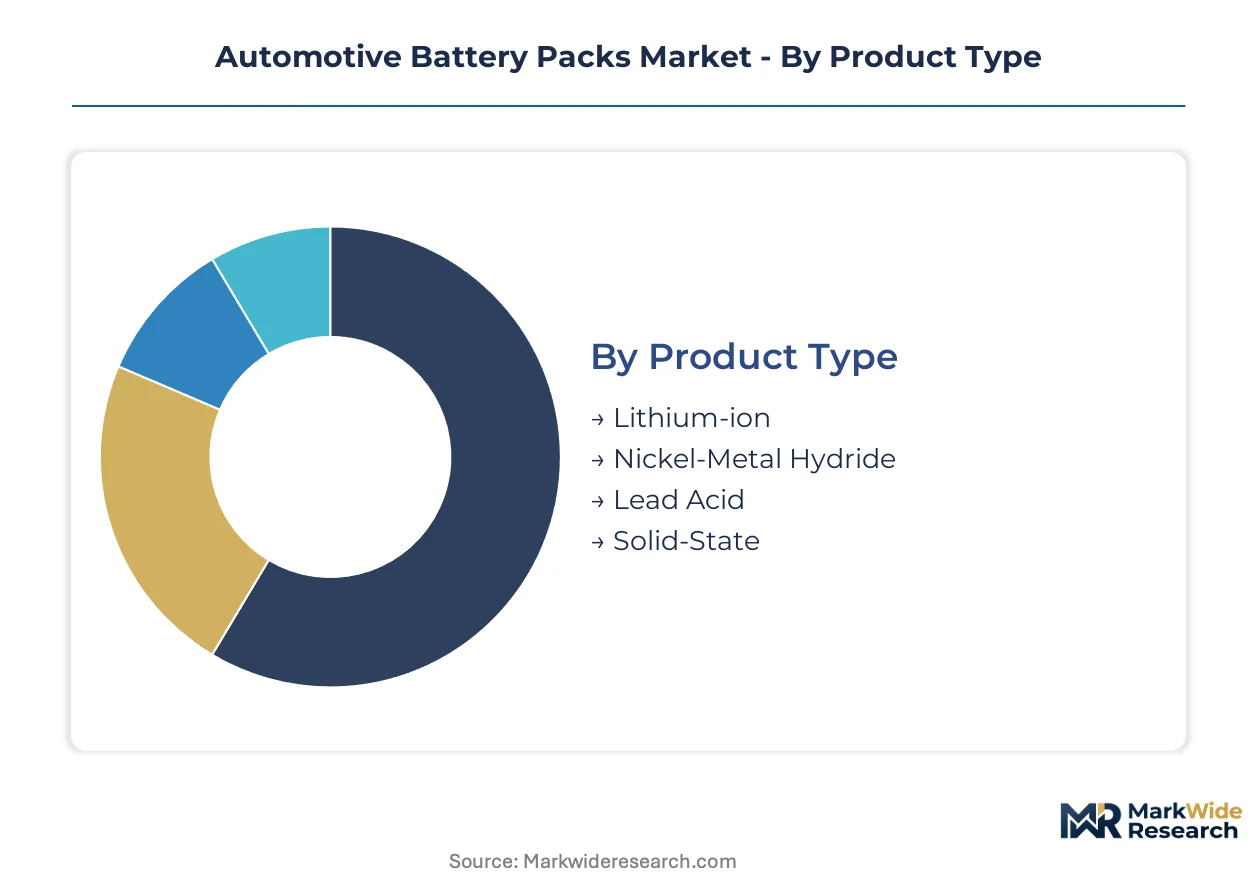
Automotive battery pack segmentation reveals how chemistry choices, vehicle integration requirements, and ownership models fragment procurement patterns across passenger and commercial electrification programs. Understanding these splits enables suppliers to align R&D spend with where margin pools and volume commitments are concentrating.
Product Type:
Lithium-ion dominates current volume while solid-state commands premium positioning, creating a bifurcated market where scale economies and performance premiums pull in opposite directions.
- Lithium-ion:NMC and LFP chemistries deliver 250-300 Wh/kg energy density through liquid electrolyte architectures. CATL and BYD manufacturing clusters in Fujian and Jiangsu provinces supply German and US automakers under MIIT-certified export frameworks.
- Solid-State:Ceramic electrolyte designs enable lithium-metal anodes with 40-50% density improvement over conventional cells. Toyota and BMW production commitments for 2027-2028 vehicle integration are reshaping competitive positioning in the premium EV segment despite yield rate challenges.
- Nickel-Metal Hydride:Mature chemistry retains cost advantage for hybrid auxiliary power applications.
- Lead Acid:Legacy technology serves 12V subsystem support in mild-hybrid architectures.
Today's leader: Lithium-ion. Tomorrow's challenger: Solid-State.
Application:
Passenger electrification absorbs the deepest R&D investment while commercial mandates compress fleet procurement timelines fastest.
- Commercial Vehicles:Heavy-duty packs for logistics fleets face 800V+ architectures and megawatt-hour scale requirements. German and Dutch operators are accelerating electrification timelines ahead of EU CO2 fleet targets.
- Electric Vehicles:Passenger BEV applications generate the steepest margin pools through software-defined performance tiers and battery-as-a-service monetization. IRA tax credits in the US and F-Gas Regulation compliance costs in Europe are restructuring pack sourcing decisions.
- Hybrid Vehicles:Smaller-capacity packs optimize cost for transitional powertrain architectures.
- Power Tools:Compact cylindrical cell formats serve professional and consumer equipment segments.
Commercial vehicle procurement is expanding most quickly. Electric vehicle applications retain the deepest margin capture.
End User:
Direct OEM relationships concentrate buying power while fleet operators are unbundling ownership from vehicle acquisition.
- Fleet Operators:California and Netherlands logistics consortia are shifting capital expenditure to operating lease structures managed by specialized battery asset companies. This disintermediation compresses manufacturer-customer relationships and concentrates procurement power among procurement consortia.
- Automakers:Volkswagen, BMW, and Tesla integrate pack design with platform engineering to optimize thermal management and crash safety. Their GB standard certification timelines with China's MIIT extend product launch windows by 12-18 months for foreign cell suppliers.
- Aftermarket Providers:Independent service networks address replacement demand outside warranty periods.
- OEMs:Tier-1 suppliers deliver integrated powertrain solutions to vehicle manufacturers without captive cell production.
Automaker integration depth currently defines competitive position. Fleet operator buying consolidation is gaining share fastest.
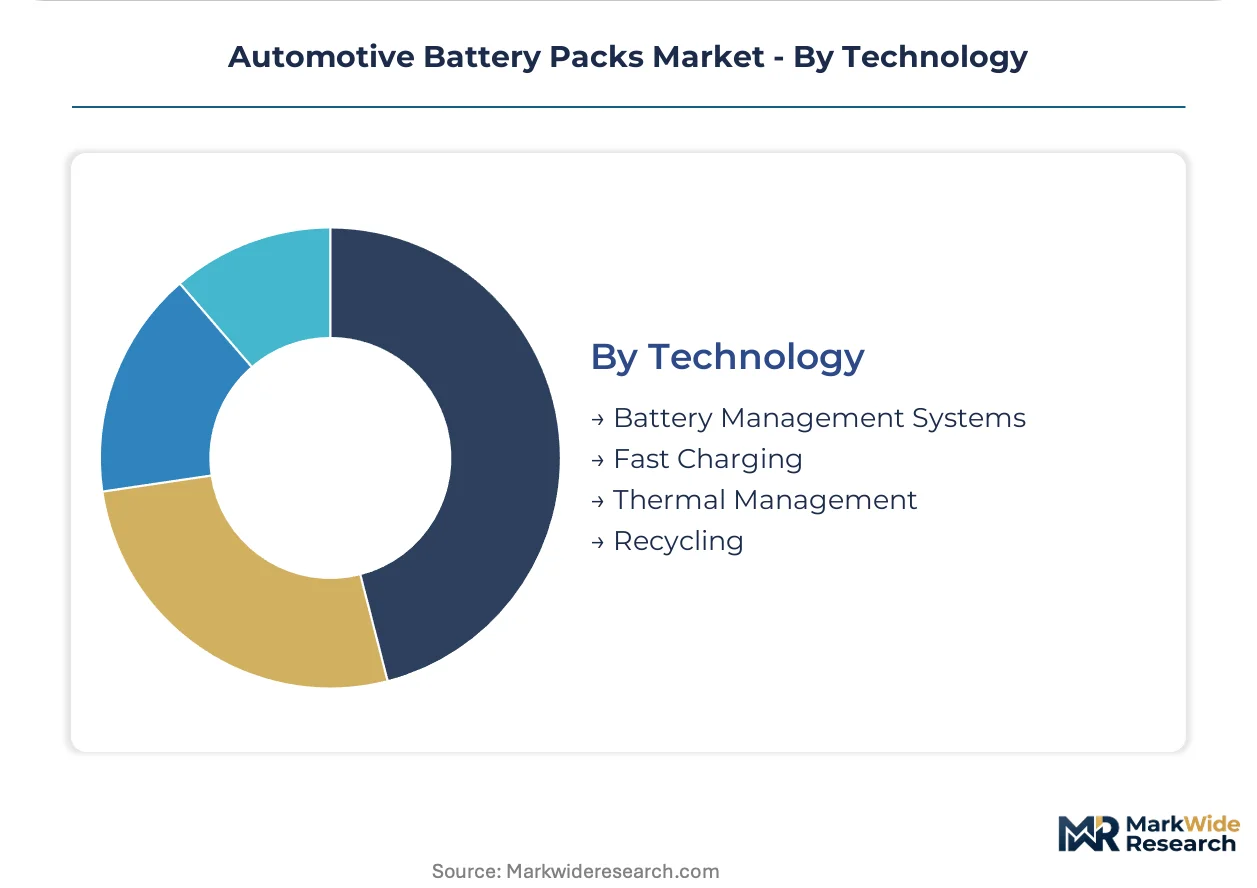
Technology:
Thermal hardware and software layers are decoupling as separate value creation points within pack architecture.
- Thermal Management:Liquid cooling plates and phase-change materials maintain cell temperatures across fast-charging cycles. EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing redesign of cooling architectures toward next-generation hardware.
- Battery Management Systems:Software-defined performance tiers enable over-the-air updates that optimize state-of-charge windows and degradation curves. This capability is central to battery-as-a-service subscription models.
- Fast Charging:800V architectures and silicon carbide inverters reduce charging duration for highway corridor deployment.
- Recycling:Hydrometallurgical recovery processes extract lithium, nickel, and cobalt from retired packs for closed-loop supply.
Thermal hardware commands current capital allocation. Battery management software is climbing the fastest as a monetization layer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing scale and Germany's regulatory stringency are pulling automotive battery pack development in different directions, while the United States leverages tax incentives to reshore supply chains.
China
CATL and BYD anchor the world's largest lithium-ion cell production base in Fujian and Jiangsu provinces. MIIT enforces GB standards for cell safety and recycling traceability that determine market access for domestic and imported packs. Shenzhen and Ningbo industrial clusters supply German and US automakers under certified export frameworks.
Germany
Volkswagen and BMW integrate pack design with platform engineering to optimize thermal management and crash safety. The F-Gas Regulation and EU Green Deal mandate carbon footprint declarations and restrict fluorinated greenhouse gases in cooling systems. Bavaria and Baden-Württemberg host R&D centers where automakers pressure Korean and Chinese cell partners to retrofit smelters with emissions monitoring.
United States
IRA tax credits are restructuring pack sourcing decisions and accelerating domestic assembly investments. EPA and NHTSA coordinate tailpipe and fuel economy rules that effectively require expanded battery electric vehicle lineups. Michigan and Texas industrial zones attract cathode material refiners seeking to bypass supply concentration risk.
South Korea
LG Energy Solution and Samsung SDI anchor competitive positions through R&D intensity in high-nickel cathode chemistries and prismatic cell architectures. The country's national industrial regulator supports battery sector investments through strategic technology programs. Gyeonggi-do and Ulsan manufacturing corridors supply premium European automakers with specialized cell formats.
Japan
Toyota has committed production lines for solid-state battery integration by 2027-2028 despite manufacturing yield challenges. METI coordinates national battery strategy to secure raw material supply chains and next-generation technology development. Aichi and Osaka prefectures concentrate automotive electronics expertise that supports pack management system innovation.
Automotive Battery Packs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cell producers capturing upstream value and pack assemblers competing on integration engineering. The vendor base concentrates around three strategic archetypes: vertically integrated material-to-cell producers, pure-play cell specialists, and automaker-captive pack divisions. Capacity expansion and strategic partnerships dominate competitive moves as players race to secure cathode supply and thermal engineering talent.
Within the integrated producer tier, CATL and BYD exemplify upstream control over raw material refining that compresses cell costs across multiple continents. LG Energy Solution occupies a position among Korean specialists leveraging R&D intensity in advanced cathode formulations. These three anchors represent divergent approaches to securing margin pools as the industry transitions toward solid-state architectures and software-defined performance tiers.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Corporation |
| BYD Company Limited |
| SK On |
| Samsung SDI |
| Tesla |
| AESC |
| Svolt |
| Others |
Pricing and Supply Chain Analysis
Solid-state manufacturing scale-up in Japan and Germany is compressing cost curves for next-generation cells while simultaneously redrawing supplier power maps away from liquid-electrolyte incumbents. This dual transformation forces pack assemblers to renegotiate long-term offtake terms as cathode material volatility and thermal hardware redesign costs ripple through contract structures.
Pricing Analysis
Capacity additions in China's Jiangsu and Fujian provinces are reshaping price floors for LFP and NMC cells, forcing Korean and Japanese suppliers into premium-mid-economy pricing differentiation. Price differentiation hinges on MIIT certification status and cathode chemistry grade, with IRA-compliant sourcing commanding premiums over standard export tiers. Cost compression in standard-density packs is intensifying because automakers are consolidating procurement volumes among fewer cell partners. Fleet operators in California show highest price sensitivity through battery-as-a-service negotiations, while premium European OEMs absorb cost premiums for solid-state pilot programs.
Supply Chain Analysis
Cathode active material supply rests on Indonesian nickel processing, Chilean lithium brine operations, and Chinese precursor refining. The automotive battery pack supply chain draws from spodumene concentrate, nickel sulfate, and cobalt hydroxide as primary feedstocks. Single-source vulnerability concentrates in China's MIIT-certified cell manufacturing base, exposing European and North American automakers to geopolitical disruption. Distribution runs through automaker-captive pack assembly plants in Michigan, Bavaria, and Gyeonggi-do, with fleet operators increasingly sourcing through specialized battery asset companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive battery packs market reads as a late-cycle quality story where fleet electrification mandates and solid-state technology maturation are pulling procurement toward premium thermal management and software-defined performance tiers.
For Market Incumbents: Cement backward integration into cathode precursor refining to defend margin position against Korean and Chinese cell specialists. Lock in GB standard certification pipelines with China's MIIT to compress launch timelines for foreign market entry. Prioritize thermal engineering talent acquisition from semiconductor cooling specialists before competitors exhaust this scarce pool. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and the Netherlands opens a window for next-generation cooling hardware specialists to capture redesign cycles among premium automakers. Target heavy-duty commercial vehicle segments where 800V architectures and megawatt-hour scale requirements outpace incumbent capacity expansion. Lead with battery-as-a-service financing structures that disintermediate traditional OEM procurement relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among thermal management hardware specialists with automotive-adjacent aerospace or semiconductor heritage. The five-to-ten-year viability window favors acquisition targets with solid-state electrolyte pilot production and established OEM validation programs. Watch silicon anode yield rate breakthroughs as the signal for premium segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with CATL or LG Energy Solution secure cathode allocation for German OEM platform launches. |
| Software-Defined Vehicle Investment | Over-the-air battery management updates enable subscription revenue streams and lifecycle value capture. |
| Geographic Manufacturing Footprint | IRA-compliant assembly in Michigan and Texas unlocks tax credits for US fleet operator procurement. |
| Charging Infrastructure Partnership | 800V fast-charging corridor deployment with silicon carbide inverters reduces range anxiety for commercial logistics. |
| Platform Standardization | Cell-to-pack architectures across Volkswagen and BMW models compress thermal hardware engineering costs. |
Research Methodology
Bottom-up electric vehicle and commercial fleet modeling reconciled against top-down cell production tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator sustainability directors, and thermal management R&D heads combined with secondary validation from SEC filings, IHS Markit vehicle registration data, MIIT production disclosures, and EU F-Gas Regulation compliance filings. This dual-source approach enables cross-checking between demand-side adoption curves and supply-side capacity expansion timelines.
Historical trendline analysis of lithium-ion cost curves and solid-state pilot production yields informed projection parameters across the modeling period. Segmentation dimensions include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from slope analysis of segment-specific adoption curves, incorporating cathode chemistry transition rates, thermal hardware redesign cycles, and battery-as-a-service penetration assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden nickel-cobalt price spikes or MIIT certification timeline extensions. Forecasts reflect documented assumptions regarding solid-state yield maturation, IRA credit continuity, and EU CO2 fleet target enforcement. A small set of named triggers—silicon anode commercialization, F-Gas Regulation expansion, and fleet operator bankruptcy cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Special Purpose Electric Vehicle Market