
 Exhaust Gas Recirculation (EGR) Valve Market | 2026-2036
Exhaust Gas Recirculation (EGR) Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Exhaust Gas Recirculation (EGR) Valve Market Analysis
Buyer concentration among commercial vehicle fleets is rebalancing toward integrated procurement contracts with Tier-1 suppliers. BorgWarner Inc. leverages its turbocharger-EGR bundling to anchor long-term supply agreements with North American truck manufacturers. Continental AG competes through embedded sensor integration that sustains premium positioning in smart EGR architectures. Mahle GmbH specializes in thermal management co-design, occupying a defensible niche in high-load diesel applications.
An exhaust gas recirculation valve meters cooled exhaust back into the intake manifold to suppress combustion temperatures and curtail nitrogen oxide formation, typically operating at exhaust temperatures exceeding 600°C with corrosion-resistant stainless steel or Inconel valve bodies and precision-stepper motor or pneumatic actuator control. Electronic EGR valves now dominate OEM fitment for light commercial vehicles where closed-loop feedback enables real-time NOx compliance, while smart EGR systems represent the fastest-expanding technology tier as integrated sensor arrays and predictive control algorithms displace fixed-geometry hardware in heavy-duty platforms. Pneumatic variants retain aftermarket relevance due to lower replacement cost, though margin pools increasingly migrate toward software-calibrated electronic units.
The EPA enforces Tier 4 Final and upcoming Tier 5 standards for off-road diesel engines, compelling valve suppliers to certify thermal fatigue resistance and leak-tight shutoff under cyclic duty. Euro VI Stage V mandates from the European Commission, alongside China's MIIT emission benchmarks for commercial vehicles, shape product roadmaps across export-oriented manufacturers. Stakeholders must monitor regulatory divergence between California Air Resources Board pathways and federal EPA timelines, as compliance strategy fragmentation threatens tooling amortization schedules and cross-border platform commonality.
Market Dynamics
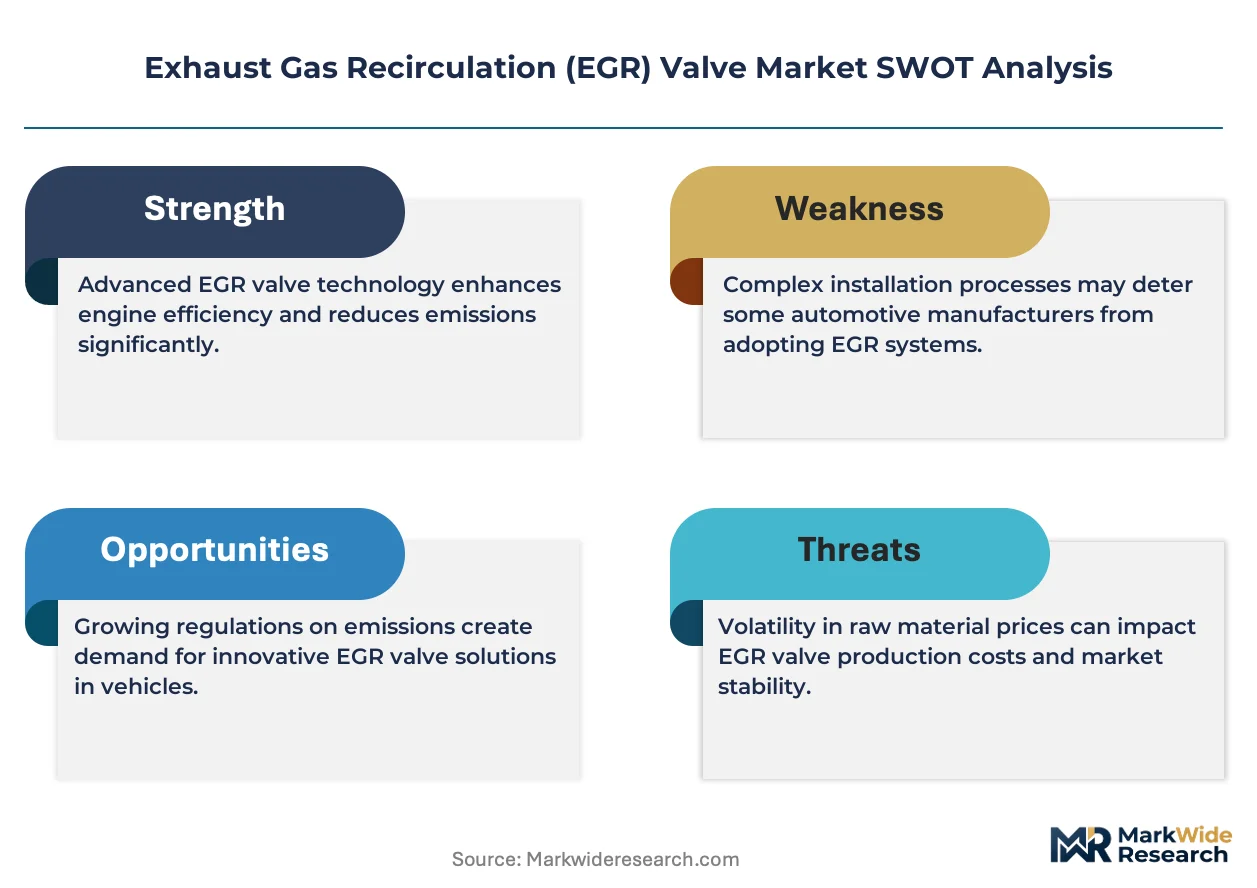
Commercial vehicle fleet procurement is consolidating around long-term supply agreements with Tier-1 suppliers capable of delivering integrated turbocharger-EGR bundles and embedded sensor architectures.
Growth Catalysts
- EPA Tier 4 Final mandates:Off-road diesel engine standards compel thermal fatigue-resistant valve redesigns, expanding certified supplier rosters across construction and agricultural equipment.
- Electronic valve architecture:Closed-loop feedback systems with precision stepper motor control enable real-time NOx compliance in light commercial vehicle platforms.
- German commercial vehicle production:Concentrated OEM manufacturing in Baden-Württemberg and Bavaria anchors component procurement volumes for high-load diesel applications.
Market Restraints
- Inconel and stainless steel input costs:Corrosion-resistant alloys required for 600°C exhaust exposure face commodity price volatility, compressing margin pools on pneumatic aftermarket variants.
- Supplier concentration risk:Turbocharger-EGR bundling capabilities concentrate among integrated Tier-1s, limiting second-source options for mid-volume truck manufacturers.
- Smart EGR substitution pressure:Predictive control algorithms with integrated sensor arrays threaten fixed-geometry hardware viability in heavy-duty platforms.
Strategic Opportunities
- Euro VI Stage V regulatory tailwind:European Commission mandates for commercial vehicles create certified product demand across export-oriented manufacturers serving continental fleets.
- Thermal management co-design services:Engineering partnerships for high-load diesel applications offer defensible positioning beyond commodity valve supply.
- China MIIT emission benchmarks:Commercial vehicle standards open procurement channels for certified suppliers capable of meeting dual carbon compliance timelines.
Industry Challenges
- Calibration software integration complexity:Electronic EGR valve deployment requires embedded systems engineering talent scarce among traditional pneumatic valve suppliers.
- Cross-border certification timeline fragmentation:Divergent California Air Resources Board and federal EPA pathways threaten tooling amortization schedules for common platform architectures.
- Legacy fleet retrofit compatibility:Aftermarket electronic valve installation demands controller reprogramming capabilities beyond standard replacement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhaust Gas Recirculation (EGR) Valve Market |
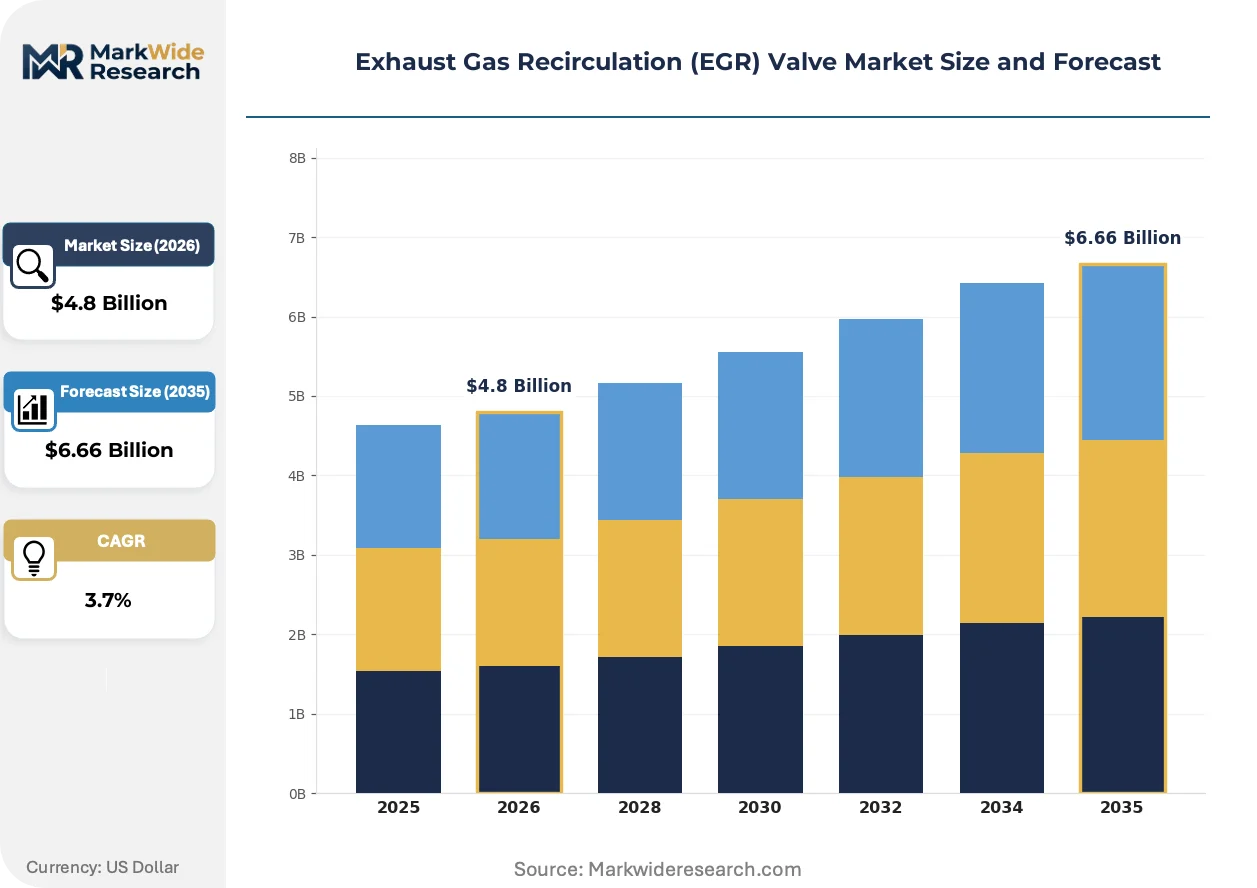
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Pneumatic, Hydraulic, Mechanical Application: Light Commercial Vehicles, Heavy-Duty Vehicles, Passenger Cars, Agricultural Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Variable Geometry, Fixed Geometry, Integrated Solutions, Smart EGR Systems |
| Companies Covered | BorgWarner Inc., Continental AG, Denso Corporation, Mahle GmbH, Valeo SA, Delphi Technologies, Rheinmetall Automotive, Hitachi Automotive Systems, Aisin Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhaust Gas Recirculation (EGR) Valve Market Emerging Trajectories
Smart EGR architectures are compressing the competitive window for fixed-geometry hardware as predictive algorithms and sensor fusion redefine valve control paradigms across heavy-duty diesel platforms.
Electronic actuator technology with precision stepper motor control is electrifying valve response characteristics in light commercial vehicles. Fleet operators operating under EPA Tier 4 compliance timelines demand sub-100-millisecond positioning accuracy for transient load conditions. This capability compression is eliminating pneumatic alternatives from OEM fitment specifications.
REACH substance restrictions and RoHS compliance deadlines are forcing material substitutions in valve body manufacturing. European suppliers face accelerated certification cycles for lead-free bearing surfaces and hexavalent chromium-free coatings. German KBA type-approval processes now prioritize documented supply chain chemical compliance over legacy performance benchmarking.
Integrated procurement contracts with multi-year volume commitments are displacing spot purchasing across North American truck manufacturing. Tier-1 suppliers capturing turbocharger-EGR bundling mandates now dictate aftermarket parts pricing through captive distribution networks. This channel consolidation is most visible in long-haul fleet maintenance operations where total cost of ownership calculations override component-level sourcing flexibility.
Exhaust Gas Recirculation (EGR) Valve Market Segmentation
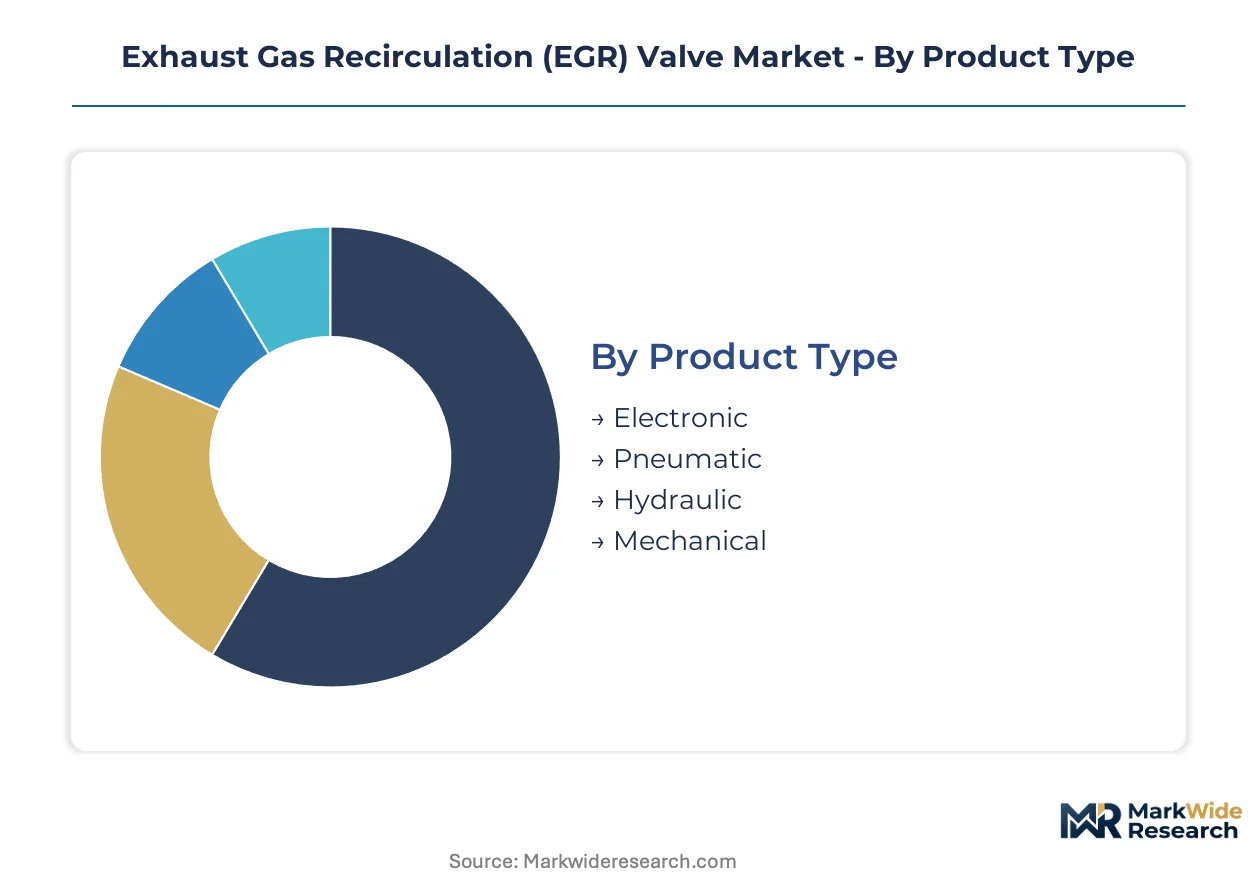
EGR valve segmentation tracks how thermal management requirements diverge across duty cycles and compliance tiers. Procurement patterns split between embedded OEM architectures and aftermarket replacement protocols.
Product Type:
Replacement cycles accelerate where electronic actuation supersedes pneumatic legacy hardware in fleet refresh programs.
- Electronic:Precision stepper motors enable closed-loop feedback with sub-100-millisecond positioning accuracy. Demand clusters in North American light commercial fleets facing EPA Tier 4 Final compliance deadlines. OEMs now specify electronic units exclusively for new platform certification.
- Pneumatic:Compressed air actuation operates without controller integration, sustaining aftermarket relevance where replacement cost dominates total ownership calculations. Margin compression from alloy input volatility limits supplier investment in pneumatic line extensions.
- Hydraulic:Fluid-pressure actuation tolerates sustained high-temperature exposure in off-road construction equipment.
- Mechanical:Cable-linkage designs persist in legacy agricultural machinery with minimal electronic infrastructure.
Electronic valves sit at the top of the volume ranking, with smart EGR systems climbing the fastest.
Application:
Cost tiers stratify around thermal load severity and certification stringency rather than vehicle class alone.
- Heavy-Duty Vehicles:Sustained 600°C exhaust exposure demands Inconel valve bodies with thermal fatigue certification. German long-haul fleets anchor procurement volumes through integrated turbocharger-EGR bundles.
- Light Commercial Vehicles:Transient duty cycles prioritize rapid actuator response over peak temperature tolerance. EPA Tier 4 compliance timelines concentrate North American demand for electronic valve fitment.
- Passenger Cars:Downsized gasoline turbocharging reduces EGR dependency in light-duty segments.
- Agricultural Equipment:Seasonal operation patterns extend replacement intervals, favoring pneumatic aftermarket sourcing.
Heavy-duty applications command premium positioning, while light commercial vehicles gain share fastest in unit terms.
End User:
Customer type determines specification authority and margin capture through the value chain.
- OEMs:Direct platform integration mandates calibrate valve response maps to engine control unit architectures. German commercial vehicle OEMs in Baden-Württemberg specify embedded sensor arrays for Euro VI Stage V pre-certification.
- Tier-1 Suppliers:Turbocharger-EGR bundling capabilities concentrate procurement influence among integrated system houses. Long-term supply agreements now span multi-year volume commitments with captive aftermarket pricing.
- Aftermarket Providers:Independent distribution networks face channel consolidation as Tier-1s tighten parts availability.
- Vehicle Assemblers:Contract manufacturing arrangements delegate component specification to platform owners.
Tier-1 suppliers sit at the top of the volume ranking, with OEM direct sourcing climbing the fastest.
Technology:
Maturity gradients separate commodity hardware from algorithm-dependent control architectures.
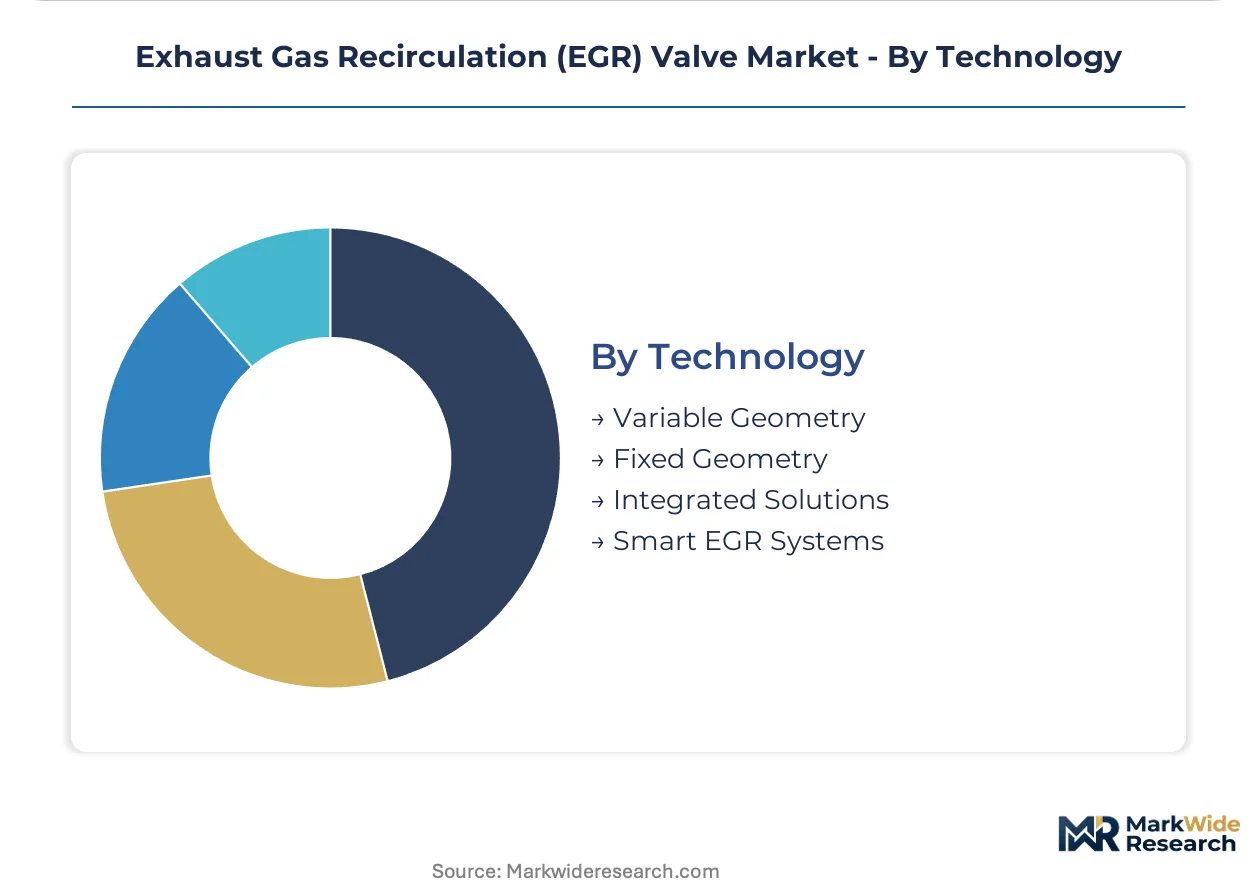
- Smart EGR Systems:Predictive control algorithms with sensor fusion displace fixed-geometry hardware through real-time NOx optimization. Integrated procurement contracts from North American truck manufacturers accelerate deployment.
- Variable Geometry:Adjustable valve lift profiles match exhaust flow rates to transient load conditions. Euro VI Stage V mandates sustain European demand for calibrated thermal management.
- Fixed Geometry:Static flow orifices face substitution pressure as smart systems compress the competitive window.
- Integrated Solutions:Turbocharger-EGR packaging reduces installation complexity at the assembly line.
Variable geometry sits at the top of the volume ranking, with smart EGR systems climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent clusters around Stuttgart and Munich anchor EGR valve design capabilities for commercial vehicle applications. Component procurement concentrates where OEM manufacturing density intersects with emissions engineering expertise.
Germany
Baden-Württemberg and Bavaria host dense concentrations of commercial vehicle OEMs demanding Euro VI Stage V certified components. The KBA type-approval process prioritizes documented chemical compliance in supply chains. Stuttgart's engineering workforce sustains thermal management co-design partnerships between valve suppliers and engine manufacturers.
United States
North American truck manufacturers consolidate procurement around integrated turbocharger-EGR bundles from Tier-1 suppliers. EPA Tier 4 Final and upcoming Tier 5 standards compel thermal fatigue-resistant valve redesigns for off-road diesel engines. Michigan and Indiana manufacturing corridors anchor heavy-duty platform development with sub-100-millisecond actuator response specifications.
China
MIIT emission benchmarks for commercial vehicles open procurement channels for certified suppliers meeting dual carbon compliance timelines. Domestic OEMs in the Yangtze River Delta and Pearl River Delta regions scale production of heavy-duty diesel platforms requiring smart EGR architectures. Shanghai-based engineering centers coordinate sensor integration for predictive control algorithms.
Japan
Precision actuator manufacturers in the Nagoya-Chubu region supply stepper motor technologies for electronic valve fitment. METI industrial standards shape thermal management specifications for export-oriented engine platforms. Toyota City and surrounding Aichi Prefecture clusters integrate EGR calibration with engine control unit architectures.
South Korea
Seoul Capital Area conglomerates pursue backward integration into valve manufacturing for captive diesel engine supply. Domestic commercial vehicle producers face tightening emissions benchmarks aligned with Euro VI equivalent standards. Busan-Ulsan industrial zones concentrate heavy machinery production demanding hydraulic EGR variants for sustained high-temperature exposure.
Exhaust Gas Recirculation (EGR) Valve Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The market structure tilts toward consolidated procurement influence where turbocharger-EGR bundling capabilities concentrate supply relationships. Three archetypes dominate: integrated system houses with multi-product portfolios, thermal management specialists with co-design expertise, and component fabricators serving aftermarket replacement cycles. Competitive moves center on long-term supply agreement capture and embedded sensor architecture development.
Among German-based integrated suppliers, Continental AG and Mahle GmbH exemplify divergent positioning strategies within the same regulatory environment. BorgWarner Inc. anchors the North American premium tier through bundled system offerings. These three entities represent how geographic proximity to OEM engineering centers shapes competitive archetype selection.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Continental AG |
| Denso Corporation |
| Mahle GmbH |
| Valeo SA |
| Delphi Technologies |
| Rheinmetall Automotive |
| Hitachi Automotive Systems |
| Aisin Seiki |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between Euro VI Stage V pre-certified smart architectures and pneumatic aftermarket replacements manifests simultaneously in pricing power concentration and supply chain tiering. German KBA type-approval processes anchor premium positioning through documented chemical compliance, while commodity pneumatic variants face margin compression from Inconel price volatility and limited supplier differentiation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electronic valve actuators as domestic OEMs scale heavy-duty diesel production. Contract-based long-term offtake agreements dominate OEM procurement, with pricing stratifying across premium smart EGR systems, standard electronic units, and economy pneumatic replacements. Cost compression in pneumatic aftermarket tiers intensifies because alloy input volatility outpaces replacement volume growth. Fleet operators in agricultural equipment show highest price sensitivity, while German commercial vehicle OEMs prioritize thermal fatigue certification over unit cost.
Supply Chain Analysis
EPA Tier 4 Final and Euro VI Stage V qualification gating concentrates certified production among German, Chinese, and North American manufacturing clusters. Valve body fabrication draws from corrosion-resistant stainless steel and Inconel supply chains anchored in specialty alloy foundries. Single-source vulnerability runs through precision stepper motor suppliers in Japan's Nagoya-Chubu region. Distribution runs through Tier-1 captive networks for OEM fitment and independent aftermarket channels for legacy pneumatic replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between EPA Tier 5 pre-certification investments in North America and established Euro VI Stage V production bases in Germany, where regulatory compliance costs are already amortized across existing platform architectures.
For Market Incumbents: Lock in turbocharger-EGR bundling mandates through multi-year volume commitments before smart EGR substitution accelerates fixed-geometry obsolescence. Deepen backward integration into precision actuator manufacturing to offset Japanese stepper motor supply concentration. Channel control through captive aftermarket parts networks defends margin pools against independent distributors.
For New Entrants and Emerging Players: Aftermarket service providers represent the most penetrable channel partner type for electronic valve retrofit capabilities beyond standard replacement workflows. Agricultural equipment fleets in North America offer white-space targeting where controller reprogramming expertise remains scarce among traditional pneumatic suppliers. A go-to-market angle centered on calibration software integration partnerships with regional fleet maintenance operators bypasses direct Tier-1 supplier competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where embedded sensor architecture development costs outpace standalone valve manufacturer R&D budgets. Long-term viability favors thermal management co-design specialists with defensible engineering partnerships rather than commodity fabricators. Acquisition target archetypes include precision actuator manufacturers and calibration software houses. The signal to watch is California Air Resources Board pathway divergence from federal EPA timelines fragmenting certification commonality.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart EGR Architecture Development | Sensor fusion capabilities displace fixed-geometry hardware in heavy-duty platforms requiring real-time NOx optimization. |
| Thermal Management Co-Design Partnership | Engineering collaboration with Baden-Württemberg OEMs creates defensible positioning beyond commodity valve supply. |
| Precision Actuator Backward Integration | In-house stepper motor production reduces dependency on Nagoya-Chubu specialty suppliers and compresses lead times. |
| Long-Term Supply Agreement Capture | Multi-year turbocharger-EGR bundling mandates with North American truck manufacturers lock in aftermarket pricing control. |
| Dual Certification Investment | Parallel EPA Tier 5 and Euro VI Stage V qualification sustains cross-border platform commonality amid regulatory divergence. |
Methodological Framework
Direct dialogue with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket service heads, and thermal management R&D directors grounded qualitative findings in operational reality. Secondary validation drew from EPA certification filings, KBA type-approval registries, MIIT emission benchmark disclosures, and vehicle production databases. Bottom-up unit economics triangulated against top-down market sizing across electronic, pneumatic, hydraulic, and mechanical product categories.
Bottom-up volume modeling tracked valve shipments by propulsion architecture, vehicle class, content per engine, and regional production cluster, while top-down approaches validated aggregate market magnitude against OEM procurement disclosures. CAGRs were derived from segment-level growth rate convergence across the projection horizon. Industry-specific forecast inputs included EPA Tier 5 implementation timing assumptions and Euro VI Stage V fleet penetration curves for commercial vehicle applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between California Air Resources Board and federal EPA pathways, alloy commodity price volatility, and smart EGR algorithm adoption rates in heavy-duty platforms. Forecasts reflect documented assumptions about certification timeline alignment and thermal management co-design partnership durability. A model refresh is warranted upon material change in EPA Tier 5 final rule promulgation or Euro VII standard advancement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Rail Components Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Headlight Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Global Automotive Composite Liftgate Market