
 Two-Wheeler Lubricants Market | 2026-2036
Two-Wheeler Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Lubricants Market Analytics
Base oil refining capacity in Southeast Asia is hardening as regional processors expand Group II and Group III output. Shell PLC leverages integrated supply chains from Singapore to serve motorcycle OEMs across ASEAN markets. Castrol sustains brand equity through technical partnerships with Indian and Indonesian manufacturers. Idemitsu Kosan Co., Ltd anchors its position in Japan and exports high-performance synthetic formulations to premium motorcycle segments globally.
Two-wheeler lubricants are formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and protect engine components under high RPM and stop-start operating cycles, with viscosity grades typically ranging from 10W-30 to 20W-50 for tropical climates. Engine oil dominates product type revenue due to frequent drain intervals and OEM-specified formulations, while synthetic and semi-synthetic categories capture expanding margin pools as scooter and motorcycle makers specify longer service intervals. Electric bike lubrication represents an emerging application segment with distinct thermal management and bearing protection requirements that diverge from internal combustion formulations.
India's BIS lubricant standards, Indonesia's SNI certification requirements, and Thailand's industrial product standards collectively shape formulation compliance and market access across the three largest ASEAN motorcycle markets. The US EPA and California Air Resources Board influence additive chemistry through emissions-linked engine durability requirements that extend to export markets. Stakeholders must monitor evolving OEM oil specifications and regional certification timelines to align R&D investments with tightening performance mandates.
Market Dynamics
OEM oil specification tightening across Southeast Asian motorcycle manufacturers is compressing drain intervals and forcing blenders toward higher-grade Group II and Group III base oil formulations. This specification creep creates margin pressure for independent lubricant suppliers while rewarding integrated refiners with captive base oil supply.
Growth Catalysts
- Urban Delivery Network Expansion:Indonesia's last-mile logistics operators are extending fleet sizes and maintenance frequencies, concentrating lubricant demand in Jakarta and Surabaya metropolitan zones.
- BIS Certification Mandates:India's Bureau of Indian Standards lubricant performance requirements are eliminating substandard formulations and redirecting blender investment toward API SN-plus and JASO MA2 qualified products.
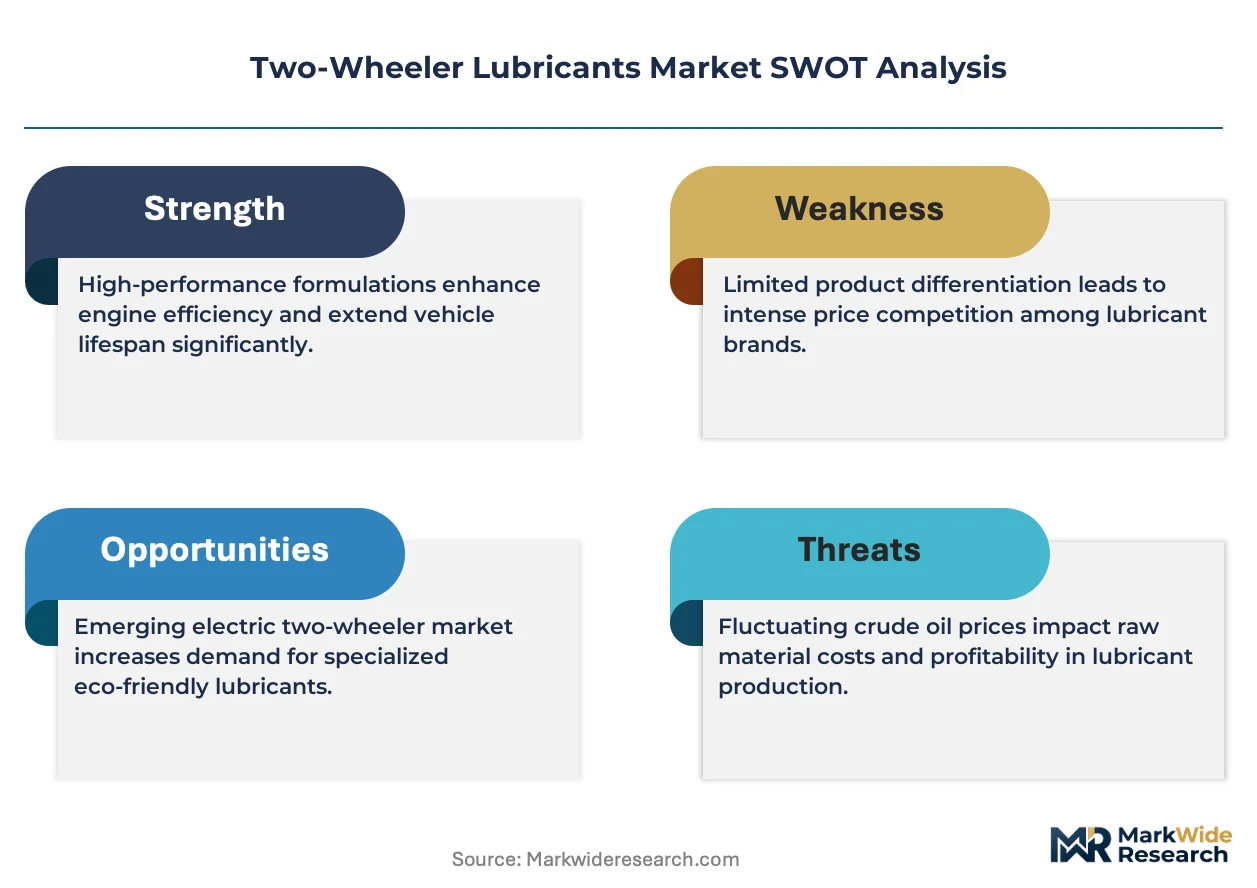
- Scooter Electrification Infrastructure:Thermal management fluid requirements for electric two-wheeler battery packs and reduction gearboxes are opening formulation white spaces distinct from internal combustion engine oils.
Market Restraints
- Base Oil Supply Concentration:Southeast Asian Group II and Group III refining capacity remains concentrated in Singapore and Thailand, exposing blenders in Indonesia and Vietnam to freight cost volatility and import duty exposure.
- Additive Chemistry Constraints:US EPA and California Air Resources Board emissions durability requirements limit phosphorus and sulfur content in motorcycle oils, constraining anti-wear package efficacy for high-RPM air-cooled engines.
- Extended Drain Interval Technology:Synthetic and semi-synthetic formulations achieving 5,000-10,000 kilometer service intervals are compressing unit volume demand per vehicle in service despite premium pricing.
Strategic Opportunities
- Tier-Two Indian Urbanization:Cities including Lucknow, Indore, and Coimbatore are experiencing two-wheeler density increases without proportional service infrastructure, creating whitespace for branded quick-lube networks.
- Electric Powertrain Fluid Specialization:Dielectric coolants and bearing greases formulated for electric motor thermal profiles represent uncaptured margin pools as OEMs finalize e-scooter platform designs.
- Thailand's Industrial Product Standards Alignment:Convergence with ASEAN harmonized lubricant specifications is reducing multi-country formulation complexity for suppliers with Thai manufacturing presence.
Industry Challenges
- Formulation Chemist Scarcity:Blend plants in Vietnam and the Philippines face recruitment gaps for tribologists capable of balancing JASO clutch friction standards with fuel economy requirements.
- Certification Timeline Compression:OEM co-engineering agreements now demand 12-18 month lubricant qualification cycles versus historical 24-36 month windows, straining R&D pipeline capacity.
- Multi-Grade Inventory Complexity:Tropical climate 20W-50, 10W-40, and emerging 5W-30 specifications require parallel stockkeeping units that fragment distributor warehousing economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Lubricants Market |
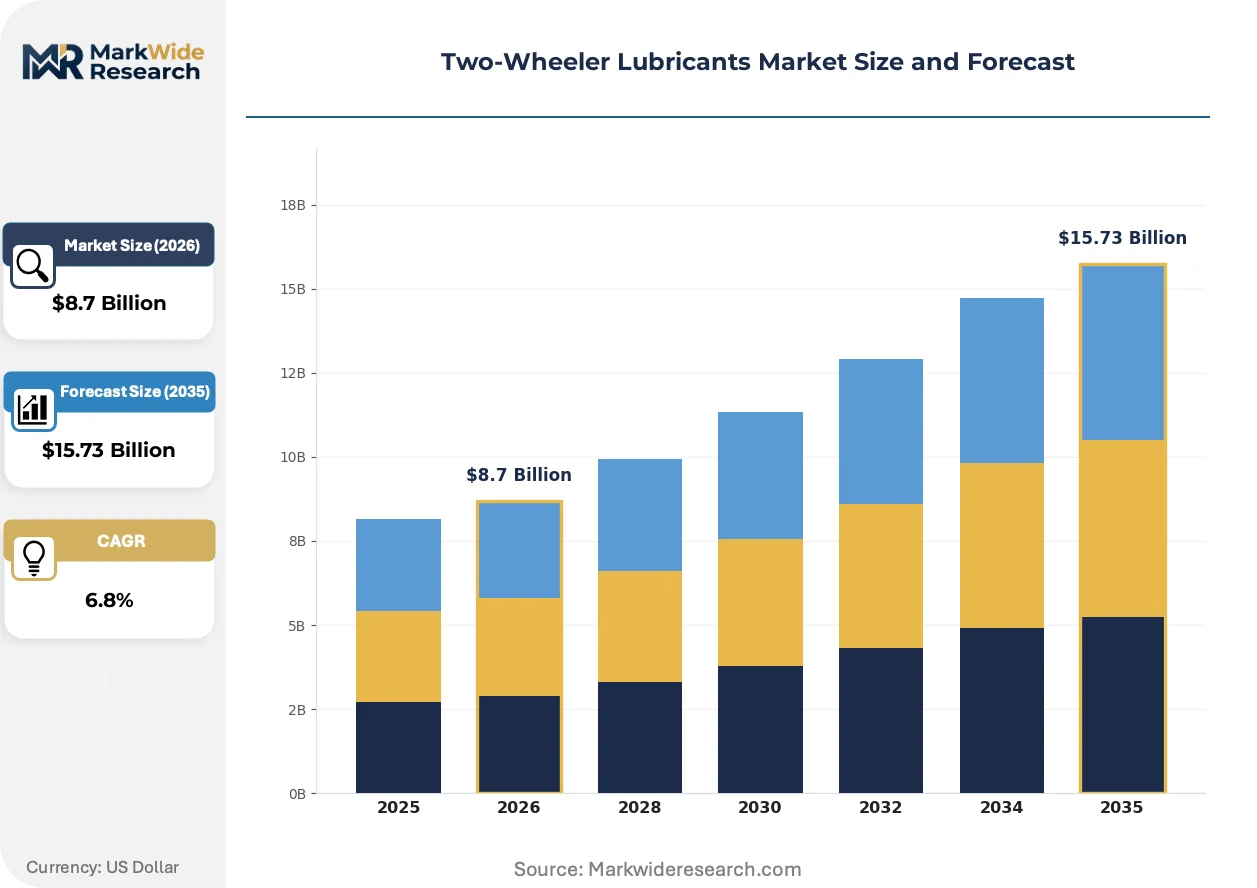
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Brake Fluid, Grease Application: Motorcycles, Scooters, Electric Bikes, Off-Road Vehicles Distribution Channel: Retail, Online, Direct Sales, Service Stations Formulation: Synthetic, Semi-Synthetic, Mineral, Biodegradable |
| Companies Covered | Shell PLC, Exxon Mobil Corporation, TotalEnergies, BP p.l.c., Castrol, Chevron Corporation, Petronas Lubricants International, Idemitsu Kosan Co., Ltd, Motul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Lubricants Market Evolving Landscape
Automated formulation testing and in-line blending controls are compressing product development cycles while real-time viscosity monitoring during motorcycle operation is enabling predictive maintenance business models. These shifts are reconfiguring how lubricant suppliers engage OEM engineering departments and fleet operators.
Artificial intelligence-driven tribology simulation is automating additive package optimization for specific engine architectures. Castrol and Shell's technical centers in Singapore and Bangalore are deploying machine learning models that predict wear scar formation under variable load conditions. This capability is automating the traditional test-bench iteration cycle and compressing OEM approval timelines from 18 months toward 9 months for derivative formulations.
India's BIS lubricant standards revision and Indonesia's SNI certification requirements are mandating deposit control and oxidative stability thresholds that exclude Group I base oils from premium motorcycle segments. The industrial consequence is accelerated capital expenditure toward hydrocracker and catalytic dewaxing capacity at regional refiners. Motorcycle OEMs including Honda and Yamaha are responding by specifying JASO T903:2021 friction certification for factory-fill and service-fill products across ASEAN markets.
Fleet procurement consolidation among Indonesian ride-hailing and delivery operators is displacing fragmented individual rider purchases with centralized lubricant supply agreements. Gojek and Grab's maintenance subsidiaries are negotiating direct blender contracts that bypass traditional multi-tier distribution. This pattern is most visible in Jakarta's metropolitan service zones where fleet density supports dedicated bulk fluid delivery infrastructure and on-site oil analysis programs.
Two-Wheeler Lubricants Market Segmentation
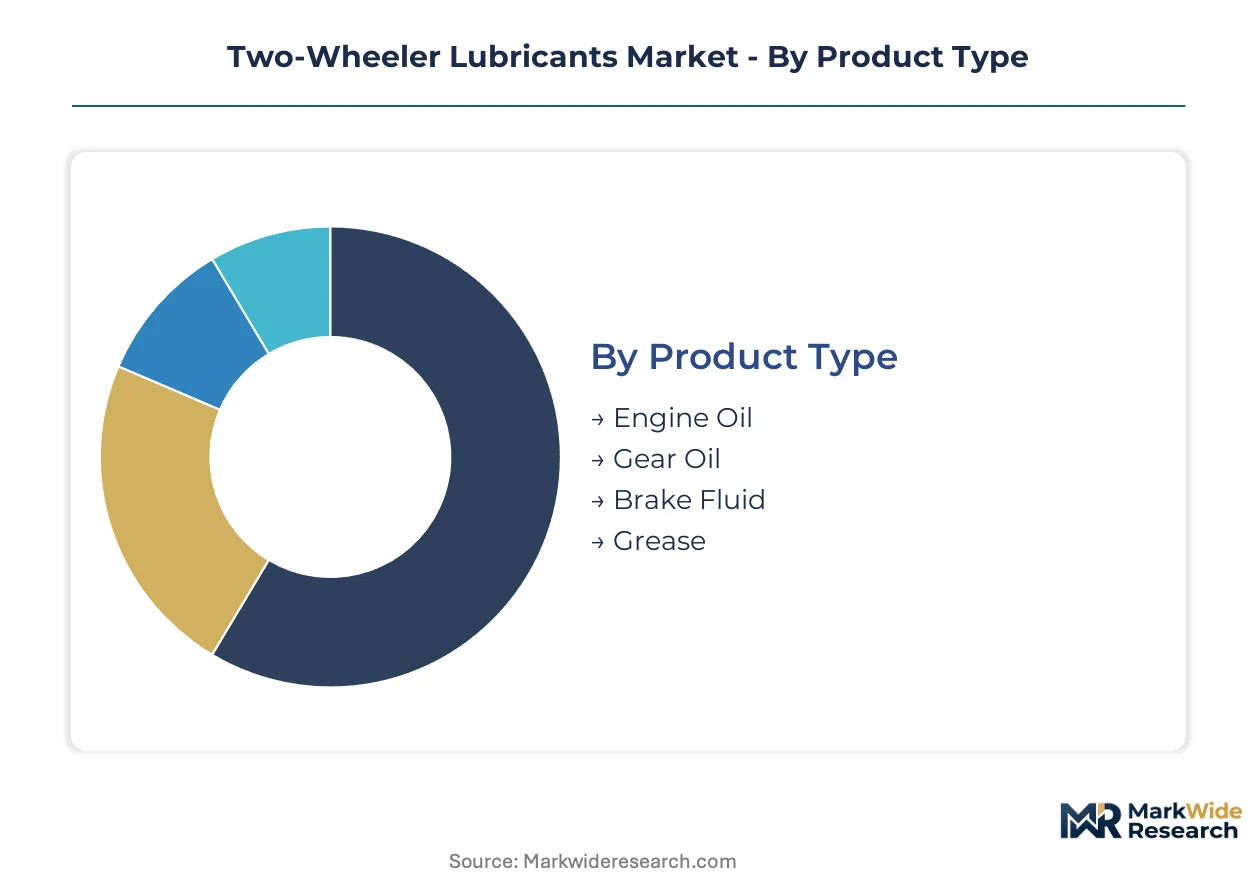
Two-wheeler lubricant suppliers configure product portfolios around OEM factory-fill specifications, regional climate demands, and evolving electrification requirements. Segmentation discipline determines which formulation investments capture margin pools versus commodity volume.
Product Type:
Supply concentration in engine oil manufacturing creates scale advantages for integrated refiners while niche lubricant categories remain fragmented among specialty blenders.
- Engine Oil:Formulated blends of Group II/III base oils with detergent-dispersant and anti-wear additive packages meeting JASO MA2 or API SN-plus specifications. Demand concentrates in Indonesia's Gojek and Grab fleet maintenance networks where 3,000-kilometer drain intervals sustain high throughput. OEM co-engineering agreements with Honda and Yamaha lock in factory-fill positions.
- Gear Oil:Hypoid gear lubricants with extreme-pressure additives protecting scooter CVT and motorcycle transmission components under high-torque loading. India's tier-two cities including Lucknow and Indore show rising scooter density without proportional service infrastructure, creating whitespace for branded gear oil distribution.
- Brake Fluid:Glycol-ether or silicone-based formulations meeting DOT 3/4/5.1 specifications for hydraulic brake systems.
- Grease:Lithium-complex or calcium-sulfonate thickened lubricants for wheel bearings, swing arms, and electric motor reduction gears.
Today's leader: Engine Oil. Tomorrow's challenger: Grease (electric powertrain bearing protection).
Application:
Cost tier differentiation separates premium synthetic formulations for high-displacement motorcycles from economy mineral oils for commuter scooters.
- Motorcycles:High-RPM air-cooled and liquid-cooled engines demanding thermal stability under stop-start urban traffic and sustained highway operation. Synthetic and semi-synthetic categories gain share as manufacturers specify longer service intervals. India's BIS certification mandates are eliminating substandard formulations from this segment.
- Scooters:Automatic CVT transmissions and enclosed engine designs with lower operating temperatures but higher contamination exposure from dust ingress. Indonesia's urban delivery network expansion in Jakarta and Surabaya concentrates fleet procurement of scooter-specific lubricants.
- Electric Bikes:Dielectric coolants and bearing greases formulated for battery thermal management and reduction gearbox protection. Requirements diverge entirely from internal combustion formulations.
- Off-Road Vehicles:High-dust-tolerance formulations with enhanced detergent packages for agricultural and recreational use.
Volume dominance: Scooters. Margin expansion: Electric Bikes.
Distribution Channel:
Customer type fragmentation between individual riders, fleet operators, and OEM service networks determines channel economics and working capital requirements.
- Retail:Branded quick-lube networks and independent spare parts shops serving individual motorcycle owners. India's tier-two urbanization creates whitespace for organized retail chains in Coimbatore and Indore.
- Online:E-commerce platforms and direct-to-consumer lubricant sales with convenience positioning. Growing fastest in metropolitan areas with established logistics infrastructure.
- Direct Sales:Bulk supply agreements between blenders and fleet operators bypassing traditional distribution tiers. Gojek and Grab maintenance subsidiaries in Indonesia negotiate direct blender contracts.
- Service Stations:OEM-authorized service centers with captive lubricant specifications and factory-fill obligations.
Incumbent strength: Service Stations. Disruption vector: Direct Sales.
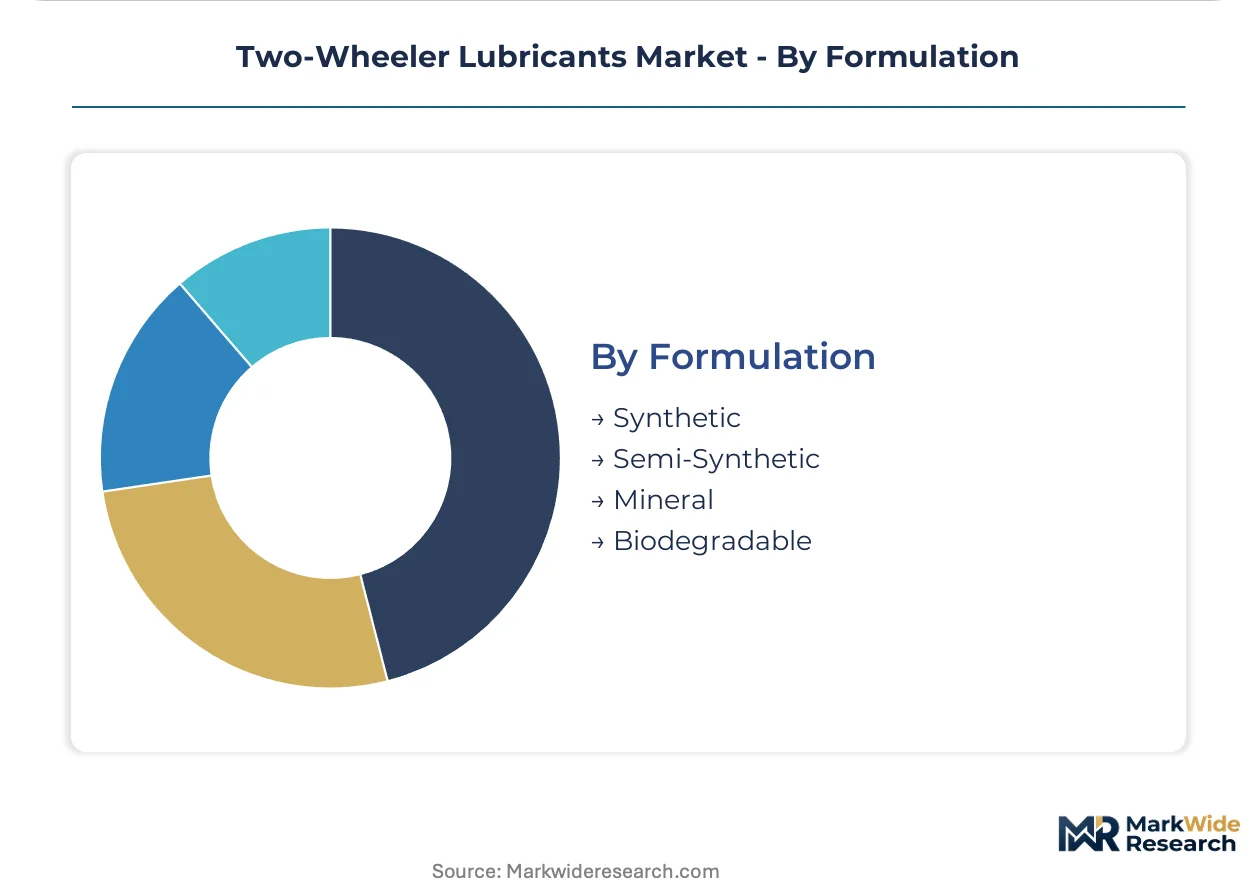
Formulation:
Maturity gradients separate established mineral oil infrastructure from capital-intensive synthetic upgrading investments.
- Synthetic:Group III and PAO base oils achieving 10,000-kilometer drain intervals with oxidative stability and low-temperature pumpability. OEM specification tightening across ASEAN manufacturers compresses qualification timelines toward synthetic adoption.
- Semi-Synthetic:Blends combining Group II base stocks with synthetic content for mid-tier pricing and 5,000-7,000 kilometer service intervals. Captures expanding share in India's BIS-compliant market as substandard mineral oils exit.
- Mineral:Group I base oil formulations with shorter drain intervals and lower price positioning. Concentrating in economy scooter segments and rural markets.
- Biodegradable:Vegetable oil or synthetic ester base stocks for environmentally sensitive applications and regulatory compliance.
Current margin pool: Synthetic. Volume transition zone: Semi-Synthetic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting lubricant blending capacity toward jurisdictions with harmonized ASEAN standards and away from markets with fragmented certification requirements. Singapore and Thailand capture investment flows due to converged industrial product standards, while Indonesia and Vietnam absorb cost pressures from import-dependent base oil supply chains.
India
Bureau of Indian Standards certification mandates are eliminating substandard mineral formulations from premium motorcycle segments. The PLI scheme for advanced chemistry cell manufacturing indirectly pressures lubricant blenders to align with cleaner technology trajectories. Mumbai-Pune industrial corridor hosts concentrated R&D facilities serving Honda and Yamaha factory-fill specifications.
Indonesia
SNI certification requirements and urban delivery network expansion are concentrating demand in Jakarta and Surabaya metropolitan zones. Gojek and Grab fleet procurement subsidiaries negotiate direct blender contracts that bypass traditional distribution tiers. The country's national standards body enforces deposit control thresholds that exclude Group I base oils from OEM-approved formulations.
Thailand
Industrial product standards alignment with ASEAN harmonized specifications is reducing multi-country formulation complexity for suppliers with domestic manufacturing presence. Board of Investment incentives attract hydrocracker capacity expansions serving regional Group II and Group III base oil demand. Rayong industrial estate anchors integrated refining and blending operations for export across mainland Southeast Asia.
Vietnam
Import duty exposure on Singapore and Thailand-sourced base oils creates margin pressure for independent blenders serving Ho Chi Minh City and Hanoi service networks. The country's national quality standards institute is drafting motorcycle lubricant specifications that will mandate JASO friction certification. Northern port infrastructure constraints fragment distributor warehousing economics for multi-grade inventory.
Japan
Ministry of Economy, Trade and Industry efficiency regulations and JIS standards shape high-performance synthetic formulation requirements for domestic OEMs. Idemitsu Kosan Co., Ltd anchors domestic supply while exporting specialized products to premium segments globally. Chubu region refining complexes maintain technical leadership in catalytic dewaxing capacity for ultra-low viscosity grades.
Two-Wheeler Lubricants Market Competitive Landscape
European and American majors anchor the premium synthetic tier; Japanese specialists hold technical leadership in friction certification standards. The market structure concentrates around integrated refiners with captive base oil supply and independent blenders with regional formulation agility. Three archetypes dominate: vertically integrated energy majors with ASEAN supply chain control, Japanese precision lubricant specialists with OEM co-engineering relationships, and regional independents competing on distributor reach. Competitive moves center on backward integration into Group II/III base oil capacity and strategic partnerships with fleet procurement platforms.
Among integrated energy majors, Shell PLC exemplifies supply chain control from Singapore refining through ASEAN distribution networks. Castrol occupies a position representing technical partnership archetypes with Indian and Indonesian OEM engineering departments. Idemitsu Kosan Co., Ltd sits within the Japanese specialist tier, anchoring high-performance synthetic expertise that extends beyond domestic boundaries.
| Leading Market Players |
|---|
| Shell PLC |
| Exxon Mobil Corporation |
| TotalEnergies |
| BP p.l.c. |
| Castrol |
| Chevron Corporation |
| Petronas Lubricants International |
| Idemitsu Kosan Co., Ltd |
| Motul |
| Others |
Value Network & Pricing Analysis
India's BIS certification mandates and Indonesia's SNI deposit control standards gate qualified supply for premium-tier lubricant pricing, forcing blenders toward Group II and Group III base oil investments that exclude substandard mineral formulations from factory-fill positions. OEM co-engineering agreements with Honda and Yamaha compress qualification timelines while rewarding integrated refiners with captive base oil supply and pricing power over independent distributors.
Pricing Analysis
Distributor margin compression in Indonesia's Gojek and Grab fleet procurement networks is displacing traditional multi-tier markups with direct blender contracts. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels separates JASO MA2-certified factory-fill products from service-fill alternatives, with brand premium and certification grade as primary differentiation drivers. Cost compression in economy mineral tiers is intensifying because India's BIS mandates eliminate substandard formulations, while fleet operators show lowest price sensitivity due to total cost of ownership focus on extended drain intervals.
Supply Chain Analysis
Single-source vulnerability sits with Singapore and Thailand for Group II and Group III base oil refining capacity, exposing Indonesian and Vietnamese blenders to freight cost volatility. Raw material dependencies center on hydrocracker feedstock, detergent-dispersant additive packages, and extreme-pressure chemistry for CVT applications. Tariff exposure on cross-border base oil movements fragments distributor warehousing economics for multi-grade inventory. Distribution runs through OEM-authorized service stations for factory-fill volumes, while direct bulk delivery serves consolidated fleet operators in Jakarta and Surabaya metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The two-wheeler lubricants market functions as a stable compounder anchored by OEM specification tightening that forces recurring formulation upgrades and captive supply relationships across Southeast Asian motorcycle manufacturing.
For Market Incumbents: Cement factory-fill positions through accelerated JASO T903:2021 friction certification investment ahead of ASEAN harmonization timelines. Deepen backward integration into Singapore or Thai hydrocracker capacity to secure Group III base oil supply against additive chemistry constraints from EPA emissions durability rules. Lock in multi-year direct supply agreements with Indonesian ride-hailing fleet subsidiaries before procurement consolidation completes. For New Entrants and Emerging Players: Launch via branded quick-lube networks in India's tier-two cities including Lucknow and Coimbatore where two-wheeler density rises without proportional service infrastructure. Target dielectric coolant formulation for electric scooter battery thermal management as OEMs finalize e-scooter platform designs. Penetrate through technical partnerships with Vietnamese distributors facing formulation chemist scarcity for JASO clutch friction standards. For Investors and Strategic Acquirers: Roll-up economics work for regional independent blenders with ASEAN distributor reach because OEM qualification timelines stretch R&D pipeline capacity beyond mid-cap balance sheets. Five-to-ten year viability rests on capturing fleet procurement consolidation and electric powertrain fluid specialization. Signal to watch: Thai Board of Investment hydrocracker capacity announcements indicating regional supply rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Capacity | Singapore and Thai hydrocracker investments secure supply against Indonesian import duty exposure. |
| JASO T903:2021 Friction Certification Acceleration | Honda and Yamaha factory-fill specifications across ASEAN markets demand qualified supply. |
| Direct Fleet Supply Agreement | Gojek and Grab maintenance subsidiaries bypass traditional distribution tiers in Jakarta. |
| Electric Powertrain Fluid R&D | Dielectric coolants for battery thermal management diverge from internal combustion formulations. |
| Tier-Two Quick-Lube Network Expansion | India's Coimbatore and Indore urbanization creates whitespace for organized retail chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant plant managers, OEM procurement leads at Honda and Yamaha, Indonesian fleet maintenance directors, and ASEAN distribution channel partners with secondary validation from customs trade data, BIS certification registries, SEC 10-K filings of integrated energy majors, and JASO standard documentation. Bottom-up volume modeling triangulated against top-down regional motorcycle fleet estimates.
Historical reference periods anchored the projection horizon to observed specification creep timelines and OEM co-engineering cycle compression. Segmentation dimensions modeled include formulation grade tier, application type across motorcycles scooters and electric bikes, distribution channel structure, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating base oil capacity expansion schedules and fleet procurement consolidation patterns.
Several conditions sit outside the modeled scope, including unannounced ASEAN harmonization timeline shifts, breakthrough electric two-wheeler battery chemistry eliminating thermal management fluid requirements, and trade policy restructuring affecting Singapore-Thailand base oil export duties. Forecasts reflect documented assumptions around OEM specification adoption rates and refinery capacity commissioning schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Transfer Case Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Electric Parking Brake Actuator Components Market