
 Automotive Data Cables Market | 2026-2036
Automotive Data Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Data Cables Market Intelligence
Asset-light manufacturing partnerships and contract electronics manufacturing services are rewriting capital requirements for cable suppliers entering the automotive data cable value chain. TE Connectivity leverages captive fiber drawing and copper metallurgy capabilities to sustain margin pools in high-speed shielded assemblies. Sumitomo Electric Industries anchors its position through backward integration into polymer compounding for heat-resistant jacketing materials.
Automotive data cables are engineered transmission media—typically 22-28 AWG copper conductors or multimode optical fibers with fluoropolymer or cross-linked polyethylene insulation—designed to maintain signal integrity across temperature extremes from minus 40 to 150 degrees Celsius while resisting electromagnetic interference in densely packed vehicle harnesses. Shielded cables dominate current revenue as OEMs prioritize electromagnetic compatibility for ADAS sensor networks, while fiber optic technology captures the fastest expansion as in-vehicle data throughput requirements exceed 10 Gbps for camera and lidar fusion architectures. Twisted pair configurations retain cost advantages in chassis control and powertrain signaling where bandwidth demands remain moderate.
NHTSA crashworthiness and electrical safety standards, ECE R10 electromagnetic compatibility regulations, and China's GB/T vehicle networking protocols collectively mandate verified cable performance across thermal cycling, vibration, and shielding effectiveness tests. The European Union's REACH and RoHS frameworks restrict halogenated flame retardants and heavy metals in cable jacketing compounds, forcing reformulation investments. Stakeholders must monitor how software-defined vehicle architectures redistribute cable content per platform and whether regional content requirements reshape supplier qualification pathways.
Market Dynamics
Software-defined vehicle architectures are redistributing cable content per platform as zonal computing consolidates sensor inputs and reduces point-to-point wiring runs. Tier-1 suppliers must requalify harness designs against shifting bandwidth specifications while maintaining backward compatibility with legacy controller networks.
Growth Catalysts
- NHTSA Advanced Driver Assistance System Mandates:Federal crash-avoidance requirements in the United States compel OEMs to deploy camera-radar fusion systems requiring shielded twisted pair and fiber optic assemblies rated for 10 Gbps throughput.
- Copper Raw Material Volatility:LME copper price swings above historical baselines compress margin pools for cable assemblers lacking metallurgical hedging instruments or captive smelter relationships.
- Polymer Compounding Concentration:Fluoropolymer resin supply concentrates among Japanese and German chemical producers, exposing harness manufacturers to allocation risk during semiconductor-driven automotive production surges.
Market Restraints
- Copper Raw Material Volatility:LME copper price swings above historical baselines compress margin pools for cable assemblers lacking metallurgical hedging instruments or captive smelter relationships.
- Polymer Compounding Concentration:Fluoropolymer resin supply concentrates among Japanese and German chemical producers, exposing harness manufacturers to allocation risk during semiconductor-driven automotive production surges.
- REACH Substance Restrictions:ECHA authorization requirements for halogenated flame retardants force reformulation of jacketing compounds, extending qualification timelines by 12-18 months for European-bound vehicle programs.
Strategic Opportunities
- India Production Localization:PLI scheme incentives for automotive electronics manufacturing create qualification pathways for cable suppliers establishing compounding and extrusion operations near Chennai and Pune assembly clusters.
- Centralized Zonal Gateway Architectures:Domain controller consolidation in premium electric vehicle platforms reduces harness complexity while elevating fiber optic content per vehicle for camera and lidar backhaul.
- China MIIT Vehicle Networking Standards:GB/T protocol mandates for intelligent connected vehicles accelerate domestic supplier certification programs, creating captive demand for shielded cable assemblies meeting electromagnetic compatibility test specifications.
Industry Challenges
- Signal Integrity Engineering Talent Scarcity:Specialized electromagnetic compatibility simulation and high-speed channel design skills concentrate among semiconductor and aerospace industries, forcing cable suppliers to recruit from adjacent sectors or build internal training academies.
- Platform-Specific Qualification Burden:OEM zonal architecture roadmaps diverge across Volkswagen Group, Toyota, and BYD ecosystems, requiring redundant validation cycles for common cable specifications against incompatible test protocols.
- Legacy Controller Network Integration:CAN-FD and Ethernet backbone coexistence demands hybrid harness designs bridging 500 kbps control traffic with multi-gigabit sensor fusion, complicating shielding effectiveness verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Data Cables Market |
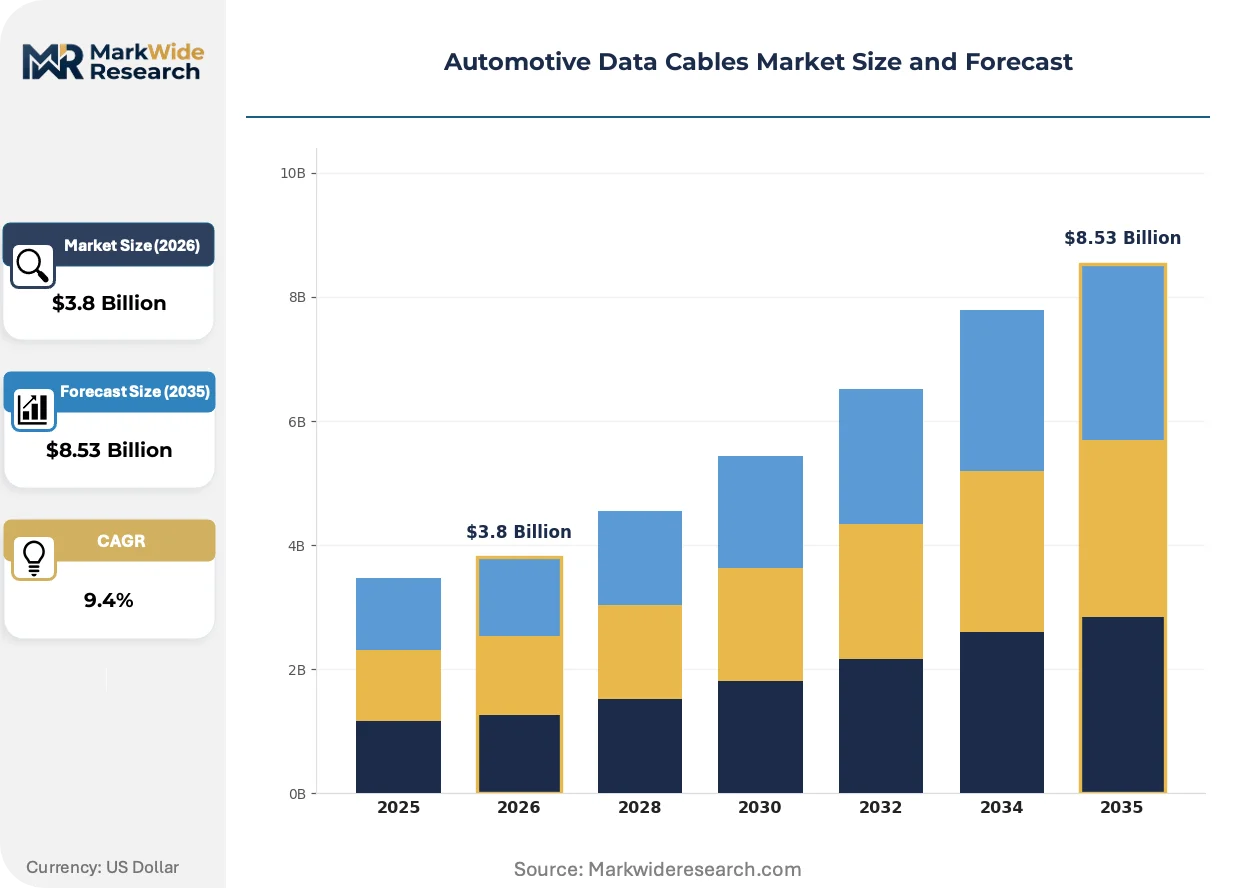
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shielded Cables, Coaxial Cables, Twisted Pair Cables, Ribbon Cables Technology: Fiber Optic, Copper Wire, Hybrid, Wireless Transmission Application: Infotainment Systems, Advanced Driver Assistance Systems, Telematics, Engine Control Units, Chassis Control End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers |
| Companies Covered | Sumitomo Electric Industries, Prysmian Group, Furukawa Electric, LEONI AG, Belden Inc., TE Connectivity, Yazaki Corporation, Amphenol Corporation, ACOME, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Data Cables Market Strategic Shifts & Innovations
Active optical cable assemblies are compressing harness mass and electromagnetic interference vulnerability as vehicle data architectures migrate from copper-centric to photonic transmission media. Tier-1 engineering teams now specify polymer optical fiber for infotainment backbones and glass fiber for safety-critical ADAS networks.
Polymer optical fiber with graded-index fluorinated cladding is rendering obsolete heavy copper coaxial runs for 4K display and audio distribution in luxury vehicle cabins. German OEM engineering centers specify active optical cables for seatback entertainment systems, reducing harness weight by 40% while eliminating ground loop interference. This photonic transition is compressing traditional copper assembly revenue pools in infotainment applications.
ECE R10 electromagnetic compatibility revisions tighten radiated emission limits for electric vehicle power electronics, forcing cable suppliers to redesign shielding termination methods. The regulation mandates improved transfer impedance performance across 150 kHz to 5 GHz frequency ranges. European premium OEMs now require double-shielded coaxial constructions for onboard charger and inverter control interfaces.
Consolidated procurement of cable assemblies by platform engineering teams is displacing decentralized commodity purchasing at individual plant levels. Volkswagen Group and Stellantis now mandate global harness specifications negotiated at headquarters level with approved supplier panels. This concentration is visible most acutely in Germany and the United States, where single-source contracts cover multiple vehicle architectures.
Automotive Data Cables Market Segmentation
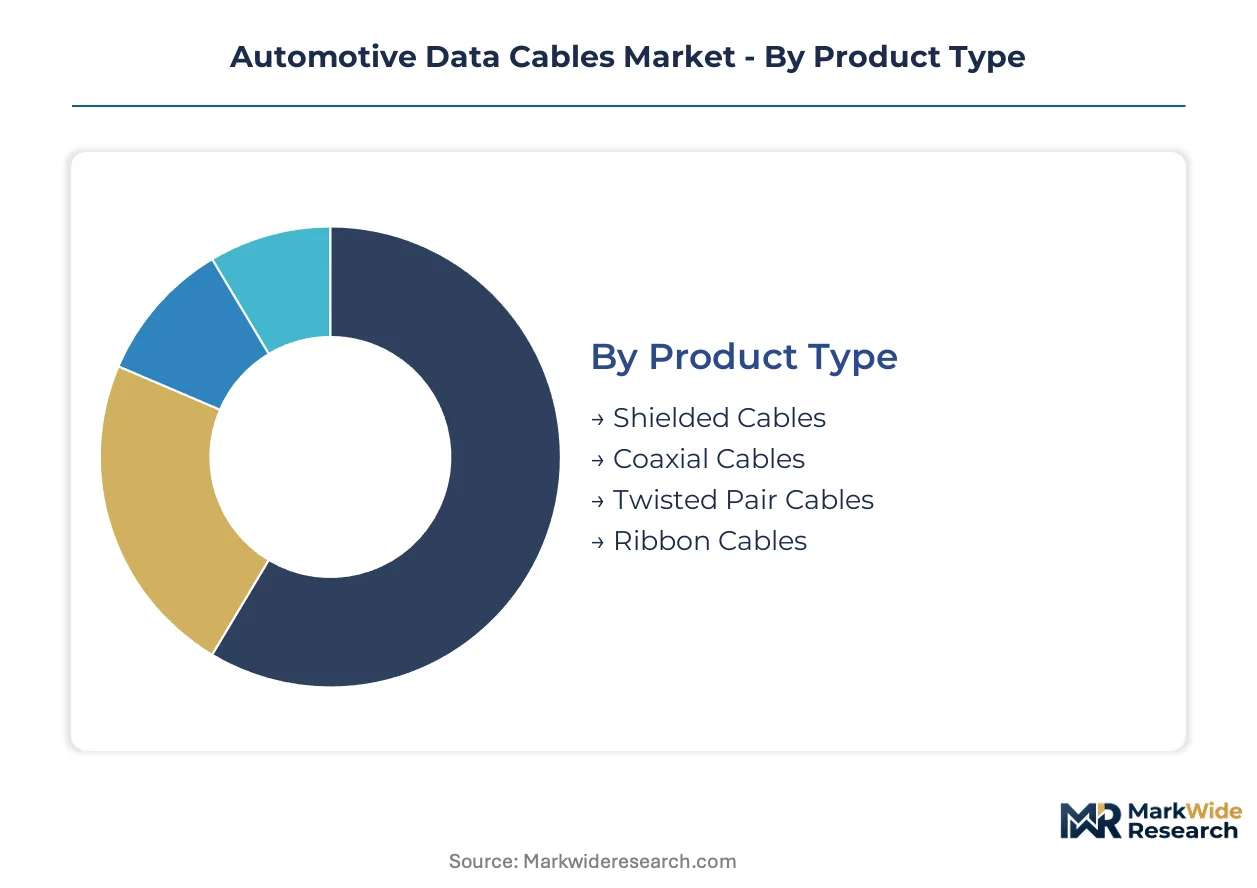
Automotive data cable segmentation reflects divergent technical requirements across vehicle domains. Shielding effectiveness, bandwidth headroom, and temperature resilience define procurement specifications for each application cluster.
Product Type:
Cost tier differentiation separates commodity harness components from precision-engineered transmission media for safety-critical networks.
- Shielded Cables:Multi-layer constructions with aluminum-polyester tape and tinned copper braid maintain electromagnetic compatibility across 150 kHz to 5 GHz. OEMs in Germany and the United States specify these for ADAS sensor fusion backbones where signal integrity failures carry liability exposure.
- Coaxial Cables:Central conductor with dielectric insulation and tubular shielding delivers controlled impedance for radio frequency applications. Infotainment antenna feeds and V2X communication modules in premium electric vehicle platforms drive procurement concentration.
- Twisted Pair Cables:Two insulated conductors twisted at precise pitch lengths cancel electromagnetic interference through common-mode rejection. Cost-sensitive chassis control and legacy CAN networks favor these configurations.
- Ribbon Cables:Parallel conductors laminated in flat flexible substrates enable high-density board-to-board connections within instrument cluster assemblies.
Shielded cables command the established base. The steepest expansion runs through coaxial variants for connected vehicle communication stacks.
Technology:
Application bandwidth requirements determine material selection between metallic and photonic transmission media.
- Fiber Optic:Glass or polymer optical fibers with fluorinated cladding transmit data via light pulses, eliminating electromagnetic susceptibility. Lidar and camera fusion architectures exceeding 10 Gbps in German premium OEM programs favor this technology.
- Copper Wire:Electrolytic copper conductors with cross-linked polyethylene insulation dominate established controller networks. Raw material volatility and proven reliability sustain its position in powertrain and body electronics.
- Hybrid:Combined copper-power and fiber-data elements within single jacketed assemblies reduce connector count in zonal gateway implementations. Stellantis and Volkswagen Group validation programs are accelerating qualification timelines.
- Wireless Transmission:Short-range radio frequency links for tire pressure monitoring and smartphone integration reduce harness mass in specific accessory applications.
Copper wire retains volume leadership across legacy platforms. Fiber optic technology is gaining share fastest in electric vehicle domain controller architectures.
Application:
Customer type concentration varies by vehicle system criticality and data throughput intensity.
- Advanced Driver Assistance Systems:Multi-gigabit shielded assemblies connect camera, radar, and lidar modules to central compute nodes. NHTSA federal mandates in the United States compel OEM deployment of these safety-critical networks.
- Infotainment Systems:Polymer optical fiber and high-speed copper pairs distribute 4K video and audio across cabin displays. German luxury OEM engineering centers specify active optical cables to reduce harness mass by 40 percent.
- Telematics:Cellular and satellite communication modules require ruggedized coaxial connections for antenna feeds in connected vehicle platforms.
- Engine Control Units:Temperature-resistant twisted pair and shielded cables maintain signal integrity across powertrain thermal cycling from minus 40 to 150 degrees Celsius.
- Chassis Control:Moderate-bandwidth CAN-FD networks for braking and steering systems prioritize cost efficiency over electromagnetic shielding sophistication.
Engine control applications anchor historical procurement volumes. Advanced Driver Assistance Systems demonstrate the steepest upward trajectory as regulatory mandates tighten.
End User:
Supply concentration patterns diverge between captive OEM operations and outsourced tier-1 manufacturing.
- OEMs:Volkswagen Group and Toyota maintain internal harness engineering centers that specify global cable standards and approved supplier panels. Consolidated procurement at headquarters level displaces plant-level commodity purchasing.
- Tier-1 Manufacturers:Delphi Aptiv and LEONI operate dedicated automotive cable assembly facilities with captive extrusion and termination capabilities. These suppliers manage qualification burden across incompatible OEM test protocols.
- Aftermarket Suppliers:Independent distributors service repair and retrofit demand for legacy vehicle electrical systems with standardized cable configurations.
- Vehicle Assemblers:Contract manufacturing partners in India and Mexico integrate cable harnesses during final assembly operations under OEM technical supervision.
Tier-1 manufacturers capture the dominant procurement share. The aftermarket channel is expanding most quickly as vehicle fleet age extends service intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and China's MIIT connectivity mandates are redistributing automotive data cable manufacturing capacity across established and emerging supply hubs. Regulatory divergence between NHTSA crash-avoidance requirements in the United States and ECE R10 electromagnetic compatibility rules in Europe forces suppliers to maintain parallel qualification pathways.
United States
NHTSA federal mandates for Advanced Driver Assistance Systems compel OEMs to deploy camera-radar fusion networks requiring 10 Gbps shielded assemblies. The Department of Transportation enforces FMVSS electrical safety standards that cable suppliers must validate against thermal cycling and vibration protocols. Detroit-area engineering centers specify global harness standards for Ford and General Motors platforms.
Germany
Premium OEM engineering centers in Munich and Stuttgart specify fiber optic backbones for lidar fusion architectures exceeding 10 Gbps throughput. ECE R10 electromagnetic compatibility revisions mandate improved transfer impedance performance across 150 kHz to 5 GHz frequency ranges. The KBA enforces type approval requirements that extend qualification timelines for European-bound vehicle programs.
China
MIIT vehicle networking standards under GB/T protocols accelerate domestic supplier certification programs for intelligent connected vehicles. The government's dual carbon goals pressure OEMs to reduce harness mass through polymer optical fiber adoption in premium electric vehicle platforms. Shanghai and Shenzhen anchor production volumes for BYD and NIO domain controller architectures.
India
PLI scheme incentives for automotive electronics manufacturing create qualification pathways for cable suppliers establishing compounding operations near Chennai and Pune assembly clusters. The BIS mandates compliance with IS standards for vehicle electrical systems. Tamil Nadu and Maharashtra host expanding harness integration facilities under OEM technical supervision.
Japan
METI technology roadmaps prioritize next-generation vehicle connectivity standards that elevate fiber optic content per vehicle. JIS standards govern cable performance across temperature extremes from minus 40 to 150 degrees Celsius. Toyota City and Nagoya engineering centers validate harness designs for global platform deployment.
Automotive Data Cables Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. Tier-1 harness manufacturers with captive extrusion capabilities capture consolidated procurement contracts from Volkswagen Group and Stellantis headquarters. Three archetypes dominate: vertically integrated metallurgy specialists, polymer compounding-anchored suppliers, and contract electronics manufacturing services. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships for zonal gateway qualification.
Among Japanese industrial conglomerates, Sumitomo Electric Industries and Furukawa Electric occupy positions representing metallurgical and optical fiber specialization archetypes. TE Connectivity exemplifies the channel-controlling tier through captive fiber drawing capabilities. German cable specialists LEONI AG and Prysmian Group anchor European supply positions against ECE R10 regulatory requirements. These named entities represent structural concentration rather than definitive market share claims.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Prysmian Group |
| Furukawa Electric |
| LEONI AG |
| Belden Inc. |
| TE Connectivity |
| Yazaki Corporation |
| Amphenol Corporation |
| ACOME |
| Others |
Cost & Logistics Intelligence
Japanese and German fluoropolymer resin producers concentrate supply for heat-resistant jacketing materials, anchoring margin pools with cable assemblers who lack captive compounding capabilities or long-term offtake agreements with polymer suppliers.
Pricing Analysis
Certification level against ECE R10 electromagnetic compatibility and NHTSA electrical safety standards creates the primary spread between premium and commodity tiers. Three-tier pricing structure across OEM-validated, Tier-1 approved, and aftermarket generic levels stratifies procurement contracts. Pricing pressure stems from LME copper volatility above historical baselines, compressing margin pools for assemblers without metallurgical hedging. Fleet operators and aftermarket distributors exhibit highest price sensitivity, while German premium OEMs prioritize shielding effectiveness over unit cost.
Supply Chain Analysis
Extended payment terms from Volkswagen Group and Stellantis headquarters procurement teams force Tier-2 cable assemblers to rely on supply-chain finance facilities or accept working capital strain. Manufacturing concentrates in Germany, China, and Japan, with Mexico and India expanding as final integration hubs. Raw material dependencies center on electrolytic copper cathodes, fluoropolymer resins, and glass optical fiber preforms. Single-source vulnerability runs through Japanese polymer compounding capacity during semiconductor-driven automotive production surges. Distribution runs through Tier-1 harness manufacturers with captive extrusion capabilities rather than direct OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive data cables function as a service-attach opportunity where qualification engineering and platform-specific validation services expand faster than commodity hardware margins. Recurring-revenue layers from requalification cycles and zonal architecture migration support are displacing one-time assembly sales.
For Market Incumbents: Pre-empt fiber optic qualification bottlenecks by securing captive polymer optical fiber drawing capacity before German premium OEMs consolidate approved supplier panels. Defend position against contract electronics manufacturing services by deepening backward integration into fluoropolymer compounding. Lock in multi-year metallurgical offtake agreements to neutralize copper price volatility exposure. For New Entrants and Emerging Players: Mid-market electric vehicle platforms in India represent the most penetrable entry point, as PLI scheme incentives reduce capital barriers for compounding and extrusion operations near Chennai assembly clusters. Target hybrid copper-fiber assemblies for Stellantis and Volkswagen Group zonal gateway validation programs where incumbent capacity constraints create qualification backlogs. Lead with engineering services rather than price to bypass entrenched Tier-1 relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cable assemblers lacking backward integration into resin compounding or fiber drawing. Long-term viability across the analysis window hinges on exposure to software-defined vehicle architectures elevating fiber content per vehicle. Monitor GB/T protocol certification velocity among domestic Chinese suppliers as the signal for when regional content requirements will reshape global supplier qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive fluoropolymer supply neutralizes Japanese-German allocation risk during production surges. |
| Fiber Optic Qualification Investment | ECE R10 revisions and 10 Gbps ADAS architectures mandate photonic transmission expertise. |
| India Manufacturing Footprint Expansion | PLI scheme incentives near Chennai and Pune reduce capital requirements for compounding operations. |
| Zonal Gateway Architecture Partnership | Domain controller consolidation in premium electric vehicles elevates hybrid assembly content. |
| REACH Compliance Reformulation | ECHA authorization timelines force 12-18 month qualification investments for European-bound programs. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution managers, and polymer compounding technical leads, then refined against secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed harness manufacturers, and customs trade records for copper and fluoropolymer flows. Bottom-up segment sizing across shielded, coaxial, twisted pair, and fiber optic categories was triangulated with top-down OEM procurement budget analysis.
Demand-supply balance modeling across the analysis window incorporated vehicle class stratification, propulsion architecture mix, content per vehicle trajectories, and regional production cluster shifts. Segmentation dimensions included product type, transmission technology, application domain, and end-user procurement channel. CAGRs were derived from regression analysis against ADAS penetration curves and regulatory mandate implementation timelines, with fiber optic share expansion calibrated to lidar fusion architecture roadmaps from German premium OEM engineering centers.
Macroeconomic conditions sit as an overlay; deviation in LME copper pricing, automotive semiconductor availability, or China-EU trade friction would shift the trajectory. Forecasts reflect documented assumptions about zonal architecture adoption rates and REACH substance restriction timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Brake Cables Market