
 Transmission Control System Market | 2026-2036
Transmission Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Control System Market Analysis
German Tier-1 suppliers is recalibrating production footprints across Europe and Asia to match electrified drivetrain demand. Continental AG leverages its integrated powertrain electronics portfolio to secure long-term OEM contracts. Robert Bosch GmbH sustains competitive advantage through in-house semiconductor sourcing for transmission modules. ZF Friedrichshafen AG anchors its position via dedicated manufacturing scale in precision mechatronic assemblies.
A transmission control system governs gear selection, clutch engagement, and torque converter lockup through sensor fusion, embedded software algorithms, and actuator command outputs operating at millisecond response intervals. Its primary purpose is to optimize fuel efficiency, reduce mechanical wear, and ensure drivability across varying load and speed conditions. Electronic control technology leads unit shipments due to mandatory integration with engine management and vehicle stability networks, while dual-clutch transmission architectures command the fastest growth trajectory among product types as performance-oriented passenger vehicles and commercial fleets prioritize shift-speed optimization. Hydraulic control retains dominance in heavy equipment applications where pneumatic alternatives face thermal reliability constraints.
EPA tailpipe regulations and NHTSA corporate average fuel economy standards in the United States compel OEMs to adopt multi-speed automatic transmissions with predictive shift logic. The EU Green Deal and F-Gas Regulation constrain refrigerant and lubricant chemistries used in transmission cooling circuits, altering component material specifications. Stakeholders must monitor how ISO 26262 functional safety mandates reshape software validation costs and supplier qualification timelines as electrified architectures converge with conventional transmission control domains.
Market Dynamics
The transmission control system market pivots on the convergence of electrified drivetrains and embedded software complexity, as automakers retool supply chains to serve hybrid architectures that blend mechanical gearboxes with electric motor management.
Growth Catalysts
- EPA Corporate Average Fuel Economy Standards:US OEMs deploy predictive shift algorithms and multi-speed automatic transmissions to meet tightening fleet efficiency mandates.
- Dual-clutch architectures:Performance passenger vehicles and commercial truck fleets prioritize sub-100-millisecond shift intervals for torque continuity.
- Software-defined vehicle platforms:Over-the-air update capability transforms transmission calibration from fixed hardware to iterative digital refinement.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea foundries constrain ECU output during capacity allocation cycles.
- Rare earth magnet dependency:Neodymium and dysprosium price volatility elevates actuator motor costs in precision mechatronic assemblies.
- ISO 26262 validation burden:Functional safety certification extends development timelines by 18-24 months for ASIL-D rated systems.
Strategic Opportunities
- India commercial vehicle electrification:BIS certification pathways and PLI scheme incentives attract module suppliers to local assembly.
- AI-driven predictive maintenance:Machine learning models trained on torque converter vibration signatures enable service revenue unbundling from hardware sales.
- EU Green Deal thermal regulations:F-Gas constrained cooling circuits create demand for dielectric fluid-compatible transmission control hardware.
Industry Challenges
- Embedded software talent scarcity:Real-time operating system engineers with automotive safety experience command premium compensation in Germany and Michigan.
- Legacy powertrain integration:Internal combustion architectures require backward-compatible control interfaces that complicate zonal E/E topology migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Control System Market |
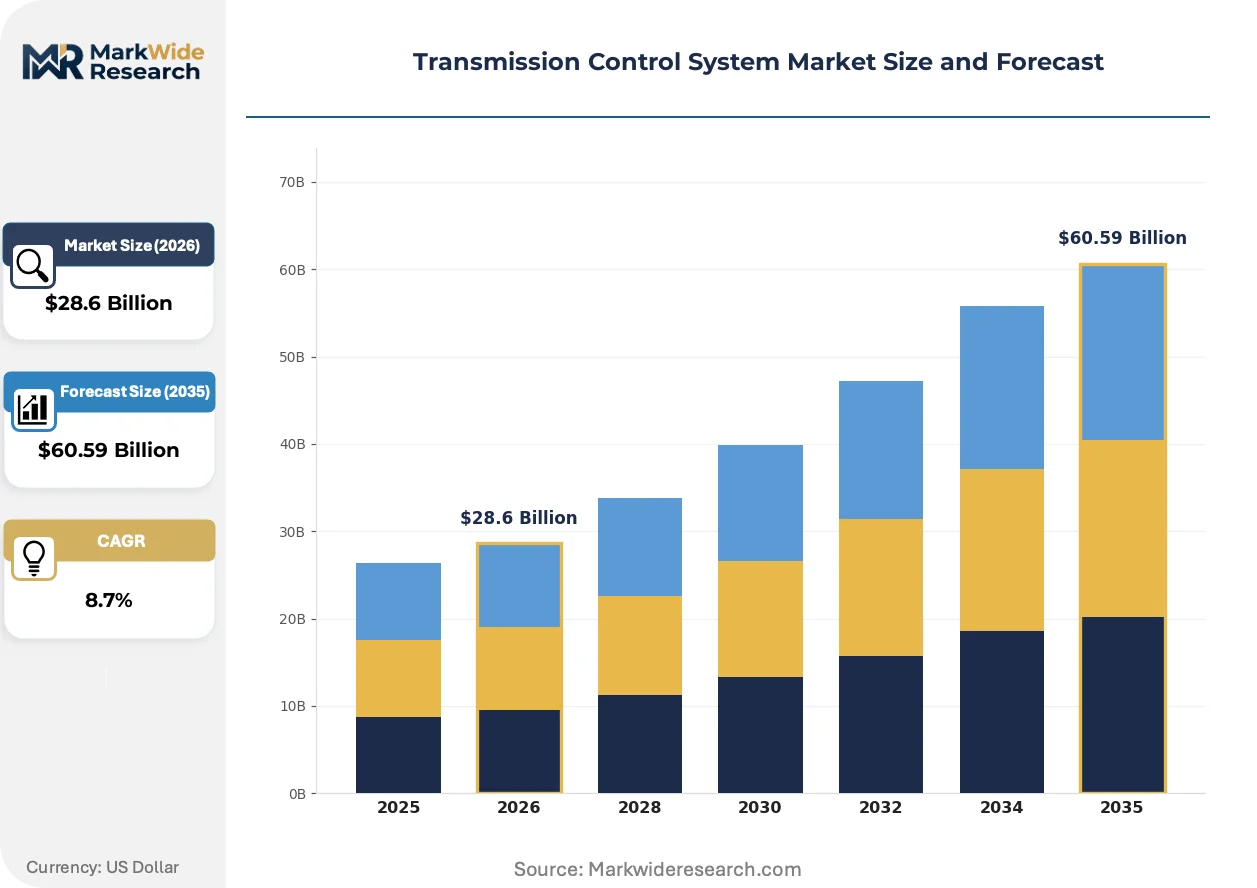
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transmission, Manual Transmission, Semi-Automatic Transmission, Dual-Clutch Transmission Technology: Electronic Control, Hydraulic Control, Mechanical Control, Pneumatic Control End User: Passenger Vehicles, Commercial Trucks, Motorcycles, Heavy Equipment Application: On-Road Vehicles, Off-Road Vehicles, Industrial Use, Agricultural Machinery |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Aisin Seiki Co., Ltd., Denso Corporation, Infineon Technologies AG, Eaton Corporation PLC, Delphi Technologies PLC, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Control System Market Emerging Trajectories
Software-defined functionality is absorbing hardware-bound features across the transmission control stack, compressing the traditional boundary between mechanical systems and digital platforms.
Silicon carbide power semiconductors is absorbing thermal management loads previously handled by liquid cooling circuits in high-torque EV transmissions. Commercial truck manufacturers in the US and Germany are qualifying SiC-based inverter modules for integrated e-axle applications. This displacement reduces cooling circuit complexity while extending peak power duration during grade hauling.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of transmission friction modifiers and seal elastomers across European supply chains. Compounders must validate alternative chemistries without degrading clutch plate engagement characteristics. German Tier-1 suppliers are accelerating in-house tribology testing to maintain OEM qualification timelines.
Fleet operators are consolidating procurement around full-lifecycle service agreements that bundle hardware, software licensing, and predictive maintenance. This model displaces transactional component purchasing in North American commercial vehicle channels. Long-haul trucking carriers now prioritize uptime guarantees over unit acquisition cost in vendor selection criteria.
Transmission Control System Market Segmentation
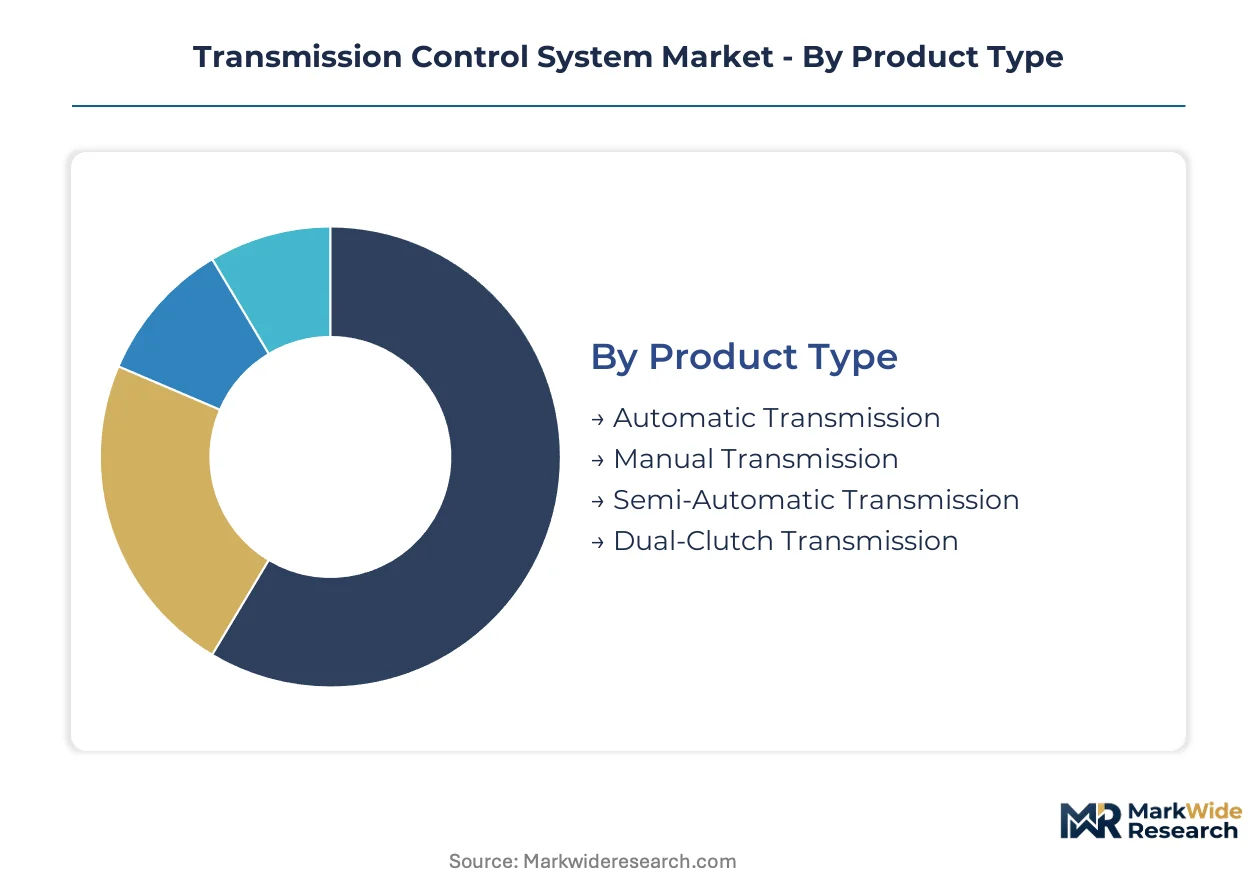
Transmission control system architectures vary dramatically in software complexity, sensor integration density, and actuator response protocols. Segment boundaries increasingly blur as electrified drivetrains force hybrid control strategies across traditional mechanical categories.
Product Type:
Standalone transmission units dominate replacement channels and legacy fleet retrofits, while embedded integrated systems anchor new vehicle production lines across passenger and commercial segments.
- Automatic Transmission:Torque converter-based architectures with planetary gear sets and electronic shift solenoids deliver seamless power delivery across urban duty cycles. Demand concentrates in US passenger vehicles where EPA fuel economy mandates favor eight-speed and ten-speed configurations over older four-speed designs.
- Dual-Clutch Transmission:Twin wet or dry clutch packs enable sub-100-millisecond gear changes through mechatronic actuator coordination. German performance passenger vehicles and North American commercial truck fleets prioritize this architecture for torque continuity during heavy load transitions.
- Manual Transmission:Driver-operated clutch and gear selector mechanisms persist in emerging market cost-sensitive segments and enthusiast vehicle niches.
- Semi-Automatic Transmission:Automated manual transmissions with electronic clutch actuation bridge cost and efficiency requirements in commercial vehicle applications.
Volume placements concentrate in Automatic Transmission; the faster expansion belongs to Dual-Clutch Transmission.
Technology:
Cost tiers separate premium electronic architectures from legacy hydraulic and mechanical alternatives, with pneumatic systems occupying a narrow heavy-equipment niche.
- Electronic Control:Microcontroller-based modules executing sensor fusion algorithms and real-time actuator commands at millisecond intervals. Embedded software validation under ISO 26262 functional safety mandates drives qualification costs upward for ASIL-D rated systems in passenger vehicles and commercial trucks.
- Hydraulic Control:Pressurized fluid circuits modulating clutch engagement through valve body spool positioning. Heavy equipment manufacturers in mining and construction retain this technology for thermal reliability under sustained high-torque operation.
- Mechanical Control:Cable and linkage systems without electronic intervention serve replacement markets and regulatory-exempt vehicle categories.
- Pneumatic Control:Compressed air actuation for clutch and gear selection in specific heavy-duty commercial applications with existing air brake infrastructure.
Revenue concentrates in Electronic Control; steepest expansion trajectory appears in Electronic Control as software-defined vehicle platforms proliferate.
End User:
Customer type determines calibration priorities, with passenger vehicles optimizing shift comfort against commercial trucks prioritizing durability under load.
- Passenger Vehicles:Multi-speed automatic and dual-clutch systems calibrated for fuel efficiency and drivability across variable urban and highway conditions. German and US OEMs integrate transmission control with engine management and stability networks as standard architecture.
- Commercial Trucks:Heavy-duty automated manual and automatic transmissions engineered for million-mile service intervals under sustained torque loading. Fleet operators in North America now contract full-lifecycle service agreements bundling hardware, software licensing, and predictive maintenance.
- Motorcycles:Compact electronic control modules for dual-clutch and quick-shift systems in performance and touring segments.
- Heavy Equipment:Hydraulic and electronic-hydraulic hybrid controls for excavators, loaders, and agricultural tractors requiring precision creep modes.
Unit volume concentrates in Passenger Vehicles; Commercial Trucks generate the highest revenue per installed system.
Application:
Operating environment dictates sealing specifications, thermal management requirements, and vibration resistance in transmission control hardware.
- On-Road Vehicles:Passenger cars, light trucks, and commercial vehicles operating on paved surfaces with standardized duty cycles. EPA and NHTSA regulations in the United States and EU Green Deal constraints in Europe shape control system specifications and software validation requirements.
- Off-Road Vehicles:Mining trucks, construction equipment, and military vehicles exposed to dust ingress, temperature extremes, and shock loading. Hydraulic control retention rates exceed electronic alternatives in these environments due to thermal reliability constraints.
- Industrial Use:Forklifts, port equipment, and material handling machinery with intermittent duty cycles and specialized safety interlocks.
- Agricultural Machinery:Tractors and harvesters requiring precision speed control for implement operation across variable terrain.
Production volume concentrates in On-Road Vehicles; Off-Road Vehicles command premium pricing for hardened environmental specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet deposits in China's Inner Mongolia and Jiangxi provinces anchor actuator motor supply chains for precision mechatronic assemblies serving transmission control module production.
United States
Commercial truck fleets in Michigan and Ohio accelerate adoption of electronic control modules for automated manual transmissions. EPA Corporate Average Fuel Economy standards and NHTSA safety mandates tighten hardware specifications for multi-speed automatic systems. Detroit's automotive engineering corridor concentrates Tier-1 supplier engineering centers and powertrain electronics validation facilities.
Germany
Performance passenger vehicle manufacturers prioritize dual-clutch transmission architectures with sub-100-millisecond shift intervals. EU Green Deal constraints and F-Gas Regulation alter cooling circuit material specifications for transmission control hardware. Stuttgart and Friedrichshafen host dedicated manufacturing scale in precision mechatronic assemblies and integrated powertrain electronics.
China
Domestic OEMs expand local sourcing of transmission control modules for hybrid and electrified drivetrain platforms. MIIT fuel consumption regulations and dual carbon goals accelerate multi-speed automatic transmission deployment. Shanghai and Yangtze River Delta clusters concentrate ECU assembly capacity and semiconductor packaging operations.
Japan
Automotive electronics specialists advance sensor fusion algorithms for torque converter lockup optimization. METI industrial policy supports domestic semiconductor fabrication for safety-critical automotive applications. Nagoya's Chubu region anchors precision manufacturing of mechatronic actuator components and embedded software development centers.
India
Commercial vehicle electrification drives module supplier interest in local assembly operations. BIS certification pathways and PLI scheme incentives attract powertrain electronics manufacturers. Tamil Nadu and Maharashtra industrial corridors concentrate automotive component manufacturing and emerging transmission control system integration facilities.
Transmission Control System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined vehicle platforms and AI-driven predictive maintenance services. The vendor base organizes around three structural tiers: integrated Tier-1 powertrain suppliers with captive semiconductor sourcing, specialized electronics manufacturers focused on microcontroller modules, and regional system integrators serving aftermarket replacement channels. Dominant competitive moves include strategic partnerships for over-the-air update capability and geographic expansion into India commercial vehicle electrification corridors.
Among Germany-based engineering conglomerates, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG exemplify the integrated Tier-1 archetype. Continental AG represents the diversified powertrain electronics portfolio approach. Robert Bosch GmbH occupies a position emphasizing in-house semiconductor sourcing capabilities. ZF Friedrichshafen AG anchors the precision mechatronic manufacturing scale segment within this tier.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Aisin Seiki Co., Ltd. |
| Denso Corporation |
| Infineon Technologies AG |
| Eaton Corporation PLC |
| Delphi Technologies PLC |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
ASIL-D certification tiers bifurcate transmission control module pricing into premium safety-validated systems and economy-grade alternatives, with this divergence manifesting in both unit economics and supply chain sourcing strategies across German engineering corridors and Taiwanese semiconductor channels.
Pricing Analysis
Warranty and predictive maintenance bundling separates full-lifecycle service agreements from transactional hardware sales in North American commercial truck procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and software update entitlements. Pricing pressure stems from semiconductor foundry allocation cycles constraining ECU output. Fleet operators exhibit highest price sensitivity for standalone replacement units, while OEMs prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai coordinate hub-and-spoke patterns for just-in-time delivery to powertrain assembly lines. Manufacturing concentrates in Germany, China, and the United States for precision mechatronic assemblies. Rare earth magnets from China's Inner Mongolia and Jiangxi provinces feed actuator motor production. Single-source vulnerability in Taiwan and South Korean foundry capacity poses structural risk. Distribution runs through Tier-1 supplier direct channels and authorized aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transmission control system market is accelerating into a vertical-integration race, with captive semiconductor sourcing and in-house mechatronic manufacturing emerging as decisive competitive levers.
For Market Incumbents: Anchor market position through backward integration into silicon carbide power semiconductor fabrication and dedicated ASIL-D software validation facilities. Defend against emerging software-defined vehicle entrants by locking long-term OEM platform engineering contracts. Prioritize capacity addition in India's Tamil Nadu corridor to capture commercial vehicle electrification incentives. For New Entrants and Emerging Players: Cloud-based calibration platforms offer a direct-channel route around incumbent hardware bundling. White-space targets include AI-driven predictive maintenance services for North American long-haul fleets and dielectric fluid-compatible modules for EU Green Deal compliance. Target India's BIS certification pathways with local assembly partnerships as the most penetrable geography. For Investors and Strategic Acquirers: Re-rating potential sits with specialized electronics manufacturers possessing ISO 26262 ASIL-D validation capabilities given NHTSA safety mandate tightening. Long-term viability favors suppliers with software-defined vehicle update architectures over pure hardware plays. Watch for fleet procurement consolidation around full-lifecycle service agreements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Integration | SiC power modules reduce cooling circuit complexity in high-torque EV transmissions serving US grade-hauling applications. |
| ASIL-D Software Validation Investment | Functional safety certification facilities in Germany and Michigan compress supplier qualification timelines for OEM contracts. |
| India Manufacturing Footprint Expansion | BIS certification and PLI scheme incentives attract module assembly for commercial vehicle electrification corridors. |
| Predictive Maintenance Platform Launch | Machine learning on torque converter vibration signatures unbundles service revenue from hardware sales. |
| EU Green Deal Thermal Compliance | F-Gas constrained cooling circuits create demand for dielectric fluid-compatible control hardware specifications. |
Methodological Framework
Independent corroboration across Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distributors underwrites the qualitative findings. Primary interviews with transmission control module engineering directors, semiconductor sourcing managers, and fleet maintenance heads combined with secondary validation from vehicle production databases, EPA regulatory filings, and IHS Markit registration data. Bottom-up unit shipment estimates and top-down value triangulation anchor the analytical framework.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, certification tier, and regional production cluster. CAGRs derive from regression analysis against historical adoption curves and regulatory mandate timelines. Forecast inputs incorporate EPA CAFE standard phase-in schedules and EU F-Gas Regulation implementation trajectories.
The model holds under stable semiconductor foundry capacity allocation and continued NHTSA safety mandate enforcement; deviation in rare earth magnet supply disruptions or ISO 26262 validation timeline extensions would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Engine Starter Market
Powertrain
Clutch Friction Plate Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Sway Bar Bushing Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Tuning Box Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Automotive Brake Booster Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
North America Precision Gearbox Market