
 Vehicle Intercom System Market | 2026-2036
Vehicle Intercom System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Intercom System Market Intelligence
Defense electronics manufacturing in Israel is restructuring intercom supply chains as Elbit Systems Ltd. leverages integrated battlefield management systems to anchor its position in armored vehicle platforms. Thales Group sustains technology leadership through advanced digital audio processing for crewed military vehicles. L3Harris Technologies, Inc. competes across NATO defense procurement channels with hardened communication architectures designed for electromagnetic-contested environments.
A vehicle intercom system comprises audio distribution electronics, crew control boxes, and helmet or headset interfaces operating across frequency ranges from 300 Hz to 3.4 kHz for intelligible speech transmission in high-noise vehicle cabins. These systems enable coordinated crew operations in military, emergency, and commercial transport applications where ambient noise exceeds 100 dB and radio isolation prevents acoustic feedback. Wired systems dominate current defense procurement due to electromagnetic hardening requirements and proven reliability in combat conditions, while wireless Bluetooth configurations are gaining traction in commercial fleet management where installation flexibility outweighs hardening priorities. Intercom over IP technology represents the fastest-growing architecture as military platforms migrate to Ethernet-based vehicle electronics standards that consolidate audio, data, and video traffic.
The U.S. Department of Defense mandates MIL-STD-461G electromagnetic compatibility and MIL-STD-810H environmental resilience for all vehicle intercom equipment, creating certification barriers that favor established defense suppliers over commercial entrants. The European Union's Radio Equipment Directive and CE marking requirements under the Electromagnetic Compatibility Directive govern civilian vehicle intercom deployments across member states, while EASA airworthiness standards extend to rotorcraft intercom applications. Stakeholders must monitor the divergence between military hardening specifications and commercial wireless standards as dual-use procurement strategies reshape supplier qualification pathways.
Market Dynamics
Military vehicle electronics migration toward Ethernet-based architectures is compressing procurement cycles for legacy analog intercom systems while opening certification pathways for IP-native suppliers.
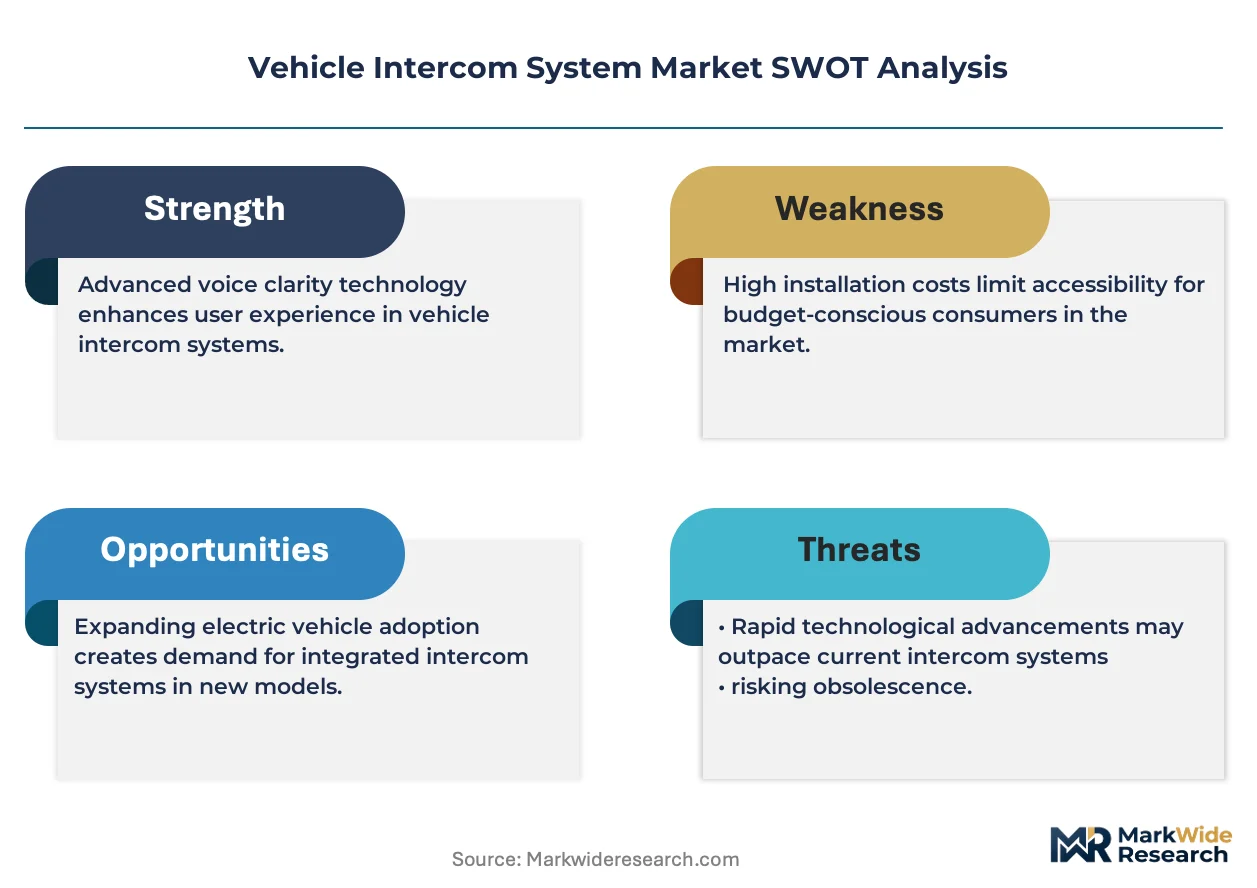
Growth Catalysts
- MIL-STD-810H environmental mandates:NATO defense ministries are mandating hardened digital suites for armored vehicle modernization programs, accelerating replacement of 1980s-era analog systems.
- Bluetooth Low Energy integration:Commercial fleet operators in logistics and mining are adopting wireless crew stations to reduce installation downtime and cabin wiring complexity.
- Germany's heavy armor procurement:The Bundeswehr's Puma and Leopard 2 upgrade contracts are specifying networked intercom nodes compatible with battlefield management systems.
Market Restraints
- Copper and rare earth magnet costs:Headset driver assemblies depend on neodymium supply chains concentrated in Chinese processing facilities, creating input price volatility.
- MIL-STD-461G certification barriers:Electromagnetic compatibility testing timelines of 18-24 months lock out commercial audio suppliers lacking defense contracting experience.
- Software-defined radio substitution:Integrated tactical radio units with embedded voice switching are displacing standalone intercom boxes in some light vehicle categories.
Strategic Opportunities
- Poland's mechanized brigade expansion:The Polish Ministry of National Defense is procuring over 1,000 new armored vehicles requiring NATO-interoperable digital intercom suites.
- RoHS exemption pathways:European defense procurement directives are creating regulatory carve-outs for lead-based solder in military electronics, preserving established manufacturing processes.
- Intercom-over-IP convergence:Audio distribution networks are merging with vehicle Ethernet backbones, enabling single-cable installation and remote diagnostics.
Industry Challenges
- Embedded software security clearance:Development teams require national security vetting to work on cryptographic voice processing modules, constraining talent pools.
- Legacy platform integration:Retrofit installations must interface with 30-year-old analog harnesses without degrading audio latency specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Intercom System Market |
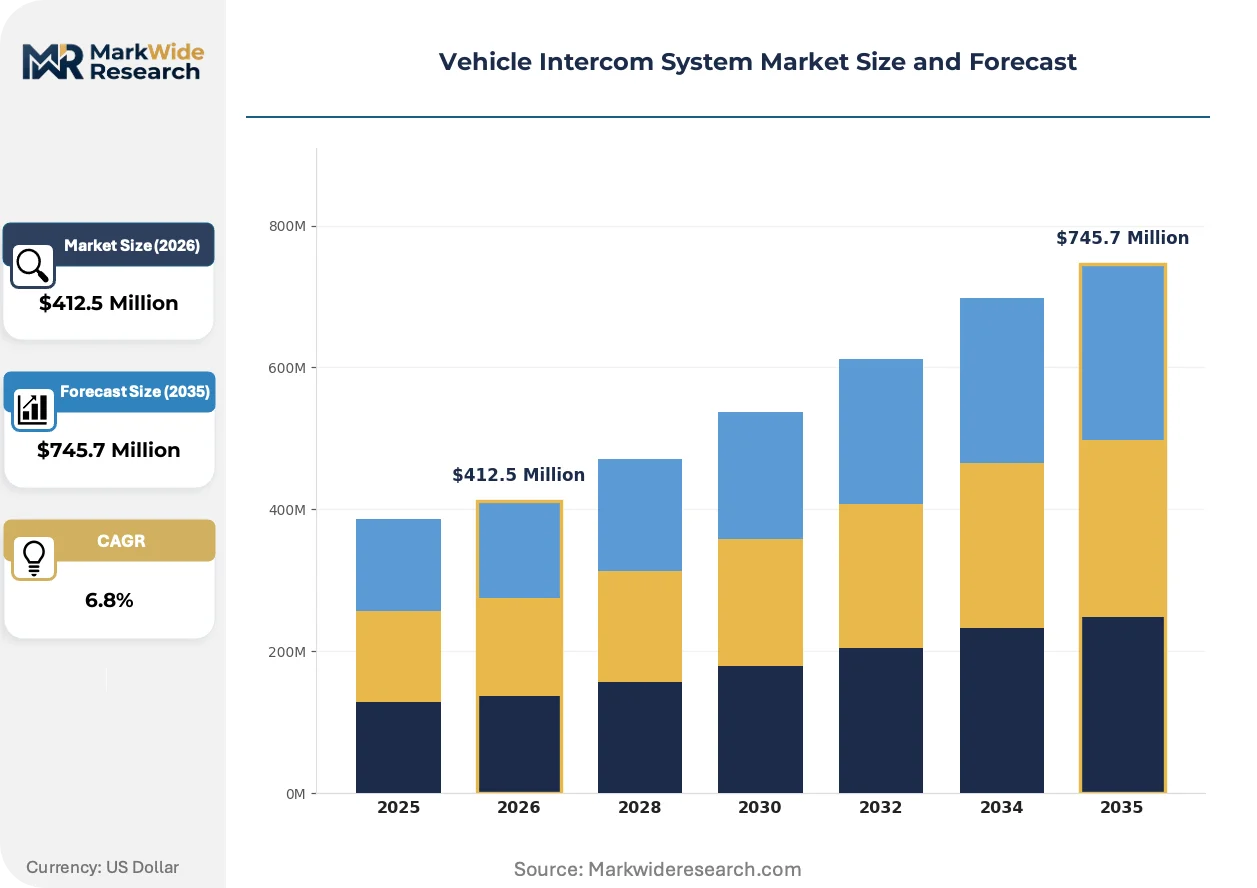
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Systems, Wireless Systems, Hands-Free Units, Portable Units End User: Commercial Vehicles, Emergency Vehicles, Personal Vehicles, Fleet Management Installation Type: OEM, Aftermarket, Custom Installation, Factory Installed Technology: Bluetooth, Intercom over IP, Analog, Digital |
| Companies Covered | L3Harris Technologies, Inc., Thales Group, Elbit Systems Ltd., Cobham Plc, David Clark Company, General Dynamics Mission Systems, Chelton Limited, INVISIO AB, Leonardo DRS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Intercom System Market Strategic Shifts & Innovations
Vehicle intercom architectures are pivoting from dedicated audio buses to shared Ethernet infrastructures, collapsing hardware layers while introducing cybersecurity and software lifecycle complexities.
Intercom-over-IP technology is absorbing functions previously handled by separate audio distribution units, crew control boxes, and radio interface modules. Military procurement offices in France and the United Kingdom are specifying IP-based systems for new armored vehicle programs. This convergence is absorbing middleware vendors into platform integrator supply chains while compressing margins for standalone hardware specialists.
The European Union's Radio Equipment Directive is tightening electromagnetic emission limits for vehicle-mounted communication hardware. CE marking requirements now extend to military-derived systems sold into dual-use emergency vehicle markets. German and French certification bodies are expanding testing scope to cover co-channel interference scenarios, forcing redesigns of power amplifier stages.
Defense procurement offices are consolidating vendor relationships around platform-level contracts rather than component sourcing. Thales Group and Elbit Systems are capturing intercom procurement through integrated battlefield management system awards. This bundling is most visible in NATO member state armored vehicle programs, where prime contractors now specify intercom performance as a subsystem requirement rather than procuring boxes separately.
Vehicle Intercom System Market Segmentation
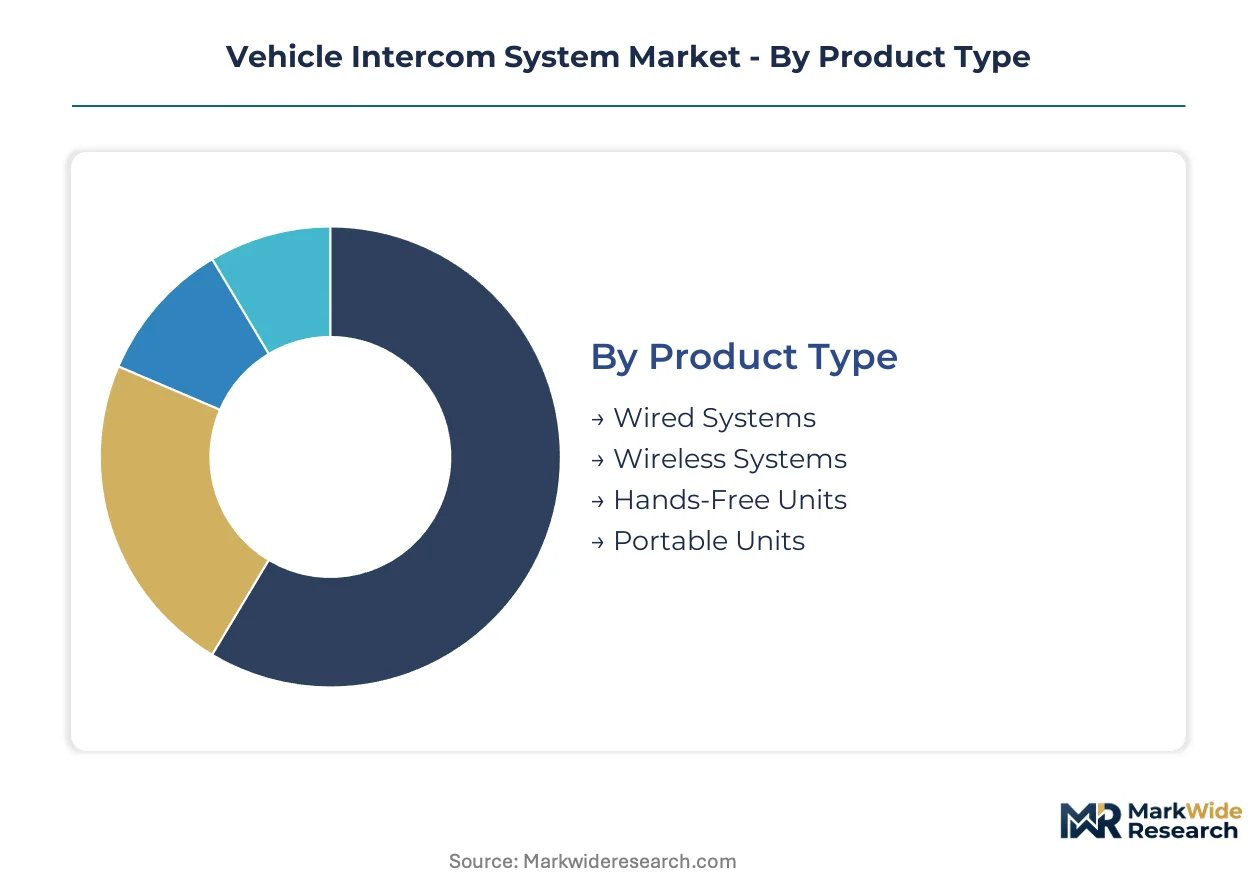
Vehicle intercom architectures diverge sharply between hardened military specifications and commercial fleet flexibility. Understanding where each segment sits on the reliability-versus-convenience spectrum shapes procurement strategy and supplier qualification pathways.
Product Type:
Wired systems command the premium tier through electromagnetic hardening and combat-proven reliability. Wireless configurations capture volume through installation speed and cabin reconfigurability.
- Wired Systems:Copper-based audio distribution with shielded harnesses meeting MIL-STD-461G electromagnetic compatibility requirements. NATO armored vehicle programs in Germany and France specify wired architectures for battlefield resilience against jamming and electromagnetic pulse events.
- Wireless Systems:Bluetooth Low Energy and proprietary radio links eliminating cabin harness runs. Mining and logistics fleet operators in Poland and the United Kingdom prioritize wireless crew stations to reduce vehicle downtime during retrofits.
- Hands-Free Units:Voice-activated microphone arrays with noise-canceling algorithms for high-decibel environments.
- Portable Units:Battery-powered intercom nodes for temporary vehicle assignments and training scenarios.
Mature deployment sits with wired systems. Newer deployment is concentrated in wireless systems.
End User:
Military and emergency applications drive specification intensity. Commercial transport emphasizes total cost of ownership and scalability across mixed fleets.
- Commercial Vehicles:Intercom systems for construction, agriculture, and heavy logistics where crew coordination reduces operational risk. German freight operators integrate intercom with fleet telematics platforms.
- Emergency Vehicles:Hardened audio distribution for fire apparatus, police armored vehicles, and medical evacuation platforms requiring radio isolation and priority override functions. French emergency vehicle procurement under CE marking directives is expanding dual-use military-derived systems.
- Personal Vehicles:Aftermarket intercom kits for recreational off-road and motorsport applications.
- Fleet Management:Centralized intercom provisioning across hundreds of vehicles with remote diagnostics and over-the-air configuration updates.
Specification intensity peaks in emergency vehicles. Fleet management is expanding most quickly as logistics operators consolidate vendor relationships.
Installation Type:
Factory integration locks in long-term supply agreements. Aftermarket channels reward installation speed and backward compatibility with legacy harnesses.
- OEM:Original equipment manufacturer contracts where vehicle primes specify intercom performance as a subsystem requirement. Thales Group and Elbit Systems capture this tier through integrated battlefield management system awards.
- Aftermarket:Retrofit installations for aging armored vehicle fleets and commercial fleet upgrades. Polish defense modernization programs are driving aftermarket demand as legacy platforms receive digital intercom suites.
- Custom Installation:Bespoke audio architectures for special mission vehicles and VIP protection details.
- Factory Installed:Line-fit intercom at vehicle assembly plants with standardized harness routing and quality verification protocols.
Revenue concentration favors OEM. Aftermarket is gaining share fastest as NATO armored vehicle fleets accelerate analog-to-digital replacement cycles.
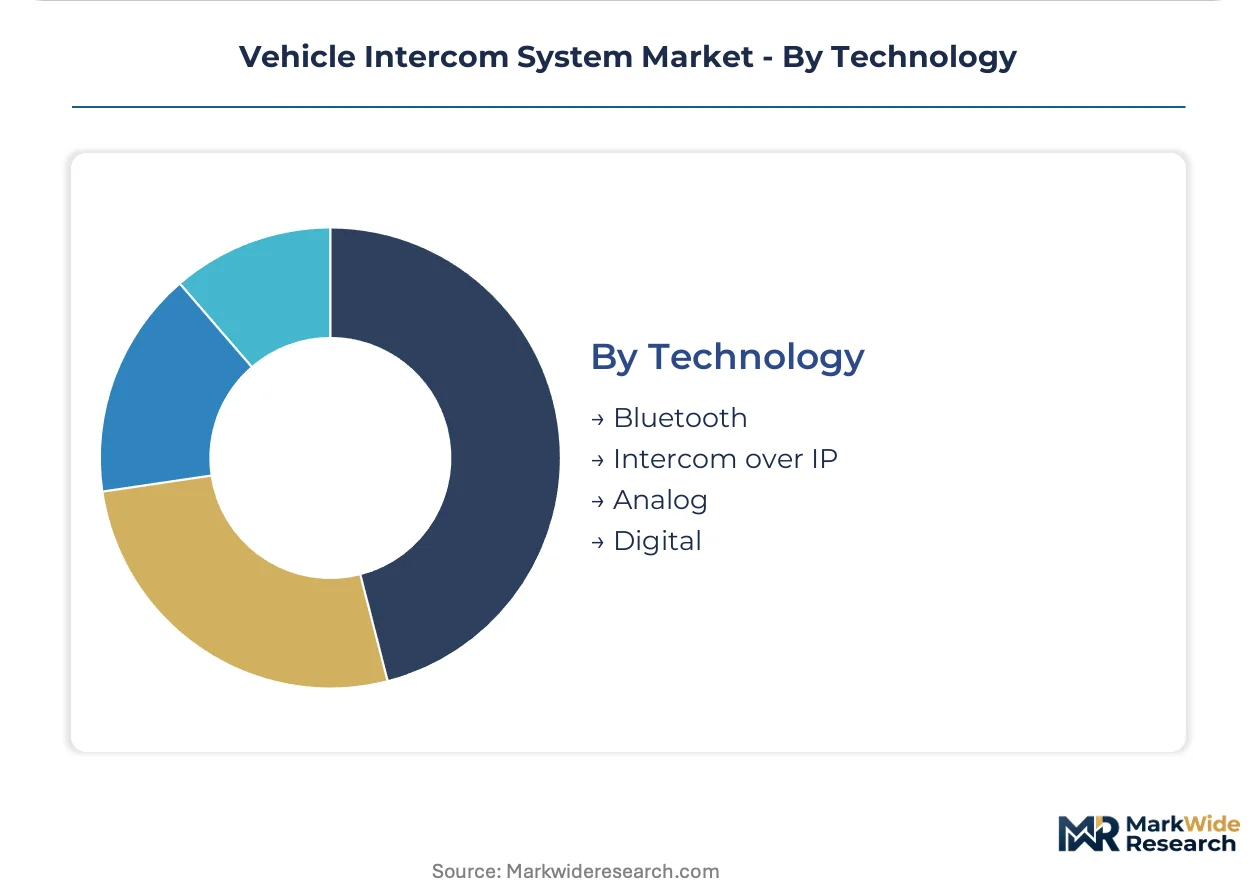
Technology:
Legacy analog maintains installed base inertia. Digital and IP-native architectures are collapsing hardware layers while introducing cybersecurity lifecycle requirements.
- Bluetooth:Short-range wireless audio links operating in the 2.4 GHz ISM band with AES-128 encryption for commercial fleet applications. United Kingdom logistics operators specify Bluetooth crew stations for driver flexibility without cabin rewiring.
- Intercom over IP:Ethernet-based audio distribution merging with vehicle backbone networks, enabling single-cable installation and remote diagnostics. French and British military procurement offices are specifying IP-native systems for new armored vehicle programs.
- Analog:Traditional copper-based audio buses with discrete component amplifiers, still specified for some legacy platform retrofits requiring minimal latency.
- Digital:Pulse-code modulation and adaptive differential pulse-code modulation architectures with digital signal processing for noise reduction.
Installed base inertia protects analog. Intercom over IP represents the steepest expansion trajectory as vehicle electronics migrate to Ethernet standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet processing facilities in China supply critical headset driver components, yet defense procurement mandates in NATO member states are redirecting final assembly and system integration toward European and North American manufacturing clusters.
Germany
The Bundeswehr's Puma IFV and Leopard 2 upgrade programs are driving procurement of networked digital intercom nodes compatible with battlefield management systems. KBA vehicle certification requirements and EU Radio Equipment Directive compliance govern dual-use emergency vehicle deployments. Defense electronics manufacturing concentrates in Bavaria and Baden-Württemberg, where primes integrate intercom subsystems into armored vehicle platforms.
United States
The Department of Defense mandates MIL-STD-461G electromagnetic compatibility and MIL-STD-810H environmental resilience for all vehicle intercom equipment, creating 18-24 month certification timelines. FCC equipment authorization applies to commercial fleet Bluetooth configurations. Defense contracting clusters in Virginia and Texas anchor hardened system production for armored vehicle modernization programs.
France
ANSM and military procurement offices are specifying IP-native intercom architectures for new armored vehicle programs under SCORPION modernization. CE marking under the Electromagnetic Compatibility Directive extends to military-derived emergency vehicle systems. The Île-de-France and Provence-Alpes-Côte d'Azur regions host Thales Group integration facilities for NATO interoperable platforms.
Poland
The Ministry of National Defense is procuring over 1,000 new armored vehicles requiring NATO-interoperable digital intercom suites for mechanized brigade expansion. National security vetting requirements constrain development teams working on cryptographic voice processing modules. Industrial activity clusters around Warsaw and Poznań for retrofit installations on legacy platforms.
United Kingdom
EASA airworthiness standards extend to rotorcraft intercom applications while logistics operators specify Bluetooth crew stations for commercial fleet flexibility. The Electromagnetic Compatibility Directive governs civilian deployments. Defense electronics manufacturing in the Midlands and Southwest England focuses on analog-to-digital replacement cycles for aging armored vehicle fleets.
Vehicle Intercom System Market Key Industry Players
Global majors compete with regional champions across defense contracting channels and certification pathways. The vendor structure tiers between electromagnetic-hardening specialists with MIL-STD pedigree and commercial audio suppliers seeking dual-use qualification. Three archetypes dominate: platform integrators capturing subsystem awards, component specialists defending hardware margins, and IP-native entrants exploiting Ethernet convergence. Competitive moves center on strategic partnerships with vehicle primes and portfolio diversification into adjacent battlefield management systems.
Within the platform integrator tier, Thales Group and Elbit Systems Ltd. occupy positions as anchors for NATO armored vehicle procurement, while L3Harris Technologies, Inc. represents the hardened architecture specialist archetype for electromagnetic-contested environments. These entities exemplify how defense contracting consolidation around vehicle-level awards is absorbing standalone intercom vendors into broader battlefield electronics supply chains.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| Cobham Plc |
| David Clark Company |
| General Dynamics Mission Systems |
| Chelton Limited |
| INVISIO AB |
| Leonardo DRS, Inc. |
| Others |
Cost & Logistics Intelligence
Intercom-over-IP technology migration is simultaneously collapsing hardware layer counts and concentrating procurement leverage around platform integrators with Ethernet-native engineering capabilities. This shift rewards vendors that control battlefield management system integration while squeezing margins for standalone audio hardware specialists.
Pricing Analysis
Extended warranty and field service bundling separate premium-tier defense contracts from unbundled commercial fleet transactions. Three-tier pricing structure across MIL-STD-certified, dual-use emergency, and standard commercial levels reflects certification investment recovery timelines. Cost compression in commercial Bluetooth configurations is intensifying because logistics operators prioritize installation speed over electromagnetic hardening. Fleet management buyers exhibit highest price sensitivity, while NATO defense ministries accept premium positioning for combat-proven reliability.
Supply Chain Analysis
Direct-to-OEM channels handle platform-integrator procurement for armored vehicle programs, while aftermarket distributors serve retrofit installations on legacy fleets. Neodymium magnet processing concentrates in China, with final assembly clusters in Germany, France, and the United States. Headset driver assemblies and shielded copper harnesses anchor component dependencies. Single-source vulnerability in rare earth processing creates tariff exposure risk. Distribution runs through defense primes for military contracts and specialized audio distributors for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification capacity constraints for MIL-STD-461G electromagnetic compatibility testing prop pricing power for established defense suppliers with approved laboratory relationships.
For Market Incumbents: Cement platform-level contract capture by deepening integration with battlefield management system architectures. Invest in cryptographic voice processing module development to defend against software-defined radio substitution threats. Secure national security vetting for engineering teams to constrain competitor talent access. For New Entrants and Emerging Players: Capture aftermarket retrofit demand in Poland and the United Kingdom where aging armored vehicle fleets require analog-to-digital intercom upgrades. Commercial fleet Bluetooth configurations offer the most penetrable entry path. Pursue CE marking qualification under the Electromagnetic Compatibility Directive as a go-to-market foundation. For Investors and Strategic Acquirers: Exit pathways concentrate in platform integrator acquisitions by defense electronics majors. Five-to-ten year viability favors vendors with IP-native Ethernet capabilities and NATO interoperability certifications. Monitor Bundeswehr and Polish Ministry of National Defense procurement award timing as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-461G Certification Investment | Locks out commercial audio suppliers lacking defense contracting experience for 18-24 month testing timelines. |
| Intercom-over-IP Platform Integration | Enables Thales Group and Elbit Systems to capture subsystem awards through battlefield management bundling. |
| Bluetooth Low Energy Crew Station Deployment | Reduces vehicle downtime for United Kingdom logistics operators prioritizing installation flexibility. |
| Neodymium Supply Chain Diversification | Mitigates Chinese processing concentration risk for headset driver assembly cost stability. |
| RoHS Exemption Pathway Utilization | Preserves lead-based solder manufacturing processes under European defense procurement carve-outs. |
Research Approach
Multi-period observation of NATO defense procurement awards, commercial fleet telematics integration rates, and electromagnetic compatibility certification timelines anchored the trend analysis, supplemented by interviews with platform integration engineers, defense procurement officers, fleet operations managers, and aftermarket distribution specialists. Secondary validation drew from MIL-STD documentation, EU Radio Equipment Directive filings, Bundeswehr equipment schedules, and customs trade records for neodymium magnet flows. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Segment-weighting across wired, wireless, and IP-native architectures combined with end-user stratification by military, emergency, and commercial applications shaped the analytical framework. Deployment model, certification tier, and regional procurement cluster dimensions structured the modeling approach. CAGRs derived from installation base replacement cycles and new platform introduction schedules. Voice-activated noise-canceling algorithm adoption and Ethernet backbone penetration served as technology diffusion inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to defense budget reallocation, rare earth export restriction events, and software-defined radio displacement velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market