
 Automotive Head-Up Display (HUD) and Instrument Cluster Market | 2026-2036
Automotive Head-Up Display (HUD) and Instrument Cluster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Head-Up Display (HUD) and Instrument Cluster Market Insights
Project finance and operational leasing for automotive display production lines is reconfiguring competitive entry barriers, allowing capital-light suppliers to secure capacity without owning fabs. Robert Bosch GmbH leverages its captive semiconductor sourcing to anchor display module production in Europe. Panasonic Holdings Corporation competes through vertical integration into OLED backplane manufacturing. Nippon Seiki Co. Ltd. specializes in optical waveguide designs that dominate Japanese OEM supply chains.
Automotive Head-Up Display and Instrument Cluster systems combine transparent combiner optics, TFT-LCD or OLED microdisplays, and vehicle-network interfaces to project speed, navigation, and ADAS alerts within the driver's forward field of view. Manufacturing employs precision injection-molded polycarbonate waveguides, vacuum-bonded display stacks, and anti-reflective coatings to achieve luminance levels exceeding 15,000 cd/m² for daylight readability. Augmented Reality HUD commands the premium tier due to holographic overlay complexity and sensor fusion requirements, while Digital Instrument Cluster volumes are accelerating as OEMs phase out electromechanical gauges. LCD technology sustains the volume base across mid-range vehicles, whereas OLED is displacing legacy architectures in luxury platforms where contrast ratio and form factor flexibility justify cost premiums.
The EU AI Act and UNECE WP.29 cybersecurity regulations are mandating functional safety certification for connected cockpit displays, reshaping supplier qualification timelines. NHTSA guidelines on driver distraction limit field-of-view placement and information density for HUD systems sold in the United States. China's MIIT enforces GB standards for electromagnetic compatibility that govern display module integration with vehicle antenna systems. Stakeholders must monitor divergence between regional certification regimes when allocating R&D budgets across platform generations.
Market Dynamics
AR HUD systems are compressing development cycles as premium electric vehicle platforms demand holographic overlays fused with real-time sensor data, forcing suppliers to requalify optical stacks under accelerated timelines.
Growth Catalysts
- EU AI Act compliance mandates:Functional safety certification for connected cockpit displays is creating captive demand for pre-certified module suppliers.
- Electromechanical gauge phase-outs:OEMs across Germany, Japan, and the United States are retiring analog instrument clusters in favor of full-digital architectures.
- OLED microdisplay luminance thresholds:Advances in emissive pixel density are enabling daylight-readable HUD projections without auxiliary boost optics.
Market Restraints
- Polycarbonate optical substrate concentration:Precision waveguide manufacturing depends on injection-molding capacity concentrated in East Asian tooling networks.
- Vacuum-bonded display stack yield rates:Anti-reflective coating lamination remains a throughput bottleneck with scrap rates above acceptable thresholds.
- NHTSA field-of-view restrictions:Driver distraction guidelines limit information density and placement geometry for HUD systems in the United States market.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Localized display module assembly incentives are opening import-substitution pathways for tier-2 suppliers.
- Sensor fusion integration:Convergence of lidar point clouds with AR HUD rendering engines is creating new software licensing revenue pools.
- Aftermarket retrofit channels:Authorized dealer networks in China are beginning to stock HUD upgrade kits for legacy internal combustion platforms.
Industry Challenges
- Optical design talent scarcity:Waveguide simulation expertise resides in a narrow pool of specialists trained on proprietary ray-tracing platforms.
- UNECE WP.29 cybersecurity recertification:Connected instrument clusters require revalidation with each firmware update, compressing release cycles.
- Legacy vehicle network protocol fragmentation:HUD integration demands translation layers between modern Ethernet backbones and aging CAN bus architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Head-Up Display (HUD) and Instrument Cluster Market |
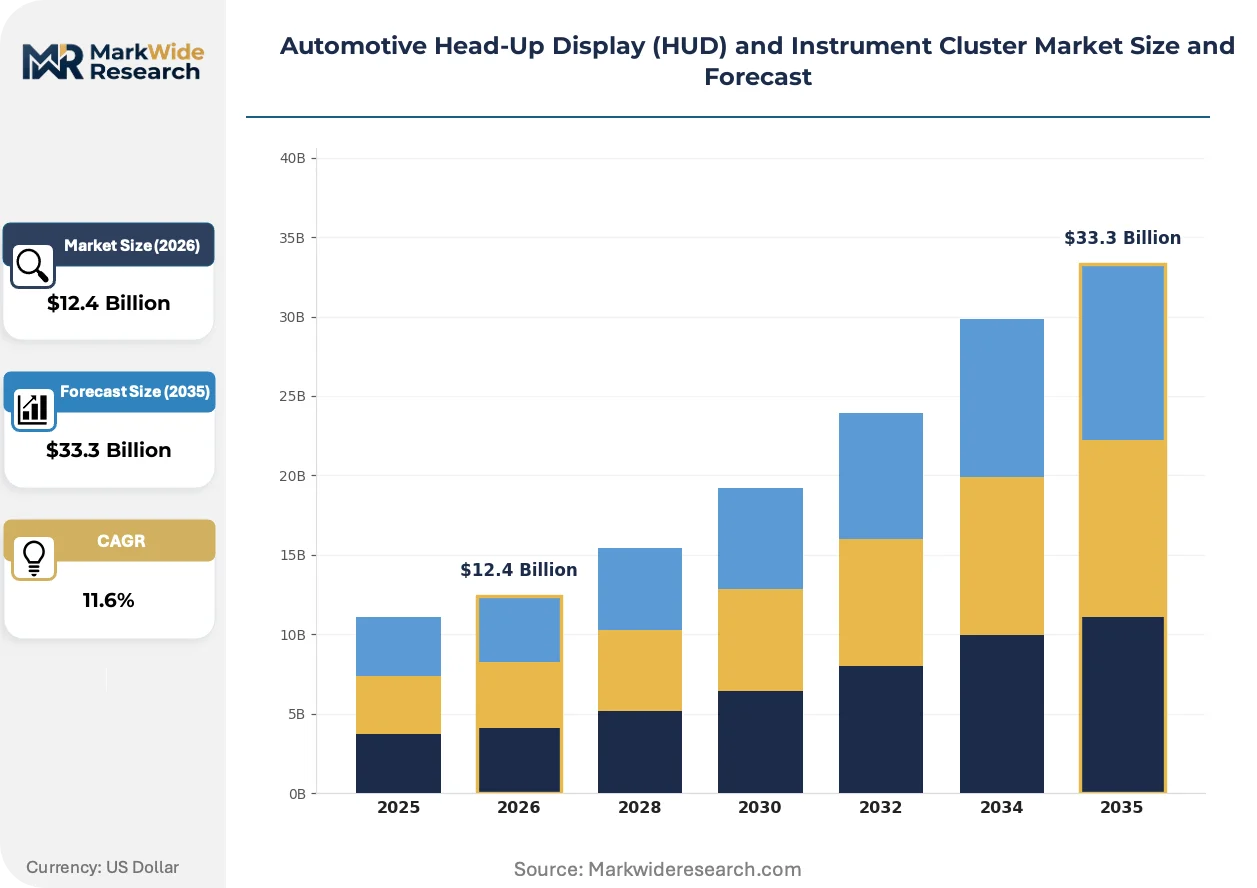
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.3 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
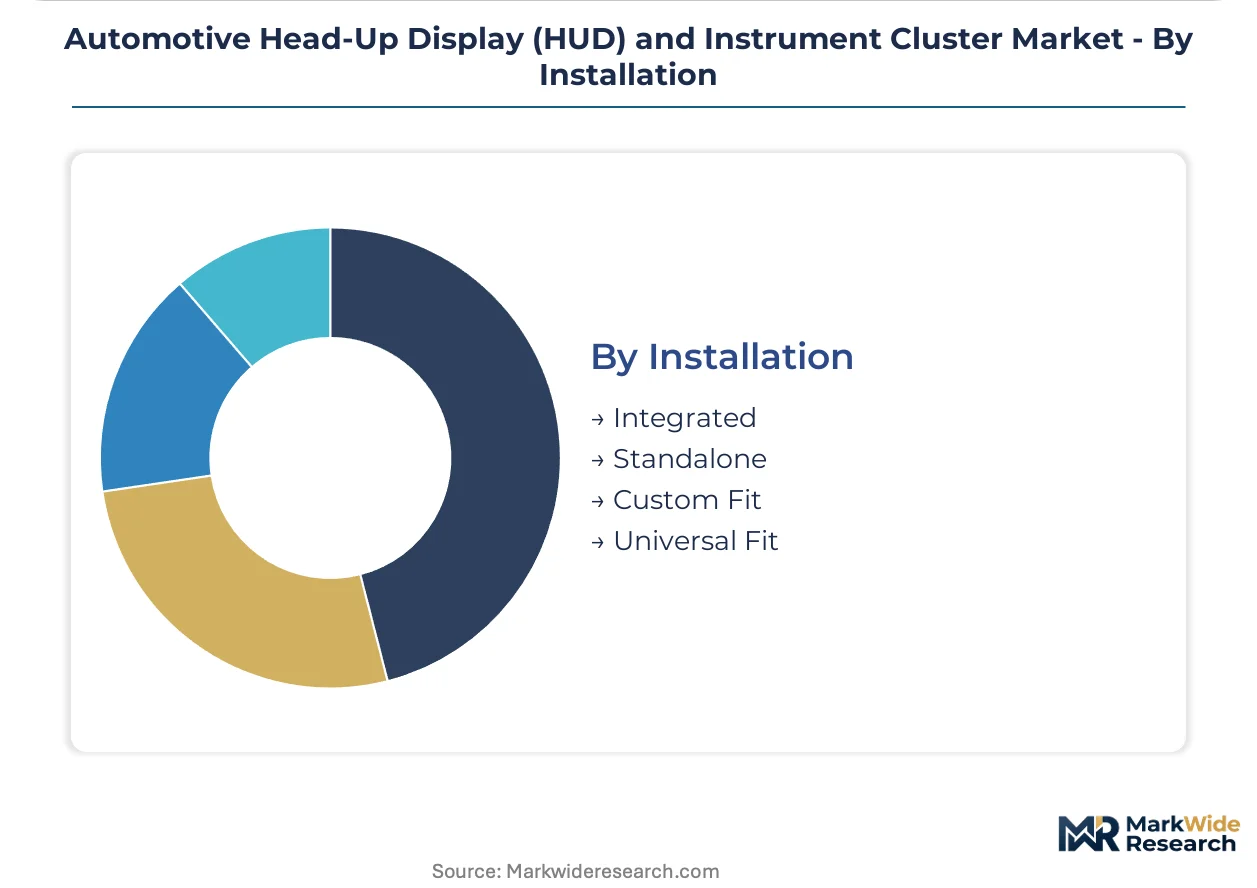
| Segmentation | Product Type: Augmented Reality HUD, Conventional HUD, Digital Instrument Cluster, Analog Instrument Cluster Technology: LCD, OLED, Laser, DLP End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Integrated, Standalone, Custom Fit, Universal Fit |
| Companies Covered | Continental AG, Robert Bosch GmbH, DENSO Corporation, Visteon Corporation, Nippon Seiki Co. Ltd., Yazaki Corporation, Panasonic Holdings Corporation, Hyundai Mobis Co., Ltd., Pioneer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Head-Up Display (HUD) and Instrument Cluster Market Trends and Innovations
Software-defined cockpit architectures are decoupling display hardware from rendering pipelines, enabling over-the-air feature activation and subscription monetization models that reshape supplier value capture.
Optical waveguide combiners are virtualizing the physical aperture of head-up displays, allowing windscreen-integrated projection without dedicated glass segments. Tier-1 suppliers in Germany and Japan are adopting holographic optical element designs for 2026 platform launches. This virtualization is compressing the bill-of-materials differential between AR HUD and conventional combiner systems.
China's MIIT GB standards for electromagnetic compatibility are tightening integration requirements between display modules and vehicle antenna systems. Suppliers must now pre-validate harmonic emissions across the 700MHz-6GHz spectrum before homologation. Premium electric vehicle platforms in the domestic market are absorbing these certification costs fastest.
Fleet procurement of standardized cockpit display suites is displacing bespoke OEM development programs. Rental and mobility service operators in the United States are specifying common HUD and cluster configurations across multi-brand vehicle pools. This consolidation concentrates volume with module suppliers capable of platform-agnostic software stacks.
Automotive Head-Up Display (HUD) and Instrument Cluster Market Segmentation
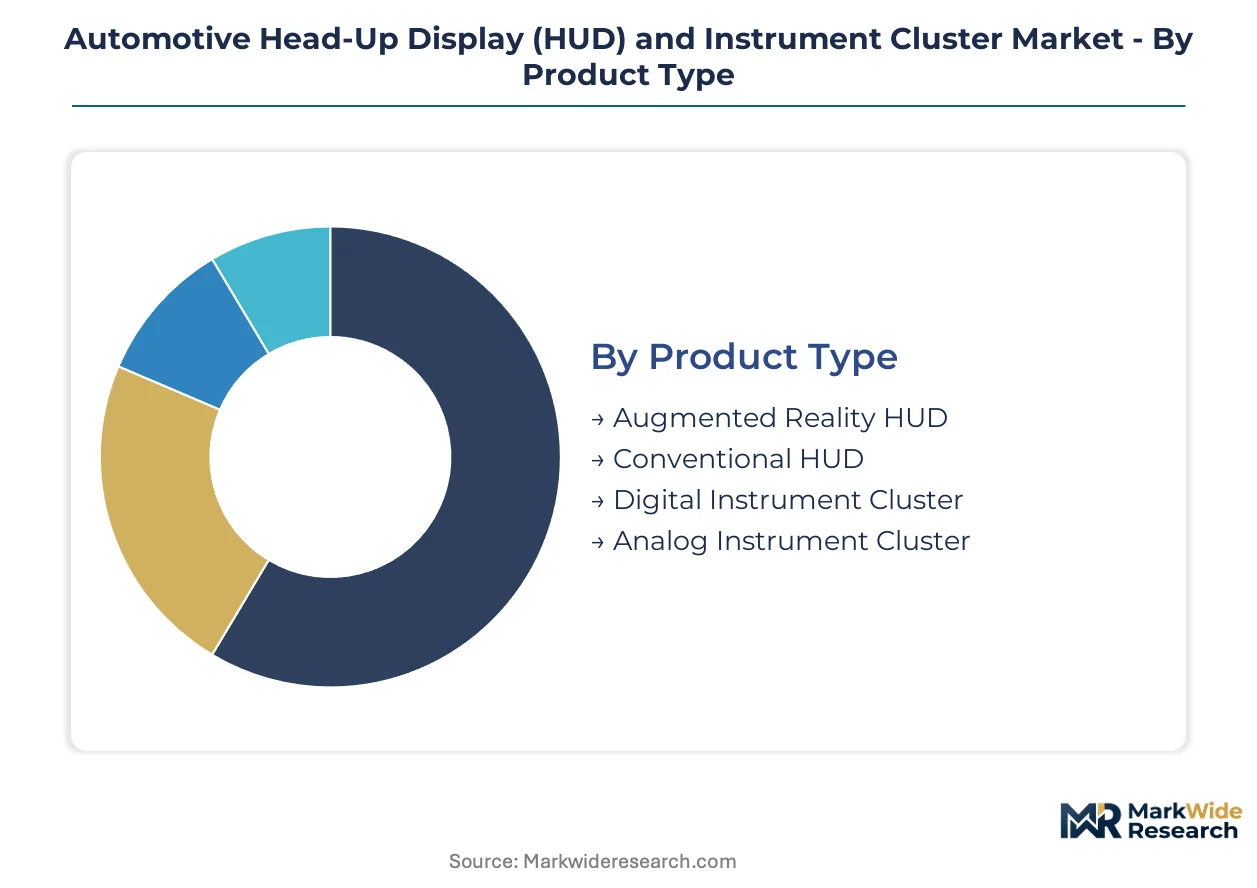
Automotive display procurement splits across performance tiers, integration depth, and supply chain position. Understanding these segment boundaries clarifies where module suppliers capture margin versus where assembly integration dominates.
Product Type:
Windshield projection systems span a spectrum from simple speed readouts to full holographic overlays fused with sensor data.
- Augmented Reality HUD:Holographic optical elements project navigation and ADAS alerts onto the forward road scene. Premium electric vehicle platforms in Germany and the United States specify these for sensor fusion integration.
- Digital Instrument Cluster:TFT-LCD or OLED microdisplays replace electromechanical gauges with reconfigurable graphics. Japanese and German OEMs are phasing out analog architectures fastest.
- Conventional HUD:Basic combiner optics display speed and turn-by-turn prompts without environmental anchoring. Mid-range vehicle lines specify these for cost containment.
- Analog Instrument Cluster:Electromechanical dials and needles persist in emerging-market vehicle lines and commercial truck segments where durability outweighs flexibility.
Established volume favors Digital Instrument Cluster; emerging adoption favors Augmented Reality HUD.
Technology:
Display backplane selection hinges on luminance requirements, form factor constraints, and thermal budgets.
- LCD:Thin-film transistor liquid crystal displays sustain the volume base through mature supply chains and daylight-readable brightness with auxiliary boost optics. Cost-sensitive vehicle lines across China and India specify these.
- OLED:Organic light-emitting diode microdisplays achieve contrast ratios exceeding 100,000:1 without backlighting. Luxury platforms in Germany and Japan absorb cost premiums for curved and free-form implementations.
- Laser:Scanning laser projection enables infinite depth of field and wide color gamut. Niche applications in high-end AR HUD systems exploit this for holographic waveguide illumination.
- DLP:Digital light processing uses micromirror arrays for high-brightness projection. Texas Instruments' chipset ecosystem supports aftermarket retrofit channels and specialized commercial vehicle applications.
Mature cost curves favor LCD; steepest expansion trajectory belongs to OLED as luminance thresholds improve.
End User:
Supply chain position determines specification authority and margin capture.
- OEMs:Vehicle manufacturers own cockpit design integration and software-defined feature roadmaps. German and U.S. OEMs are consolidating supplier relationships to single-source module platforms.
- Tier-1 Suppliers:Bosch, Panasonic, and Nippon Seiki engineer complete display modules including optics, backplanes, and thermal management. These firms qualify directly against EU AI Act functional safety mandates.
- Aftermarket Providers:Authorized dealer networks and e-commerce channels stock HUD retrofit kits. China's domestic market shows strongest uptake for legacy internal combustion platform upgrades.
- Vehicle Assemblers:Contract manufacturers in India and Mexico integrate pre-certified modules without design ownership. India's PLI scheme for automotive electronics attracts these assemblers.
Design authority concentrates with OEMs; manufacturing scale aggregates at Tier-1 Suppliers.
Installation:
Physical integration method shapes warranty liability and upgrade flexibility.
- Integrated:Factory-installed systems embed waveguide optics within windscreen lamination and dashboard structures. OEM production lines in Germany and Japan favor this for clean-sheet electric vehicle platforms.
- Standalone:Combiner glass or reflective film mounts on dashboard surfaces without windscreen modification. Fleet procurement of rental and mobility vehicles in the United States specifies these for cross-platform standardization.
- Custom Fit:Vehicle-specific mounting hardware and software calibration for particular model years. Aftermarket channels in China specialize in domestic-brand compatibility kits.
- Universal Fit:Suction-cup or adhesive mounts with generic OBD-II data interfaces. Lowest-cost entry point for consumer self-installation segments.
Factory integration dominates premium segments; retrofit flexibility drives aftermarket growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for automotive electronics is redirecting display module assembly capacity away from traditional East Asian hubs. Germany's EU AI Act implementation timeline is compressing supplier qualification windows for functional safety certification. China's MIIT GB standards for electromagnetic compatibility are raising pre-validation barriers for windscreen-integrated HUD systems.
China
Domestic EV platforms from BYD and NIO are specifying AR HUD as standard equipment across premium trims. MIIT enforces GB standards for electromagnetic compatibility that govern display module integration with vehicle antenna systems. The Yangtze River Delta cluster around Shanghai concentrates precision injection-molding capacity for polycarbonate waveguide substrates.
Germany
BMW and Mercedes-Benz are consolidating supplier relationships to single-source module platforms for 2026 electric vehicle launches. The EU AI Act mandates functional safety certification for connected cockpit displays, reshaping Tier-1 qualification timelines. Bavaria's Munich-Stuttgart corridor hosts Robert Bosch GmbH's captive semiconductor sourcing operations anchoring European display production.
United States
Fleet procurement from rental and mobility operators is standardizing HUD configurations across multi-brand vehicle pools. NHTSA guidelines on driver distraction limit field-of-view placement and information density for HUD systems. Michigan's Detroit-Auburn Hills cluster concentrates engineering talent for ADAS sensor fusion integration with AR HUD rendering engines.
Japan
Toyota and Honda are phasing out analog instrument clusters fastest among legacy OEMs, accelerating digital cluster volumes. METI oversees JIS standards alignment with UNECE WP.29 cybersecurity frameworks for connected vehicle displays. The Chubu region around Nagoya anchors Nippon Seiki Co. Ltd.'s optical waveguide design specialization serving domestic OEM supply chains.
India
Maruti Suzuki and Tata Motors are absorbing cost premiums for localized display module assembly under import-substitution pressure. The PLI scheme for automotive electronics offers tier-2 suppliers capacity incentives without fab ownership. Tamil Nadu's Chennai-Sriperumbudur corridor attracts vehicle assemblers integrating pre-certified modules for compact vehicle platforms.
Automotive Head-Up Display (HUD) and Instrument Cluster Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers. Captive semiconductor sourcing and in-house OLED backplane production define the top tier's defensive moats. Mid-tier specialists compete through optical design differentiation and regional OEM relationships. Capacity-light entrants leverage project finance and operational leasing to secure fabrication access without asset ownership. Dominant competitive moves include strategic partnerships for sensor fusion software licensing and geographic expansion into India's PLI-subsidized assembly zones.
Within the vertically integrated tier, Robert Bosch GmbH and Panasonic Holdings Corporation exemplify divergent sourcing strategies—Bosch through captive semiconductor supply in Europe, Panasonic through upstream control over OLED backplane manufacturing. Nippon Seiki Co. Ltd. occupies a specialist position anchored in Japanese OEM supply chains, representing the optical waveguide design archetype that dominates Asia-Pacific premium platform specifications.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| DENSO Corporation |
| Visteon Corporation |
| Nippon Seiki Co. Ltd. |
| Yazaki Corporation |
| Panasonic Holdings Corporation |
| Hyundai Mobis Co., Ltd. |
| Pioneer Corporation |
| Others |
Pricing and Supply Chain Analysis
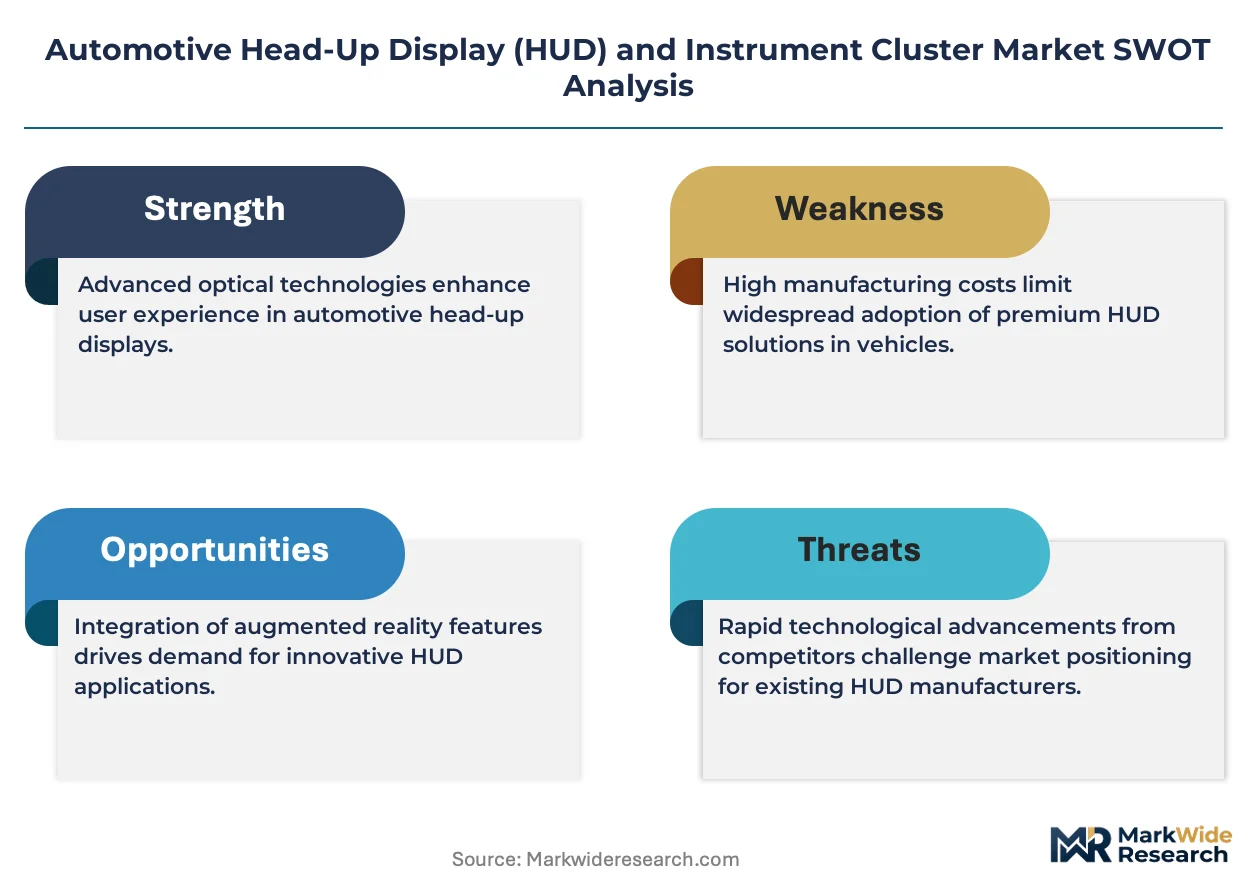
Undercapacity in precision polycarbonate waveguide injection-molding across East Asian tooling networks is compressing supplier margins while amplifying pricing power for optical substrate specialists serving European OEM qualification programs.
Pricing Analysis
Certification level under EU AI Act functional safety mandates creates the primary spread between module tiers. Pricing stratifies across premium AR HUD systems, standard digital instrument clusters, and economy conventional HUD units. Cost compression in conventional HUD segments is intensifying because LCD backplane commoditization allows Chinese assemblers to undercut established Tier-1 quotes. Fleet procurement operators exhibit highest price sensitivity, whereas German luxury OEMs absorb certification premiums without volume negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for windscreen-integrated HUD modules. Manufacturing draws from concentrated precision molding capacity in China, Japan, and Germany. Polycarbonate optical substrates, OLED microdisplays, and vacuum-bonded display stacks constitute critical input dependencies. Single-source vulnerability persists for holographic optical element designs held by Japanese specialists. Distribution runs through OEM direct procurement channels and Tier-1 module supplier networks, with aftermarket retrofit channels expanding fastest in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AR HUD penetration in premium electric vehicle platforms signals early-cycle expansion, with sensor fusion integration creating captive demand for pre-certified optical module suppliers.
For Market Incumbents: Entrench functional safety certification moats by accelerating EU AI Act compliance investment ahead of 2026 platform deadlines. Deepen captive semiconductor sourcing relationships to defend against emerging fabless entrants leveraging project finance for capacity access. Prioritize holographic optical element design talent retention as waveguide simulation expertise concentrates in narrow specialist pools.
For New Entrants and Emerging Players: Build out aftermarket retrofit channels for legacy internal combustion platforms in China's domestic market, where authorized dealer networks show strongest HUD upgrade kit uptake. Target India's PLI-subsidized assembly zones for localized module production without fab ownership. Pursue sensor fusion software licensing partnerships with lidar perception stack providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across display module assembly as operational leasing and project finance displace asset-heavy entry models. Long-term viability favors suppliers with pre-certified platform architectures spanning multiple OEM customers. Acquisition target archetype: optical waveguide design specialists with Japanese OEM supply chain anchoring. Watch India's PLI scheme uptake rates as the inflection signal for geographic manufacturing shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW and Mercedes-Benz single-source module consolidation reduces supplier qualification overhead. |
| Software-Defined Vehicle Investment | Over-the-air feature activation enables subscription monetization for Tier-1 module suppliers. |
| Geographic Manufacturing Footprint | Tamil Nadu's Chennai-Sriperumbudur corridor attracts assemblers under India's PLI scheme incentives. |
| Sensor Fusion Integration | Lidar point cloud convergence with AR HUD rendering creates new software licensing revenue pools. |
| Backward Integration into OLED Backplanes | Panasonic's upstream control over emissive pixel manufacturing secures contrast ratio leadership. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive electronics suppliers, and MIIT GB standards documentation. Bottom-up segment sizing and top-down macro anchoring were triangulated to constrain estimate variance.
Calibration against historical production volumes and announced platform launches shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from S-curve adoption modeling for AR HUD technology transitions and replacement cycle analysis for digital instrument clusters. Industry-specific inputs incorporated EU AI Act implementation timelines and NHTSA field-of-view restriction enforcement patterns.
Stress conditions across polycarbonate substrate supply disruptions, OLED luminance threshold advancement rates, and cybersecurity recertification frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM consolidation behavior and regulatory divergence trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market