
 Automotive Display Units Market | 2026-2036
Automotive Display Units Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Display Units Market Analysis
OLED substrates is recalibrating cost structures across the Automotive Display Units landscape as panel makers reduce reliance on amorphous silicon backplanes. Continental AG leverages captive semiconductor partnerships to secure display driver supply. Robert Bosch GmbH sustains R&D intensity on curved glass bonding processes for instrument clusters. LG Display anchors high-volume OLED capacity for premium electric vehicle programs.
Automotive display units are electronic visual interface systems combining TFT-LCD or OLED panels with touch sensors, anti-reflective coatings, and thermal management layers to present vehicle status, navigation, and infotainment data to drivers and passengers. These systems typically operate across temperature ranges from minus forty to eighty-five degrees Celsius and must meet automotive-grade reliability standards for vibration and electromagnetic interference. Center stack displays command the largest revenue pool as passenger vehicles integrate multi-zone touchscreens, while OLED technology is capturing the fastest expansion in head-up display applications where luminance and contrast ratios determine readability. Rear seat entertainment remains a margin-concentrated niche as luxury OEMs specify larger diagonal sizes and 4K resolution.
FCC certification governs electromagnetic emissions for displays sold into the United States, while Ecodesign frameworks in Europe mandate power consumption thresholds that favor OLED over conventional LCD architectures. Japan's METI promotes domestic display supply chain resilience through JIS standard alignment on automotive optical performance. Stakeholders must weigh panel technology commitments against evolving thermal and durability requirements as autonomous driving interfaces demand higher information density without driver distraction.
Market Dynamics
Electric vehicle manufacturers are consolidating display sourcing around large-format OLED architectures, forcing tier-1 suppliers to recalibrate semiconductor partnerships and thermal management capabilities.
Growth Catalysts
- Europe's Ecodesign mandates:Energy labeling requirements accelerate OLED transitions across instrument cluster applications, favoring low-power architectures over conventional LCD backplanes.
- Autonomous driving interfaces:Information density requirements for Level 3+ systems pull demand toward curved glass bonding and multi-zone touch integration.
- German automotive clusters:Stuttgart and Munich anchor concentrated procurement from domestic display driver foundries, reducing lead times for premium electric vehicle programs.
Market Restraints
- Amorphous silicon dependency:Panel makers face input cost volatility as LTPO backplane yields remain below commercial thresholds for automotive qualification cycles.
- South Korean supply concentration:OLED substrate production clusters around two domestic conglomerates, creating single-source vulnerability for European and Japanese OEMs.
- Electromagnetic interference limits:FCC Part 15 certification timelines for head-up display modules extend 14-18 months, gating product launches.
Strategic Opportunities
- India's PLI scheme for electronics:Component-level incentives attract display module assembly for compact vehicle exports to Southeast Asian markets.
- Rear seat entertainment convergence:4K resolution specifications in luxury electric SUVs open white space for local dimming zone differentiation.
- Japan's METI supply chain resilience:JIS standard alignment funds domestic optical film coating capacity, reducing import dependency for instrument clusters.
Industry Challenges
- Curved glass bonding expertise:Thermal expansion mismatch between cover lens and TFT substrate demands specialized process engineers scarce in Central European labor pools.
- Automotive-grade qualification cycles:AEC-Q100 compliance for display driver ICs requires 12-24 month validation timelines incompatible with consumer electronics refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Display Units Market |
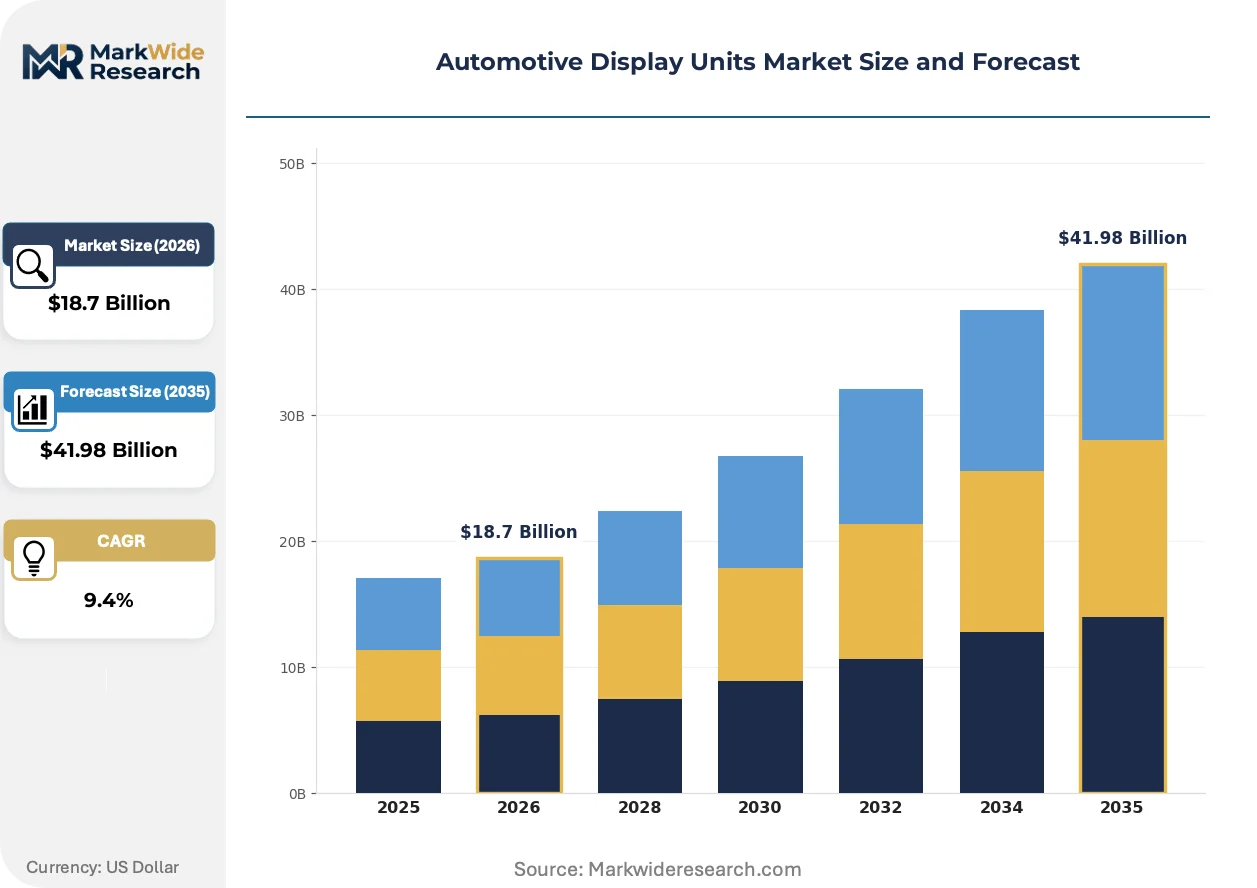
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrument Cluster, Head-Up Display, Center Stack, Rear Seat Entertainment Technology: LCD, OLED, LED, QLED Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Cars End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Visteon Corporation, LG Display, Panasonic Corporation, Valeo, Aptiv, Nippon Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Display Units Market Emerging Trajectories
Touch sensor integration is compressing stack heights and forcing optical bonding process upgrades across the supplier base. Thermal management layers now determine form factor flexibility as much as panel selection.
Local dimming algorithms are automating luminance control across mini-LED backplanes for head-up display applications. Luxury electric vehicle programs in Germany and South Korea adopt these architectures first. The technology is automating supplier selection criteria toward semiconductor-fluent tier-1s with captive driver IC partnerships.
REACH restrictions on halogenated flame retardants are reshaping optical film substrate specifications. European OEMs now specify phosphorus-based alternatives for center stack modules. Tier-2 laminators in Italy and Poland retool coating lines to maintain CE marking compliance for instrument cluster exports.
Fleet procurement consortia are aggregating display unit volumes across multiple OEM brands. Shared specification platforms reduce per-unit qualification costs for mid-size electric vehicle programs. This consolidation is most visible in Japanese keiretsu structures and German supplier councils coordinating OLED capacity reservations.
Automotive Display Units Market Segmentation
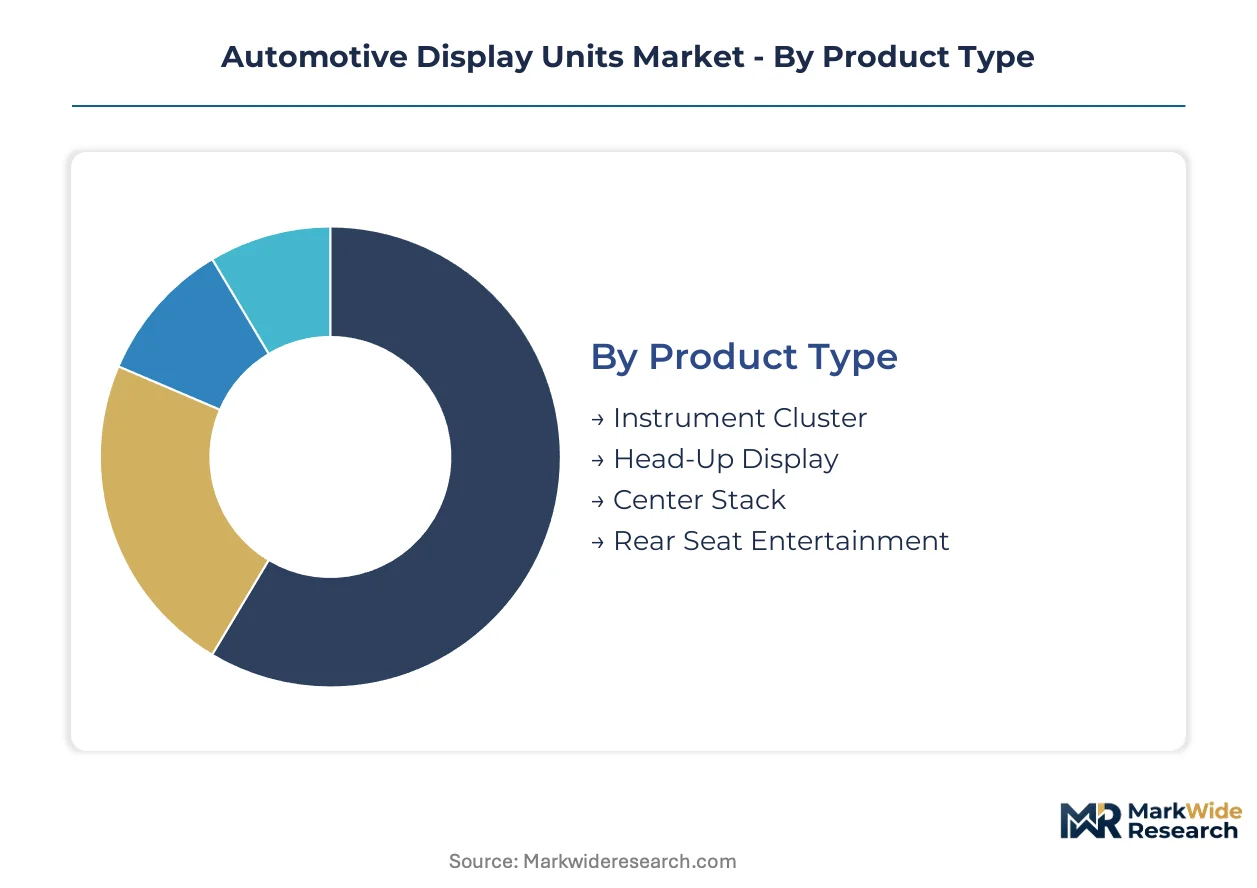
Display unit segmentation reveals where capital commitments concentrate and which technology transitions reshape procurement economics. Panel architecture choices and vehicle electrification rates determine supplier positioning across each dimension.
Product Type:
Capital intensity varies sharply across product categories, with curved glass bonding and optical stack complexity driving upfront equipment requirements.
- Instrument Cluster:Combines TFT-LCD or OLED panels with anti-reflective coatings and thermal management layers for driver-facing information presentation. German OEMs in Stuttgart and Munich specify curved glass architectures that demand specialized bonding processes and extend qualification timelines.
- Head-Up Display:Projects vehicle speed, navigation, and ADAS alerts onto windshields using high-brightness micro-displays with precise optical path engineering. South Korean electric vehicle programs pull demand toward OLED micro-displays where luminance and contrast ratios determine readability in direct sunlight conditions.
- Center Stack:Multi-zone touchscreen modules integrating capacitive sensors and haptic feedback layers for infotainment control.
- Rear Seat Entertainment:Larger diagonal displays with 4K resolution specifications targeting luxury SUV segments.
Center stack modules absorb the bulk of installed capacity; head-up display architectures are expanding most quickly as Level 3+ autonomous driving interfaces proliferate.
Technology:
Backplane material selection and substrate sourcing define the cost tier structure across display technologies.
- LCD:Mature TFT-LCD architectures using amorphous silicon backplanes dominate volume production for mid-range passenger vehicles. Europe's Ecodesign mandates on power consumption are accelerating transitions away from conventional LCD backplanes in favor of lower-energy alternatives.
- OLED:Self-emissive organic compounds eliminate backlight requirements and enable thinner form factors with superior contrast ratios. LG Display anchors high-volume capacity for premium electric vehicle programs in Germany and South Korea where curved instrument clusters command specification premiums.
- LED:Direct-lit and edge-lit configurations for high-brightness commercial vehicle applications.
- QLED:Quantum dot enhancement layers applied to LCD backplanes for expanded color gamut in rear seat entertainment modules.
LCD retains the dominant share of production volume; OLED is climbing the fastest as electric vehicle manufacturers consolidate sourcing around large-format digital interfaces.
Application:
Vehicle electrification intensity and autonomous capability levels segment demand by information density requirements.
- Passenger Vehicles:Multi-display architectures spanning instrument clusters, center stacks, and optional rear seat screens. Japanese keiretsu structures aggregate procurement volumes across multiple OEM brands to reduce per-unit qualification costs.
- Electric Vehicles:Large-format OLED specifications with integrated touch sensors and reduced bezel requirements. Battery-electric platforms in Germany, Japan, and South Korea concentrate demand as tier-1 suppliers recalibrate semiconductor partnerships and thermal management capabilities.
- Commercial Vehicles:Ruggedized displays meeting extended temperature ranges and vibration standards for fleet operators.
- Autonomous Cars:Redundant display paths and higher information density for Level 3+ systems where driver monitoring interfaces supplement traditional instrument clusters.
Passenger vehicles anchor current procurement volumes; electric vehicle applications are gaining share fastest as OEMs specify premium display architectures for differentiated cabin experiences.
End User:
Supply chain position determines technical specification authority and volume consolidation potential across buyer categories.
- OEMs:Direct procurement of display modules for flagship electric vehicle programs with custom optical specifications. German automotive clusters coordinate OLED capacity reservations through supplier councils that aggregate demand across multiple premium brands.
- Tier-1 Suppliers:System integrators combining displays with custom electronics, software stacks, and thermal management for multiple OEM customers. Continental AG and Robert Bosch GmbH leverage captive semiconductor partnerships to secure display driver supply amid foundry constraints.
- Dealerships:Retrofit and upgrade installations for existing vehicle fleets seeking enhanced infotainment capabilities.
- Aftermarket Providers:Replacement displays and third-party entertainment systems for vehicle owners outside warranty coverage.
Tier-1 suppliers intermediate the majority of display volume; OEM direct procurement is expanding most quickly as electric vehicle programs consolidate around proprietary interface designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart, Munich, and South Korea's Gyeonggi Province concentrate automotive display manufacturing through tax incentives and supplier clustering. These zones anchor procurement for premium electric vehicle programs.
Germany
Stuttgart and Munich automotive clusters specify curved OLED instrument clusters for Mercedes-Benz and BMW electric platforms. Ecodesign mandates from Brussels accelerate transitions away from conventional LCD backplanes. Continental AG and Robert Bosch GmbH coordinate capacity reservations through domestic supplier councils.
South Korea
LG Display anchors high-volume OLED substrate production for Hyundai-Kia and Genesis electric vehicle programs. The country's national industrial regulator promotes domestic supply chain resilience through standard alignment on automotive optical performance. Gyeonggi Province concentration creates single-source vulnerability for European OEMs seeking alternative suppliers.
Japan
Denso Corporation and Nippon Seiki leverage keiretsu procurement structures to aggregate display volumes across Toyota, Honda, and Nissan. METI funds domestic optical film coating capacity through JIS standard alignment. Kanto and Kansai industrial corridors reduce import dependency for instrument cluster modules.
United States
Detroit-area OEMs source center stack displays through tier-1 integrators for Ford and General Motors electric platforms. FCC Part 15 certification timelines extend 14-18 months for head-up display modules, gating product launches. Michigan and Ohio supplier parks concentrate module assembly near final vehicle assembly plants.
India
The PLI scheme for electronics attracts display module assembly for compact vehicle exports to Southeast Asian markets. Domestic tier-1 suppliers establish captive semiconductor partnerships to secure display driver supply. Tamil Nadu and Gujarat industrial corridors host emerging capacity for instrument cluster exports.
Automotive Display Units Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-1 system integrators commanding instrument cluster and center stack volumes while panel makers retain direct OEM relationships for premium OLED specifications. The structure concentrates around semiconductor-fluent integrators with captive driver IC partnerships and thermal management capabilities. Three archetypes dominate: captive semiconductor tier-1s, high-volume OLED substrate specialists, and regional module assemblers serving cost-sensitive compact vehicle programs. Competitive moves center on curved glass bonding process licensing and strategic capacity reservations for electric vehicle launch windows.
Among German-based tier-1 integrators, Continental AG and Robert Bosch GmbH occupy positions within the captive semiconductor partnership archetype, securing display driver supply amid foundry constraints. LG Display exemplifies the high-volume substrate specialist tier, anchoring OLED capacity for premium electric vehicle programs in Germany and South Korea. These three companies represent distinct competitive positioning vectors across the technology stack.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Visteon Corporation |
| LG Display |
| Panasonic Corporation |
| Valeo |
| Aptiv |
| Nippon Seiki |
| Others |
Supply Flow & Price Mechanics
Curved OLED instrument cluster specifications versus conventional LCD center stack modules bifurcate the Automotive Display Units landscape into premium and commodity tiers, with the former commanding captive semiconductor partnerships and the latter feeding from spot-market driver IC procurement. Europe's Ecodesign mandates on power consumption amplify this divergence by accelerating OEM transitions toward OLED architectures that carry steeper upfront qualification costs but reduce long-term energy penalties.
Pricing Analysis
Volume-margins split sharply across the technology stack: high-unit center stack LCD modules compete on scale economies while low-volume curved OLED instrument clusters extract premiums through specialized bonding processes and AEC-Q100 certification. Price differentiation hinges on thermal management layer complexity and optical film substrate specifications, with REACH-compliant phosphorus-based alternatives commanding 15-20% premiums over halogenated legacy materials. Cost compression in the LCD tier intensifies as amorphous silicon backplane yields fluctuate, while OLED pricing holds firmer due to concentrated substrate supply. Fleet procurement consortia exhibit highest price sensitivity through aggregated volume negotiations; luxury electric vehicle OEMs show lowest sensitivity when specifying custom optical paths for head-up display modules.
Supply Chain Analysis
Amorphous silicon wafer supply rests on Japanese and Taiwanese specialty foundries, while OLED organic compound synthesis clusters around South Korean and German chemical producers. Display driver IC fabrication draws from Taiwan and South Korea, with back-end module assembly concentrating in China, Mexico, and Central European supplier parks. Single-source vulnerability pervades the OLED substrate tier, where LG Display and Samsung Display anchor global capacity. Distribution runs through tier-1 system integrators—Continental AG, Robert Bosch GmbH, Denso Corporation—who consolidate procurement across multiple OEM programs and manage qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Display Units sector occupies a technology-transition phase where OLED architectures displace conventional LCD backplanes under regulatory pressure from Europe's Ecodesign framework and autonomous driving interface requirements.
For Market Incumbents: Cement curved glass bonding expertise through captive process engineering teams in Stuttgart and Munich clusters, insulating against emerging Chinese module assemblers with cost-advantaged labor. Deepen semiconductor partnerships with Taiwan and South Korean foundries to secure display driver IC allocation amid persistent foundry constraints. Prioritize AEC-Q100 pre-certification investments to compress qualification timelines for electric vehicle launch windows. For New Entrants and Emerging Players: Tier-2 optical film laminators in Poland and Italy present partnership opportunities for REACH-compliant coating capacity expansion, addressing European OEM demand for phosphorus-based flame retardant substrates. India's PLI scheme for electronics offers white-space entry for compact vehicle instrument cluster assembly serving Southeast Asian export markets. Pursue fleet procurement consortium relationships in Japanese keiretsu structures where aggregated volumes reduce per-unit qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with semiconductor-fluent tier-1 integrators with captive driver IC partnerships given the persistent foundry allocation bottlenecks across Taiwan and South Korea. Long-term viability favors archetypes with thermal management layer expertise and curved glass bonding capabilities rather than pure panel resellers. Watch OLED substrate yield improvements at LG Display and Samsung Display as the signal for accelerated premium electric vehicle program adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Curved Glass Bonding Process Licensing | Secures premium electric vehicle instrument cluster specifications from Mercedes-Benz and BMW platforms. |
| Captive Display Driver IC Partnership | Insulates tier-1 suppliers against Taiwan foundry allocation constraints for OLED module production. |
| REACH-Compliant Optical Film Capacity | Enables CE marking compliance for center stack exports to European OEMs under halogenated flame retardant restrictions. |
| India PLI Scheme Module Assembly | Positions compact vehicle instrument cluster production for Southeast Asian market penetration. |
| Fleet Procurement Consortium Participation | Reduces per-unit qualification costs through Japanese keiretsu volume aggregation across Toyota, Honda, and Nissan. |
Methodological Framework
Independent corroboration across Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with thermal management specialists, optical bonding process engineers, and semiconductor supply chain managers at Continental AG, Robert Bosch GmbH, and Denso Corporation. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed display panel manufacturers, and regulatory filings with Europe's Ecodesign framework. Bottom-up segment sizing triangulated against top-down OEM procurement budget analysis.
Comparable-period anchoring to historical electric vehicle display content per vehicle trends established the forecast baseline across the projection horizon. The analytical framework modeled demand across vehicle class, propulsion architecture, panel technology, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Industry-specific inputs included OLED substrate yield curves, AEC-Q100 qualification timeline distributions, and Ecodesign mandate compliance cost trajectories.
Caveats apply where LTPO backplane yield breakthroughs, South Korean supply disruptions, or FCC Part 15 certification timeline extensions could materially shift the outlook. Forecasts embed assumptions regarding electric vehicle adoption curves and autonomous driving interface deployment schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market