
 Display Unit in Vehicle Infotainment Market | 2026-2036
Display Unit in Vehicle Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
Display Unit in Vehicle Infotainment Market Insights
Luxury passenger vehicle buyers are rotating toward immersive cockpit experiences that integrate multiple high-resolution touch surfaces. Continental AG leverages captive display production to secure supply for German OEM programs. Harman International sustains its position through audio-visual system bundling that raises attach rates for larger screens. Robert Bosch GmbH competes on software-defined display architectures that separate hardware from content rendering.
A display unit in vehicle infotainment constitutes an integrated electronic visual interface, typically measuring 7 to 17 inches diagonally with pixel densities exceeding 150 ppi, manufactured through thin-film transistor backplane processes on glass or flexible polymer substrates. Its primary commercial purpose is to present navigation, entertainment, and vehicle status information to occupants while accepting touch, gesture, or voice-mediated inputs. OLED panels command premium positioning in flagship vehicle lines where contrast ratios and form factor flexibility justify higher module costs, while TFT-LCD variants anchor volume production for mid-range nameplates. Fleet management applications represent a developing margin pool as commercial operators specify ruggedized displays with extended temperature tolerances for logistics and ride-hail duty cycles.
FCC equipment authorization governs electromagnetic emissions from integrated display modules sold into the United States, while ECHA REACH restrictions on hazardous substances constrain substrate and coating chemistries across European supply chains. Japan's METI energy efficiency benchmarks indirectly shape backlighting power budgets that display engineers must accommodate. Stakeholders must monitor how software liability frameworks evolve as displays transition from passive output devices to active control surfaces for autonomous driving functions.
Market Dynamics
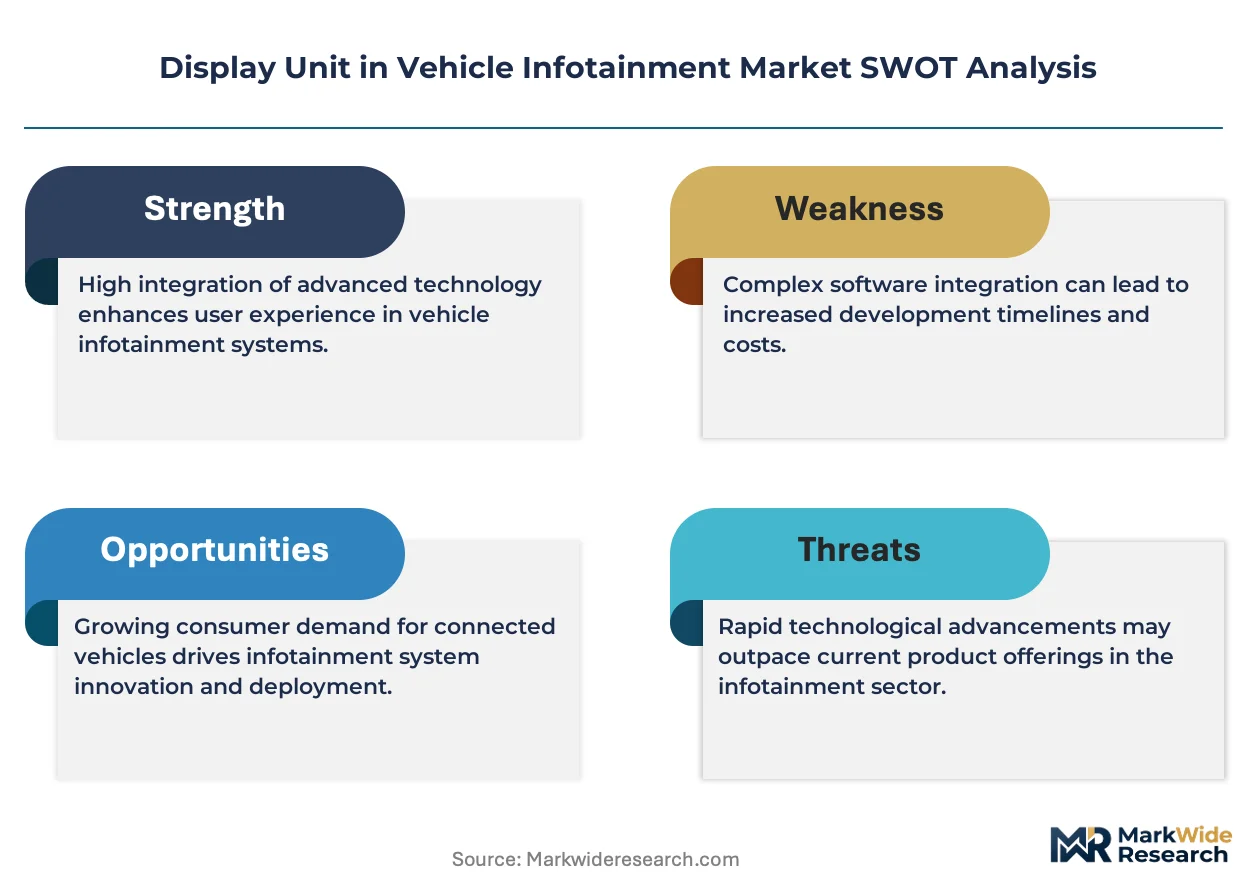
Automotive OEMs are consolidating display procurement around software-defined architectures that decouple hardware from content rendering, compressing traditional tier-one supplier margins while opening module sourcing to specialized panel manufacturers.
Growth Catalysts
- Europe's F-Gas Regulation:Phasedown of fluorinated greenhouse gases in thermal management systems accelerates OLED adoption over LCD panels in premium vehicle lines where thermal efficiency requirements tighten.
- Curved display arrays:Domestic Chinese EV brands specify larger, non-planar screen configurations that exceed legacy automaker specifications elsewhere, pulling capacity expansion from Korean and Taiwanese panel makers.
- Logistics fleet digitization:Commercial operators in ride-hail and last-mile delivery segments specify ruggedized displays with extended temperature tolerances, creating attach-rate expansion for hardened interface modules.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor deposition depends on Chinese rare earth processing capacity, exposing display makers to export quota volatility and geopolitical sourcing risk.
- Driver IC fabrication bottlenecks:Advanced timing controller chips for high-refresh panels concentrate at TSMC and Samsung Foundry, constraining output scaling for automotive-qualified silicon.
- REACH substance restrictions:ECHA constraints on cadmium and lead in substrate coatings force reformulation of quantum dot enhancement films, raising qualification timelines for European-bound modules.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced electronics manufacturing attract display module assembly investments serving domestic OEMs and export markets.
- Head-up display convergence:Windshield projection systems integrating with central stack screens create bundled cockpit electronics procurement, favoring suppliers with optical and flat-panel dual capabilities.
- Subscription-based feature activation:Over-the-air unlock of heated seats, navigation, and entertainment functions extends display monetization beyond hardware shipment, reshaping tier-one revenue models.
Industry Challenges
- Automotive functional safety certification:ISO 26262 ASIL-B and ASIL-C ratings for displays controlling autonomous driving functions require validation cycles that extend eighteen to thirty months beyond consumer electronics norms.
- Legacy vehicle electrical architectures:CAN bus bandwidth limitations in pre-2020 nameplates constrain data throughput for high-resolution screens, forcing expensive gateway electronics or content downgrade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Unit in Vehicle Infotainment Market |
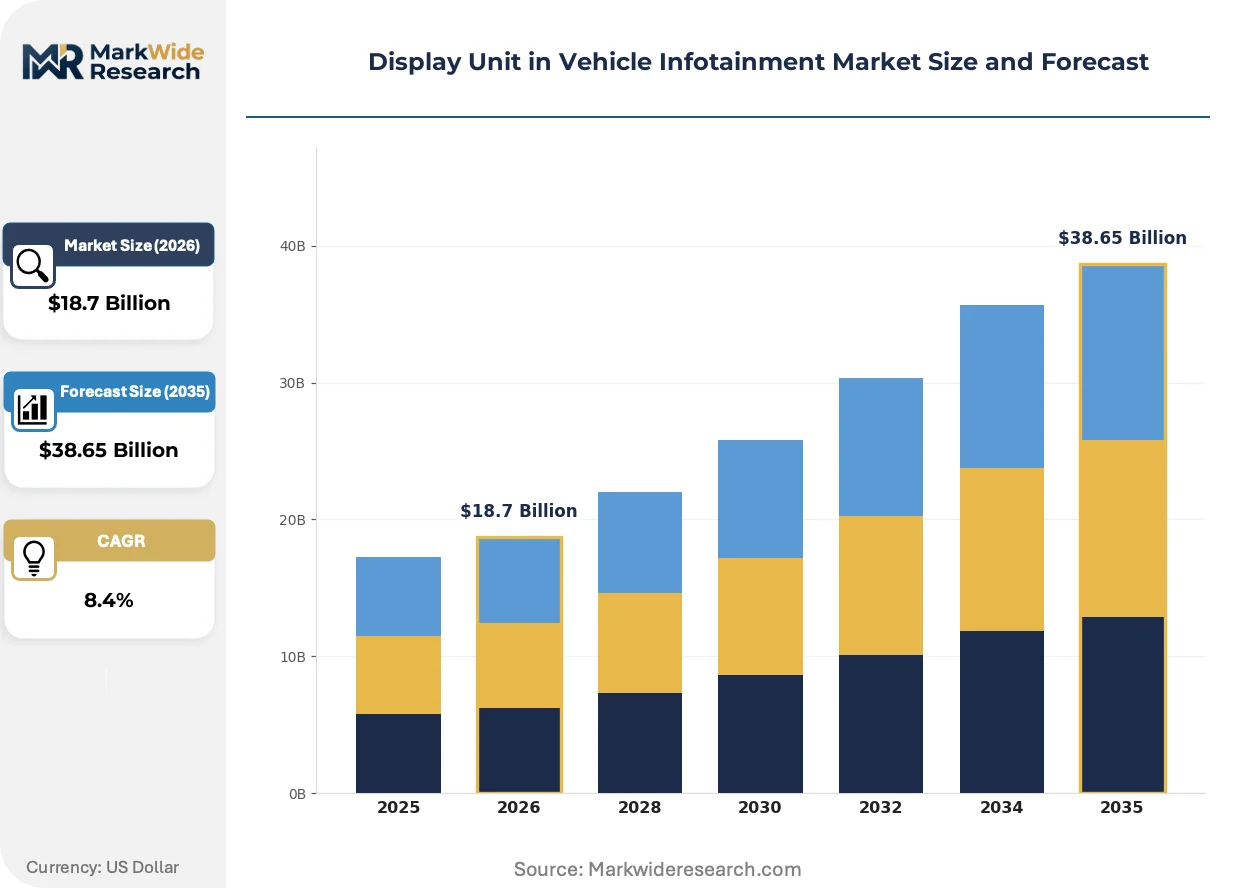
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
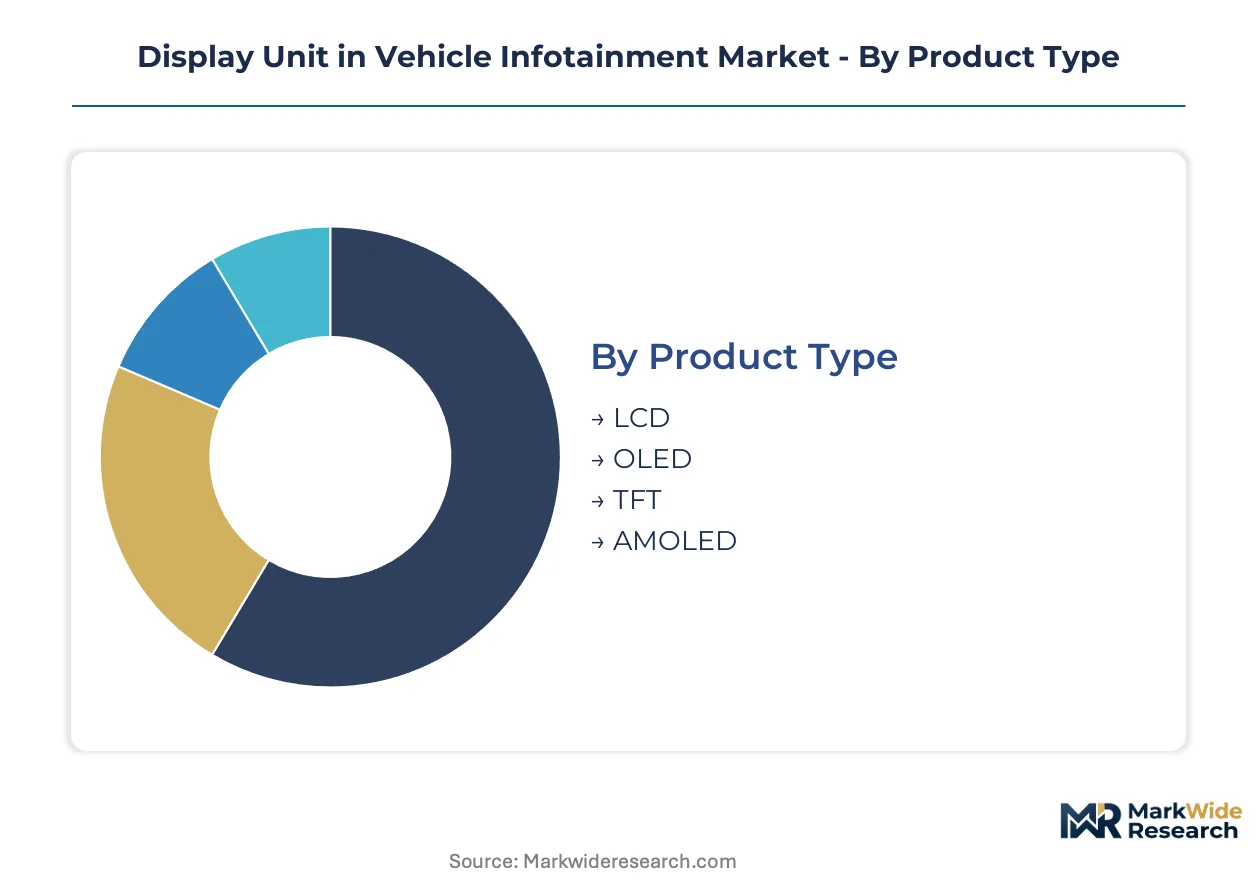
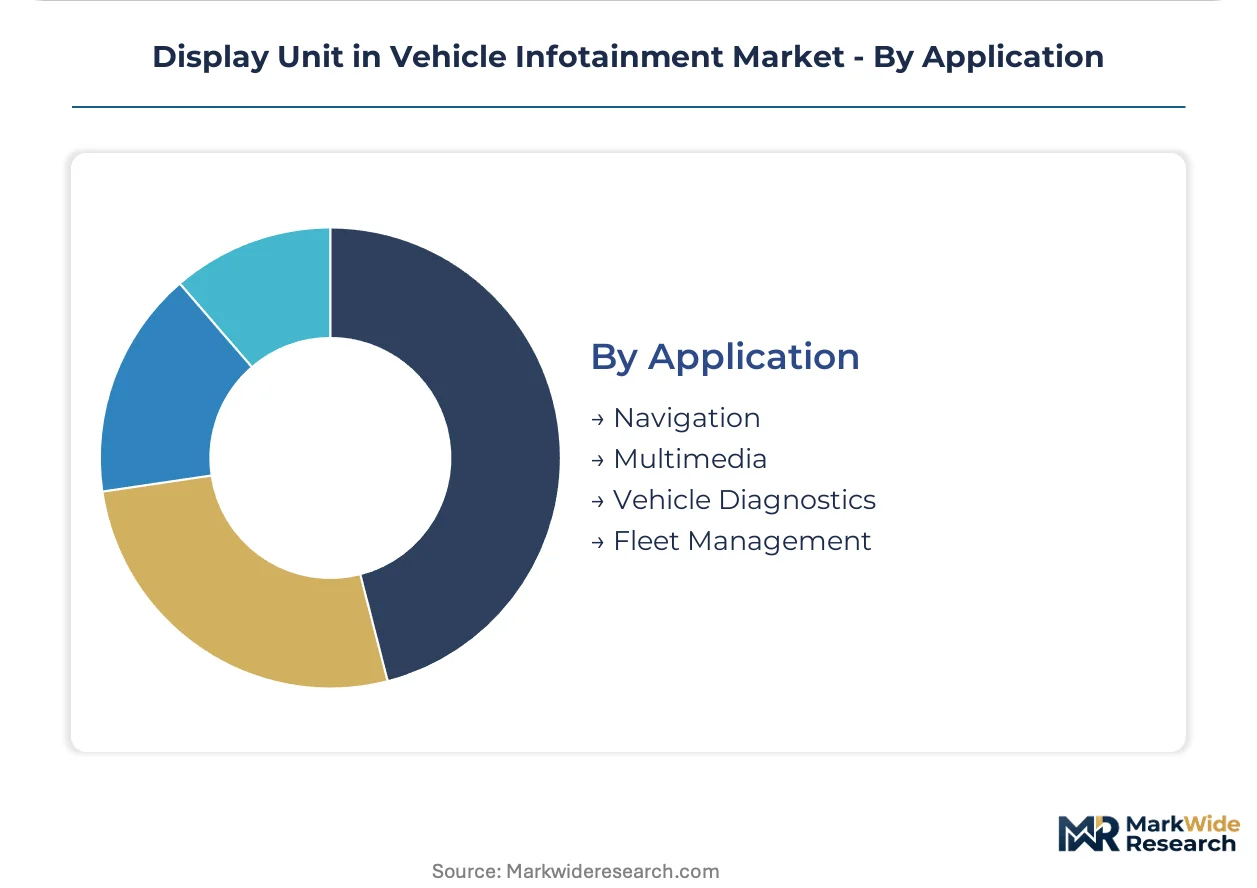
| Segmentation | Product Type: LCD, OLED, TFT, AMOLED Connectivity: Wi-Fi, Bluetooth, USB, HDMI End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Navigation, Multimedia, Vehicle Diagnostics, Fleet Management |
| Companies Covered | Continental AG, Harman International, Panasonic Corporation, Denso Corporation, Robert Bosch GmbH, Visteon Corporation, LG Electronics, Alps Alpine Co., Ltd., LG Display Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Unit in Vehicle Infotainment Market Trends and Innovations
Interface technology is bifurcating between flagship OLED deployments emphasizing form factor flexibility and volume TFT-LCD production optimized for cost absorption in mass-market nameplates.
LTPO backplane technology enables variable refresh rates from one to one hundred twenty hertz without dedicated display controller hardware. German and Korean OEMs are adopting these panels for flagship electric sedans where power budget optimization extends range claims. Variable refresh is displacing fixed-rate LCD modules in segments above fifty thousand dollars, compressing margins for suppliers lacking low-temperature polysilicon fabrication partnerships.
ECHA REACH restrictions on hazardous substances now cover per- and polyfluoroalkyl substances in anti-smudge coatings applied to touch surfaces. Panel makers serving European OEM programs must qualify alternative oleophobic treatments that meet finger-drag friction specifications without fluorinated chemistry. Suppliers with pre-qualified coating formulations capture allocation priority for German and Swedish vehicle launches.
Fleet operators in logistics and ride-hail segments now specify total cost of ownership contracts that bundle display replacement, software maintenance, and connectivity fees into per-mile charges. This procurement model transfers obsolescence risk from vehicle owners to tier-one electronics suppliers. North American commercial vehicle lessors have pioneered these arrangements, pressuring traditional hardware-margin business models.
Display Unit in Vehicle Infotainment Market Segmentation
Display module procurement patterns diverge sharply across customer archetypes, with captive OEM supply chains, tier-1 integrators, and independent aftermarket channels each imposing distinct specification requirements on panel suppliers. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where cost absorption dominates supplier selection.
Product Type:
Domestic Chinese EV programs drive outsized demand for curved OLED arrays, while European and North American volume production remains anchored to LCD and TFT variants with established supply chains.
- LCD:Thin-film transistor liquid crystal displays with cold-cathode fluorescent or LED edge-lit backlights dominate mid-range vehicle programs where cost-per-module targets fall below premium thresholds. German and Japanese OEMs specify these panels for fleet and economy nameplates where thermal management constraints from Europe's F-Gas Regulation have not yet forced technology migration.
- OLED:Organic light-emitting diode panels with self-illuminating pixels eliminate backlight assemblies, enabling sub-2mm form factors and contrast ratios exceeding 1,000,000:1. Korean panel makers supply these modules to premium electric vehicle lines where dashboard curvature and power budget optimization justify 40-60% module cost premiums over LCD equivalents.
- TFT:Thin-film transistor active-matrix addressing enables refresh rates above 60Hz for navigation map animation and video playback. Volume production concentrates at Taiwanese and Chinese fabs serving legacy automaker programs with stable, multi-year procurement commitments.
- AMOLED:Active-matrix OLED variants with low-temperature polysilicon backplanes support variable refresh rate protocols that extend electric vehicle range claims. Samsung Display and LG Display control capacity expansion for these panels, with allocation priority flowing to German and Korean flagship sedan launches.
LCD commands the established base. The steepest expansion runs through OLED.
Connectivity:
Module specification increasingly bundles wireless protocols as standard rather than options, compressing differentiation among hardware suppliers while shifting margin capture toward software integration layers.
- Wi-Fi:IEEE 802.11ac/ax modules enable over-the-air firmware updates and streaming content delivery without tethered smartphone dependency. Chinese EV brands specify Wi-Fi 6E as baseline across all trim levels, forcing module suppliers to absorb chipset cost premiums that legacy automakers relegate to option packages.
- Bluetooth:Low-energy and classic audio protocols support hands-free telephony and device pairing for navigation audio streaming. Tier-1 suppliers bundle Bluetooth 5.3 controllers with display modules as a commodity inclusion, with minimal pricing power for standalone protocol upgrades.
- USB:Type-C Power Delivery ports with DisplayPort alternate mode support wired smartphone mirroring and rapid charging up to 100W. Aftermarket providers specify USB 3.2 modules for retrofit applications where vehicle electrical architectures predate wireless protocol integration.
- HDMI:High-definition multimedia interface inputs enable rear-seat entertainment system daisy-chaining from central stack sources. Premium vehicle programs in Germany and the United States retain HDMI as a differentiation feature for executive-class rear compartments.
Bluetooth anchors volume shipments. USB Type-C is gaining share fastest.
End User:
Customer concentration varies dramatically, with top-five global OEMs controlling majority procurement volume while aftermarket fragmentation creates margin dispersion.
- Automakers:Vehicle manufacturers with captive electronics divisions or exclusive tier-1 partnerships specify proprietary display form factors that lock out second-source competition. Volkswagen Group and Stellantis programs exemplify this procurement mode.
- Tier-1 Suppliers:Delphi Technologies, Visteon, and similar integrators aggregate panel procurement across multiple OEM programs, achieving volume leverage but ceding specification control to customer engineering teams.
- Aftermarket Providers:Pioneer, Alpine, and regional installers serve vehicle owners outside warranty periods with standardized DIN-form-factor replacements.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source display modules directly from panel makers, bypassing traditional tier-1 relationships.
Automakers direct the volume base. Vehicle assemblers are climbing the fastest.
Application:
Functional requirements stratify sharply, with safety-critical navigation displays subject to ISO 26262 validation that entertainment modules escape.
- Navigation:GPS-integrated displays with real-time traffic rendering and augmented reality overlay capabilities require ASIL-B functional safety certification. These modules carry 25-40% cost premiums over entertainment-only equivalents.
- Multimedia:Video and audio playback interfaces prioritize pixel density and color gamut over operational reliability metrics. Chinese domestic brands specify 4K resolution as standard, pulling capacity from Korean panel makers.
- Vehicle Diagnostics:Service technician interfaces and owner-accessible health monitors display OBD-II data streams with ruggedized touch surfaces for garage environments.
- Fleet Management:Logistics operators specify hardened displays with -30°C to 85°C operating ranges and anti-glare treatments for cab-forward commercial vehicles.
Multimedia commands the installed base. Fleet management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean display panel exports supply German premium automakers and Chinese EV manufacturers with OLED modules, establishing a trans-Pacific technology corridor that shapes procurement patterns across three continents.
Germany
Volkswagen Group and BMW specifications for curved dashboard arrays drive demand for flexible OLED substrates. ECHA REACH restrictions on fluorinated compounds in anti-smudge coatings force panel suppliers to qualify alternative surface treatments. Stuttgart engineering clusters coordinate validation cycles for ISO 26262 ASIL-certified displays controlling autonomous driving functions.
China
Domestic EV brands NIO, Xpeng, and Li Auto specify 15-17 inch curved screen configurations exceeding legacy automaker dimensions elsewhere. MIIT energy efficiency benchmarks for new energy vehicles indirectly constrain display power budgets. Shenzhen and Hefei panel fabrication hubs expand LTPO backplane capacity to serve local OEM programs with variable refresh rate modules.
United States
Fleet operators in ride-hail and last-mile logistics segments specify ruggedized displays with extended temperature tolerances for commercial duty cycles. FCC equipment authorization governs electromagnetic emissions from integrated modules sold into the market. Michigan-based tier-1 integrators aggregate procurement across Detroit Three programs, achieving volume leverage on standardized form factors.
South Korea
Samsung Display and LG Display control expansion for AMOLED panels with low-temperature polysilicon backplanes supporting variable refresh protocols. Korean-flagship electric sedan launches receive allocation priority from domestic panel makers. Gyeonggi-do fabrication complexes supply German and Chinese OEMs through dedicated automotive-grade production lines.
Japan
Alps Alpine and Denso anchor domestic supply chains for TFT-LCD modules serving legacy automaker programs with stable procurement commitments. METI energy efficiency benchmarks shape backlighting power budgets that display engineers must accommodate. Aichi Prefecture electronics clusters maintain qualification partnerships for fixed-refresh panels in mass-market nameplates.
Display Unit in Vehicle Infotainment Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive display divisions and specialized tier-1 automotive integrators. Market structure concentrates procurement leverage among five global OEMs controlling majority volume, compressing margins for module suppliers lacking scale or differentiation. Strategic archetypes include full-stack cockpit electronics bundlers, software-defined architecture specialists, and panel makers with direct OEM relationships. Competitive moves center on M&A for display controller semiconductor capabilities and strategic partnerships for LTPO backplane access.
Among German diversified suppliers, Continental AG and Robert Bosch GmbH exemplify contrasting approaches to cockpit electronics integration. Continental leverages captive display production to secure supply allocation for domestic OEM programs, while Bosch competes on software-defined architectures that separate hardware modules from content rendering layers. Harman International, a Samsung subsidiary, sustains positioning through audio-visual system bundling that raises attach rates for larger screen configurations in premium vehicle lines. These three anchors illustrate how geographic origin and corporate structure shape competitive archetype selection.
| Leading Market Players |
|---|
| Continental AG |
| Harman International |
| Panasonic Corporation |
| Denso Corporation |
| Robert Bosch GmbH |
| Visteon Corporation |
| LG Electronics |
| Alps Alpine Co., Ltd. |
| LG Display Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Panel fabrication scale economies at Samsung Display and LG Display shape both supply allocation and price floors across automotive programs. Korean and Taiwanese capacity utilization rates directly determine module cost structures, compressing margins for second-tier suppliers while concentrating pricing power with integrated conglomerates serving German and Chinese OEMs.
Pricing Analysis
OLED-to-LCD pricing gaps widen as AMOLED variable-refresh modules command 40-60% premiums over fixed-rate TFT-LCD equivalents in flagship electric sedans. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified navigation displays from entertainment-only panels and aftermarket DIN-form-factor replacements. Cost compression in mid-range LCD segments is intensifying because Chinese EV brands specify Wi-Fi 6E and USB-C Power Delivery as baseline rather than options. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership contracting that bundles replacement and maintenance.
Supply Chain Analysis
South Korea and Taiwan anchor driver IC and backplane fabrication for automotive-qualified silicon, while China concentrates rare earth processing for indium tin oxide transparent conductors. Display module assembly draws from Korean OLED substrates, Japanese TFT-LCD glass, and Chinese flexible polymer films. Single-source vulnerability concentrates at TSMC and Samsung Foundry for advanced timing controller chips. Distribution runs through tier-1 integrators in Michigan and Stuttgart that aggregate procurement across multiple OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's F-Gas Regulation and REACH compliance mandates constitute a regulatory inflection accelerating OLED adoption and reshaping supplier qualification requirements. This technological disruption creates asymmetric opportunities across incumbent defense, entrant positioning, and investment screening.
For Market Incumbents: Shield core allocation relationships with Volkswagen Group and Stellantis by accelerating LTPO backplane partnerships before Korean panel makers lock capacity. Deepen captive supply integration into driver IC semiconductor capabilities to reduce dependency on TSMC and Samsung Foundry bottlenecks. ISO 26262 ASIL-B certification investment represents the critical defensive lever against software-defined architecture specialists.
For New Entrants and Emerging Players: Fleet management software integration gaps where incumbents under-serve logistics operators create white-space entry points. Target ride-hail and last-mile delivery segments in North America with ruggedized displays bundled into per-mile service contracts. Bypass tier-1 relationships by supplying vehicle assemblers for emerging EV brands directly from Shenzhen and Hefei fabrication hubs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors panel makers with pre-qualified REACH-compliant coating formulations and direct OEM relationships. Long-term viability over the next decade hinges on software-defined architecture capabilities that separate hardware from content rendering. Monitor ECHA substance restriction expansion as the signal indicating qualification timeline compression and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| LTPO Backplane Partnership | Secures variable refresh rate capacity for German flagship electric sedan programs. |
| REACH-Compliant Coating Qualification | Captures allocation priority for European OEM launches under ECHA restrictions. |
| Fleet Management Service Contracting | Transfers obsolescence risk from vehicle owners to tier-one electronics suppliers. |
| Driver IC Semiconductor Acquisition | Reduces single-source vulnerability to TSMC and Samsung Foundry bottlenecks. |
| Software-Defined Architecture Investment | Separates hardware modules from content rendering layers, compressing traditional margins. |
Research Methodology
A standing panel of tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists provided ongoing calibration against secondary validation. Primary interviews combined with customs and trade data, SEC 10-K filings, vehicle production databases, and IHS Markit registration data enabled bottom-up and top-down triangulation across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from historical shipment trajectories and technology substitution curves incorporated MIIT energy efficiency benchmarks and FCC equipment authorization timelines as industry-specific forecast inputs.
Underlying assumptions cover technology adoption curves, regulatory enforcement intensity, and supply chain stability, with deviation risk concentrated in indium tin oxide export quota volatility and driver IC fabrication capacity constraints. Recalibration cycles align with material shifts in ECHA substance restriction schedules and OEM platform launch timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market