
 Concrete Demolition Professional Equipment Market | 2026-2036
Concrete Demolition Professional Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Demolition Professional Equipment Market Insights
Infrastructure development is consolidating as the dominant demand vector for concrete demolition professional equipment, displacing traditional mining-linked procurement cycles. Caterpillar leverages its North American dealer density to anchor highway reconstruction contracts. Komatsu competes through integrated machine-to-machine telemetry that sustains fleet uptime metrics for large contractors.
Concrete demolition professional equipment encompasses specialized machinery engineered to fracture, cut, or pulverize reinforced concrete structures, with hydraulic breakers typically delivering impact energy ratings from 500 to 12,000 joules depending on carrier weight class. The primary industrial purpose centers on controlled deconstruction of built infrastructure where precision fragmentation minimizes collateral structural damage and enables material recovery. Hydraulic breakers occupy the largest installed base among equipment types, though electric and fuel cell technologies are capturing specification share in urban emission-restricted zones. Tunnel excavation and bridge demolition applications command premium pricing due to confined-space engineering requirements and specialized carrier configurations.
OSHA enforces permissible exposure limits for respirable crystalline silica during concrete demolition, compelling manufacturers to integrate vacuum-assisted dust suppression and enclosed operator cabs. EPA Tier 4 Final and emerging state-level zero-emission mandates for construction equipment are accelerating electric and hybrid powertrain development. Stakeholders must monitor regulatory divergence between federal emission timelines and municipal procurement preferences that increasingly specify electrified fleets for public projects.
Market Dynamics
OSHA silica exposure limits and EPA Tier 4 Final emissions rules are compressing equipment replacement cycles, forcing contractors to retire diesel-powered breakers ahead of schedule and redirect capital toward electrified and dust-suppressed systems.
Growth Catalysts
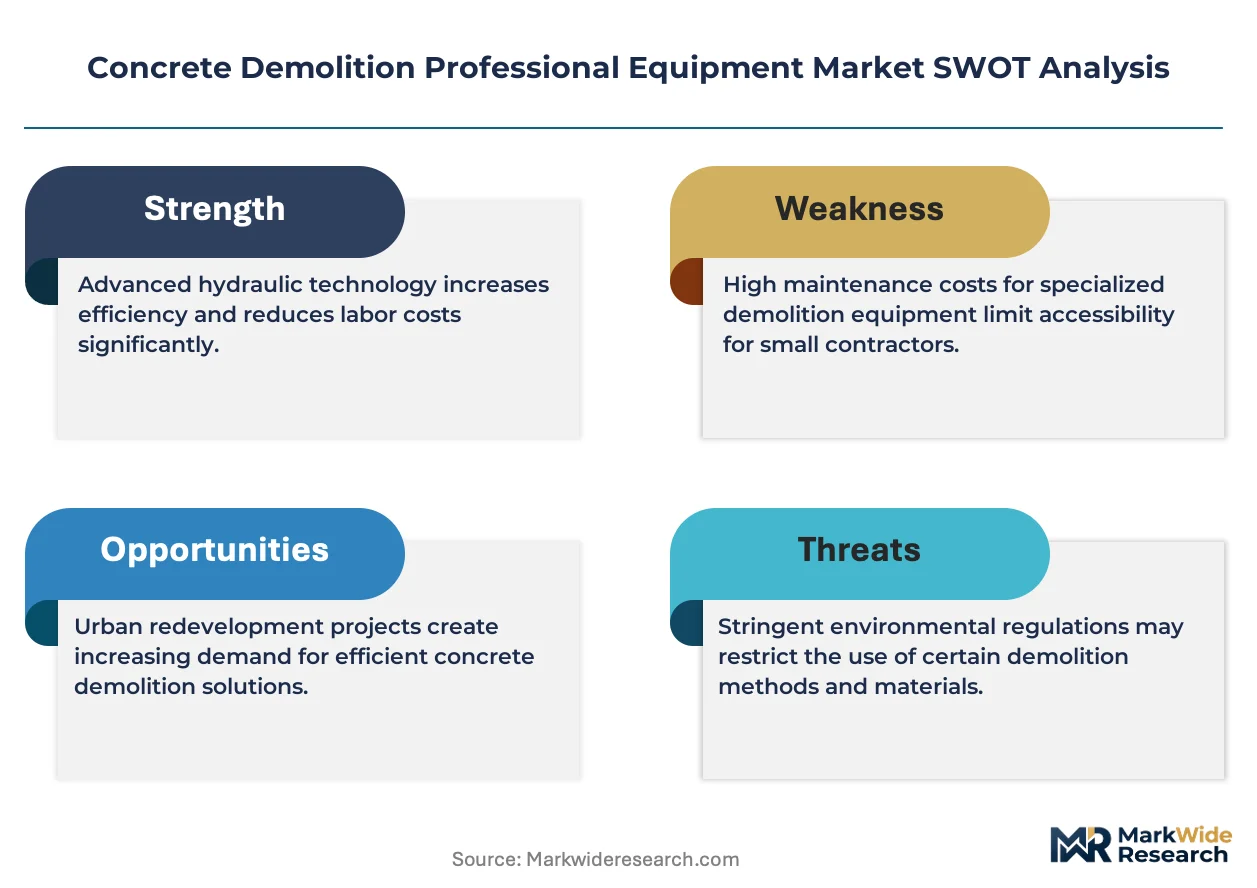
- Bridge replacement programs:Federal infrastructure spending in the United States prioritizes highway reconstruction and aging bridge demolition, channeling fleet procurement toward high-impact hydraulic breakers.
- OSHA silica compliance:Vacuum-assisted dust suppression systems are becoming mandatory specification elements on public works contracts, expanding addressable equipment value per unit.
- Urban renewal acceleration:Municipal redevelopment authorities in major metropolitan areas are consolidating demolition contracts, creating volume demand for precision fragmentation equipment.
Market Restraints
- Steel and hydraulic component costs:Volatility in alloy steel prices and specialized hydraulic cylinder supply from concentrated European and Japanese suppliers compresses manufacturer margins.
- Battery energy density limitations:Current lithium-ion cell chemistry restricts operational duration of electric breakers on remote sites lacking grid access, constraining adoption outside urban cores.
- EPA certification timelines:Extended testing protocols for Tier 4 Final and emerging state zero-emission mandates delay product launch schedules by 12-18 months.
Strategic Opportunities
- Fuel cell powertrains:Hydrogen fuel cell integration for heavy-class breakers offers zero-emission operation with refueling speed comparable to diesel, addressing range limitations of battery-electric systems.
- Tunnel excavation specialization:Confined-space carrier configurations for metro and utility tunnel projects command premium pricing and long-term service contracts.
- Machine-to-machine telemetry:Integrated fleet uptime monitoring enables predictive maintenance revenue streams and equipment-as-a-service models for large contractors.
Industry Challenges
- Certified operator scarcity:OSHA silica compliance training and specialized hydraulic breaker operation certification programs face instructor bottlenecks, slowing workforce expansion.
- Legacy fleet integration:Retrofitting dust suppression and telematics onto existing carrier platforms requires engineering customization that fragments service protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Demolition Professional Equipment Market |
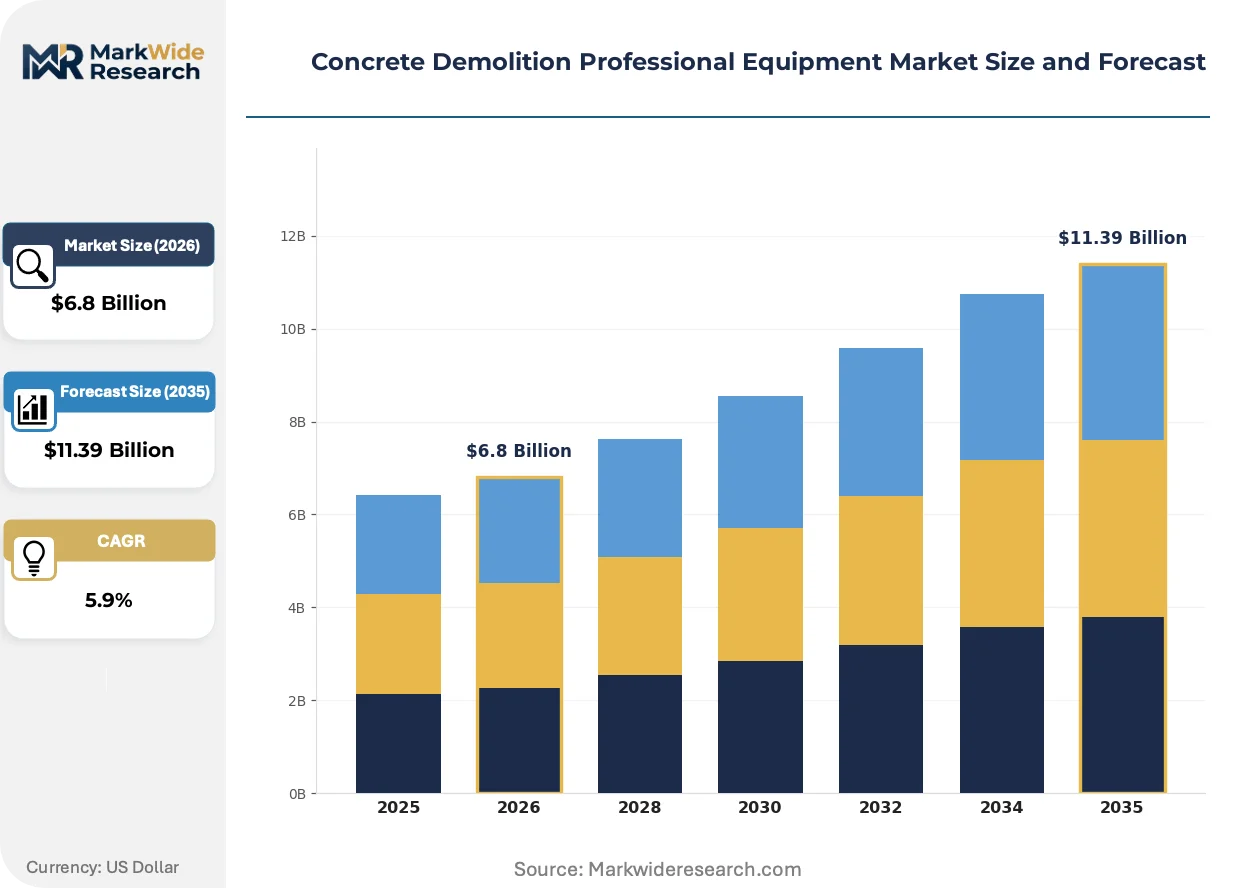
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Hydraulic Breakers, Rotary Drills, Wrecking Balls, Concrete Saws, Pulverizers Technology: Pneumatic, Hydraulic, Electric, Pneumatic-Electric Hybrid, Fuel Cell Application: Bridge Demolition, Road Removal, Building Dismantling, Industrial Plant Clearance, Tunnel Excavation End User: Construction Contractors, Infrastructure Developers, Mining Companies, Civil Engineering Firms |
| Companies Covered | Komatsu, Doosan, Caterpillar, Liebherr, JCB, Hitachi, Volvo Construction Equipment, Hyundai, Kobelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Demolition Professional Equipment Market Trends and Innovations
Electrification and dust suppression technologies are converging to redefine equipment specifications, while procurement patterns shift toward integrated fleet management systems that bundle hardware with uptime guarantees.
Electric powertrains for hydraulic breakers are absorbing specification share in urban emission-restricted zones where diesel operation faces municipal procurement bans. Infrastructure contractors in California and New York are piloting battery-electric units for bridge deck removal, though operational range constraints limit deployment to grid-accessible sites. This technology absorption is compressing the addressable market for conventional diesel breakers in metropolitan cores.
EPA Tier 4 Final and California Air Resources Board zero-emission mandates are accelerating hybrid and electric powertrain development timelines. Equipment manufacturers must now certify simultaneous compliance with federal emission standards and municipal electrification preferences that diverge in implementation schedules. Large fleet operators are responding by consolidating procurement specifications around the stricter standard to simplify cross-jurisdictional deployment.
Rental and leasing channels are capturing share from direct equipment purchases as contractors seek to transfer regulatory compliance risk and residual value uncertainty to fleet providers. National rental companies are expanding specialized demolition equipment inventories and bundling operator training with equipment access. This channel shift is most pronounced in the United States, where federal infrastructure volatility makes long-term capital commitment less attractive to mid-sized contractors.
Concrete Demolition Professional Equipment Market Segmentation
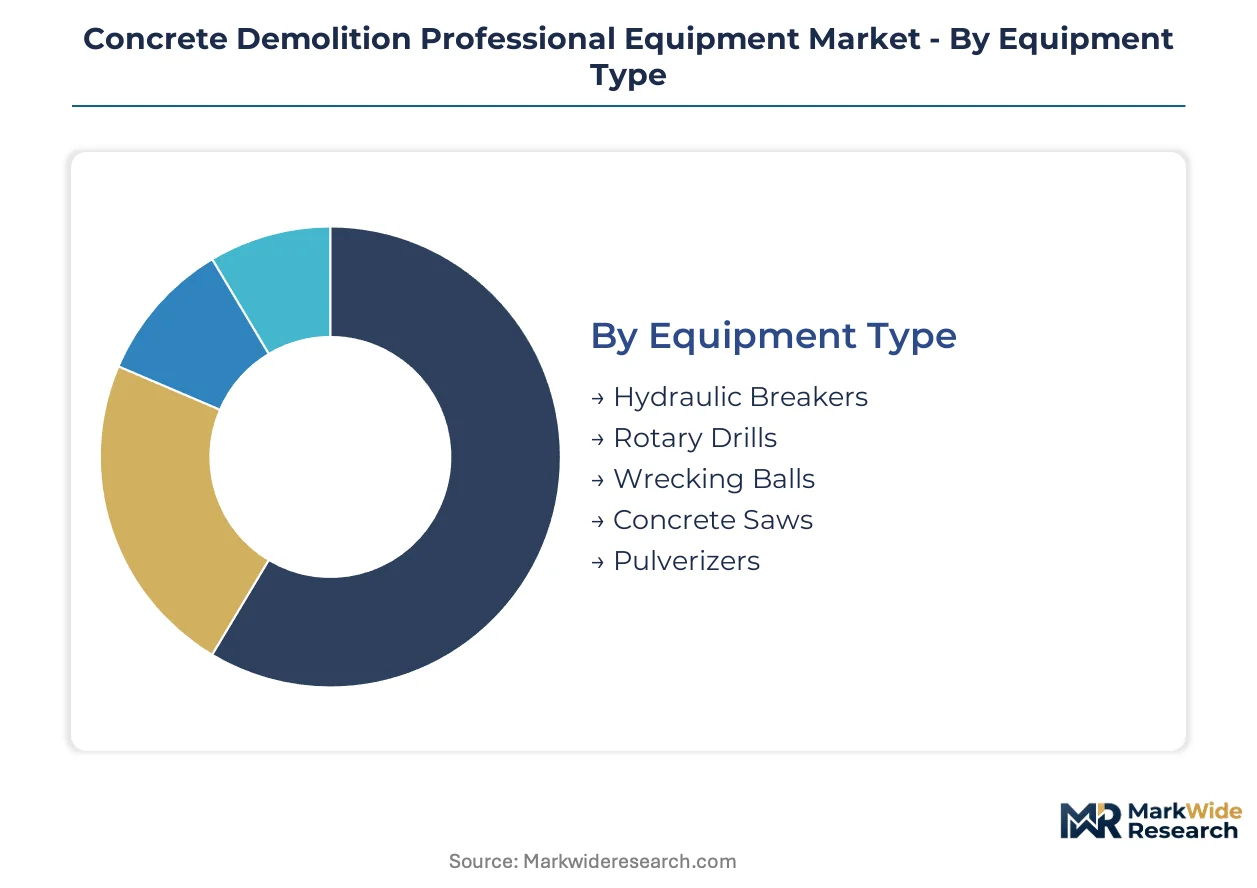
Segmentation in concrete demolition equipment reveals how regulatory pressure and application specialization fragment procurement patterns. Contractors configure fleets around OSHA silica mandates, EPA emission tiers, and project-specific fragmentation requirements rather than universal specifications.
Equipment Type:
Certification burdens vary sharply by equipment type. Hydraulic breakers face EPA Tier 4 Final engine certification plus OSHA silica dust suppression validation. Wrecking balls operate under simpler crane safety protocols without emission testing. Rotary drills and concrete saws trigger additional electrical safety certifications when specified in electric configurations.
- Hydraulic Breakers:These systems deliver impact energy from 500 to 12,000 joules through carrier-mounted hydraulic circuits. Bridge demolition contractors in the United States specify high-impact classes for reinforced concrete fracturing, driven by federal highway reconstruction spending and precision fragmentation requirements for material recovery.
- Concrete Saws:Diamond-blade cutting systems enable controlled slab sectioning with minimal vibration transmission to adjacent structures. Urban renewal projects in metropolitan cores favor electric variants to comply with municipal procurement bans on diesel operation in emission-restricted zones.
- Rotary Drills:Percussion drilling systems for pre-weakening concrete matrices prior to breaker deployment.
- Wrecking Balls:Suspended mass demolition for unreinforced masonry and low-precision clearance applications.
- Pulverizers:Jaw-based concrete crushing attachments for on-site material processing and aggregate reuse.
Leading the category by volume: Hydraulic Breakers. Growing fastest: Concrete Saws.
Technology:
Technology selection determines upfront capital outlay and operational cost structure. Pneumatic systems carry lower acquisition costs but tether operators to compressor infrastructure. Fuel cell configurations command premium pricing while eliminating diesel emission compliance entirely.
- Hydraulic:Dominant power transmission using pressurized fluid circuits integrated with diesel or electric prime movers. Infrastructure developers in the United States anchor fleet procurement around hydraulic systems for bridge replacement programs, constrained by EPA certification timelines that delay product launches.
- Electric:Battery-electric or grid-tethered systems eliminating tailpipe emissions at point of operation. California and New York contractors pilot these units for bridge deck removal, though lithium-ion energy density limits operational duration on remote sites lacking grid access.
- Pneumatic:Compressed air power for rotary drilling in tunnel excavation where spark suppression matters.
- Pneumatic-Electric Hybrid:Dual-mode systems switching between compressor and battery power for operational flexibility.
- Fuel Cell:Hydrogen fuel cell integration offering zero-emission operation with refueling speed comparable to diesel.
Hydraulic systems retain the largest installed base. Electric configurations are climbing the fastest as municipal procurement bans expand.
Application:
Application specificity dictates carrier configuration complexity and pricing tier. Tunnel excavation demands confined-space engineering with specialized ventilation integration. Bridge demolition requires precision fragmentation to protect structural elements scheduled for retention.
- Bridge Demolition:Controlled deconstruction of reinforced concrete superstructures and substructures with precision fragmentation protocols. Federal infrastructure spending in the United States channels the largest equipment procurement volumes toward this application, with OSHA silica compliance mandating vacuum-assisted dust suppression.
- Tunnel Excavation:Confined-space carrier configurations for metro and utility tunnel projects with specialized ventilation and operator protection systems. Premium pricing and long-term service contracts characterize this segment due to engineering complexity and safety certification requirements.
- Road Removal:Highway and pavement surface demolition for reconstruction or widening projects.
- Building Dismantling:Urban structure takedown with debris management and adjacent property protection.
- Industrial Plant Clearance:Chemical and manufacturing facility demolition with hazardous material protocols.
Bridge demolition commands the greatest equipment value. Tunnel excavation shows the steepest expansion trajectory.
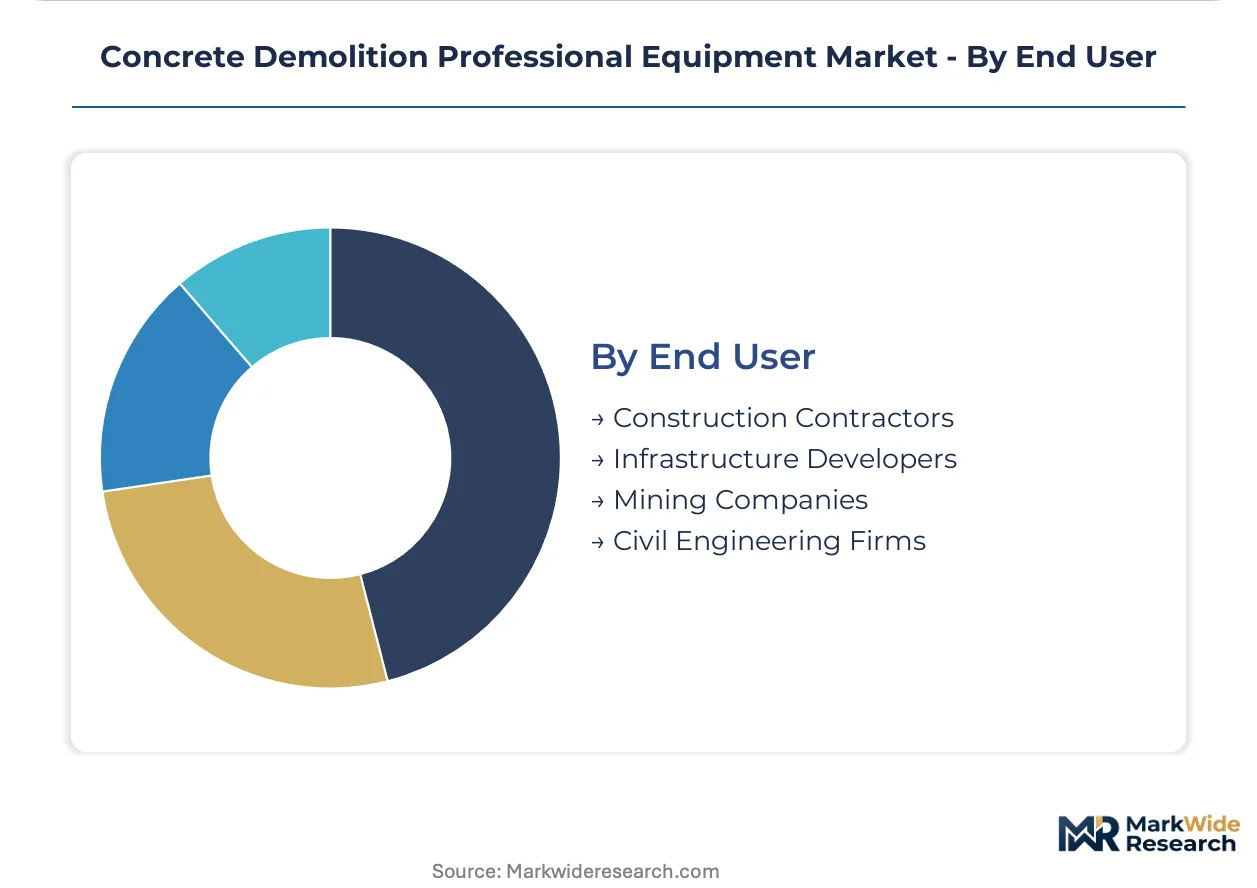
End User:
End user type shapes procurement channel preference and fleet management sophistication. Infrastructure developers consolidate large-scale purchases with integrated telemetry requirements. Construction contractors increasingly shift toward rental channels to transfer regulatory compliance risk.
- Construction Contractors:General demolition and building dismantling specialists operating mixed fleets across project types. Mid-sized contractors in the United States are accelerating rental channel adoption to avoid residual value uncertainty from emission regulation shifts.
- Infrastructure Developers:Large-scale highway, bridge, and tunnel project owners with consolidated procurement specifications. These entities bundle machine-to-machine telemetry requirements with uptime guarantees, favoring integrated fleet management systems over discrete equipment purchases.
- Mining Companies:Open-pit and underground extraction operations with demolition requirements for overburden and infrastructure.
- Civil Engineering Firms:Design-build contractors with in-house demolition capabilities for project delivery integration.
Infrastructure developers lead end user spending. Construction contractors represent the fastest-growing channel as rental penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany, Japan, and South Korea, while consumption tilts toward the United States, China, and India where infrastructure renewal accelerates fleet procurement. This geographic split shapes trade flows and certification requirements across regulatory jurisdictions.
United States
Federal infrastructure spending channels the largest equipment procurement volumes toward bridge replacement and highway reconstruction programs. OSHA silica exposure limits and EPA Tier 4 Final emissions rules compress replacement cycles for diesel-powered breakers. Texas and California metropolitan areas anchor demand for dust-suppressed and electric-configured systems under municipal procurement bans.
Germany
Precision engineering capabilities support specialized carrier configurations for tunnel excavation and confined-space demolition. REACH chemical regulations and EU Green Deal emission targets accelerate hydrogen fuel cell integration for heavy-class breakers. The Ruhr industrial corridor and Bavarian manufacturing clusters concentrate R&D investment in hybrid powertrain development.
China
Urban renewal in tier-one cities drives specification share for electric and dust-suppressed equipment under municipal air quality mandates. MIIT industrial standards and dual carbon goals pressure manufacturers toward electrified product lines. Yangtze River Delta construction equipment clusters supply domestic infrastructure developers while expanding export capacity to Southeast Asia.
Japan
Advanced hydraulic component manufacturing anchors supply chains for high-impact breaker systems. METI energy efficiency standards and JIS certification protocols shape product development timelines for domestic and export markets. Osaka-Kobe industrial zones specialize in compact carrier configurations for seismic retrofit demolition applications.
India
Metro rail expansion and smart city programs generate demand for precision fragmentation equipment in dense urban cores. BIS equipment safety standards and state-level construction emission norms create fragmented compliance requirements. Maharashtra and Karnataka infrastructure contractors consolidate fleet purchases around rental channel access to transfer regulatory risk.
Concrete Demolition Professional Equipment Market Competitive Landscape
Top-tier vendors anchor highway reconstruction and large-scale infrastructure contracts, while mid-tier specialists capture urban renewal and rental channel volume. The vendor base stratifies across integrated construction equipment conglomerates, hydraulic component specialists, and regional fabrication houses serving localized procurement preferences. Strategic archetypes include telemetry-integrated fleet providers, dust-suppression technology licensors, and fuel cell powertrain developers. Competitive positioning depends on EPA certification speed and dealer network density for aftermarket service capture.
Within the integrated equipment tier, Caterpillar and Komatsu occupy positions exemplifying divergent competitive vectors: Caterpillar leverages North American dealer density for highway reconstruction contract anchoring, while Komatsu represents machine-to-machine telemetry integration for fleet uptime guarantees. Doosan sits among Korean-based fabricators competing on hydraulic system cost engineering for mid-market contractors. These three companies illustrate how geographic origin and corporate structure map to distinct strategic archetypes in a market where regulatory compliance speed determines specification capture.
| Leading Market Players |
|---|
| Komatsu |
| Doosan |
| Caterpillar |
| Liebherr |
| JCB |
| Hitachi |
| Volvo Construction Equipment |
| Hyundai |
| Kobelco |
| Others |
Pricing and Supply Chain Analysis
EPA Tier 4 Final certification gates both qualified supply and premium-tier pricing access, as manufacturers lacking emission-compliant powertrains face exclusion from federal infrastructure contracts while certified suppliers command pricing premiums on dust-suppressed and electrified configurations.
Pricing Analysis
Margin tightening in mid-tier hydraulic breakers reflects alloy steel cost volatility and extended EPA certification timelines that compress manufacturer returns. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-integrated fleet packages from basic breaker attachments and rental-channel units. Pricing pressure stems from lithium-ion battery cost curves and municipal procurement bans favoring electric configurations. Infrastructure developers show lowest price sensitivity due to uptime guarantee requirements, while mid-sized contractors exhibit highest sensitivity as rental channel penetration deepens.
Supply Chain Analysis
Certified hydraulic technician shortages in Germany, Japan, and South Korea constrain production scaling for specialized breaker systems. Manufacturing draws from concentrated European and Japanese suppliers for alloy steel castings and precision hydraulic cylinders. Single-source vulnerability persists for high-pressure hydraulic seals sourced from Osaka-Kobe industrial zones. Distribution runs through OEM dealer networks in North America and rental company procurement consortia for mid-market contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA silica compliance operates as a cost-of-compliance moat, elevating capital requirements for dust-suppression engineering and vacuum-assisted cab integration that filters out undercapitalized competitors.
For Market Incumbents: Acquire specialized dust-suppression technology licensors to consolidate intellectual property around enclosed operator cab systems. Deepen backward integration into hydraulic cylinder manufacturing to offset European supplier concentration risk. Anchor fleet management contracts with integrated telemetry that locks in long-term service revenue against emerging equipment-as-a-service entrants. For New Entrants and Emerging Players: Capture rental channel volume in Texas and California metropolitan areas where municipal procurement bans on diesel equipment create immediate specification gaps. Target fuel cell powertrain development for heavy-class breakers to bypass battery energy density constraints that limit incumbent electric offerings. Lead with operator training bundling to differentiate against established OEMs lacking certified instructor networks. For Investors and Strategic Acquirers: EPA certification backlog clearance is the leading indicator that manufacturing capacity will tighten and pricing power will shift toward compliant suppliers. Five-to-ten year viability favors vertically integrated fabricators with captive hydraulic component supply and established dealer service networks. Watch for state-level zero-emission mandate acceleration as the signal for fuel cell powertrain valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Tier 4 Final Certification Investment | Unlocks federal infrastructure contract eligibility and anchors premium pricing tiers. |
| Hydraulic Component Backward Integration | Reduces exposure to concentrated Japanese and European supplier bottlenecks. |
| Fuel Cell Powertrain Development | Addresses battery range limitations for remote bridge demolition sites under emission mandates. |
| Machine-to-Machine Telemetry Platform | Enables predictive maintenance revenue streams and equipment-as-a-service models. |
| Certified Operator Training Network | Captures rental channel differentiation while addressing OSHA compliance instructor shortages. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with equipment fleet managers, demolition contractors, OEM procurement directors, and aftermarket service heads. Bottom-up triangulation cross-validated unit shipment data from Association of Equipment Manufacturers reports with EPA certification databases and import records. Top-down reconciliation applied infrastructure spending allocations from federal budget disclosures.
Reconciliation of equipment shipment volumes, rental fleet utilization rates, and project backlog indices informed the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, powertrain technology, application specificity, and end-user procurement channel. CAGRs derived from regression analysis of historical replacement cycles against regulatory compliance deadlines and federal spending authorization trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density breakthroughs and municipal electrification mandate acceleration. Forecasts reflect assumptions around EPA certification timeline stability and alloy steel price normalization. A small set of triggers—including state-level zero-emission mandate adoption speed and hydrogen refueling infrastructure deployment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
United States Crane Market
Construction Equipment
CNC Machine Market
Construction Equipment
Tower Crane Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
TBR Hydraulic Curing Press Market