
 Mini Cranes Market | 2026-2036
Mini Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Cranes Market Outlook
ISO 4309 crane rope inspection certification is collapsing the vendor landscape by disqualifying smaller assemblers who lack in-house metallurgical testing. Maeda Seisakusho Co., Ltd. dominates crawler-type mini crane production with captive forging operations in Osaka. Böcker Maschinenwerke GmbH differentiates through German-engineered stabilization systems for uneven terrain. UNIC Cranes Europe anchors distribution across Nordic markets with localized service depots.
Mini cranes are self-propelled or stationary lifting machines with rated capacities typically below 10 tonnes, utilizing telescopic or lattice booms mounted on compact chassis for maneuverability in confined spaces. Electric mini cranes are capturing margin pools in indoor warehousing as lithium-ion powertrains eliminate exhaust ventilation costs. Hydraulic mini cranes sustain dominance in outdoor construction where instantaneous power density matters more than emissions compliance. Truck mounted mini cranes occupy a mature niche serving utility contractors requiring rapid highway transit between job sites.
OSHA crane operator certification requirements in the United States and CE machinery directives in Europe enforce divergent control-system standards that fragment product development roadmaps. Japan's METI energy-efficiency benchmarks for compact construction equipment are accelerating R&D investment in regenerative hoist drives. Stakeholders must monitor how emerging urban noise ordinances in major metropolitan areas redefine acceptable decibel thresholds for overnight equipment operation.
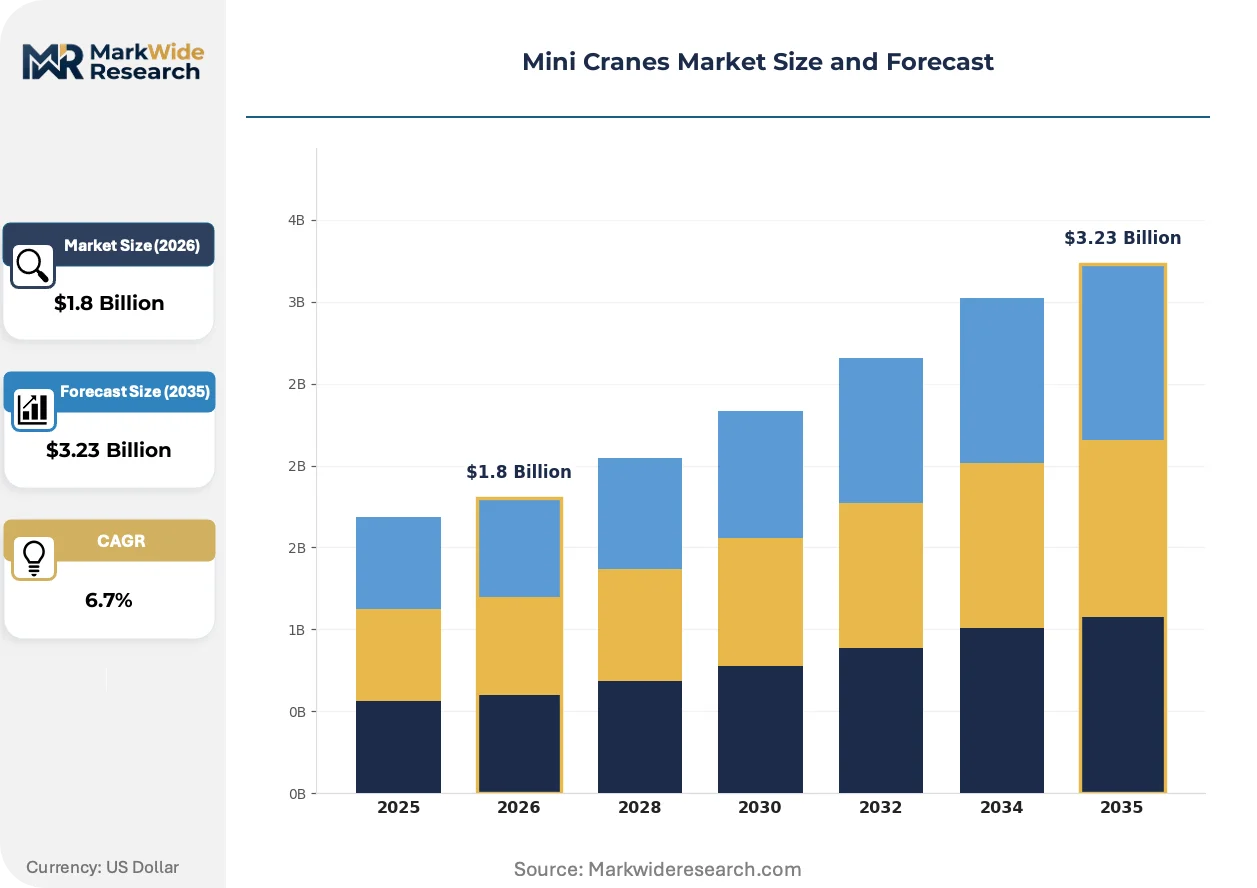
Market Dynamics
Urban emission mandates are compressing diesel mini crane lifecycles while forcing fleet operators toward electrified alternatives. Equipment procurement decisions now hinge on municipal noise ordinances and indoor air quality thresholds rather than lifting capacity alone.
Growth Catalysts
- Japan's METI energy-efficiency benchmarks:Compact construction equipment standards are accelerating regenerative hoist drive adoption across Tokyo-Osaka infrastructure corridors.
- Warehousing automation:E-commerce fulfillment centers in dense European city centers require exhaust-free lithium-ion mini cranes to eliminate ventilation infrastructure costs.
- Aging infrastructure renewal:Japan's metropolitan corridor demands compact lifting equipment for bridge rehabilitation and utility tunnel maintenance in confined rights-of-way.
Market Restraints
- ISO 4309 rope certification barriers:In-house metallurgical testing requirements disqualify smaller assemblers from supplying certified crawler-type units.
- Lithium-ion cell supply concentration:Battery pack sourcing depends on concentrated East Asian cell manufacturing, exposing European assemblers to input volatility.
- Hydraulic fluid disposal regulations:Germany's KBA vehicle certification adds compliance layers for traditional powertrain mini cranes serving outdoor construction.
Strategic Opportunities
- France's ANSM urban equipment safety directives:Stabilization system mandates for uneven terrain create premium positioning for German-engineered chassis designs.
- Nordic localized service networks:Maintenance-depot density gaps in Norway, Sweden, and Finland reward distributors building captive technical support infrastructure.
- Regenerative drive convergence:Integration of energy-recovery hoists with telematics platforms enables outcome-based equipment leasing for municipal contractors.
Industry Challenges
- OSHA-CE control system divergence:Fragmented certification timelines force parallel product development tracks for US and European operator interface standards.
- Metallurgical testing capex:Captive forging and rope inspection facilities require capital deployment that mid-scale assemblers cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Cranes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Mini Cranes, Hydraulic Mini Cranes, Truck Mounted Mini Cranes, Folding Mini Cranes Application: Construction Sites, Warehousing, Landscaping, Urban Interior Projects End User: Contractors, Event Planners, Tree Care Professionals, Manufacturing Facilities Technological Feature: Remote Control, Compact Design, All-Terrain Capability, Safety Mechanism |
| Companies Covered | Maeda Seisakusho Co., Ltd., UNIC Cranes Europe, Jekko S.p.A., BG Lift, Hoeflon International B.V., Furukawa UNIC Corporation, Kato Works Co., Ltd., Manitex International Inc., Böcker Maschinenwerke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Cranes Market Strategic Shifts
Powertrain architectures are splitting along indoor-outdoor operational boundaries, with distinct technical specifications emerging for warehouse versus construction site deployment. Control system standardization is fragmenting across Atlantic regulatory jurisdictions.
Electrification is bifurcating mini crane product architectures. Lithium-ion powertrains serve indoor warehousing where instantaneous torque and zero emissions justify battery weight penalties. Hydraulic systems sustain outdoor construction dominance where power density and rapid refueling compress project timelines. The technology split is enabling distinct pricing tiers and service models rather than unified platform strategies.
France's ANSM urban equipment safety directives are mandating terrain-adaptive stabilization systems for street-deployed mini cranes. The regulation forces redesign of outrigger geometry and load-moment limiting algorithms. German-engineered chassis configurations are capturing specification premiums as municipal contractors in Paris, Lyon, and Marseille retrofit fleets for compliance.
Rental procurement is displacing ownership among European urban contractors facing emission compliance uncertainty. Equipment-as-a-service models bundle maintenance and certification updates, transferring regulatory risk from operators to lessors. The shift concentrates most visibly in Germany's dense city centers where diesel ban phases remain politically volatile.
Mini Cranes Market Segmentation
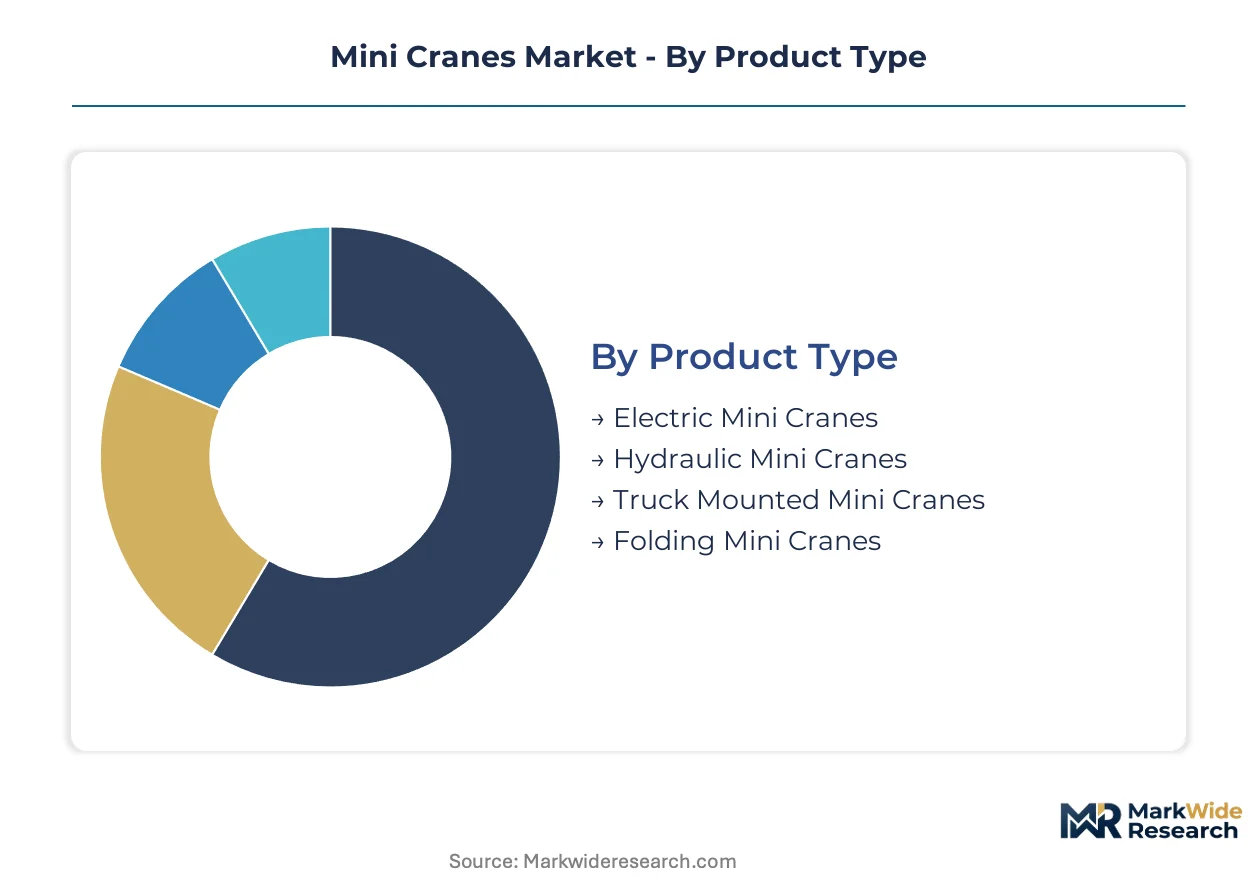
Mini crane segmentation reveals divergent margin structures across powertrain technologies and operational environments. Procurement patterns split sharply between indoor electrification mandates and outdoor hydraulic dominance.
Product Type:
Margin pools concentrate in electric configurations where lithium-ion powertrains command specification premiums for indoor compliance.
- Electric Mini Cranes:Battery-powered units utilizing lithium-ion cells and regenerative hoist drives eliminate exhaust ventilation infrastructure. Demand clusters in European e-commerce fulfillment centers facing tightening indoor air quality thresholds.
- Hydraulic Mini Cranes:Diesel or biofluid-powered systems deliver instantaneous torque density for outdoor lifting operations. Germany's KBA vehicle certification requirements and France's ANSM stabilization mandates reshape chassis specifications for street-deployed units.
- Truck Mounted Mini Cranes:Highway-transit configurations serve utility contractors requiring rapid job-site mobility.
- Folding Mini Cranes:Collapsible boom geometries enable transport through constrained urban rights-of-way.
The dominant share belongs to Hydraulic Mini Cranes, while Electric Mini Cranes is closing the gap fastest.
Application:
Volume distribution tracks urbanization density and infrastructure renewal cycles across metropolitan corridors.
- Construction Sites:Bridge rehabilitation, facade maintenance, and utility tunnel projects in Japan's Tokyo-Osaka corridor drive specification requirements for confined-space maneuverability.
- Warehousing:E-commerce fulfillment automation demands exhaust-free lifting equipment to eliminate ventilation capital expenditure.
- Landscaping:Tree care and terrain modification applications favor compact crawler configurations.
- Urban Interior Projects:Building renovation and equipment installation inside occupied structures requires noise-compliant electric units.
Construction Sites retains the largest procurement volume, though Warehousing is expanding most quickly.
End User:
Customer type determines service model preferences and certification burden allocation.
- Contractors:Municipal and general construction firms face divergent OSHA and CE operator certification requirements that fragment fleet standardization.
- Event Planners:Temporary rigging applications prioritize rapid deployment and strike capabilities over lifting capacity specifications.
- Tree Care Professionals:Arborist contractors require compact crawler units with terrain-adaptive stabilization for uneven ground conditions.
- Manufacturing Facilities:In-plant maintenance departments specify electric mini cranes to comply with indoor air quality and noise ordinances.
Contractors account for the predominant procurement base, with Manufacturing Facilities gaining share fastest.
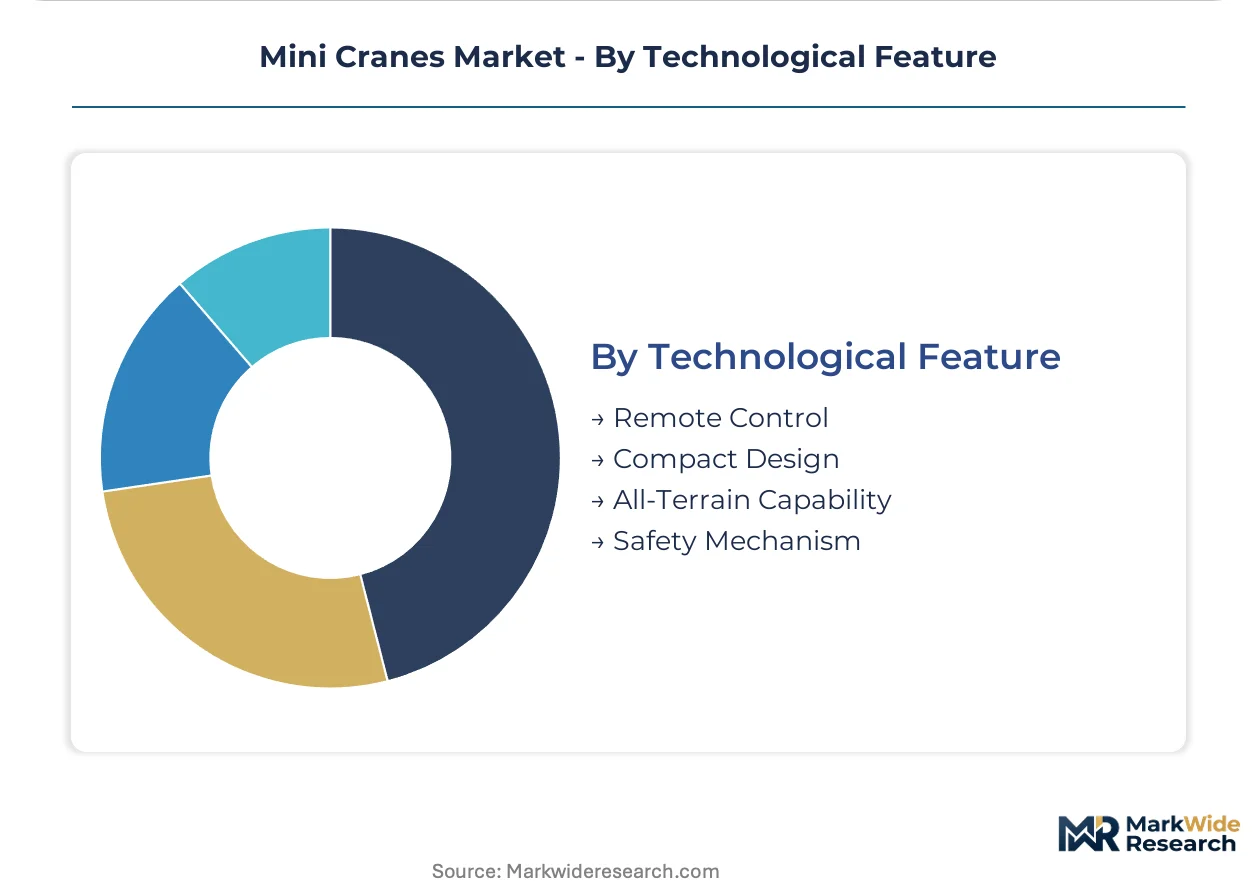
Technological Feature:
Feature adoption correlates with regulatory jurisdiction and labor cost structures.
- Remote Control:Wireless operator interfaces enable precision positioning in hazardous or confined environments while reducing labor exposure.
- Compact Design:Reduced swing radius and transport dimensions unlock access to Japan's dense metropolitan construction corridors.
- All-Terrain Capability:Outrigger geometry and load-moment limiting algorithms satisfy France's ANSM urban equipment safety directives for uneven terrain deployment.
- Safety Mechanism:Anti-two-block systems and automatic overload protection address CE machinery directive and OSHA certification requirements.
Compact Design holds the dominant specification share, while Remote Control is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI energy-efficiency benchmarks for compact construction equipment are accelerating fleet electrification across metropolitan infrastructure corridors. Germany's KBA vehicle certification and France's ANSM urban equipment safety directives are reshaping procurement specifications for street-deployed units.
Japan
Aging bridge rehabilitation and utility tunnel maintenance drive demand along the Tokyo-Osaka metropolitan corridor. METI energy-efficiency benchmarks mandate regenerative hoist drives on new equipment procurements. Equipment clusters concentrate in Osaka's industrial belt where captive forging operations supply crawler-type chassis components.
Germany
Urban emission mandates in Berlin, Munich, and Hamburg compress diesel mini crane lifecycles toward electrified alternatives. KBA vehicle certification requirements add compliance layers for hydraulic powertrain disposal and stabilization system validation. Bavaria-based engineering firms capture specification premiums for terrain-adaptive chassis designs.
France
ANSM urban equipment safety directives mandate redesigned outrigger geometry and load-moment limiting algorithms for street deployment. Municipal contractors in Paris, Lyon, and Marseille retrofit fleets to satisfy uneven terrain stabilization mandates. Rental procurement displaces ownership as diesel ban phases remain politically volatile in dense city centers.
United States
OSHA crane operator certification requirements enforce control-system standards that diverge from European CE machinery directives. Utility contractors in Texas, California, and the Northeast Corridor specify truck-mounted configurations for rapid highway transit between job sites. Manufacturing facilities in the Midwest specify electric units to comply with indoor air quality ordinances.
Italy
Event planning and temporary rigging applications in Rome, Milan, and Naples prioritize rapid deployment capabilities over lifting capacity specifications. CE machinery directive compliance shapes operator interface standardization for equipment serving renovation projects in historic urban cores. Compact crawler units serve arborist contractors in Tuscany and Lombardy requiring terrain-adaptive stabilization.
Mini Cranes Market Competitive Environment
Player mix skews toward specialized engineering houses with captive manufacturing capabilities rather than diversified industrial conglomerates. Market structure concentrates around three strategic archetypes: Japanese integrated manufacturers with in-house forging operations, German precision-engineering specialists focused on stabilization systems, and European distribution networks with localized service infrastructure. Competitive moves center on vertical integration into metallurgical testing to satisfy ISO 4309 rope certification requirements, and geographic expansion of maintenance depot networks to capture rental procurement growth.
Among Japanese integrated manufacturers, Maeda Seisakusho Co., Ltd. and Kato Works Co., Ltd. exemplify the captive production archetype with Osaka-based forging operations. Within the German engineering tier, Böcker Maschinenwerke GmbH occupies a position defined by terrain-adaptive stabilization expertise. UNIC Cranes Europe represents the distribution-network archetype, anchoring Nordic market presence through localized technical support infrastructure rather than manufacturing concentration.
| Leading Market Players |
|---|
| Maeda Seisakusho Co., Ltd. |
| UNIC Cranes Europe |
| Jekko S.p.A. |
| BG Lift |
| Hoeflon International B.V. |
| Furukawa UNIC Corporation |
| Kato Works Co., Ltd. |
| Manitex International Inc. |
| Böcker Maschinenwerke GmbH |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles for lithium-ion battery packs constrain European assemblers' pricing flexibility while Japanese integrated manufacturers exploit Osaka-based captive forging to compress lead times. This divergence between input sourcing geography and downstream certification requirements creates asymmetric margin pressure across competitor archetypes.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 4309-compliant crawler-type units commanding specification premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation in metallurgical testing depth, stabilization system sophistication, and after-sales service bundling. Cost compression in economy-tier hydraulic units is intensifying because Germany's KBA vehicle certification adds compliance layers without corresponding feature premiums. Municipal contractors in dense European city centers exhibit highest price sensitivity due to rental procurement displacement, while Japanese infrastructure renewal projects demonstrate lowest sensitivity given METI-mandated efficiency benchmarks.
Supply Chain Analysis
Japan and Germany anchor high-value component production, with Osaka supplying crawler chassis forgings and Bavaria engineering terrain-adaptive stabilization systems. Raw material dependencies center on East Asian lithium-ion cell manufacturing, German hydraulic component foundries, and Japanese high-tensile steel rope production. Single-source vulnerability in battery pack sourcing exposes European assemblers to input volatility when cell manufacturing concentrates in concentrated East Asian facilities. Distribution runs through localized service depot networks, with UNIC Cranes Europe's Nordic infrastructure exemplifying the maintenance-density model displacing traditional dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mini cranes market represents a high-growth electrification disruption as urban emission mandates force fleet turnover toward lithium-ion alternatives. Regulatory divergence between OSHA and CE control-system standards fragments product development but creates defensive moats for multi-certified incumbents.
For Market Incumbents: Secure ISO 4309 rope certification through in-house metallurgical testing investment, disqualifying smaller assemblers from crawler-type supply. Expand captive forging capacity in Osaka to exploit Japan's infrastructure renewal corridor while acquiring terrain-adaptive stabilization IP to satisfy France's ANSM mandates. Defend against rental procurement displacement by bundling maintenance and certification updates into outcome-based equipment leasing.
For New Entrants and Emerging Players: Differentiate on regenerative hoist drive integration for municipal contractors facing METI efficiency benchmarks, targeting Japan's Tokyo-Osaka corridor where aging infrastructure demands compact lifting equipment. Exploit maintenance-depot density gaps in Nordic markets through localized technical support infrastructure rather than manufacturing concentration. Pursue white-label electric unit assembly for European e-commerce fulfillment centers eliminating ventilation infrastructure costs.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because urban emission mandates and safety directives perpetually refresh equipment replacement cycles. Acquisition targets should display captive forging operations or terrain-adaptive stabilization engineering capabilities. Monitor France's ANSM urban equipment safety directive enforcement as the inflection signal for stabilization system premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical Testing | ISO 4309 compliance collapses vendor landscape by disqualifying smaller assemblers lacking captive facilities. |
| Regenerative Hoist Drive Development | METI energy-efficiency benchmarks in Japan mandate adoption across metropolitan infrastructure corridors. |
| Localized Service Depot Expansion | Maintenance-density gaps in Nordic markets reward distributors building captive technical support infrastructure. |
| Terrain-Adaptive Stabilization Engineering | France's ANSM directives force redesign of outrigger geometry for street-deployed units in Paris and Lyon. |
| Outcome-Based Equipment Leasing | Rental procurement displacement in Germany transfers regulatory risk from operators to lessors through bundled service models. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at German municipal contractors, maintenance directors at Japanese infrastructure firms, and aftermarket service heads at Nordic distribution networks. Secondary validation drew from KBA vehicle certification filings, METI energy-efficiency benchmark disclosures, ANSM urban equipment safety directive texts, and CE machinery directive compliance databases. Bottom-up equipment shipment triangulation against top-down infrastructure investment flows anchored volume estimates.
Across the analysis window, the forecasting framework modeled powertrain technology splits, application environment boundaries, and end-user service model preferences. CAGRs derived from segment-level replacement cycle analysis, regulatory mandate phase-in schedules, and infrastructure renewal pipeline assessments. Key inputs included lithium-ion cell cost trajectory assumptions and urban emission ordinance enforcement intensity by metropolitan jurisdiction.
The analysis sits within stated boundaries; outcomes outside continued regulatory tightening on diesel emissions and sustained East Asian battery cell supply concentration would require recalibration. Forecasts reflect documented assumptions regarding METI benchmark adherence rates and ANSM directive compliance timelines. Recalibration cycles align with material shifts in municipal procurement modality and stabilization system technology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Autonomous Cranes Market
Construction Equipment
India Crane Market
Construction Equipment
Roadheaders Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Global Wheel Aligner Equipment Market