
 Roller Crusher Market | 2026-2036
Roller Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Roller Crusher Market Analytics
Mining application weight is rebalancing toward construction and chemical processing as commodity price cycles moderate. FLSmidth leverages its installed base in mineral processing to sustain aftermarket service revenue. McLanahan Corporation anchors its competitive position through specialized double-roll configurations for salt and potash operations. Thyssenkrupp competes on engineering depth in high-capacity quad-roll systems for cement raw material preparation.
A roller crusher employs two or more cylindrical rolls rotating toward each other to compress and fracture feed material, with typical roll diameters ranging from 500 mm to 2,000 mm and reduction ratios of 2:1 to 6:1 depending on ore hardness and gap setting. The equipment serves primary size reduction duties across hard rock mining, clinker grinding circuits, and coal preparation plants. Double roll configurations command the largest installed base due to proven reliability in medium-hardness applications, while hydraulic drive technology is gaining preference over mechanical alternatives for its overload protection and gap adjustment precision. Quad roll segments attract premium positioning in specialized high-throughput installations where staged reduction eliminates secondary crushing.
EPA opacity standards and MSHA dust exposure limits in the United States mandate enclosed housing and dust suppression integration, directly influencing crusher specification requirements. The EU F-Gas Regulation and REACH compliance frameworks constrain lubricant and seal material selection for equipment sold in Europe. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading impact on steel and cement customer capital cycles.
Market Dynamics
Stricter emissions mandates under the EU Industrial Emissions Directive are forcing cement and mining operators toward enclosed crushing systems with integrated dust suppression, compressing upgrade cycles for legacy open-rotor equipment across European installations.
Growth Catalysts
- Alternative fuel integration in cement kilns:Producers in India and Vietnam are expanding roller crusher capacity to process refuse-derived fuel and biomass, driving equipment procurement for clinker substitution.
- Hydraulic drive technology:Precision gap adjustment and overload protection capabilities are displacing mechanical drive systems in hard-rock mining applications where uncrushable tramp metal incidence is high.
- REACH compliance frameworks:European lubricant and seal material restrictions are accelerating replacement demand for crushers with compatible sealing architectures and synthetic fluid compatibility.
Market Restraints
- High-grade alloy steel input costs:Roll shell and bearing housing fabrication depends on chromium-molybdenum alloys with volatile pricing tied to ferrochrome concentrate supply from South Africa and Kazakhstan.
- Quad-roll system supply concentration:Engineering-intensive high-capacity quad-roll configurations remain concentrated among a limited supplier base with extended lead times for custom sizing.
- Jaw and cone crusher substitution:For extremely hard abrasive ores exceeding 250 MPa compressive strength, gyratory and cone alternatives maintain performance advantages that constrain roller crusher addressable share.
Strategic Opportunities
- Underpenetrated salt and potash segments:Specialized double-roll configurations for crystalline material handling remain underserved in Saskatchewan and Belarus extraction basins.
- Carbon border adjustment mechanism preparation:EU steel and cement customers are frontloading capital expenditure to qualify for CBAM-compliant production certificates, creating equipment upgrade pull-through.
- Remote condition monitoring convergence:Integration of vibration analysis and thermal imaging with hydraulic drive systems enables predictive maintenance contracts and aftermarket service expansion.
Industry Challenges
- Welding and metallurgical specialist scarcity:Fabrication of induction-hardened roll shells requires certified welders proficient in submerged arc and friction stir techniques that command premium labor rates.
- Legacy mechanical drive integration:Retrofitting hydraulic actuation into existing crusher footprints demands custom frame modifications that extend commissioning timelines and site downtime.
- MSHA dust exposure certification delays:Enclosed housing designs for underground coal applications face extended approval queues at the Mine Safety and Health Administration, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roller Crusher Market |
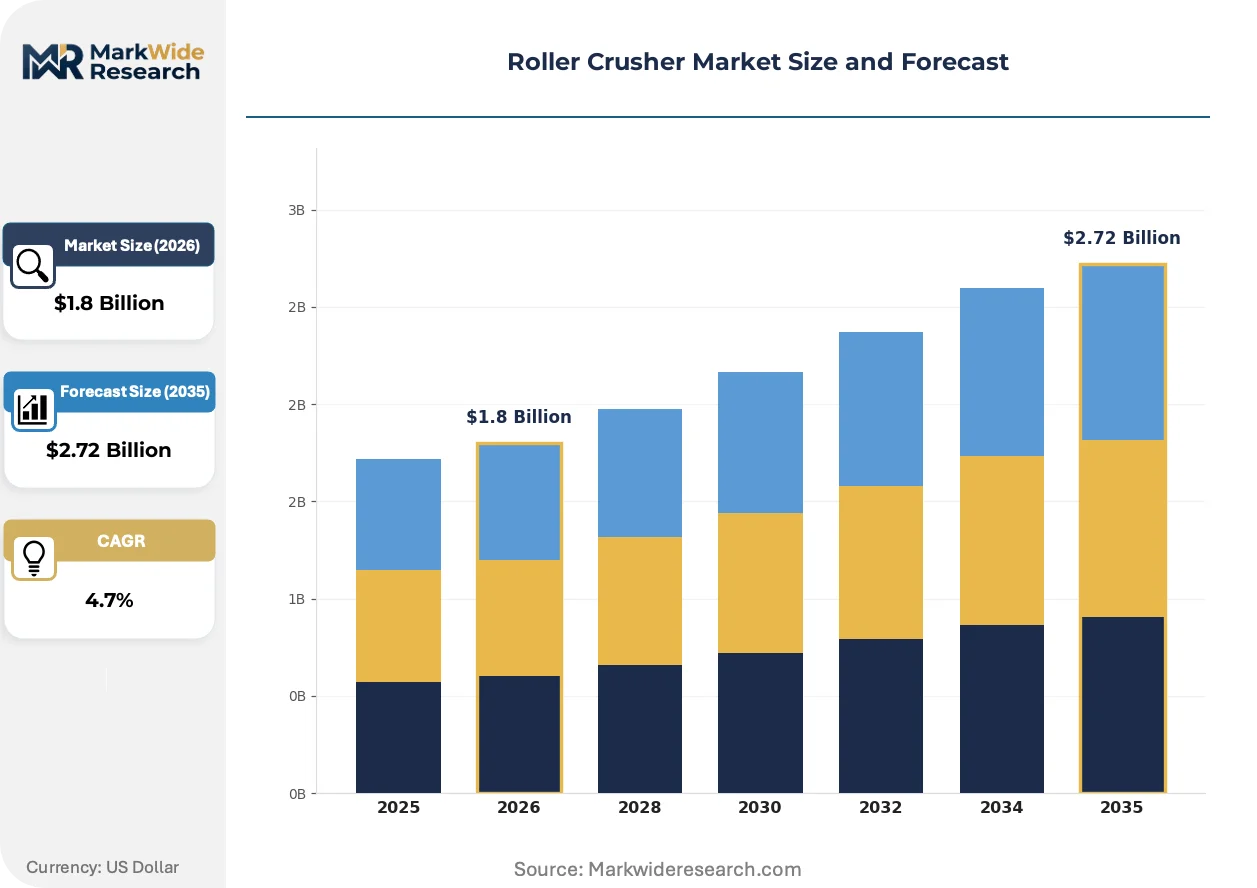
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Roll, Double Roll, Triple Roll, Quad Roll Application: Mining, Construction, Chemical Processing, Power Generation End User: Mining Companies, Construction Firms, Cement Producers, Steel Manufacturers Technology: Hydraulic Drive, Mechanical Drive, Electrical Drive, Others |
| Companies Covered | FLSmidth, McLanahan Corporation, Williams Patent Crusher and Pulverizer Co., Inc., Thyssenkrupp, TerraSource Global, Aesha Conveyors and Crushing Equipment, Ecoman India, Premur Impex Ltd., HAZEMAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roller Crusher Market Evolving Landscape
Active substitution of mechanical drive architectures with electronically controlled hydraulic systems is compressing maintenance intervals and enabling real-time process optimization across cement and mining circuits.
Hydraulic direct-drive roll crushers with variable displacement pumps and closed-loop control are overtaking traditional gearbox-and-clutch arrangements in high-tonnage installations. Cement producers in Germany and Poland are specifying these configurations for raw material preparation lines requiring frequent gap adjustments for variable clay moisture content. The technology is compressing mechanical component inventories and shifting supplier revenue toward fluid power and control system aftermarket streams.
The EU F-Gas Regulation and associated ECHA restrictions on per- and polyfluoroalkyl substances are mandating seal material transitions in equipment sold across European Economic Area member states. Crusher manufacturers must qualify hydrogenated nitrile and thermoplastic elastomer alternatives for high-temperature roll bearing environments. The segment most affected is coal preparation equipment destined for Polish and Czech underground operations, where suppliers are accelerating compatibility testing to maintain market access.
After-sales service unbundling from original equipment contracts is disrupting traditional bundled procurement in Indian mining operations. State-owned coal consumers are separating crusher supply from multi-year maintenance agreements, awarding service contracts to third-party specialists with localized spare parts warehousing. This pattern is most visible in the Singrauli and Talcher coalfields, where domestic fabrication shops are capturing rebuild and reconditioning revenue previously retained by original equipment manufacturers.
Roller Crusher Market Segmentation
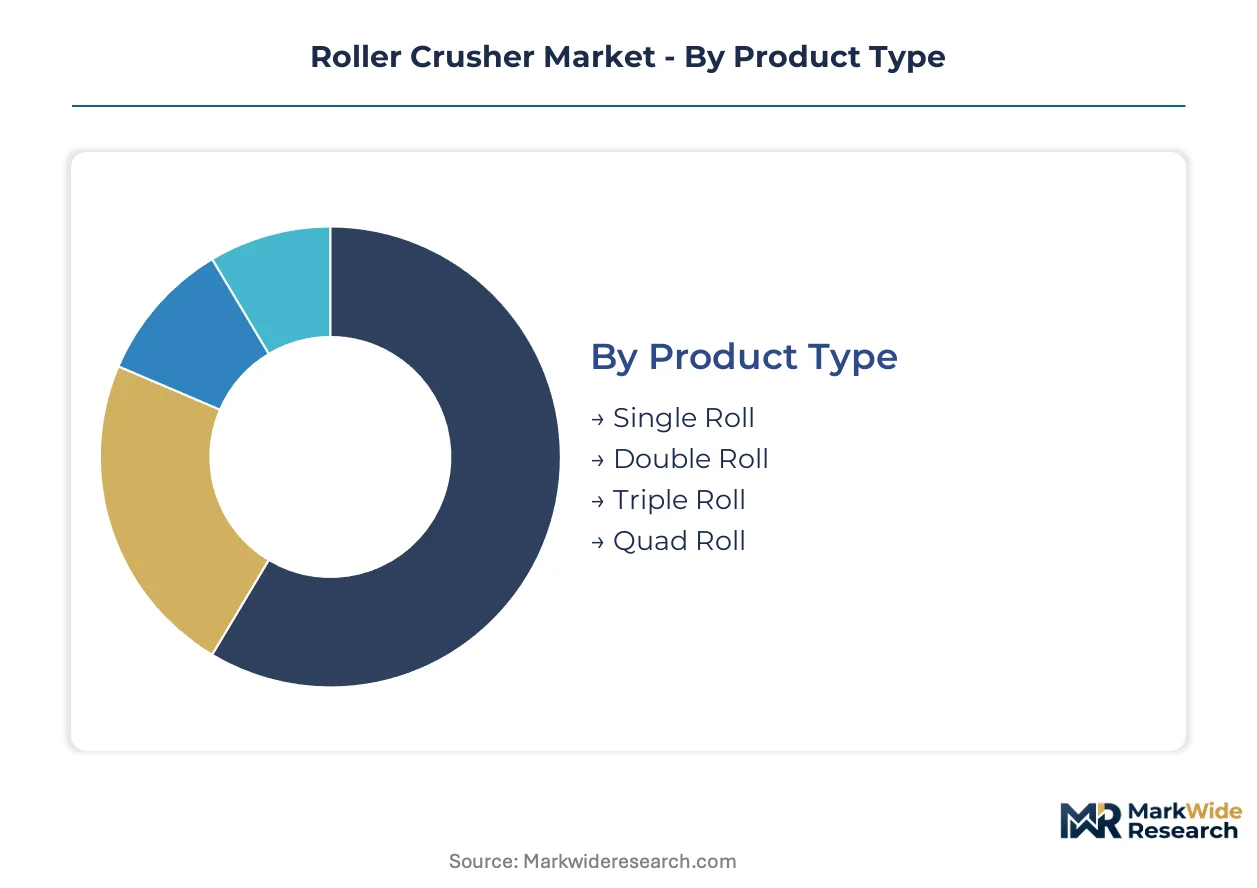
Segmentation in roller crushers reflects divergent engineering requirements across ore hardness, throughput demands, and regulatory environments. Equipment specification varies sharply between cement raw material preparation and hard-rock mining, with technology choices determining maintenance economics and operational uptime.
Product Type:
Supply concentration in roll configurations varies with engineering complexity, as multi-roll systems demand specialized fabrication capabilities that limit vendor participation.
- Double Roll:Two counter-rotating cylinders with adjustable gap settings handle medium-hardness materials at reduction ratios of 2:1 to 4:1. Cement producers in India and Vietnam specify these units for clinker and alternative fuel processing, where proven reliability outweighs premium pricing for more complex architectures.
- Quad Roll:Staged crushing across two paired roll sets achieves higher reduction ratios in a single pass, eliminating secondary crushing circuits. High-capacity installations in German and Polish cement raw material lines specify these configurations, though extended lead times from limited supplier bases constrain procurement flexibility.
- Single Roll:One roll against a stationary breaker plate suits coal and soft limestone applications with lower capital budgets.
- Triple Roll:Intermediate staging between double and quad configurations serves niche potash and salt operations requiring controlled particle shape.
Double Roll absorbs the bulk of installed capacity; Quad Roll is expanding most quickly in high-throughput cement applications.
Application:
Cost tier differentiation across applications separates premium-specification mining units from standardized construction equipment, with margin structures reflecting durability requirements and aftermarket service intensity.
- Mining:Hard-rock operations demand induction-hardened roll shells and hydraulic overload protection to process ores exceeding 150 MPa compressive strength. Australian and South African gold and platinum producers prioritize uncrushable tramp metal detection systems that prevent catastrophic roll damage.
- Chemical Processing:Crystalline material handling for salt, potash, and fertilizer production requires specialized roll surface textures that minimize fines generation. Saskatchewan extraction basins drive procurement of corrosion-resistant configurations for high-moisture brine environments.
- Construction:Aggregate producers favor mechanical drive simplicity for limestone and dolomite crushing with predictable feed characteristics.
- Power Generation:Coal preparation plants specify enclosed housing and dust suppression to meet MSHA and EPA opacity standards in underground and surface operations.
Mining absorbs the bulk of installed capacity; Chemical Processing is climbing the fastest as potash investment accelerates.
End User:
Volume concentration among end users reflects capital cycle timing, with state-owned mining enterprises and multinational cement groups driving procurement waves through synchronized expansion programs.
- Cement Producers:Clinker substitution with refuse-derived fuel and biomass demands crushers capable of processing variable moisture content and foreign material contamination. European operators under the Industrial Emissions Directive are retrofitting enclosed systems with integrated dust suppression.
- Mining Companies:Hard-rock and coal extraction operations prioritize hydraulic drive technology for real-time gap adjustment and remote condition monitoring integration. Indian state-owned coal consumers in Singrauli and Talcher coalfields are unbundling equipment supply from maintenance contracts.
- Construction Firms:Mobile and semi-mobile crushing circuits for road and infrastructure projects favor standardized double-roll configurations with rapid deployment timelines.
- Steel Manufacturers:Sinter feed preparation and coke crushing in integrated mills require high-availability systems with minimal unplanned downtime.
Cement Producers absorb the bulk of installed capacity; Mining Companies are gaining share fastest as commodity investment cycles recover.
Technology:
Customer type segmentation across technology choices separates early hydraulic adopters in premium mining applications from cost-sensitive mechanical drive users in construction aggregates.
- Hydraulic Drive:Variable displacement pumps with closed-loop electronic control enable precision gap adjustment and automatic overload protection. German and Polish cement raw material lines specify these systems for frequent adjustment to variable clay moisture, compressing mechanical inventory costs while shifting supplier revenue toward fluid power aftermarket streams.
- Mechanical Drive:Traditional gearbox-and-clutch arrangements retain cost advantages in soft-rock applications with consistent feed characteristics and low tramp metal incidence.
- Electrical Drive:Direct torque motor configurations suit underground coal operations where hydraulic fluid containment poses environmental compliance risks.
- Others:Hybrid and emerging drive architectures including electromechanical combinations serve specialized retrofit applications.
Mechanical Drive retains the bulk of legacy installed capacity; Hydraulic Drive is expanding most quickly in new high-tonnage installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for cement manufacturing are concentrating roller crusher procurement near Gujarat and Andhra Pradesh infrastructure corridors. State-backed mining expansion in Singrauli and Talcher coalfields is accelerating equipment deployment timelines.
India
Domestic mining expansion in Singrauli and Talcher coalfields is driving double-roll crusher procurement for state-owned coal consumers. The Ministry of Coal's commercial mining auctions are opening captive blocks to private operators, intensifying capital equipment competition. Cement producers in Gujarat's Special Economic Zones are retrofitting enclosed systems to process refuse-derived fuel under Central Pollution Control Board emissions guidelines.
Germany
Raw material preparation lines in North Rhine-Westphalia cement plants are specifying hydraulic direct-drive configurations for variable clay moisture processing. The EU F-Gas Regulation and Industrial Emissions Directive are mandating seal material transitions and enclosed housing retrofits. Thyssenkrupp's engineering operations in the Ruhr industrial cluster are supplying high-capacity quad-roll systems for staged reduction circuits.
United States
Coal preparation plants in Appalachia and the Powder River Basin are integrating enclosed housing designs to meet EPA opacity standards and MSHA dust exposure limits. Surface mining operations in Arizona and Nevada are prioritizing hydraulic overload protection for uncrushable tramp metal detection. TerraSource Global's fabrication network serves underground coal applications with extended MSHA certification queues compressing revenue recognition.
Poland
Cement raw material preparation facilities in the Silesian industrial region are adopting hydraulic drive technology for frequent gap adjustment capabilities. The EU F-Gas Regulation is accelerating compatibility testing for hydrogenated nitrile seal alternatives in high-temperature bearing environments. Polish underground coal operations are procuring enclosed crushing systems to satisfy ECHA restrictions on per- and polyfluoroalkyl substances.
Australia
Hard-rock gold and platinum operations in Western Australia's Kalgoorlie-Norseman belt are specifying induction-hardened roll shells with hydraulic overload protection. The country's mining safety regulators are enforcing enclosed housing standards for surface and underground crushing circuits. Perth-based engineering services are integrating remote condition monitoring with hydraulic drive systems for predictive maintenance contracts.
Roller Crusher Market Competitive Landscape
Top-tier vendors anchor high-capacity quad-roll engineering, while mid-tier fabricators compete on double-roll standardization and aftermarket service density. The supplier base concentrates around three strategic archetypes: European engineering houses with cement sector specialization, North American mining-focused system integrators, and Indian domestic fabricators capturing state-owned procurement. Competitive moves center on hydraulic drive technology licensing and geographic expansion through localized spare parts warehousing.
Within the engineering-intensive tier, Thyssenkrupp and FLSmidth occupy positions anchored by mineral processing installed bases and aftermarket service revenue streams. McLanahan Corporation exemplifies the specialized-configuration archetype through its double-roll focus. Among India-based fabricators, Aesha Conveyors and Crushing Equipment and Ecoman India represent the domestic-capture segment serving Singrauli and Talcher coalfield procurement. Premur Impex Ltd. and Williams Patent Crusher and Pulverizer Co., Inc. sit within regional fabrication tiers addressing cost-sensitive construction aggregate applications.
| Leading Market Players |
|---|
| FLSmidth |
| McLanahan Corporation |
| Williams Patent Crusher and Pulverizer Co., Inc. |
| Thyssenkrupp |
| TerraSource Global |
| Aesha Conveyors and Crushing Equipment |
| Ecoman India |
| Premur Impex Ltd. |
| HAZEMAG |
| Others |
Value Network & Pricing Analysis
Hydraulic drive technology adoption is compressing mechanical component inventories while concentrating supplier revenue in fluid power aftermarket streams, simultaneously reshaping cost economics and tilting supply power toward specialized hydraulics integrators in Germany and Poland.
Pricing Analysis
Lead-time premiums dominate pricing differentiation, with quad-roll configurations commanding substantial markups against standard double-roll units due to extended fabrication queues from limited engineering-qualified suppliers. Pricing stratifies across premium hydraulic-drive systems, standard mechanical configurations, and economy-grade single-roll alternatives. Price erosion runs through mechanical-drive tiers as Indian domestic fabricators capture state-owned coal procurement with aggressive spot pricing. Construction aggregate buyers exhibit highest price sensitivity, while German cement producers under EU F-Gas Regulation compliance mandates absorb premium positioning for REACH-compatible sealing architectures.
Supply Chain Analysis
Certification gating by MSHA and ECHA constrains supplier participation, with approved roll shell fabricators concentrated in Germany, the United States, and India. Raw material dependencies center on chromium-molybdenum alloy feedstock from South Africa and Kazakhstan, high-temperature seal elastomers, and precision hydraulic pump components. Single-source vulnerability in induction-hardened roll shell welding expertise creates procurement bottlenecks. Distribution runs through OEM-direct channels for mining applications and third-party service specialists capturing Indian aftermarket rebuild revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding and metallurgical expertise scarcity props pricing for qualified fabricators, creating durable supply constraints that incumbent suppliers can exploit through capacity discipline.
For Market Incumbents: Anticipate hydraulic technology licensing demands from Indian domestic competitors by securing patent positions in variable displacement pump integration. Defend aftermarket revenue streams against third-party service capture through localized spare parts warehousing in Singrauli and Talcher coalfields. Prioritize MSHA certification pipeline investment to compress revenue recognition delays in underground coal applications. For New Entrants and Emerging Players: Salt and potash operators in Saskatchewan extraction basins represent an underserved buyer archetype with specialized corrosion-resistant configuration requirements. Target chemical processing procurement with roll surface texture engineering capabilities that minimize fines generation. Pursue joint development agreements with established hydraulics integrators to bypass quad-roll fabrication capability gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by cement sector engineering houses seeking hydraulic drive technology integration. Long-term viability favors suppliers with captive metallurgical welding certification programs and installed base density in alternative fuel processing applications. Monitor EU carbon border adjustment mechanism implementation timelines as inflection indicator for frontloaded capital expenditure pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Hydraulic Drive Technology Licensing | Fluid power patent positions in Germany and Poland cement raw material lines secure royalty streams from Indian competitors. |
| Localized Spare Parts Warehousing | Regional inventory nodes in Singrauli and Talcher coalfields defend aftermarket revenue against domestic fabrication shops. |
| MSHA Certification Pipeline Investment | Accelerated approval queues for enclosed housing designs compress revenue recognition windows in Appalachian coal preparation. |
| REACH-Compatible Seal Qualification | Hydrogenated nitrile and thermoplastic elastomer compatibility testing maintains European Economic Area market access. |
| Remote Condition Monitoring Integration | Vibration analysis and thermal imaging convergence with hydraulic systems enables predictive maintenance contract expansion. |
Research Methodology
Multi-period observation of equipment procurement timelines, regulatory compliance transitions, and technology substitution patterns anchored the trend analysis, supplemented by interviews with plant engineers at cement producers, maintenance directors at hard-rock mining operations, aftermarket service heads, OEM procurement teams, and hydraulic systems integrators. Secondary validation drew from SEC 10-K filings of listed mining equipment suppliers, EU Industrial Emissions Directive implementation reports, MSHA certification databases, and customs trade data for chromium-molybdenum alloy imports. Bottom-up unit shipment estimates triangulated against top-down capital expenditure analysis across mining and cement verticals.
Segment-weighting applied product type, application, end user, and technology dimensions across the projection horizon, with roll configuration and drive architecture treated as primary demand determinants. CAGRs derived from regression analysis of historical equipment replacement cycles and forward projection of regulatory-driven upgrade mandates. Industry-specific inputs included alternative fuel integration rates in Indian and Vietnamese cement kilns, and carbon border adjustment mechanism preparation intensity among EU steel and cement customers.
Revisions become necessary when ferrochrome concentrate supply disruptions, MSHA certification regulatory changes, or hydraulic component lead time extensions materialize. Forecasts reflect assumptions regarding sustained infrastructure investment in India and continued EU emissions directive enforcement. A model refresh is warranted upon material change in carbon border adjustment mechanism implementation timelines or commercial mining auction velocity in Indian state-owned coalfields.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Vertical Lift Module (VLM) Market