
 Cranes Rental Market | 2026-2036
Cranes Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Cranes Rental Market Analysis
The EU Green Deal's construction machinery emissions benchmarks is shifting procurement patterns across European rental yards. Mammoet Holding B.V. leverages its engineered heavy-lift specialization to dominate petrochemical and infrastructure megaprojects requiring modular construction techniques. United Rentals Inc. sustains the largest North American rental fleet through technology leadership in telematics-enabled asset tracking and predictive maintenance systems. Liebherr Group anchors premium market positioning with in-house manufacturing of lattice boom cranes and self-erecting tower systems.
Cranes rental encompasses the temporary provision of lifting equipment with rated capacities from under 25 tons to over 1,000 tons, typically supplied with certified operators, rigging hardware, and transport logistics for project-specific durations. The equipment serves primary industrial purposes including vertical material placement, modular component assembly, and precision heavy lifting in confined or environmentally sensitive sites. Mobile cranes command the largest revenue share due to transport flexibility and rapid deployment across dispersed construction zones, while tower cranes generate concentrated margin pools in urban high-rise segments where erection complexity and operator certification create barriers. Crawler cranes represent the fastest-growing product category driven by wind turbine installation and refinery turnaround cycles requiring stable load charts on unprepared ground.
OSHA crane operator certification mandates and EPA Tier 4 Final engine emissions standards shape fleet investment cycles and equipment retirement timelines across the United States rental market. The EU Machinery Directive and CE marking requirements enforce design safety protocols and conformity assessment procedures for cranes deployed in European member states. China's GB standards and MEE air quality regulations increasingly influence manufacturing specifications for equipment exported to Asian construction markets. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content requirements that could restructure competitive access across major equipment deployment corridors.
Market Dynamics
Construction equipment ownership economics are inverting as fleet utilization tracking and predictive maintenance platforms reduce the cost advantage of captive crane fleets. Rental providers now capture value through telematics-enabled asset optimization rather than volume deployment.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Germany's port modernization and urban densification projects require electric and hybrid lifting equipment, forcing rental fleet upgrades that expand addressable project pools.
- Wind turbine installation cycles:Crawler crane demand concentrates in North Sea offshore zones and Great Plains corridors where 15MW+ nacelle weights exceed conventional mobile crane charts.
- Modular construction techniques:Petrochemical and data center builders in the US Gulf Coast and Middle East deploy engineered heavy-lift rentals for precision component placement in confined sites.
Market Restraints
- Specialized operator scarcity:OSHA crane certification timelines and European Union crane operator licensing requirements extend crew mobilization lead times beyond project scheduling windows.
- Steel and hydraulic component volatility:Lattice boom and crawler undercarriage manufacturing depends on concentrated East Asian forged component supply, exposing fleet replacement costs to input price swings.
- EPA Tier 4 Final and EU Stage V compliance:Diesel engine retrofit costs accelerate depreciation schedules for mid-life crawler and all-terrain units, compressing residual values.
Strategic Opportunities
- India infrastructure buildout:Dedicated freight corridors and metro expansion in Mumbai, Delhi, and Bangalore create demand for 100-300 ton mobile crane capacity with localized service networks.
- Telematics-to-finance convergence:Usage-based rental pricing models integrate IoT utilization data with equipment finance, unlocking project-cash-flow-aligned contract structures.
- Saudi giga-project pipeline:NEOM and Red Sea tourism developments specify extended-duration crane packages with integrated maintenance, favoring rental providers with regional depot density.
Industry Challenges
- Cross-border operator certification reciprocity:EU Machinery Directive CE marking does not harmonize with US NCCCO or Australian High Risk Work License requirements, fragmenting crew deployment across multinational projects.
- Legacy fleet telematics retrofit:Pre-2018 crawler and tower crane installations lack standardized data interfaces, forcing rental operators to maintain parallel maintenance workflows for connected and non-connected assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranes Rental Market |
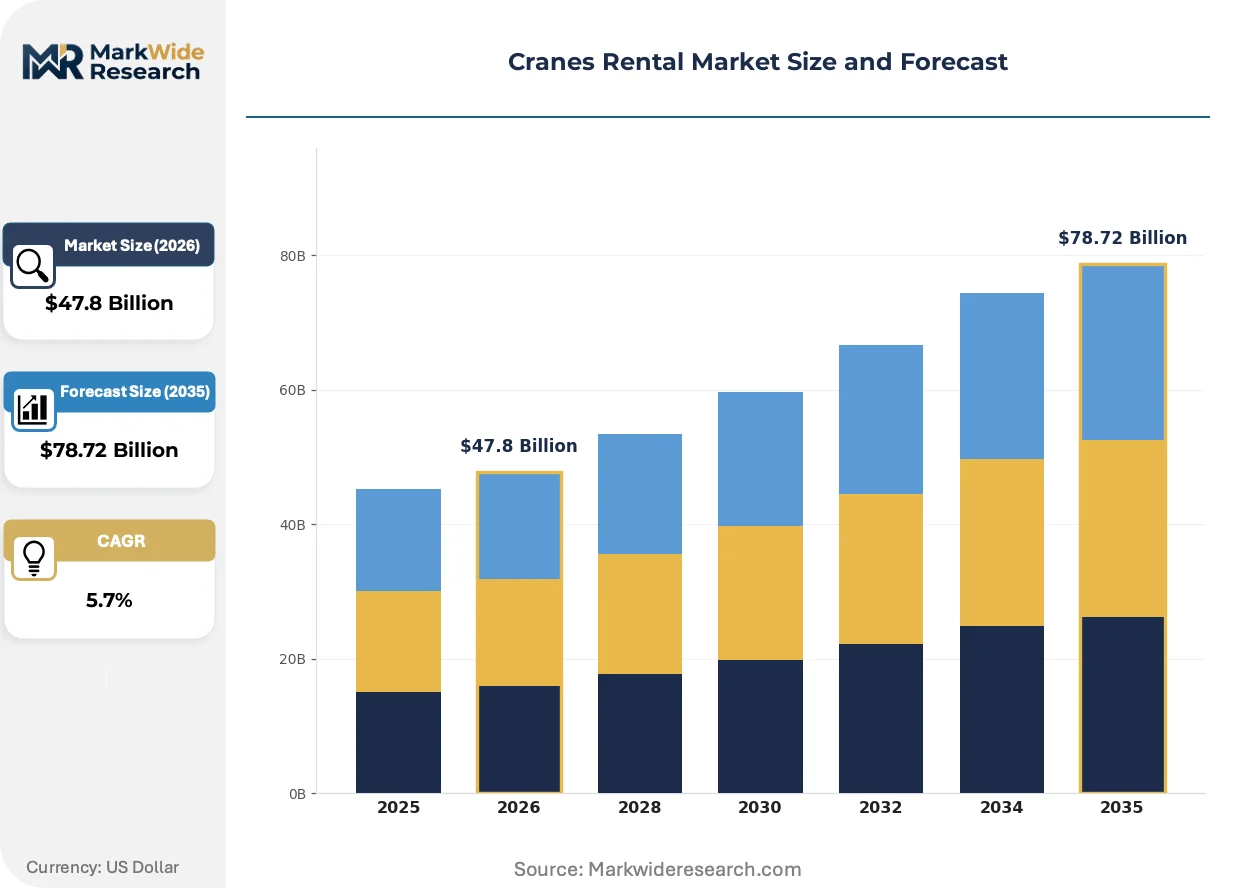
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $78.72 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Cranes, Tower Cranes, Crawler Cranes, Rough Terrain Cranes End User: Construction Companies, Shipyards, Oil & Gas, Utilities Application: Heavy Lifting, Placement, Transportation, Inspection Service Type: Short-Term Rental, Long-Term Rental, Event Rental, Maintenance Services |
| Companies Covered | Maxim Crane Works LP, Terex Corporation, United Rentals Inc., Bigge Crane and Rigging Co., TNT Crane & Rigging Inc., Mammoet Holding B.V., Liebherr Group, PALFINGER AG, Sarens NV/SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranes Rental Market Emerging Trajectories
Digital twin technology and autonomous load monitoring are compressing the expertise gap between specialized heavy-lift providers and generalist rental fleets. Equipment intelligence now substitutes for operator experience in standard lifting operations.
Telematics-integrated predictive maintenance is decentralizing crane service expertise from centralized engineering departments to field-based technician networks. Mid-size rental operators in Texas and Alberta deploy edge-computing vibration sensors to anticipate hydraulic pump failures before dispatch. The structural consequence compresses response time advantages previously held by vertically integrated national fleets.
The EU F-Gas Regulation and US EPA SNAP program are accelerating refrigerant-based hydraulic fluid substitution in temperature-sensitive lifting operations. Crane manufacturers in Finland and Austria now specify biodegradable hydraulic oils for Arctic and alpine deployments. European rental yards absorb compliance costs through premium pricing on environmentally certified equipment tiers.
Project owners now unbundle crane rental from operator provision, sourcing certified crews through specialized labor brokers rather than equipment suppliers. This pattern concentrates in German commercial construction and Australian mining infrastructure where unionized operator pools operate independently of fleet owners. The shift fragments historical bundled margins and forces rental providers to compete on bare equipment rates.
Cranes Rental Market Segmentation
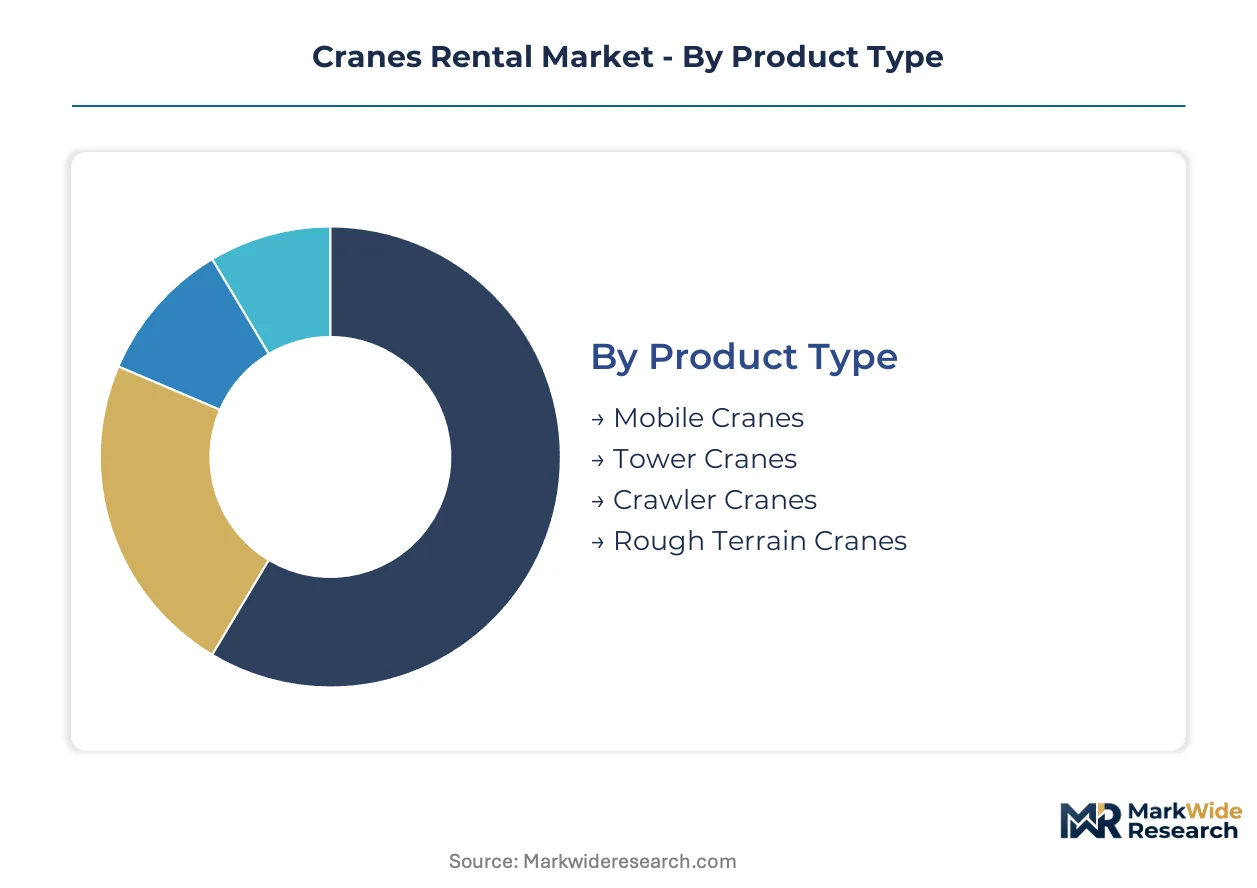
Equipment selection in crane rental hinges on load specifications, site constraints, and project duration rather than brand preference. Segmentation reveals how rental providers allocate fleet capital across mobility classes and service tiers to match contractor procurement patterns.
Product Type:
Buyers prioritize transport flexibility against ground-bearing pressure and assembly time tradeoffs when selecting crane categories.
- Mobile Cranes:Truck-mounted and all-terrain configurations with telescopic booms deploy rapidly across dispersed construction zones without auxiliary transport. German urban densification projects in Hamburg and Munich absorb the largest mobile crane rental volumes, driven by street-width restrictions that eliminate crawler alternatives.
- Tower Cranes:Self-erecting and hammerhead configurations dominate vertical material placement in high-rise construction where height and reach specifications exceed mobile crane charts. Margin concentration in Frankfurt and Berlin commercial towers stems from erection complexity and operator certification barriers that limit competitive supply.
- Crawler Cranes:Lattice boom systems with tracked undercarriages distribute load across unprepared ground for wind turbine nacelle installation and refinery turnarounds.
- Rough Terrain Cranes:Compact outrigger-based units with four-wheel drive navigate undeveloped sites in mining and pipeline construction.
Volume sits with mobile cranes; growth tilts toward crawler cranes.
End User:
Procurement sophistication varies sharply across buyer categories, with energy and marine sectors demanding bundled engineering services.
- Construction Companies:General contractors and specialty trade contractors source equipment for commercial, infrastructure, and residential verticals. US Gulf Coast petrochemical builders specify engineered heavy-lift packages with integrated rigging design, compressing rental margins through unbundled operator provision.
- Shipyards:Port modernization in Bremen and Hamburg requires floating and heavy-lift crawler capacity for hull section assembly. EU Green Deal embodied carbon mandates force fleet upgrades to electric and hybrid lifting equipment, expanding addressable project pools for certified rental providers.
- Oil & Gas:Refinery turnaround cycles and offshore platform maintenance drive demand for 500-ton-plus crawler configurations with certified rigger crews.
- Utilities:Transmission line construction and substation upgrades deploy rough terrain and mobile cranes in remote terrain with limited ground preparation.
Construction companies generate the largest equipment days; utilities are expanding most quickly on grid modernization timelines.
Application:
Functional use cases determine ancillary service bundling and operator specialization requirements.
- Heavy Lifting:Precision placement of modular components, pressure vessels, and turbine nacelles demands engineered lift planning and real-time load monitoring. North Sea offshore wind installations concentrate demand for 1,000-ton-plus crawler capacity with dynamic positioning integration.
- Placement:Vertical material handling for concrete, steel erection, and precast panel installation constitutes the highest-frequency rental use case. German commercial construction unbundles crane rental from operator provision, fragmenting historical bundled margins.
- Transportation:Self-propelled modular transporter integration and yard crane logistics support manufacturing and port material flow.
- Inspection:Man basket and under-bridge access configurations serve infrastructure condition assessment with specialized safety certification.
Placement commands the largest day-rate volume; heavy lifting captures the steepest expansion trajectory on modular construction adoption.
Service Type:
Contract duration and service integration levels segment pricing power and customer retention mechanics.
- Short-Term Rental:Daily and weekly agreements for discrete lifting tasks with minimum operator and transport bundling. Texas and Alberta mid-size operators deploy telematics-enabled predictive maintenance to compress response times against national fleet incumbents.
- Long-Term Rental:Multi-month and annual contracts with integrated maintenance, spare parts provisioning, and equipment replacement guarantees. Saudi giga-projects at NEOM specify extended-duration packages with regional depot density requirements that favor established rental networks.
- Event Rental:Temporary infrastructure for entertainment, exhibitions, and sports venue construction with rapid mobilization specifications.
- Maintenance Services:Field repair, inspection certification, and OEM-authorized overhaul services captive to rental fleet relationships.
Long-term rental anchors revenue stability; short-term rental gains share fastest on project-cash-flow-aligned contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg and Bremen anchor European crane rental demand through port modernization and dense urban redevelopment projects requiring specialized heavy-lifting capacity. Construction equipment rental agreements are displacing fleet ownership across commercial and infrastructure verticals as utilization tracking platforms improve asset economics. Regulatory pressure from embodied carbon mandates is forcing fleet electrification upgrades that expand certified providers' addressable project pools.
Germany
Port modernization in Hamburg and Bremen drives demand for floating and heavy-lift crawler capacity with electric and hybrid specifications. The EU Green Deal's embodied carbon tracking requirements for construction machinery push rental yards to modernize fleets. Frankfurt and Berlin commercial towers concentrate tower crane margins where erection complexity limits competitive supply.
United States
Petrochemical builders along the US Gulf Coast specify engineered heavy-lift packages for modular construction in confined sites. OSHA crane operator certification mandates and EPA Tier 4 Final engine emissions standards shape fleet investment cycles. Texas and Alberta mid-size operators deploy telematics-enabled predictive maintenance to compress response times against national fleet incumbents.
Saudi Arabia
NEOM and Red Sea tourism developments specify extended-duration crane packages with integrated maintenance requirements. The kingdom's giga-project pipeline favors rental providers with regional depot density and localized service networks. Western Region infrastructure corridors absorb mobile crane capacity for tourism and logistics hub construction.
India
Dedicated freight corridors and metro expansion in Mumbai, Delhi, and Bangalore create demand for 100-300 ton mobile crane capacity. The country's national infrastructure regulator enforces construction equipment safety protocols through certification requirements. Maharashtra and Gujarat industrial clusters concentrate rental fleet deployment for manufacturing and logistics facility construction.
China
Wind turbine installation cycles in northern and western provinces drive crawler crane demand for 15MW+ nacelle weights. GB standards and MEE air quality regulations increasingly influence manufacturing specifications for equipment deployed domestically. Yangtze River Delta port modernization absorbs heavy-lift capacity for shipyard and logistics infrastructure expansion.
Cranes Rental Market Vendor Landscape
The competitive structure tilts toward vertically integrated national fleets with telematics-enabled asset optimization capabilities. Mid-size regional operators compete through predictive maintenance platforms that decentralize service expertise to field-based technician networks. Three archetypes dominate: engineered heavy-lift specialists, scale-driven national lessors, and technology-enabled regional operators. Consolidation pressure manifests through fleet modernization partnerships and cross-border operator certification reciprocity agreements.
Among North American scale-driven lessors, United Rentals Inc. exemplifies the telematics-enabled national fleet archetype through technology leadership in asset tracking systems. Mammoet Holding B.V. occupies the engineered heavy-lift specialist position, leveraging modular construction expertise for petrochemical and infrastructure megaprojects. Liebherr Group anchors premium market positioning through in-house manufacturing capabilities and European regulatory compliance specialization.
| Leading Market Players |
|---|
| Maxim Crane Works LP |
| Terex Corporation |
| United Rentals Inc. |
| Bigge Crane and Rigging Co. |
| TNT Crane & Rigging Inc. |
| Mammoet Holding B.V. |
| Liebherr Group |
| PALFINGER AG |
| Sarens NV/SA |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EPA Tier 4 Final and EU Stage V compliant fleets and legacy diesel units manifests in day-rate spreads exceeding 40% for equivalent tonnage classes, while simultaneously concentrating procurement relationships around OEM-authorized service networks that control remanufactured component flows.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for crawler crane deployments in North Sea wind installations, with operators charging premium rates for 95%+ availability commitments on 15MW+ nacelle lifts. Three-tier pricing structure across premium-certified, standard-compliant, and economy-legacy equipment levels segments buyer willingness-to-pay, with German shipyards and Saudi giga-project developers occupying the premium tier. Cost compression in the economy tier intensifies because accelerated depreciation schedules for pre-2020 diesel units compress residual recovery. Generalist construction contractors exhibit highest price sensitivity, while petrochemical and data center builders absorb premium pricing for engineered heavy-lift packages with integrated rigging design.
Supply Chain Analysis
Direct-to-project-site deployment with integrated operator and transport logistics handles megaproject demand, while regional depot networks serve fragmented construction contractor procurement. Manufacturing concentration in Germany, Japan, and China for lattice boom forgings and hydraulic pump systems creates geographic dependency for fleet replacement cycles. Raw material inputs draw from East Asian forged component supply for undercarriage assemblies, European specialty steel for boom sections, and North American hydraulic systems for precision control. Single-source vulnerability in 1,000-ton-plus crawler crane component supply exposes rental operators to 12-18 month lead time extensions. Distribution runs through OEM-certified dealer networks that control aftermarket parts availability and field service technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embodied carbon mandates and EPA Tier 4 Final compliance costs are forcing sub-scale rental operators into distressed asset sales, consolidating market share among telematics-enabled national fleets and engineered heavy-lift specialists.
For Market Incumbents: Extend predictive maintenance platform coverage to pre-2018 legacy fleet installations through edge-computing retrofit modules, compressing response time advantages against regional competitors. Deepen backward integration into remanufactured hydraulic component supply through OEM-authorized service partnerships, defending margin position against parts price volatility from East Asian forging concentration. The priority lever sits with telematics-to-finance convergence that locks contractor relationships through usage-based contract structures. For New Entrants and Emerging Players: Launch via specialized operator labor brokerage models that unbundle crane rental from crew provision, capturing margin pools fragmented from historical equipment-operator bundles in German commercial construction and Australian mining infrastructure. Target India's 100-300 ton mobile crane shortage in Maharashtra and Gujarat industrial corridors, where dedicated freight corridor construction outpaces localized service network deployment. White-space penetration runs through telematics-enabled short-term rental platforms that align contract duration with project cash flow cycles. For Investors and Strategic Acquirers: Re-rating potential sits with mid-size regional operators possessing dense depot networks in Saudi giga-project corridors and Indian metro expansion zones, given extended-duration contract demand at NEOM and Red Sea tourism developments. Long-term viability favors acquisition targets with demonstrated telematics integration and OEM-authorized maintenance certifications that satisfy EU Green Deal compliance requirements. The signal to watch is cross-border operator certification reciprocity agreements that unlock crew deployment flexibility across multinational projects.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Joint development with OEMs of hybrid crawler systems satisfies EU Green Deal embodied carbon mandates for Hamburg port modernization. |
| Telematics Platform Acquisition | Integration of IoT utilization data with equipment finance unlocks project-cash-flow-aligned contract structures for contractors. |
| Regional Depot Expansion | Density buildout in Saudi Western Region and Indian Maharashtra clusters captures extended-duration giga-project and metro construction demand. |
| Operator Certification Reciprocity | Cross-border licensing agreements harmonize EU Machinery Directive CE marking with OSHA NCCCO requirements for multinational deployment. |
| Predictive Maintenance Rollout | Edge-computing vibration sensors decentralize service expertise to field technicians, compressing response times against national fleet incumbents. |
Methodological Framework
Multi-period observation of fleet utilization rates, rental day pricing, and OEM order backlogs anchored the trend analysis, supplemented by interviews with rental fleet managers, construction project directors, crane operator training certification bodies, and OEM aftermarket service heads. Primary fieldwork combined with secondary validation from customs trade data for crane component imports, SEC 10-K filings from listed equipment manufacturers, and EU Machinery Directive conformity assessment databases. Bottom-up equipment deployment tracking across Hamburg, Bremen, Texas, Alberta, Mumbai, and Riyadh construction corridors triangulated against top-down market sizing from national construction equipment associations.
Segment-weighting across mobility class, end-user vertical, and service duration dimensions informed the analytical framework, with mobile crane, tower crane, and crawler crane categories modeled separately. CAGRs derived from regression analysis of historical fleet expansion rates against projected construction output indices and wind turbine installation timelines. Industry-specific forecast inputs incorporated EPA Tier 4 Final and EU Stage V engine retirement schedules, alongside telematics adoption curves for predictive maintenance deployment across the analysis window.
Regulatory enforcement delays, steel and hydraulic component price volatility, and cross-border operator certification reciprocity failures are the dominant revision risks that could compress or extend projected equipment replacement cycles. Forecasts reflect assumptions regarding EU Green Deal implementation timelines and Saudi giga-project execution continuity. Periodic stress-testing of base assumptions against actual fleet modernization expenditure and certified operator pipeline expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Powered Screed Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Part Feeder Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Cable Winches Market