
 Surgical Loupes and Cameras Market | 2026-2036
Surgical Loupes and Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Loupes and Cameras Market Analytics
Leasing and subscription-based financing for high-magnification optical systems is narrowing the competitive field for smaller practices. ZEISS Group leverages its century-long optics heritage to sustain premium positioning across surgical visualization. Enova Illumination anchors its presence through LED-integrated headlight systems that reduce shadowing in deep-cavity procedures. Designs for Vision, Inc. differentiates via custom-fitted TTL loupes calibrated to individual pupillary distances and working distances.
Surgical loupes and cameras comprise magnifying optical devices and image-capture systems worn on the head or mounted to surgical fields, typically offering 2.5x to 8.0x magnification with focal lengths of 300-550mm and resolution thresholds exceeding 1080p for digital variants. These instruments enable tissue differentiation at sub-millimeter scales during microsurgical, dental, and ophthalmic interventions where unaided vision fails. TTL loupes command the dominant share of product-type revenue due to their fixed-barrel light weight and superior optical alignment, while digital imaging segments within the technology dimension attract accelerated R&D investment as 4K wireless connectivity protocols mature. Cameras embedded in loupes and standalone surgical cameras capture training footage and enable real-time consultation, creating secondary revenue streams beyond the primary hardware sale.
FDA 510(k) clearance requirements govern optical device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class I and IIa magnification instruments entering European markets. ISO 10993 biocompatibility testing for frame materials and IEC 60601-1 electrical safety standards for camera-integrated systems further constrain design freedom and extend development cycles. Stakeholders must monitor evolving reimbursement codes for tele-surgical consultation and remote proctoring, as these will determine whether camera-enabled loupes shift from capital equipment to connected-service platforms.
Market Dynamics
The surgical loupes and cameras market is restructuring around wireless 4K image transmission protocols that compress consultation latency from minutes to seconds, forcing hardware vendors to integrate software stacks or cede margin to platform intermediaries.
Growth Catalysts
- FDA 510(k) Precedent Pathways:Established optical clearances for TTL loupes reduce regulatory friction for iterative magnification upgrades, accelerating product cycles for US manufacturers.
- Dental Implantology Precision Thresholds:Sub-millimeter osteotomy requirements in guided surgery protocols mandate magnification systems with working distances below 400mm.
- German Precision Optics Clustering:Concentration of specialized glass grinding and coating expertise around Wetzlar and Oberkochen sustains component supply for premium barrel manufacturers.
Market Restraints
- Fluorite Crystal Supply Concentration:High-dispersion lens elements depend on Chinese rare-earth processing facilities, exposing optical houses to input volatility.
- EU MDR Clinical Evidence Burden:Class IIa magnification devices now require post-market surveillance data that extends development timelines by 18-24 months.
- Head-Mounted Display Substitution:AR visualization systems from industrial wearable vendors threaten standalone loupe demand in training environments.
Strategic Opportunities
- Tele-Surgical Proctoring Reimbursement:CMS evaluation of remote consultation codes for camera-enabled loupes could shift hardware sales toward recurring service revenue.
- Indian Tier-II City Penetration:Underdeveloped dental infrastructure in Lucknow, Jaipur, and Kochi presents first-mover positioning for leasing-model distributors.
- AI-Assisted Image Annotation Convergence:Real-time tissue boundary algorithms from radiology software vendors integrate with loupe-mounted cameras for intraoperative decision support.
Industry Challenges
- Optical Engineer Talent Scarcity:Declining university programs in precision lens design constrain R&D throughput for TTL customization at scale.
- IEC 60601-1 Edition 3.2 Compliance:Electrical safety testing for LED-integrated headlight systems adds certification costs that squeeze mid-tier vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Loupes and Cameras Market |
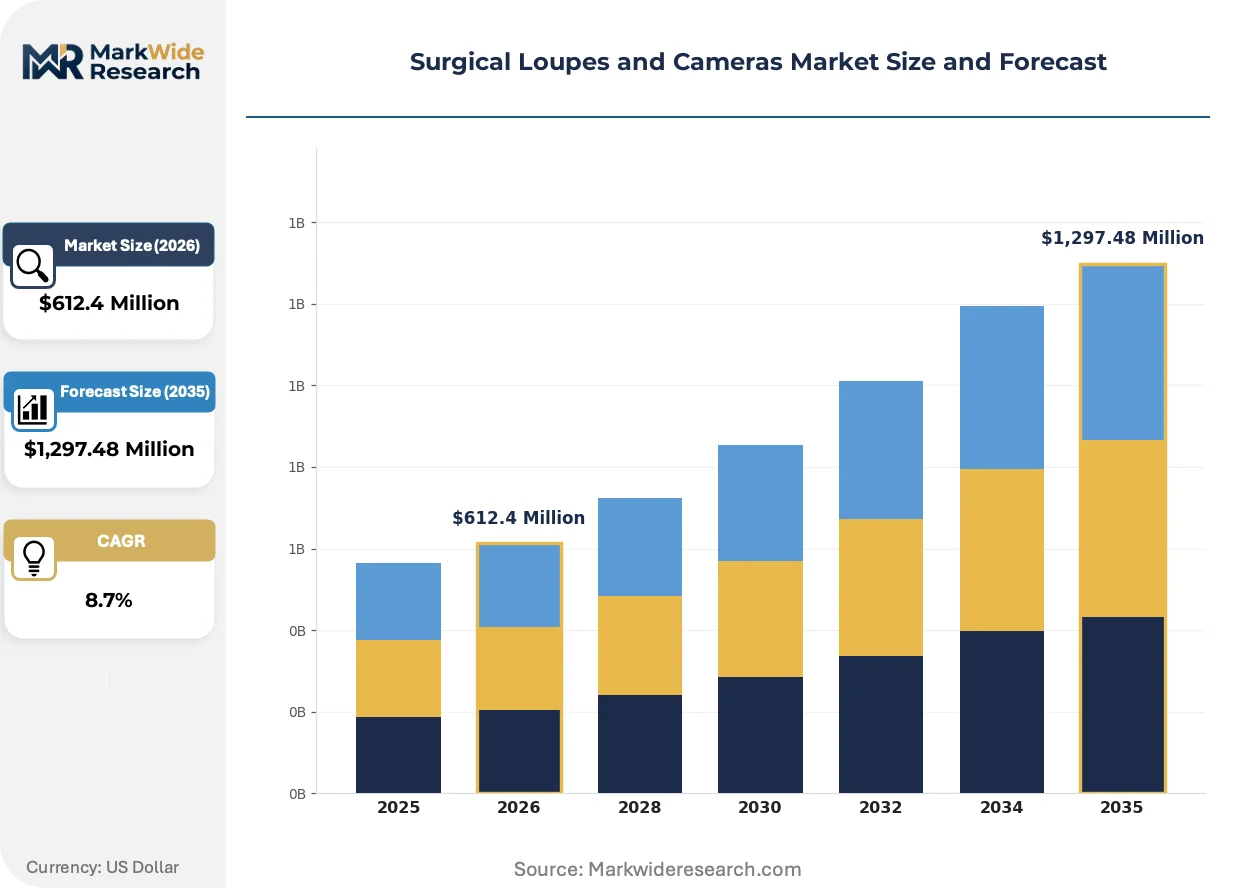
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TTL Loupes, Flip-Up Loupes, LED Lights, Cameras Technology: Optical Magnification, Digital Imaging, HD Resolution, Wireless Connectivity End User: Dentists, Surgeons, Orthodontists, Medical Technologists Application: General Surgery, Dental Procedures, Ophthalmic Surgery, Veterinary Medicine |
| Companies Covered | Enova Illumination, HEINE Optotechnik GmbH & Co. KG, ZEISS Group, Den-Mat Holdings, LLC., Rose Micro Solutions, Designs for Vision, Inc., ErgonoptiX, SheerVision Loupes & Headlights, Orascoptic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Loupes and Cameras Market Evolving Landscape
Wireless connectivity protocols and embedded compute are dissolving the boundary between magnification hardware and surgical information systems, creating platform competition where standalone optics once dominated.
4K wireless transmission modules are virtualizing the consultation interface between operating surgeons and remote proctors. Academic medical centers in Boston and Heidelberg deploy these systems for real-time resident training without physical proximity. The technology is virtualizing the traditional proctoring relationship, compressing travel costs and enabling asynchronous case review.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic clinical follow-up for Class IIa magnification instruments. Manufacturers must establish quality management systems with notified body oversight for software updates. German and Swiss optical houses absorb these compliance costs through premium positioning, while smaller competitors exit European markets.
Subscription financing for high-magnification systems displaces capital purchase in independent dental practices. DSOs and group practices in Texas and Florida negotiate fleet pricing that bundles TTL loupes with maintenance and upgrade cycles. This procurement consolidation concentrates buying power among multi-location operators, marginalizing single-practice distributors.
Surgical Loupes and Cameras Market Segmentation
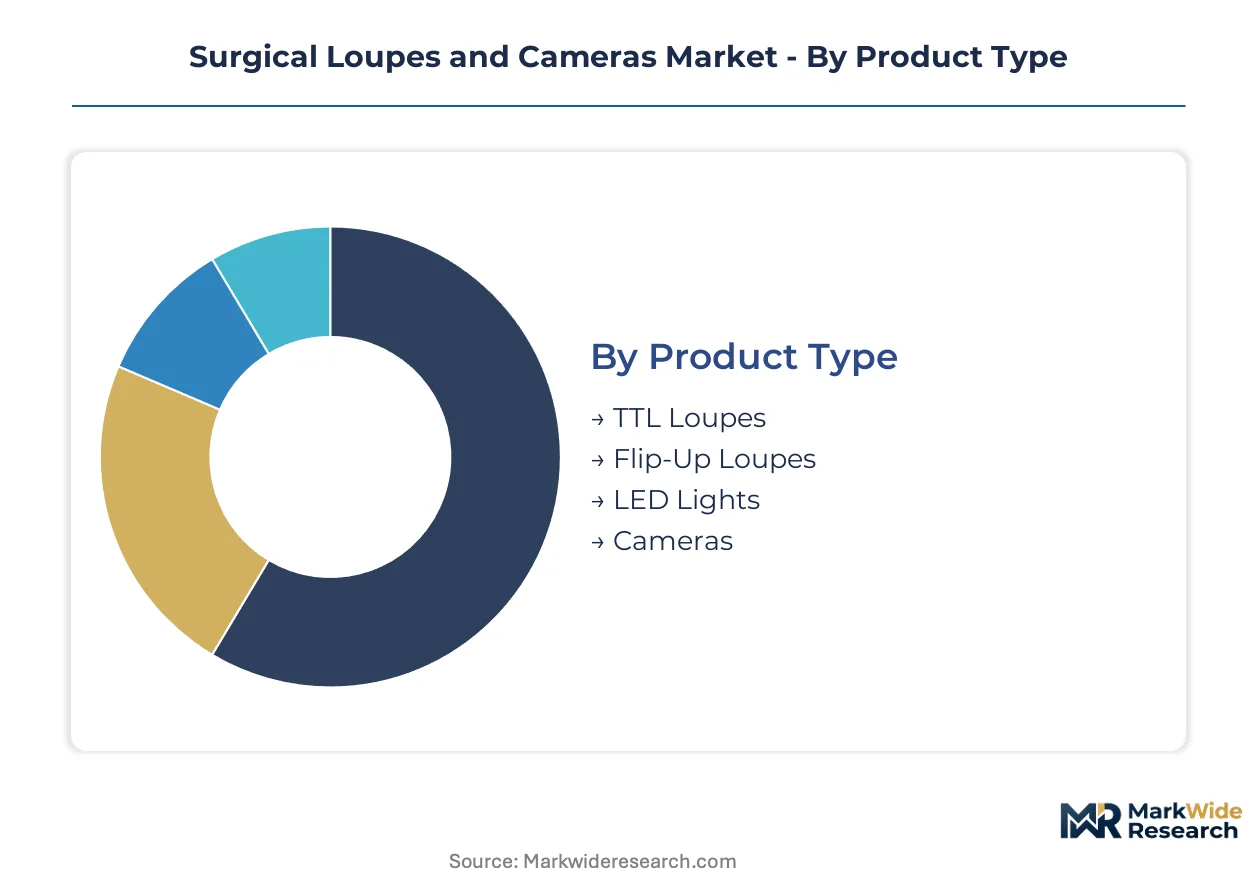
Segmentation in surgical loupes and cameras reveals how procurement priorities diverge across clinical environments. Service intensity varies sharply between capital-intensive digital imaging systems and replaceable LED accessories, reshaping vendor-customer relationships.
Product Type:
After-sales calibration and lens recoating services generate recurring revenue that sustains premium positioning for barrel manufacturers.
- TTL Loupes:Through-the-lens designs integrate fixed optical barrels with customized pupillary distance calibration. Dental implantologists in Germany and Switzerland specify working distances below 400mm for sub-millimeter osteotomy precision. Custom-fitted TTL systems command service contracts covering annual alignment verification and anti-reflective coating renewal.
- Flip-Up Loupes:Hinged mounting systems allow clinicians to alternate between magnified and natural vision without doffing headgear. Surgeons in multi-procedure hospital settings favor this flexibility for emergency departments where magnification needs fluctuate. Flip-up mechanisms introduce mechanical wear points that drive replacement cycles faster than fixed-barrel alternatives.
- LED Lights:Integrated headlamp systems attach to loupe frames or operate independently. Battery replacement programs and lumen degradation monitoring create predictable aftermarket touchpoints for distributors.
- Cameras:Image-capture modules embedded in loupes or mounted as standalone surgical field recorders. Firmware update subscriptions and cloud storage integration transform hardware sales into recurring platform relationships.
By volume, LED Lights lead due to universal compatibility and lower price points. By growth pace, Cameras are ahead as tele-surgical proctoring reimbursement codes mature.
Technology:
Cost tier stratification separates legacy optical systems from digitally integrated platforms requiring ongoing software investment.
- Optical Magnification:Pure lens-based systems relying on achromatic glass and prismatic correction. German precision optics clusters around Wetzlar supply high-dispersion fluorite elements for chromatic aberration control. These systems demand minimal post-sale support beyond physical maintenance.
- Digital Imaging:Sensor-integrated capture with onboard processing for real-time display. Academic medical centers in Boston and Heidelberg deploy these systems for resident training archives. Digital platforms require continuous cybersecurity patching and interoperability certification with hospital information systems.
- HD Resolution:1080p imaging standards for training documentation and remote consultation. Resolution specifications plateau as 4K protocols emerge, compressing upgrade cycles for early HD adopters.
- Wireless Connectivity:Low-latency transmission modules enabling real-time proctoring without physical presence. FDA 510(k) clearance pathways for wireless surgical devices add regulatory complexity that favors established vendors with quality management infrastructure.
By volume, Optical Magnification leads in installed base. By margin contribution, Wireless Connectivity is expanding most quickly as subscription models displace capital sales.
End User:
Customer type determines whether procurement flows through group purchasing organizations or direct specialty distributor relationships.
- Dentists:Independent practitioners and dental service organizations represent concentrated demand for TTL loupes with integrated LED illumination. Texas and Florida DSOs negotiate fleet pricing that bundles equipment with preventive maintenance schedules.
- Surgeons:Hospital-employed specialists and ambulatory surgery center staff require flip-up configurations for procedure flexibility. Their procurement integrates with capital equipment committees and value analysis teams.
- Orthodontists:Extended working distance requirements for extraoral examination drive distinct optical specifications. This segment purchases through dental specialty distributors with orthodontic-specific technical support.
- Medical Technologists:Laboratory and pathology personnel utilize lower magnification ranges for specimen examination. Price sensitivity here channels demand toward economy-tier products with limited service attachments.
By volume, Dentists lead procurement activity. By service revenue intensity, Surgeons are climbing the fastest as camera-enabled consultation protocols expand.
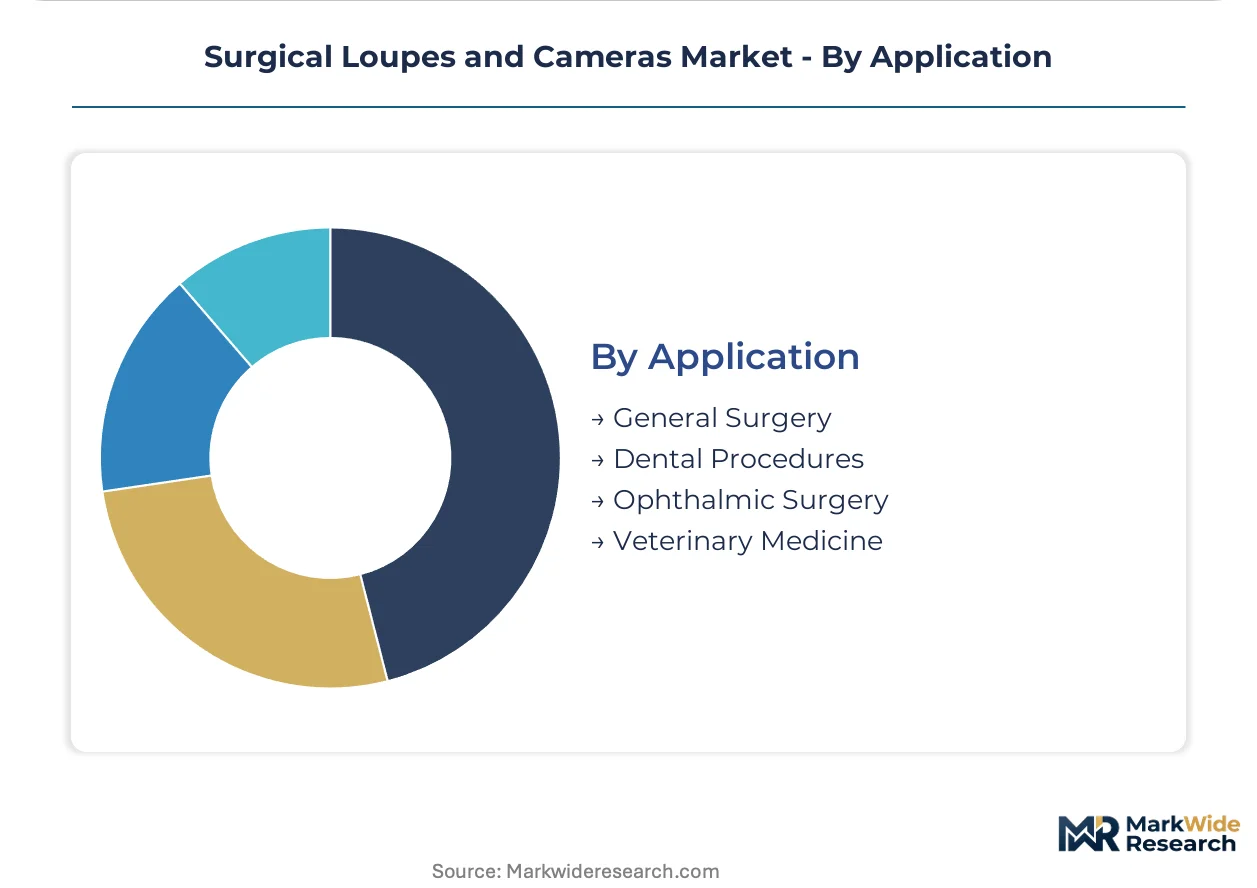
Application:
Procedure-specific optical requirements create segmentation by clinical environment and reimbursement environment.
- General Surgery:Abdominal and thoracic procedures demand wide field-of-view configurations with working distances exceeding 500mm. Hospitals in this segment prioritize loupes compatible with sterile draping protocols and steam sterilization cycles.
- Dental Procedures:Implantology and endodontics drive the most stringent magnification specifications. Indian tier-II cities including Lucknow and Jaipur present expansion opportunity as dental infrastructure develops.
- Ophthalmic Surgery:Microsurgical interventions at the retinal and corneal level require 6.0x to 8.0x magnification with exceptional depth of field. This application commands premium pricing and specialized training for optical calibration.
- Veterinary Medicine:Companion animal dentistry and orthopedic surgery adopt human medical specifications with modified working distances. Veterinary distributors serve this segment with reduced service intensity compared to human medical channels.
By volume, Dental Procedures lead. By specification intensity, Ophthalmic Surgery gains share fastest as subspecialization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways for optical medical devices accelerate commercial timelines for US manufacturers. Germany's precision optics heritage anchors component supply for premium barrel manufacturers. India's underdeveloped dental infrastructure in tier-II cities creates first-mover positioning for leasing-model distributors.
United States
Dental service organizations in Texas and Florida negotiate fleet pricing for TTL loupes bundled with maintenance schedules. FDA 510(k) precedent pathways reduce regulatory friction for iterative magnification upgrades. Academic medical centers in Boston deploy 4K wireless transmission systems for real-time resident training.
Germany
Specialized surgical instrument manufacturing clusters around Wetzlar and Oberkochen sustain fluorite element supply for chromatic aberration control. EU Medical Device Regulation post-market surveillance requirements extend development timelines by 18-24 months for Class IIa devices. German optical houses absorb compliance costs through premium positioning while smaller competitors exit European markets.
India
Lucknow, Jaipur, and Kochi present expansion opportunity as dental infrastructure develops in tier-II cities. Central Drugs Standard Control Organization oversight governs medical device registration for imported magnification systems. Leasing-model distributors target first-mover positioning where capital purchase constraints limit standalone practice adoption.
Switzerland
Swissmedic certification requirements for optical medical devices align with EU MDR standards while maintaining distinct quality management protocols. Precision manufacturing clusters around the Jura Arc supply high-dispersion lens elements to German barrel assemblers. Swiss optical houses leverage neutral positioning for Middle East and Asian market access.
Japan
Ministry of Health, Labour and Welfare pharmaceutical and medical device regulations govern loupe commercialization with emphasis on biocompativity documentation. Kanto region academic medical centers in Tokyo drive demand for camera-enabled consultation systems. Japanese precision electronics manufacturers supply sensor modules for digital imaging integration.
Surgical Loupes and Cameras Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: century-established optics houses with vertical control over glass grinding, mid-scale specialists in TTL customization, and component-integrating distributors serving price-sensitive segments. Competitive moves concentrate on software stack integration for wireless connectivity and subscription financing models that displace capital sales.
Within the heritage optics tier, ZEISS Group and HEINE Optotechnik GmbH & Co. KG exemplify premium positioning sustained through captive supply of precision lens elements. Enova Illumination occupies a position among LED-integrated system specialists, while Designs for Vision, Inc. represents the custom-fitted TTL segment with individualized pupillary distance calibration. These anchors illustrate how competitive differentiation flows from either upstream material control or downstream service intensity.
| Leading Market Players |
|---|
| Enova Illumination |
| HEINE Optotechnik GmbH & Co. KG |
| ZEISS Group |
| Den-Mat Holdings, LLC. |
| Rose Micro Solutions |
| Designs for Vision, Inc. |
| ErgonoptiX |
| SheerVision Loupes & Headlights |
| Orascoptic |
| Others |
Value Network & Pricing Analysis
Wetzlar and Oberkochen precision optics clusters control fluorite crystal grinding capacity for high-dispersion lens elements, translating upstream component scarcity into tiered pricing power for barrel manufacturers serving premium surgical visualization markets.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-compliant premium tiers and economy alternatives lacking notified body oversight. Three-tier pricing structure separates FDA 510(k)-cleared systems with wireless connectivity from standard optical magnification and unbranded imports. Cost compression in mid-tier segments is intensifying because DSO fleet procurement consolidates buying power across multi-location dental practices. Independent practitioners in tier-II Indian cities exhibit highest price sensitivity, while academic medical centers in Boston and Heidelberg demonstrate lowest sensitivity due to grant-funded technology acquisition.
Supply Chain Analysis
Export control regimes on precision optical manufacturing equipment limit technology transfer to emerging production hubs, constraining supply diversification. Manufacturing concentrates in Germany, Japan, and Switzerland for achromatic glass grinding and fluorite element coating. Barrel assembly draws from Chinese rare-earth processing facilities for high-dispersion lens substrates and Japanese sensor modules for digital imaging integration. Single-source vulnerability runs through concentrated fluorite crystal supply from specific geological deposits. Distribution runs through dental specialty distributors and hospital value analysis committees with divergent service intensity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward dental service organizations and hospital systems as procurement consolidation across Texas and Florida DSOs fragments the independent practitioner channel.
For Market Incumbents: Insulate premium positioning through captive fluorite element supply from Wetzlar-area grinding facilities and accelerated FDA 510(k) clearance for iterative wireless connectivity upgrades. AR visualization systems from industrial wearable vendors threaten standalone loupe demand in training environments; vertical integration into LED-integrated headlight manufacturing preserves margin contribution from illumination accessories. For New Entrants and Emerging Players: Build out leasing-model distribution infrastructure targeting Lucknow, Jaipur, and Kochi dental infrastructure development where capital purchase constraints limit incumbent penetration. Indian tier-II cities present the most penetrable geography due to underdeveloped distributor networks and CDSCO registration pathways for imported magnification systems. Partner with regional dental equipment financiers to offer subscription-based procurement that bypasses upfront capital barriers. For Investors and Strategic Acquirers: Long-term, this sits as a platform-convergence play because wireless 4K transmission protocols are dissolving hardware-software boundaries and enabling recurring service revenue from camera-enabled consultation systems. Target acquisition candidates with established quality management infrastructure for EU MDR compliance and existing hospital GPO contracts. Monitor CMS evaluation of remote proctoring reimbursement codes as the inflection signal determining whether hardware sales shift to connected-service platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Established optical precedents reduce regulatory friction for US manufacturers seeking iterative magnification upgrades. |
| Software Companion Development | Firmware update subscriptions for camera-embedded loupes transform capital equipment into recurring platform relationships. |
| Hospital System Partnership | Academic medical centers in Boston and Heidelberg deploy 4K wireless systems for real-time resident training archives. |
| CE Marking Pathway | EU MDR post-market surveillance requirements extend timelines but create competitive moats for compliant German optical houses. |
| Reimbursement Strategy | CMS evaluation of tele-surgical proctoring codes determines whether camera-enabled loupes shift to service-based revenue models. |
Research Methodology
Initial hypotheses were tested against primary input from dental implantologists, hospital purchasing committee members, biomedical engineers specializing in surgical visualization, and GPO contracts managers, then refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body registration records, hospital procurement databases, and customs import data for optical medical devices. Bottom-up demand modeling from procedure volumes and top-down market sizing from manufacturer revenue disclosures were triangulated to establish segmentation boundaries.
Demand-supply balance across the analysis window reflects procedure growth rates, DSO expansion trajectories, and fluorite element supply constraints from precision optics clusters. Segmentation dimensions modeled include product type, technology tier, end-user category, and application specialty. CAGRs were derived from installed base evolution and replacement cycle compression as digital imaging protocols mature. Industry-specific inputs incorporated dental implantology precision thresholds and ophthalmic subspecialization depth.
Stress conditions across fluorite supply disruption, EU MDR compliance cost escalation, and AR substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement code evolution and wireless protocol standardization. Material shifts in CMS tele-surgical proctoring policy or export control expansion on precision optical equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Autosamplers Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Cryosurgery Devices Market