
 3D Printing Medical Devices Market | 2026-2036
3D Printing Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Medical Devices Market Intelligence
The fragmentation of the customer base, as specialty clinics and dental practices increasingly adopt point-of-care manufacturing, is rebalancing competitive dynamics away from large hospital systems. Stratasys Ltd. leverages its extensive material portfolio to serve diverse medical applications. Materialise NV specializes in certified medical software and patient-specific surgical guides. Meanwhile, 3D Systems, Inc. competes with an integrated strategy combining printers, materials, and on-demand manufacturing services.
3D printing of medical devices involves the layer-by-layer fabrication of anatomical models, surgical instruments, and patient-specific implants from a digital file. This additive manufacturing process uses materials like titanium alloys or PEEK to create patient-matched devices with complex internal geometries, primarily for surgical planning and implantation. Orthopedic and dental implants represent the largest product segments, driven by demand for custom solutions in reconstructive surgery. Among technologies, Stereolithography and Selective Laser Sintering are dominant for high-precision applications.
Market access is governed by stringent regulatory frameworks for medical devices, including the FDA in the United States and the European Union's Medical Device Regulation (MDR). These bodies, along with Japan's PMDA, mandate rigorous testing for biocompatibility and mechanical performance of 3D printed materials and final products. Navigating the evolving standards for point-of-care manufacturing and personalized device validation remains a central challenge for market participants.
Market Dynamics
The proliferation of point-of-care manufacturing is the central force altering market structure. This shift empowers individual clinics and smaller hospital groups, challenging the established supply chain dominance of large-scale, centralized medical device manufacturers.
Growth Catalysts
- Biocompatible Material Innovation:Advances in photopolymers and polymers like PEEK enable durable, complex implants for orthopedic surgery, expanding clinical applications.
- Demand for Personalization:Clinical need for patient-specific solutions in reconstructive surgery drives adoption, as custom devices improve surgical outcomes.
- Evolving Regulatory Pathways:The FDA's clearer guidance for additively manufactured devices creates a predictable pathway for market approval of patient-specific implants.
Market Restraints
- High Capital Investment:The upfront cost of industrial-grade printers using Selective Laser Sintering technology is a significant adoption barrier for many hospitals.
- Material Cost Structure:Medical-grade raw materials like implantable titanium alloys and PEEK are expensive, impacting the final device cost and limiting broader use.
- Regulatory Compliance Burden:Navigating the EU's Medical Device Regulation (MDR) for novel devices is complex and resource-intensive, delaying market access.
Strategic Opportunities
- Emerging Geographic Markets:Modernizing healthcare systems in Latin America and Southeast Asia present white space for deploying 3D printing technologies in clinical settings.
- Soft Tissue Bioprinting:Development in bioprinting for creating soft tissues and vascular structures represents a long-term frontier beyond today's hard implants.
- AI-Powered Design Automation:Integrating artificial intelligence with CAD software can automate patient-specific implant design from medical scans, reducing manual design time.
Industry Challenges
- Specialized Talent Scarcity:A shortage of biomedical engineers and technicians with dual expertise in clinical workflows and additive manufacturing constrains effective implementation in hospitals.
- Standardization Gaps:A deficit of universal standards for process validation, quality control, and data management hinders interoperability and scalability in point-of-care settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Medical Devices Market |
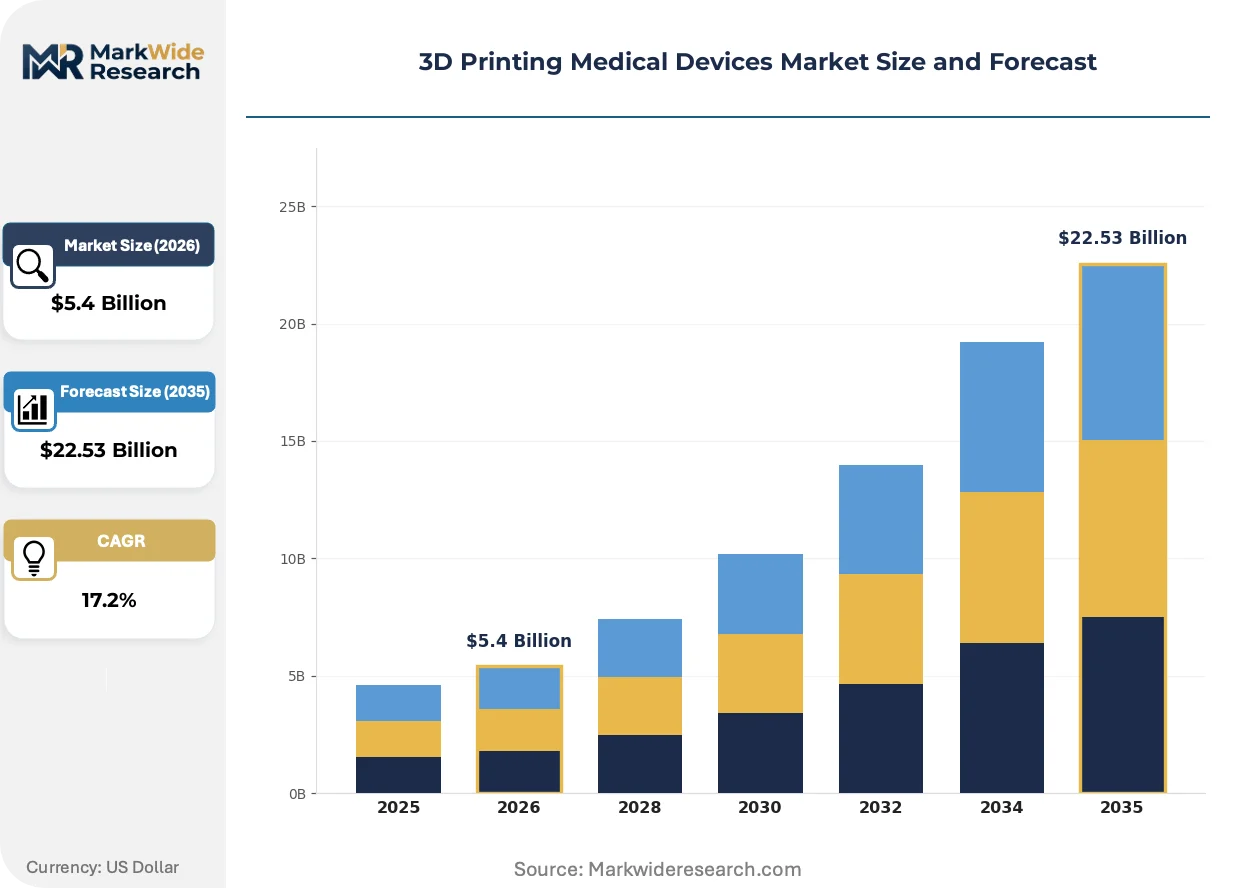
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $22.53 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Implants, Dental Implants, Prosthetics, Surgical Instruments, Cardiovascular Devices Technology: Stereolithography, Selective Laser Sintering, Fused Deposition Modeling, Digital Light Processing, Binder Jetting Application: Reconstructive Surgery, Dental Restoration, Tissue Engineering, Customized Prosthetics, Surgical Planning End User: Hospitals, Dental Clinics, Research Institutions, Specialty Clinics, Medical Device Manufacturers |
| Companies Covered | Stratasys Ltd., 3D Systems, Inc., Materialise NV, EOS GmbH, EnvisionTEC, Renishaw plc, Formlabs, Carbon Inc., HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Medical Devices Market Strategic Shifts & Innovations
Personalization at the point of care is fundamentally altering the production and delivery models for medical devices. This evolution is driven by technological accessibility, new regulatory pressures, and a demand for more integrated clinical workflows.
Point-of-care 3D printing systems are compact, user-friendly printers designed for direct use within clinical environments. Dental practices and hospital surgical departments are rapidly adopting these systems to produce anatomical models and surgical guides on-site. This trend is decentralizing device manufacturing away from industrial hubs and toward the immediate location of patient care.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices. This regulation increases the compliance burden for manufacturers of 3D printed implants, particularly for custom-made and patient-matched products. The orthopedic segment is most affected, forcing companies to invest in clinical data generation to maintain CE marking.
A shift is occurring from standalone printer purchases to integrated platforms that bundle hardware, certified medical software, and material validation services. Large hospital systems are driving this change, seeking single-vendor accountability and streamlined workflows for their internal 3D printing labs. This pattern is most visible in advanced medical centers within the United States and Germany.
3D Printing Medical Devices Market Segmentation
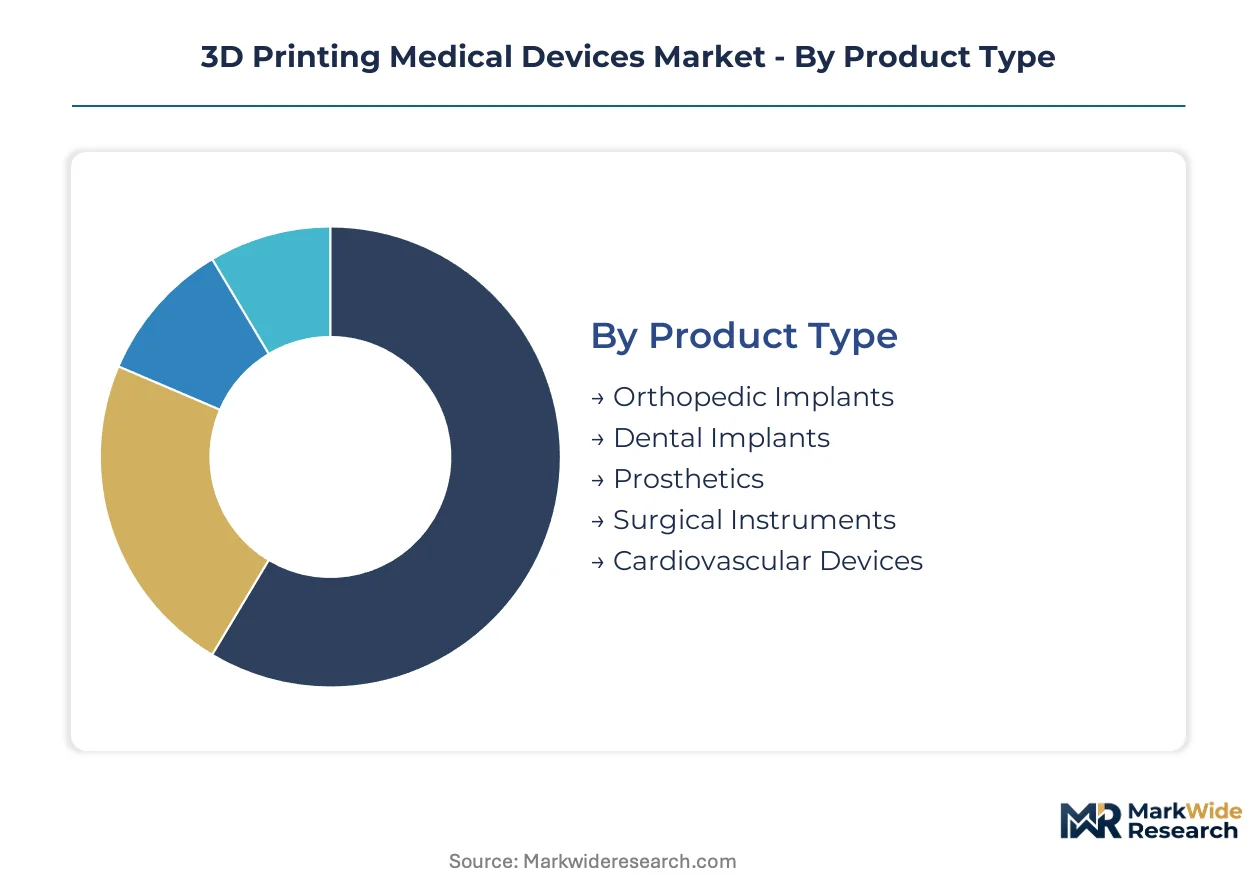
Market segmentation provides a granular view of the diverse product types, technologies, applications, and end-users driving the 3D Printing Medical Devices market. This detailed breakdown helps identify specific areas of innovation and demand concentration within the medical sector.
Product Type:
The upgrade cycle for medical devices often drives innovation, particularly for product types that see frequent patient-specific modifications.
- Orthopedic Implants:These devices include custom prostheses, joint replacements, and spinal implants, often fabricated from titanium alloys or PEEK for high strength and biocompatibility. Demand concentrates in advanced medical technology clusters within Germany and the United States, driven by the need for patient-matched solutions in reconstructive surgery.
- Dental Implants:This segment encompasses crowns, bridges, aligners, and custom surgical guides, primarily utilizing biocompatible resins and ceramics for precise fit and aesthetic integration. The growing adoption of point-of-care manufacturing in dental practices significantly fuels this segment's expansion.
- Prosthetics:Custom-fit external limbs and body parts address individual patient needs, improving comfort and functionality.
- Surgical Instruments:Patient-specific guides and instruments enhance precision and efficiency during complex surgical procedures.
- Cardiovascular Devices:Models for surgical planning and patient-specific heart valve prototypes aid in complex cardiac interventions.
Volume placements concentrate in Orthopedic Implants; the faster expansion belongs to Dental Implants.
Technology:
Technology selection in 3D printing medical devices often reflects a trade-off between precision requirements and the overall cost tier of the equipment.
- Stereolithography:This technology uses UV light to cure liquid photopolymer resins layer by layer, producing highly detailed and smooth anatomical models and surgical guides. It offers high precision for complex geometries, critical for patient-specific devices.
- Selective Laser Sintering:SLS employs a laser to fuse powdered materials like PEEK or nylon, creating strong, functional parts with complex internal structures without requiring support material. Its application in durable orthopedic implants is expanding.
- Fused Deposition Modeling:FDM extrudes thermoplastic filaments through a heated nozzle, building objects layer by layer for cost-effective prototyping and educational models.
- Digital Light Processing:DLP uses a digital light projector to cure an entire layer of liquid resin at once, enabling faster print speeds for high-resolution medical models.
- Binder Jetting:This process uses a liquid binding agent to join powdered materials, suitable for producing complex metal and ceramic parts for various medical applications.
Adoption of these technologies is primarily driven by the need for intricate geometries and material compatibility.
Application:
The varied applications cater to distinct clinical needs, each demanding specific functionalities from 3D printed medical solutions.
- Reconstructive Surgery:This application involves creating patient-specific implants for facial, cranial, and orthopedic reconstruction, significantly improving surgical outcomes and patient recovery. The demand for personalization drives the segment.
- Dental Restoration:This segment includes the production of custom crowns, bridges, and dentures, offering superior fit and aesthetics compared to traditional methods. Point-of-care manufacturing adoption in dental clinics supports its growth.
- Tissue Engineering:Bioprinting for scaffolds and cellular structures aims to repair or replace damaged tissues and organs.
- Customized Prosthetics:Tailored prosthetic limbs and devices enhance patient comfort and mobility, especially for complex cases.
- Surgical Planning:Anatomical models derived from patient scans allow surgeons to plan complex procedures with greater precision and reduce operative risks.
These applications significantly impact patient outcomes, particularly in areas requiring high levels of customization and precision.
End User:
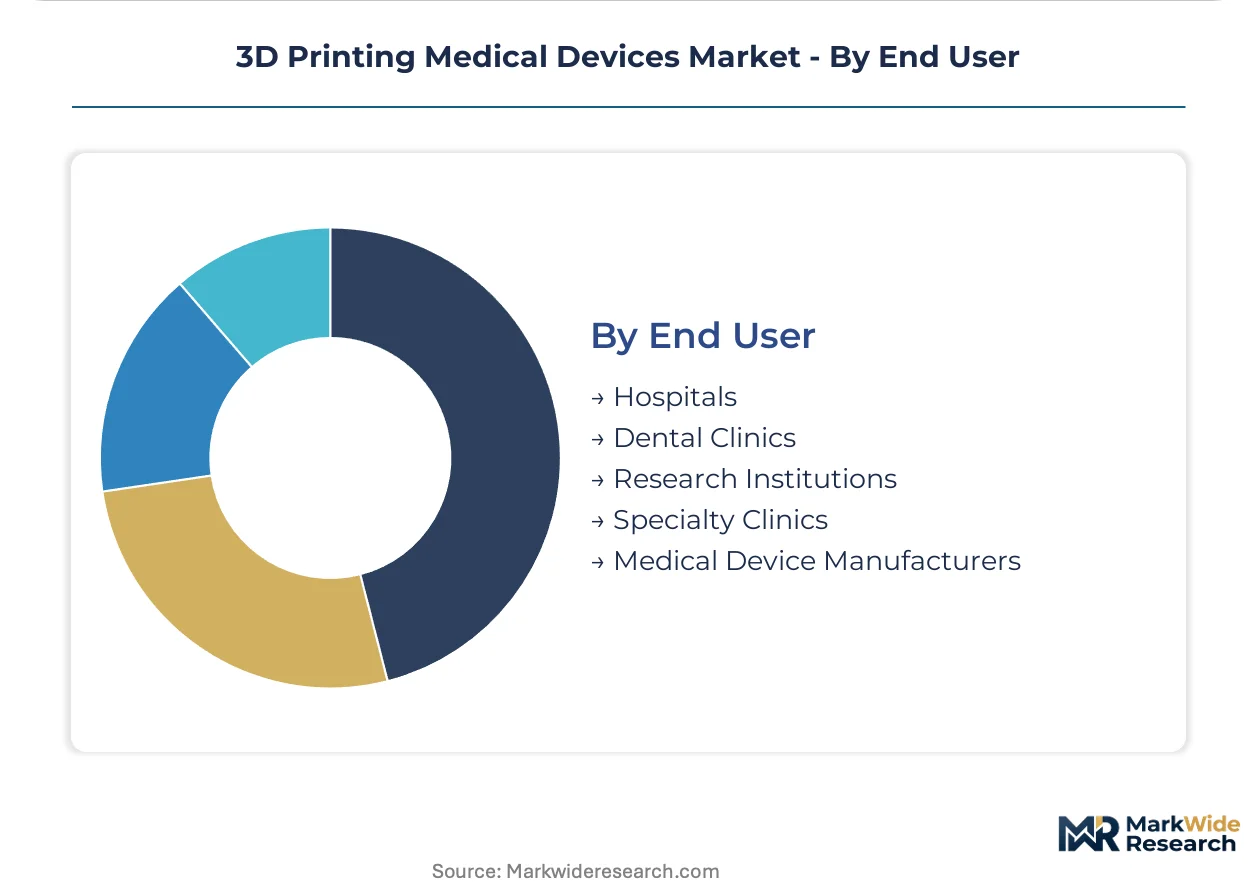
Supply concentration shifts as point-of-care manufacturing rebalances competitive dynamics among various end-user types.
- Hospitals:Large hospital systems increasingly establish in-house 3D printing labs for surgical planning models and custom implants, seeking streamlined workflows and single-vendor accountability. This trend is prominent in advanced medical centers within the United States.
- Dental Clinics:These facilities adopt compact 3D printing systems for on-site production of dental models, surgical guides, and restorations, decentralizing device manufacturing. Point-of-care adoption empowers individual practices.
- Research Institutions:Academic and private research centers utilize 3D printing for developing new biocompatible materials, bioprinting techniques, and novel medical device prototypes.
- Specialty Clinics:Orthopedic and maxillofacial clinics use 3D printing for patient-specific guides and implants, enhancing specialized surgical interventions.
- Medical Device Manufacturers:Established manufacturers integrate 3D printing into their production lines for customized components and rapid prototyping of new devices.
The trend towards decentralization is reshaping how these end users access and utilize 3D printing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloys and PEEK manufacturing hubs anchor regional demand for 3D printed medical devices. Specific regulatory frameworks and healthcare infrastructure significantly influence market development across diverse geographies. This market sees concentrated innovation in advanced medical technology clusters.
United States
Demand for personalized reconstructive surgery and intricate dental implants drives market expansion. The FDA's clear guidance for additively manufactured devices provides a predictable market approval pathway. Advanced medical centers in Boston and California lead the adoption of in-house 3D printing labs, fostering clinical innovation.
Germany
The country's strong orthopedic segment and advanced medical technology clusters fuel demand for patient-specific implants. The European Union's Medical Device Regulation (MDR) imposes stricter compliance burdens, affecting market access for novel devices. Munich and Berlin are hubs for specialized clinics and research institutions, actively utilizing additive manufacturing.
Japan
A rapidly aging population and high demand for precision dental solutions stimulate the 3D printing medical devices market. Japan's PMDA mandates rigorous testing for biocompatibility and mechanical performance. Tokyo's medical device manufacturers and research institutions focus on high-precision Stereolithography applications, particularly for anatomical models.
China
Modernizing healthcare infrastructure and a large patient base needing orthopedic and dental solutions drive significant market potential. The NMPA regulates medical devices, requiring local clinical data for market approval. Shanghai and Guangzhou host burgeoning medical technology parks and manufacturing facilities, expanding domestic production.
Brazil
The growing need for customized prosthetics and surgical planning models supports market penetration in Latin America. ANVISA provides regulatory oversight for medical devices, influencing product availability. São Paulo's private hospital systems and dental practices increasingly adopt point-of-care manufacturing, decentralizing device production.
3D Printing Medical Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche applications and advanced material innovation, particularly in bioprinting. The market structure exhibits fragmentation, with specialized software providers coexisting with integrated hardware manufacturers and service bureaus. Three distinct archetypes emerge: comprehensive solution providers, material specialists, and certified software developers. Strategic partnerships and portfolio diversification are dominant competitive moves, aiming to expand application reach, ensure regulatory compliance, and address evolving clinical needs.
On the integrated solutions vector, US-based 3D Systems, Inc. exemplifies a strategy combining printers, materials, and on-demand manufacturing services for a broad customer base. Materialise NV, a Belgian-based public limited company, anchors the certified medical software and patient-specific surgical guide segment, focusing on digital workflow integration. Stratasys Ltd., a US-based public company, represents a material-centric approach, leveraging its extensive portfolio to serve diverse medical applications, from prototyping to end-use parts. These players collectively demonstrate varied approaches to market penetration and value creation, ranging from comprehensive offerings to specialized niche plays within the industry.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems, Inc. |
| Materialise NV |
| EOS GmbH |
| EnvisionTEC |
| Renishaw plc |
| Formlabs |
| Carbon Inc. |
| HP Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-backed specialists often drive consolidation, influencing supply chain efficiencies and standardizing pricing for niche 3D printed medical devices. Family-owned mid-caps prioritize long-term relationships, shaping stable pricing and localized supply.
Pricing Analysis
Volume-based pricing dominates for standardized anatomical models, while patient-specific implants command higher margins due to customization. The dominant pricing structure blends per-unit transactional models for common items with value-based pricing for complex patient-matched devices. Price differentiation stems from the customization level and specific regulatory certification required for implantable materials. Pricing softness stems from increasing competition among point-of-care system providers. Dental clinics demonstrate higher price sensitivity compared to large hospital systems procuring specialized orthopedic implants.
Supply Chain Analysis
Logistics and freight costs significantly influence the final price of specialized medical-grade materials and finished 3D printed devices. Geographic supply concentrates in advanced manufacturing hubs like Germany, the United States, and Japan. Raw material dependencies center on titanium alloys, PEEK, and specialized biocompatible photopolymers. Single-source vulnerability for advanced implantable materials presents a structural risk. Distribution runs through direct sales channels to large hospital systems and specialized distributors serving dental and specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D Printing Medical Devices market is undergoing a significant technology-transition phase, with additive manufacturing replacing traditional subtractive methods for patient-specific solutions. This shift redefines production capabilities and clinical outcomes.
For Market Incumbents: Lock in long-term contracts with large hospital systems for integrated 3D printing platforms to secure market share. Invest in certified software solutions and material validation services to address the threat of decentralized point-of-care manufacturing. Pursue strategic acquisitions of specialized material science firms to deepen vertical integration. R&D investments in advanced biocompatible photopolymers provide a crucial lever against emerging competitors. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models targeting specialized dental practices and smaller orthopedic clinics. Target white space in emerging geographic markets like Southeast Asia for customized prosthetics. The dental restoration segment offers the most penetrable application due to its high demand for personalization. A go-to-market angle focusing on user-friendly compact systems with bundled software can attract new customers. For Investors and Strategic Acquirers: Distressed-cycle entries favor technology integrators in the United States and Germany specializing in medical software or advanced materials. The market demonstrates strong long-term viability over a 5-10 year window, driven by persistent demand for patient-specific solutions. Acquisition targets include mid-cap firms with robust intellectual property in biocompatible photopolymers or AI-powered design automation. The signal to watch is accelerated regulatory clarity from the FDA for novel bioprinted tissues and organs.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Generation for MDR | Ensures CE marking compliance for orthopedic implants in the European Union. |
| AI-Powered Design Automation Integration | Reduces manual design time for patient-specific implants from medical scans. |
| Biocompatible Photopolymer R&D | Expands clinical applications for durable, complex implants in orthopedic surgery. |
| Point-of-Care System Development | Decentralizes device manufacturing, empowering individual clinics and dental practices. |
| Strategic Partnerships with Hospitals | Streamlines workflows and ensures single-vendor accountability for in-house 3D printing labs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with biomedical engineers, hospital purchasing managers, dental practitioners, and regulatory affairs specialists provided critical insights. Secondary data sources included FDA guidance documents, EU MDR publications, and academic journals. This approach combined bottom-up data aggregation with top-down market validation, ensuring robust data integrity.
Data-stream reconciliation across multiple sources refined the analytical framework for the market forecast. Quantitative modeling projected market dynamics across the analysis window, segmented by product type, technology, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected adoption rates for patient-specific solutions. Key forecast inputs included patient demographics for reconstructive surgery and material science advancements.
Regulatory shifts, material cost volatility, and technological breakthroughs are the dominant revision risks for market forecasts. Forecasts reflect assumptions concerning market access and clinical adoption rates for novel devices. Unforeseen changes in FDA or EU MDR guidelines could significantly impact market trajectories. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ehealth Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Global Prosthetics Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
Hemoconcentrators Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Ventilation Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Corneal Implants Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Functional Electrical Stimulation Market