
 Infusion Fluid Holder Market | 2026-2036
Infusion Fluid Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Infusion Fluid Holder Market Foresight
Asset-light leasing and equipment-as-a-service models are rewriting capital deployment patterns for mid-size hospital systems seeking infusion infrastructure without balance-sheet strain. B. Braun Melsungen AG leverages captive manufacturing of stainless steel holders to sustain margin control across European and North American accounts. Baxter International Inc. anchors its position through deep integration with IV therapy sets, creating bundled procurement leverage. ICU Medical, Inc. specializes in fluid management accessories that compete on compatibility breadth rather than hardware price alone.
An infusion fluid holder is a mechanical support device, typically fabricated from stainless steel, aluminum, or medical-grade polymers, designed to suspend intravenous bags or bottles at calibrated heights to maintain gravity-driven flow rates between 10 and 125 milliliters per hour. Wall-mounted holders dominate installed base in acute care settings where permanent fixture reduces floor congestion and infection risk, while portable holders represent the fastest-expanding category as ambulatory surgical centers and home healthcare programs prioritize mobility. Stainless steel constructions command premium positioning due to sterilization durability and regulatory acceptance, whereas plastic variants occupy cost-sensitive segments in clinics and medical training environments.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and testing expenditures for holder manufacturers seeking commercial access. ISO 13485 quality management certification functions as a de facto market entry threshold for suppliers serving integrated health networks and group purchasing organizations. Stakeholders must monitor evolving home healthcare reimbursement codes and ambulatory facility accreditation standards, as these payment and credentialing mechanisms increasingly determine holder specification requirements outside traditional hospital procurement channels.
Market Dynamics
EU MDR technical documentation obligations and FDA 510(k) clearance timelines are compressing product development cycles for infusion fluid holder manufacturers, forcing capital reallocation toward sterilization validation and biocompatibility testing before commercial release.
Growth Catalysts
- Aging demographics in Japan and Germany:Chronic disease prevalence in these markets sustains hospital admission rates and IV therapy utilization, expanding installed base demand for wall-mounted holder systems.
- EU MDR compliance mandates:Stricter technical documentation requirements for medical device stability are pushing healthcare systems toward validated stainless steel constructions with established regulatory pathways.
- Ambulatory surgical center expansion:Freestanding ASCs prioritize portable holder mobility to support same-day discharge protocols and flexible room configurations.
Market Restraints
- Stainless steel price volatility:Raw material input fluctuations squeeze margin structures for manufacturers without captive metalworking capabilities or long-term supply agreements.
- Supply concentration in German precision metalworking:Specialized fabrication clusters create geographic dependency risk for holders requiring tight tolerance machining and surface finishing.
- Polymer substitution ceiling:Medical-grade plastics face sterilization durability limitations that cap their penetration in acute care settings requiring autoclave cycling.
Strategic Opportunities
- Home healthcare reimbursement expansion:Shifting payment codes in the United States create pull-through demand for lightweight, patient-operated portable holders outside institutional settings.
- Equipment-as-a-service leasing:Asset-light subscription models reduce capital barriers for mid-size hospital systems seeking infusion infrastructure without balance-sheet strain.
- Smart holder sensor integration:Convergence of mechanical supports with load-cell monitoring and wireless inventory tracking creates premium positioning in integrated health networks.
Industry Challenges
- ISO 13485 certification timeline compression:Quality management system audits and documentation reviews extend time-to-market for new holder variants, requiring dedicated regulatory affairs staffing.
- Legacy IV pole integration complexity:New holder designs must maintain backward compatibility with existing ceiling track systems and rail mounts, constraining form factor innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infusion Fluid Holder Market |
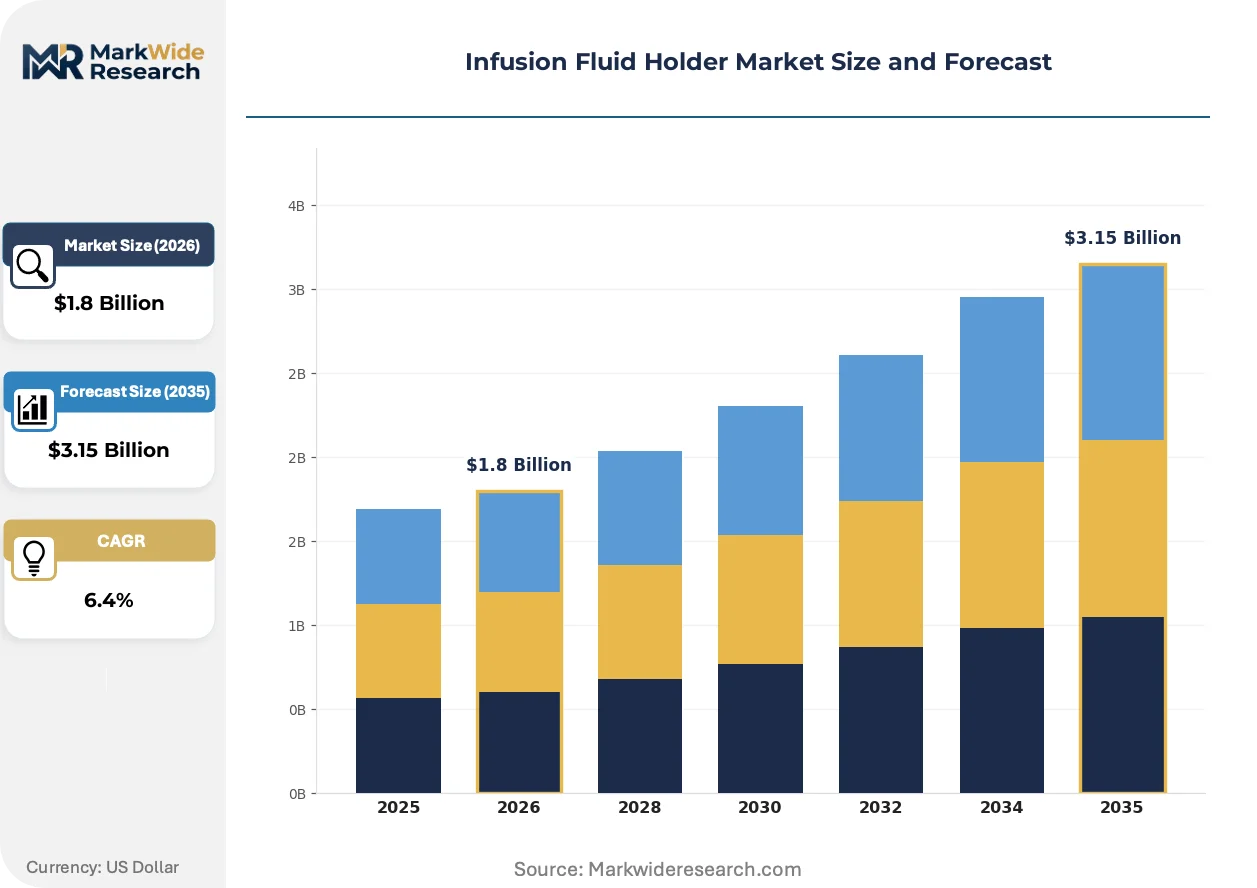
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Holders, Adjustable Holders, Portable Holders, Clamp Holders End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Material: Plastic, Stainless Steel, Aluminum, Rubber Application: IV Therapy, Fluid Management, Medical Training, Emergency Care |
| Companies Covered | B. Braun Melsungen AG, Baxter International Inc., ICU Medical, Inc., Fresenius Kabi AG, Smiths Medical, Pedigo Products, Medline, AGA Sanitätsartikel, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infusion Fluid Holder Market Shifts & Advancements
Material science advances and regulatory digitization are converging to redefine holder performance specifications and commercial access pathways across acute and ambulatory care environments.
Hybrid composite construction is hybridizing traditional stainless steel cores with polymer overmolding to reduce weight while maintaining sterilization durability. Ambulatory surgical centers in the United States are piloting these configurations for same-day procedure workflows. The technology is hybridizing procurement criteria by collapsing the historical trade-off between metal performance and plastic cost positioning.
EU MDR Article 10 technical documentation requirements are mandating expanded clinical evidence and post-market surveillance for holder stability claims. Manufacturers serving European accounts must now maintain electronic systems for incident reporting and periodic safety updates. Class I device reclassification pressures are most acute for plastic holder variants with limited historical biocompatibility data.
Group purchasing organization consolidation is compressing supplier negotiation cycles and unbundling after-sales service from hardware procurement. Integrated delivery networks are replacing individual hospital purchasing with centralized contracts spanning multiple facilities. This pattern is most visible in the United States, where GPOs like Premier and Vizient account for substantial acute care procurement volume.
Infusion Fluid Holder Market Segmentation
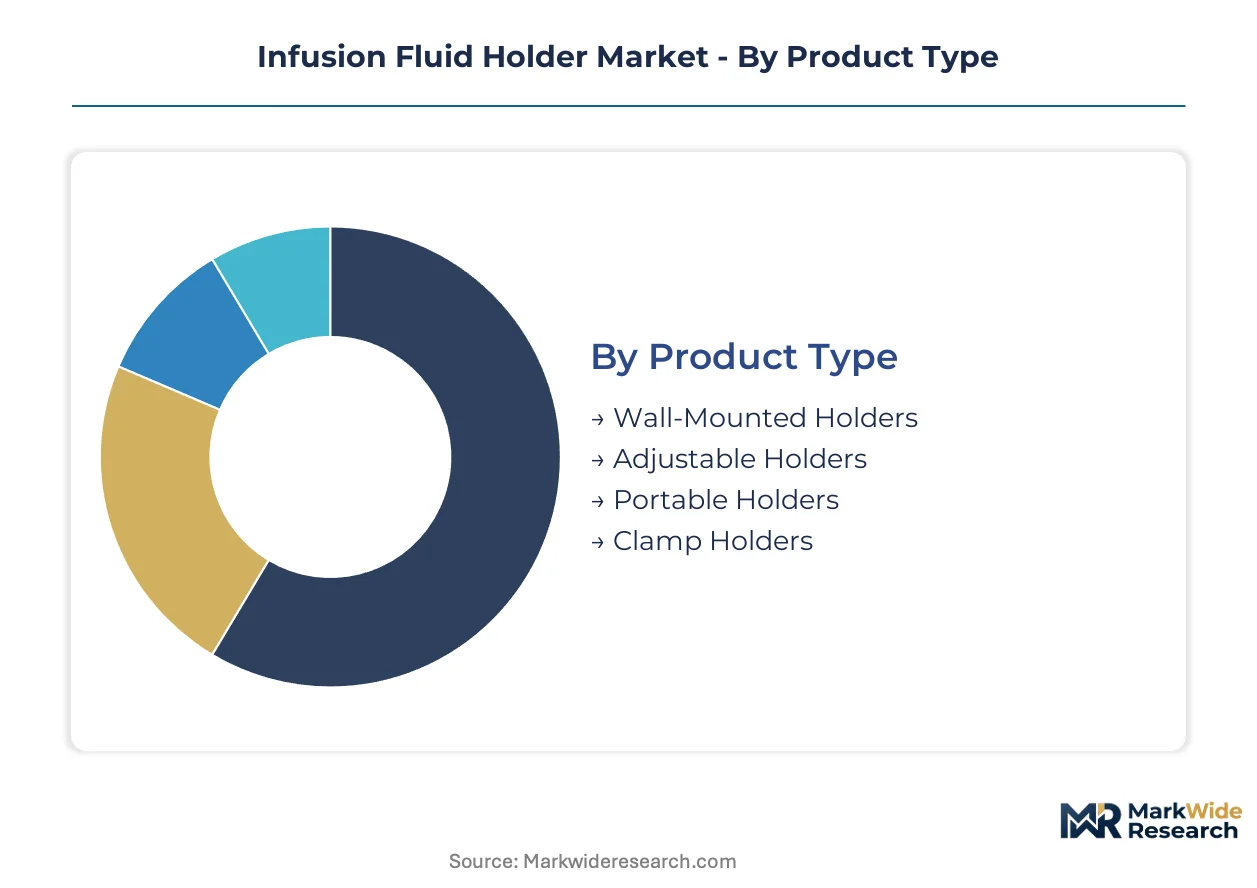
Infusion fluid holder procurement patterns diverge sharply across acute care versus ambulatory settings, with product lifespan and utilization intensity driving replacement cycles. Material selection and mounting configuration determine regulatory pathway complexity and sterilization protocol compatibility.
Product Type:
Wall-mounted holders turn over slowest due to permanent installation and capital depreciation schedules, while portable units cycle fastest from wear damage and loss in high-mobility environments.
- Wall-Mounted Holders:Fixed stainless steel or aluminum brackets affixed to structural walls or ceiling tracks in operating suites and intensive care units. United States hospital construction booms in Texas and Florida sustain new installation demand as facilities expand bed capacity.
- Portable Holders:Freestanding IV poles with wheeled bases and adjustable height mechanisms for patient transport and temporary bedside use. German rehabilitation clinics and Japanese home healthcare programs drive replacement volume from intensive daily repositioning.
- Adjustable Holders:Telescoping or articulated arm systems permitting calibrated height modification without full pole relocation.
- Clamp Holders:Rail-mounted or bed-integrated brackets securing fluid containers to existing furniture infrastructure.
Wall-Mounted Holders anchors the volume base while Portable Holders gains share at the steepest rate.
End User:
Procurement scale concentrates in institutional buyers with centralized supply chains, though reimbursement shifts are fragmenting purchasing authority toward outpatient and residential channels.
- Hospitals:Acute care facilities with 100+ beds operating 24/7 infusion services across medical, surgical, and oncology units. United States integrated delivery networks negotiate multi-year holder contracts through Premier and Vizient GPOs, bundling hardware with IV set purchases.
- Home Healthcare:Medicare-certified agencies and private duty nursing services delivering infusion therapy in residential settings. Shifting reimbursement codes in the United States create pull-through demand for lightweight patient-operated portable holders.
- Clinics:Outpatient facilities performing same-day procedures with limited overnight stays.
- Rehabilitation Centers:Post-acute facilities managing long-term IV antibiotic or pain management protocols.
Hospitals command the procurement volume base while Home Healthcare expands most quickly from reimbursement migration.
Material:
Cost tier stratification separates premium metal constructions from commodity polymer alternatives, with sterilization durability dictating acute care specification requirements.
- Stainless Steel:Medical-grade 304 or 316L alloys with electropolished surfaces withstanding autoclave cycling and caustic disinfectants. EU MDR compliance mandates in Germany and France push healthcare systems toward validated stainless steel constructions with established regulatory pathways.
- Plastic:Medical-grade polycarbonate or ABS polymers offering weight reduction and color-coding flexibility at lower unit cost. Medical training programs in the United States and India favor disposable plastic variants for simulation labs where sterilization is non-critical.
- Aluminum:Anodized lightweight metal for portable applications requiring corrosion resistance without stainless steel mass.
- Rubber:Elastomeric components for grip surfaces, wheel casters, and vibration dampening in mobile configurations.
Stainless Steel dominates the revenue base while Plastic climbs the fastest from cost-sensitive segment penetration.
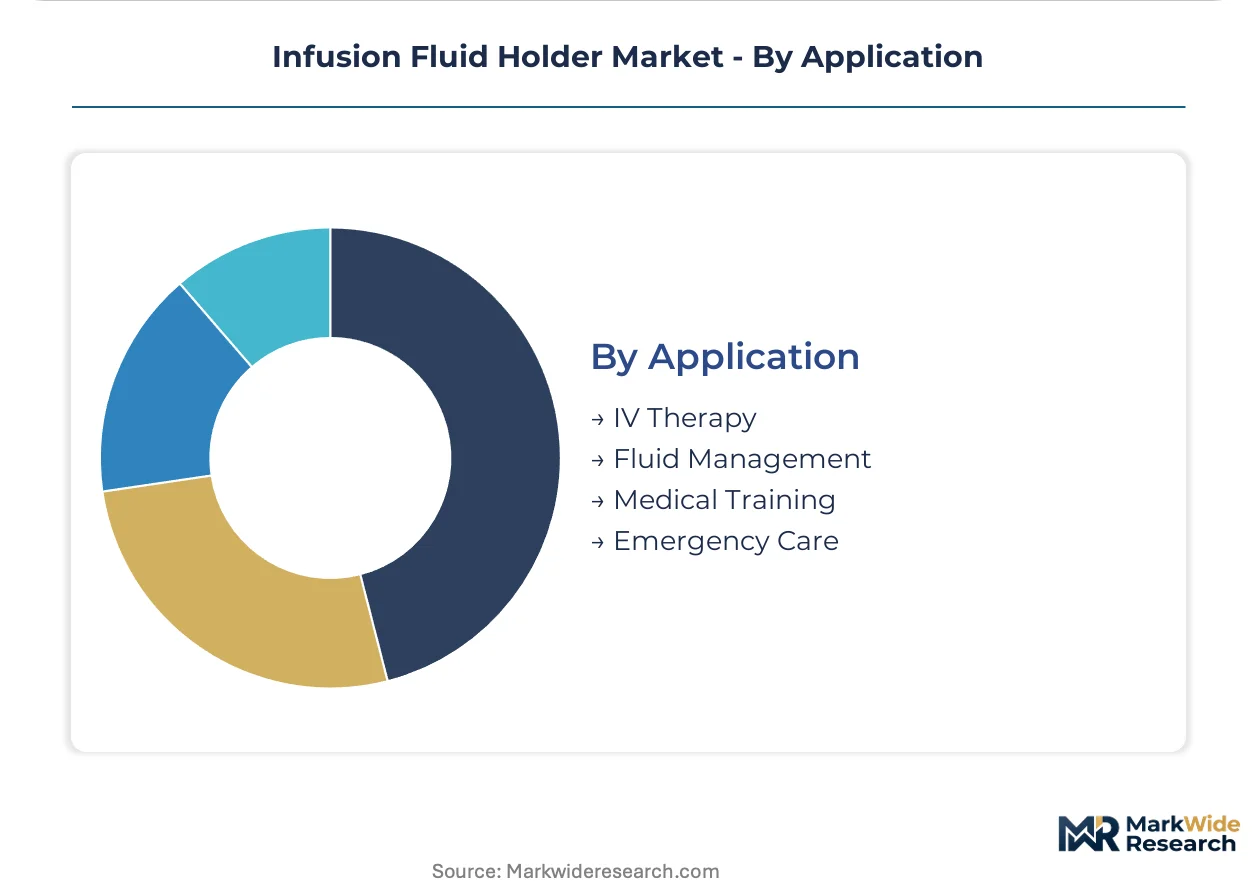
Application:
Clinical workflow intensity varies dramatically across scheduled therapy versus emergency intervention, with utilization patterns shaping holder durability specifications.
- IV Therapy:Scheduled administration of antibiotics, chemotherapy, parenteral nutrition, and hydration across inpatient and outpatient settings. Japan's aging demographic sustains hospital admission rates and IV therapy utilization, expanding installed base demand for wall-mounted holder systems.
- Emergency Care:Rapid fluid resuscitation in trauma bays and emergency departments requiring immediate access and rapid room turnover. Ambulatory surgical centers in the United States prioritize portable holder mobility to support same-day discharge protocols.
- Fluid Management:Controlled drainage and irrigation systems in surgical and wound care applications.
- Medical Training:Simulation and educational environments where holders experience low mechanical stress without patient contact.
IV Therapy anchors the installed base while Emergency Care shows the steepest expansion trajectory from ASC volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and Japan concentrate the highest-volume purchasing authority for infusion fluid holder systems, with integrated delivery networks and government tenders shaping specification requirements across acute care settings.
United States
Texas and Florida hospital construction booms sustain new installation demand for wall-mounted holders as facilities expand bed capacity. FDA 510(k) clearance timelines compress product development cycles, forcing capital toward sterilization validation. Premier and Vizient group purchasing organizations in the Midwest negotiate multi-year contracts bundling hardware with IV set purchases.
Germany
EU MDR technical documentation obligations push healthcare systems toward validated stainless steel constructions with established regulatory pathways. Precision metalworking clusters in Baden-Württemberg supply tight-tolerance machining for premium holder variants. Rehabilitation clinics in Bavaria drive portable holder replacement volume from intensive daily repositioning protocols.
Japan
Aging demographics sustain hospital admission rates and IV therapy utilization, expanding installed base demand for wall-mounted systems. PMDA quality management requirements align with ISO 13485 certification thresholds for suppliers. Home healthcare programs in the Kanto region around Tokyo prioritize lightweight portable holders for residential infusion delivery.
India
Medical training programs favor cost-sensitive plastic holder variants for simulation labs where sterilization is non-critical. CDSCO medical device rules create compliance pathways for both imported and domestically manufactured holders. Manufacturing activity concentrates in Gujarat and Maharashtra for polymer-based holder assembly serving clinic and educational segments.
United Kingdom
NHS procurement frameworks standardize holder specifications across acute trusts, favoring stainless steel durability for autoclave cycling. MHRA post-market surveillance requirements align with EU MDR incident reporting obligations for suppliers. London and Southeast England hospital networks anchor volume demand through centralized supply chain contracts.
Infusion Fluid Holder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments where group purchasing organization leverage shapes margin structures. The vendor base separates into three archetypes: diversified medical device conglomerates with captive manufacturing, focused infusion therapy specialists, and regional metalworking fabricators serving cost-sensitive accounts. M&A activity concentrates on acquiring ISO 13485-certified production facilities, while strategic partnerships with GPOs lock in multi-year supply commitments.
Within the diversified conglomerate tier, B. Braun Melsungen AG and Baxter International Inc. occupy positions reflecting European and North American manufacturing heritage. ICU Medical, Inc. represents the infusion-focused specialist archetype competing on compatibility breadth rather than hardware price positioning alone. Among these anchors, geographic origin and corporate structure signal divergent strategic postures: German AG-format entities emphasize captive metalworking control, US Inc.-format players leverage IV therapy set integration, and focused specialists prioritize accessory ecosystem breadth.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Baxter International Inc. |
| ICU Medical, Inc. |
| Fresenius Kabi AG |
| Smiths Medical |
| Pedigo Products |
| Medline |
| AGA Sanitätsartikel |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
The Rotterdam-Rhine freight corridor's container rate volatility feeds directly into landed cost spreads between German precision metalworking clusters and North American distribution hubs, compressing margin buffers for stainless steel holder manufacturers while amplifying price differentiation between validated EU MDR-compliant systems and non-certified alternatives.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between German fabricators and integrated delivery networks, embedding raw material pass-through mechanisms that shield suppliers from nickel price swings. Three-tier pricing structure across premium, standard, and economy levels separates electropolished 316L stainless steel systems with full FDA 510(k) documentation from anodized aluminum portables and medical-grade polycarbonate training variants. Cost compression in the plastic holder segment is intensifying because Indian manufacturers are scaling injection-molding capacity for simulation lab buyers. Clinic procurement committees exhibit the highest price sensitivity, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates risk planning for premium holder suppliers serving hospital construction booms in Texas and Florida. Manufacturing gravity centers on Baden-Württemberg for precision machining, Gujarat for polymer assembly, and Pennsylvania for aluminum extrusion. Raw material flows draw from Finnish stainless steel mills, Chinese rare earth processors for anodizing chemicals, and Saudi petrochemical complexes for polycarbonate feedstock. Single-source vulnerability concentrates in specialized surface finishing equipment sourced exclusively from Italian OEMs. Distribution runs through Premier and Vizient GPOs for United States acute care, direct hospital contracts for German rehabilitation clinics, and layered distributor networks for Indian medical training programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infusion fluid holder market is accelerating through EU MDR digitization mandates that reclassify mechanical supports as active surveillance devices, forcing compliance investments that favor scaled incumbents with captive regulatory affairs staffing.
For Market Incumbents: Build certification moats by accelerating ISO 13485:2016 transition audits ahead of notified body capacity constraints, while acquiring precision metalworking facilities in Baden-Württemberg to secure tight-tolerance machining capacity against emerging Asian competitors. Threat substitution from polymer holders with embedded RFID tracking demands counter-investment in smart holder sensor integration to maintain premium positioning in integrated delivery networks. For New Entrants and Emerging Players: Pursue home healthcare reimbursement expansion in the United States by developing lightweight patient-operated portable holders compatible with Medicare-certified agency workflows, bypassing GPO-controlled hospital procurement entirely. The most penetrable white space sits in Japanese residential infusion programs where PMDA quality requirements align with ISO 13485 thresholds already familiar to Western manufacturers. Go-to-market execution should anchor on direct partnerships with Kanto-region home healthcare agencies rather than distributor layering. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core medical device divisions lacking EU MDR technical documentation capabilities. Long-term viability over the projection horizon hinges on regulatory digitization infrastructure rather than hardware scale alone. Acquisition priority should focus on ISO 13485-certified fabricators with established European notified body relationships. The signal to watch is FDA 510(k) clearance timeline compression for novel holder-sensor convergence products, which will separate investable platforms from commodity metalworking operations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Electronic post-market surveillance systems satisfy Article 10 obligations for German hospital tenders. |
| Smart Holder Sensor Integration | Load-cell monitoring with wireless inventory tracking commands premium positioning in Premier GPO contracts. |
| Home Healthcare Reimbursement Strategy | Medicare-certified agency partnerships bypass traditional hospital procurement concentration. |
| Captive Precision Metalworking Acquisition | Baden-Württemberg facility control secures tight-tolerance machining against supply concentration risk. |
| ISO 13485:2016 Transition Acceleration | Notified body audit prioritization compresses time-to-market for new holder variants. |
Research Methodology
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and home healthcare agency operations leads anchored the qualitative base for this analysis. Primary field engagement combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, CMS Medicare reimbursement code releases, and Premier-Vizient GPO contract award records. Bottom-up demand modeling from installed base replacement cycles and top-down supply validation from precision metalworking capacity disclosures were triangulated to constrain forecast variance.
Scenario-bracketing around EU MDR implementation pace and home healthcare reimbursement migration framed the analytical approach across the analysis window. Segmentation dimensions modeled include mounting configuration, material grade tier, end-user channel, and regional regulatory cluster complexity. CAGRs were derived from weighted average of historical replacement cycle analysis and forward projection of ambulatory surgical center construction permits. Industry-specific forecast inputs incorporated stainless steel price index trajectories and notified body audit queue lengths.
Sensitivities concentrate around EU MDR Class I reclassification timing, nickel price volatility impacts on stainless steel input costs, and home healthcare reimbursement code expansion velocity. Forecasts embed assumptions regarding GPO consolidation pace and ambulatory facility accreditation standard evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Deaver Retractor Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Photopheresis Products Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Vaginal Inserts Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Education Microscope Market