
 Global Power Management IC (PMIC) Market | 2026-2036
Global Power Management IC (PMIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Management IC (PMIC) Market Outlook
A capital-intensity divergence between players is reorganizing competitive tiers in the PMIC landscape. Texas Instruments sustains the broadest catalog of proprietary process technologies, spanning from sub-micron BCD to advanced GaN integration. Infineon Technologies AG dominates automotive-grade voltage regulators through its captive 300mm fab network in Europe and Asia. STMicroelectronics NV leverages long-standing relationships with European industrial OEMs to anchor its position in motor-drive and factory-automation PMIC segments.
Power Management ICs are monolithic or multi-chip devices that regulate, convert, and distribute electrical power across electronic systems, typically operating at switching frequencies from hundreds of kilohertz to several megahertz while managing load currents from milliamps to tens of amps. Their primary purpose is to maximize energy efficiency, extend battery life, and ensure thermal stability in everything from smartphones to electric drivetrains. Battery Management ICs command the highest margin pools as electrification raises the complexity of cell balancing and safety monitoring across lithium-ion packs. Switching Regulators are displacing Linear Regulators in compute and telecom applications where efficiency above ninety percent is mandatory. Mixed-Signal technology leads the architecture mix, combining precision analog sensing with digital control loops to enable adaptive voltage scaling in processors and AI accelerators.
The U.S. Environmental Protection Agency and the European Union's Ecodesign Directive are tightening minimum efficiency standards for external power supplies, directly mandating specific load-profile performance thresholds that only advanced PMIC architectures can meet. China's Ministry of Industry and Information Technology enforces GB standards on standby power consumption for domestic appliances, creating a bifurcated compliance landscape for multinational suppliers. Japan's METI pursues Top Runner programs that continuously ratchet efficiency benchmarks, forcing iterative PMIC redesign cycles across consumer electronics. Stakeholders must monitor how regional efficiency mandates diverge and decide whether to architect region-specific PMIC families or pursue unified platforms that satisfy the strictest jurisdiction.
Market Dynamics
The PMIC sector is restructuring around BCD process capacity constraints, where automotive and telecom OEMs now compete for identical 200mm and 300mm wafer allocations at foundries in Taiwan, China, and Europe.
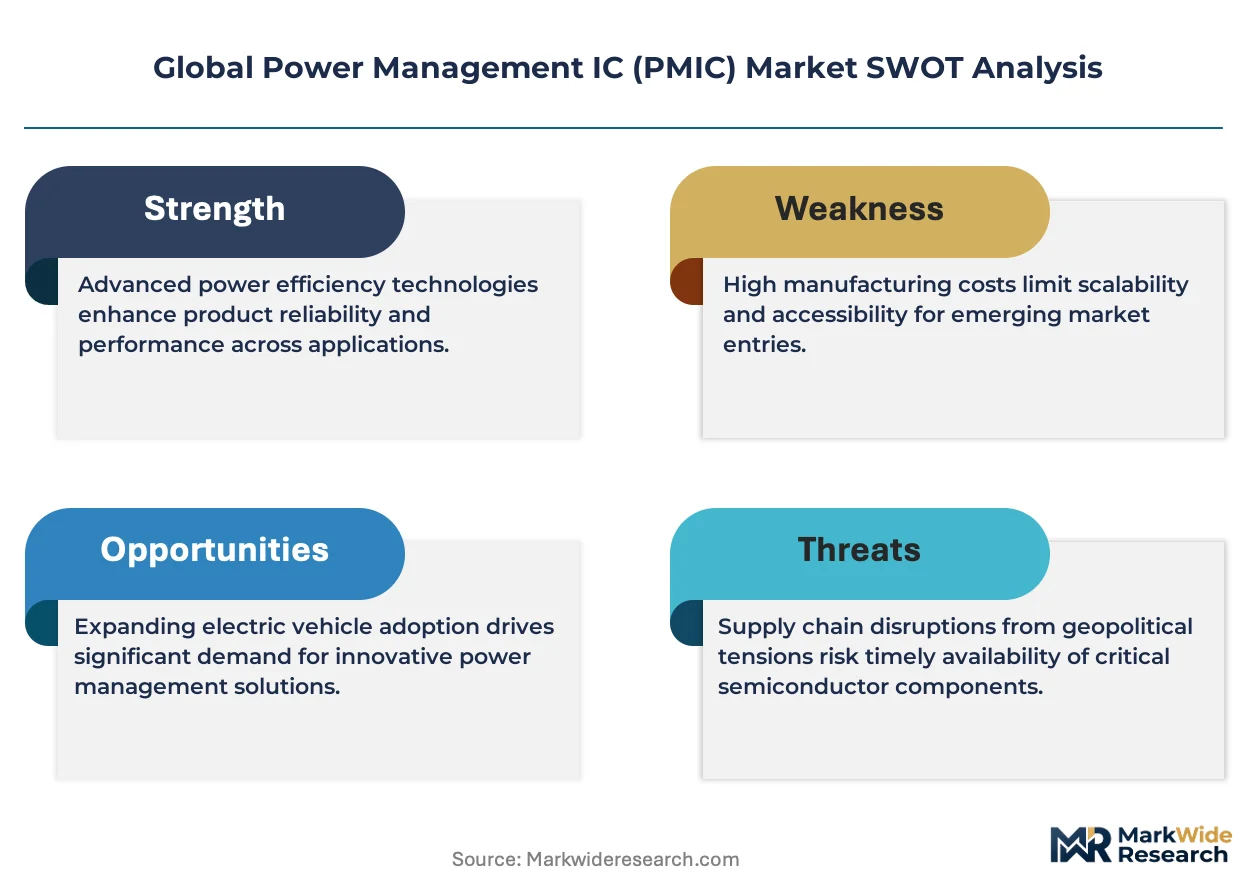
Growth Catalysts
- EU Green Deal efficiency mandates:The Ecodesign Directive's standby power limits are forcing appliance OEMs across Germany and France to redesign regulator architectures, pulling high-efficiency PMIC volumes.
- Electric vehicle battery systems:Automotive electrification is accelerating procurement of high-voltage battery management ICs for 800V architectures and onboard charging modules.
- GaN-on-Si integration:Gallium nitride power stages are decomposing traditional silicon MOSFET-plus-driver combinations in data center and telecom rectifier applications.
Market Restraints
- 300mm BCD wafer shortages:Captive automotive fabs at Infineon and STMicroelectronics are absorbing available capacity, leaving fabless suppliers exposed to allocation cuts.
- Copper and rare earth price volatility:Magnetics and packaging materials constitute 35-45% of PMIC BOM costs, with indium and gallium supply concentrated in Chinese refining operations.
- Linear regulator substitution ceiling:Noise-sensitive medical and precision instrumentation segments cannot tolerate switching ripple, freezing migration paths in those niches.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic mobile and appliance manufacturing incentives are creating demand for locally sourced PMICs with BIS certification.
- AI accelerator voltage rails:Multi-phase controllers with sub-millivolt transient response are opening adjacent high-margin pools beyond traditional CPU/GPU sockets.
- Japan METI Top Runner efficiency tiers:Continuous benchmark ratcheting forces iterative PMIC redesigns, locking in recurring engineering service contracts with Japanese consumer electronics OEMs.
Industry Challenges
- Mixed-signal analog designer scarcity:BCD process expertise combining precision voltage references with high-voltage lateral DMOS transistors resides in a shrinking cohort of experienced engineers.
- AEC-Q100 qualification timelines:Automotive-grade PMICs require 12-18 month validation cycles for temperature, EMC, and lifetime drift specifications.
- Legacy 5V/3.3V rail coexistence:Industrial control systems running 20-year lifecycles demand backward-compatible PMIC footprints that constrain die-shrinking roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Management IC (PMIC) Market |
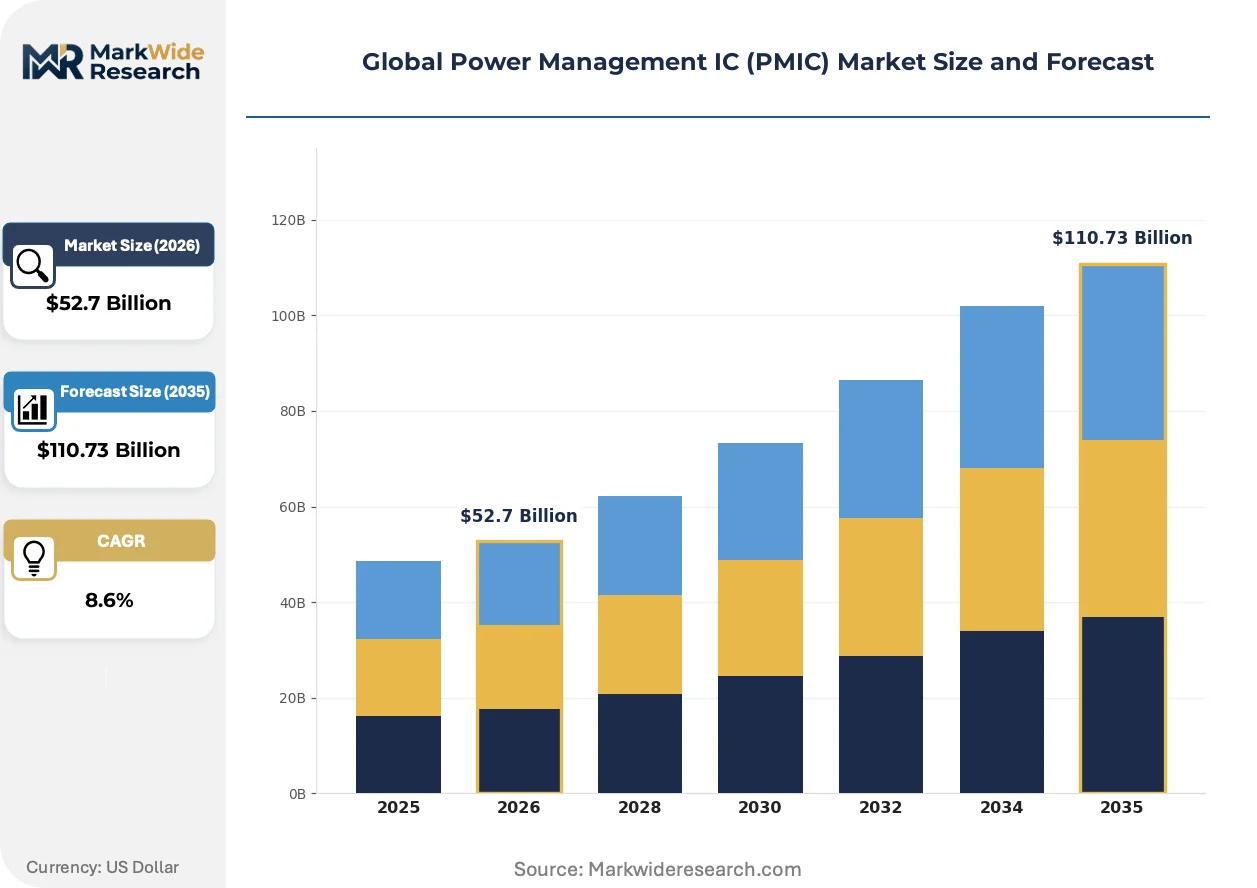
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Regulators, Switching Regulators, Voltage References, Battery Management ICs End User: Consumer Electronics, Automotive, Industrial, Telecommunications Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: Analog, Digital, Mixed-Signal, Power Factor Correction |
| Companies Covered | STMicroelectronics NV, ON Semiconductor Corp., Texas Instruments Inc., Microchip Technology Inc., Renesas Electronics Corp., Analog Devices, Inc., NXP Semiconductors NV, ROHM Co., Ltd., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Management IC (PMIC) Market Strategic Shifts
Process migration and topology innovation are compressing power stage footprints while regulatory fragmentation forces multi-jurisdictional platform architectures.
Digital power management controllers with firmware-configurable control loops are decomposing fixed-analog compensation networks in server and base station power supplies. Hyperscale data center operators in Virginia and Oregon are standardizing on PMBus-enabled multiphase controllers that allow remote telemetry and dynamic voltage adjustment. This decomposition is collapsing the traditional boundary between power supply design and software-defined infrastructure management.
The EPA's external power supply efficiency standards and the EU Ecodesign Directive's 2019/1782 regulation are mandating specific load-profile performance thresholds that only advanced quasi-resonant flyback and active-bridge architectures can satisfy. Appliance OEMs in Italy and Poland must now certify standby power below 0.5W, disqualifying legacy discrete solutions. Compliance departments are consolidating PMIC qualification testing to avoid duplicative third-party certifications across Atlantic markets.
Direct material sourcing from foundries is displacing distributor-mediated procurement for high-volume automotive and smartphone PMIC programs. Tier-1 suppliers in Bavaria and Shenzhen are negotiating multi-year wafer supply agreements that bypass traditional semiconductor distribution channels. This disintermediation is most visible in China, where domestic EV manufacturers are securing captive PMIC allocations through equity stakes in local BCD foundries.
Global Power Management IC (PMIC) Market Segmentation
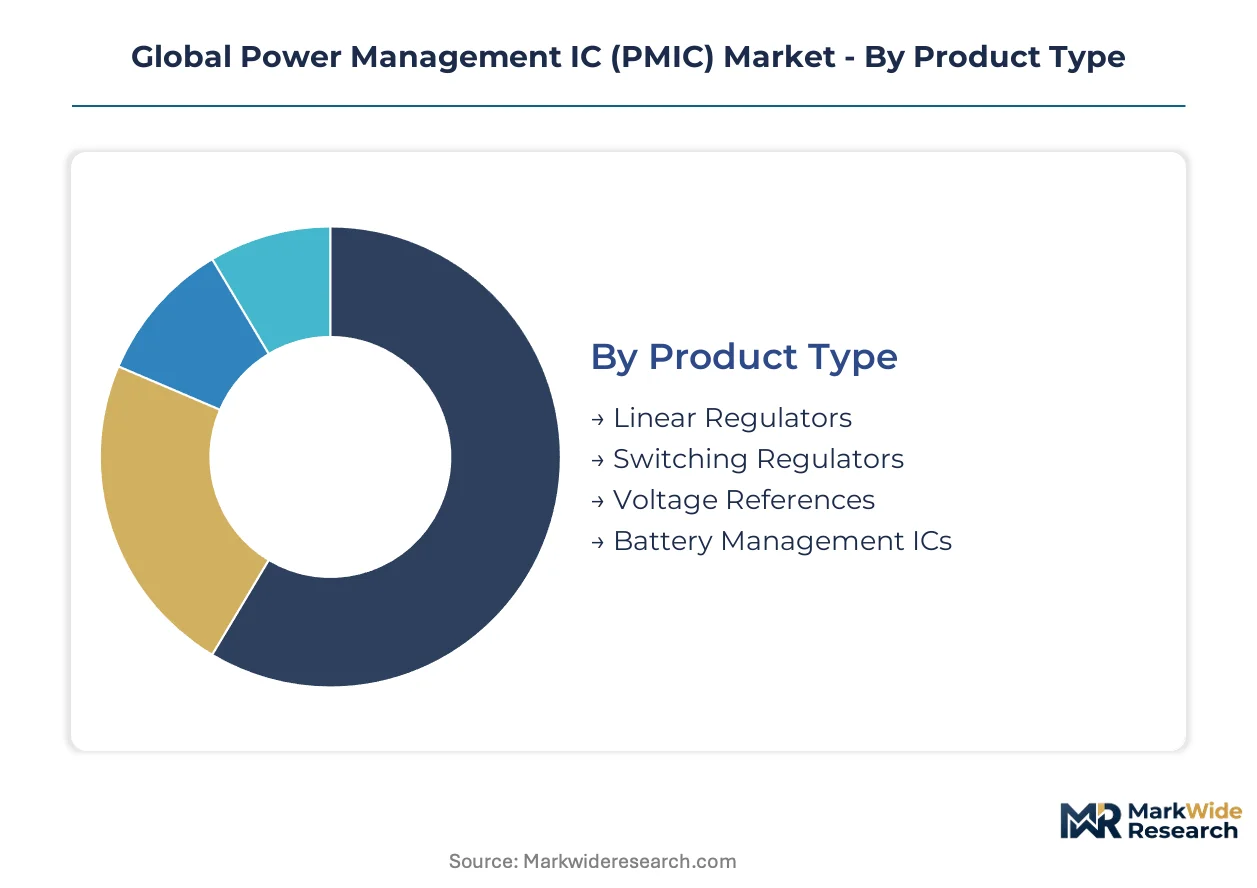
PMIC architectures fragment across voltage conversion topologies, end-use thermal requirements, and control loop implementations. Each segment carries distinct margin profiles and qualification burdens that reshape supplier positioning.
Product Type:
Switching Regulators face the most acute substitution pressure from GaN and silicon-carbide discrete solutions, while Linear Regulators defend irreplaceable positions in noise-sensitive instrumentation.
- Switching Regulators:Buck, boost, and buck-boost architectures using PWM control achieve efficiency above ninety percent in compute and telecom rectifiers. Data center operators in Virginia and Oregon are standardizing on multiphase controllers with PMBus telemetry, pulling high-frequency synchronous rectifier demand.
- Battery Management ICs:These devices orchestrate cell balancing, state-of-charge estimation, and thermal runaway protection across lithium-ion packs. Electric vehicle manufacturers in China and Germany are procuring high-voltage variants for 800V architectures, tightening foundry allocation for automotive-grade BCD processes.
- Linear Regulators:Low-dropout designs suppress switching ripple in medical imaging and precision test equipment where electromagnetic interference is unacceptable.
- Voltage References:Precision bandgap circuits provide stable baselines for ADCs and sensor signal chains in industrial automation systems.
Switching Regulators anchor the volume base while Battery Management ICs gain share at the steepest rate.
End User:
Automotive applications command the steepest cost tiers due to AEC-Q100 qualification and functional safety requirements, whereas Consumer Electronics prioritizes die-size minimization above absolute efficiency.
- Automotive:PMICs for electric drivetrains must survive temperature cycling from minus forty to one hundred fifty degrees Celsius while managing 800V battery systems. OEMs in Bavaria and Shenzhen are negotiating multi-year wafer supply agreements that bypass traditional distribution channels.
- Consumer Electronics:Smartphones and wearables demand sub-millimeter packages with sub-microamp quiescent current to extend battery life. India's PLI scheme for electronics manufacturing is creating localized demand for BIS-certified PMICs in mobile and appliance production.
- Industrial:Motor drives and factory automation require isolation-rated gate drivers and robust thermal management for twenty-year operational lifecycles.
- Telecommunications:Base stations and optical transport equipment need wide-input-range controllers with remote voltage adjustment capabilities.
Consumer Electronics ships the highest unit volumes while Automotive commands the premium pricing tier.
Deployment:
Edge Computing deployments concentrate in latency-sensitive manufacturing and autonomous vehicle perception systems, whereas Cloud-Based power management remains concentrated in hyperscale facilities with software-defined infrastructure.
- Edge Computing:Distributed AI inference nodes require compact PMICs with rapid transient response to support processor voltage rails. Manufacturing clusters in Guangdong and Baden-Württemberg are deploying edge gateways with integrated power stages.
- Cloud-Based:Centralized data centers leverage PMBus-enabled controllers for remote telemetry and dynamic voltage scaling across thousands of server racks.
- Hybrid:Split architectures partition control loops between local analog regulation and cloud-based optimization for predictive maintenance.
- On-Premises:Enterprise server rooms and private infrastructure maintain traditional analog-dominant power architectures with limited digital telemetry.
Cloud-Based deployment dominates infrastructure spend while Edge Computing climbs the fastest.
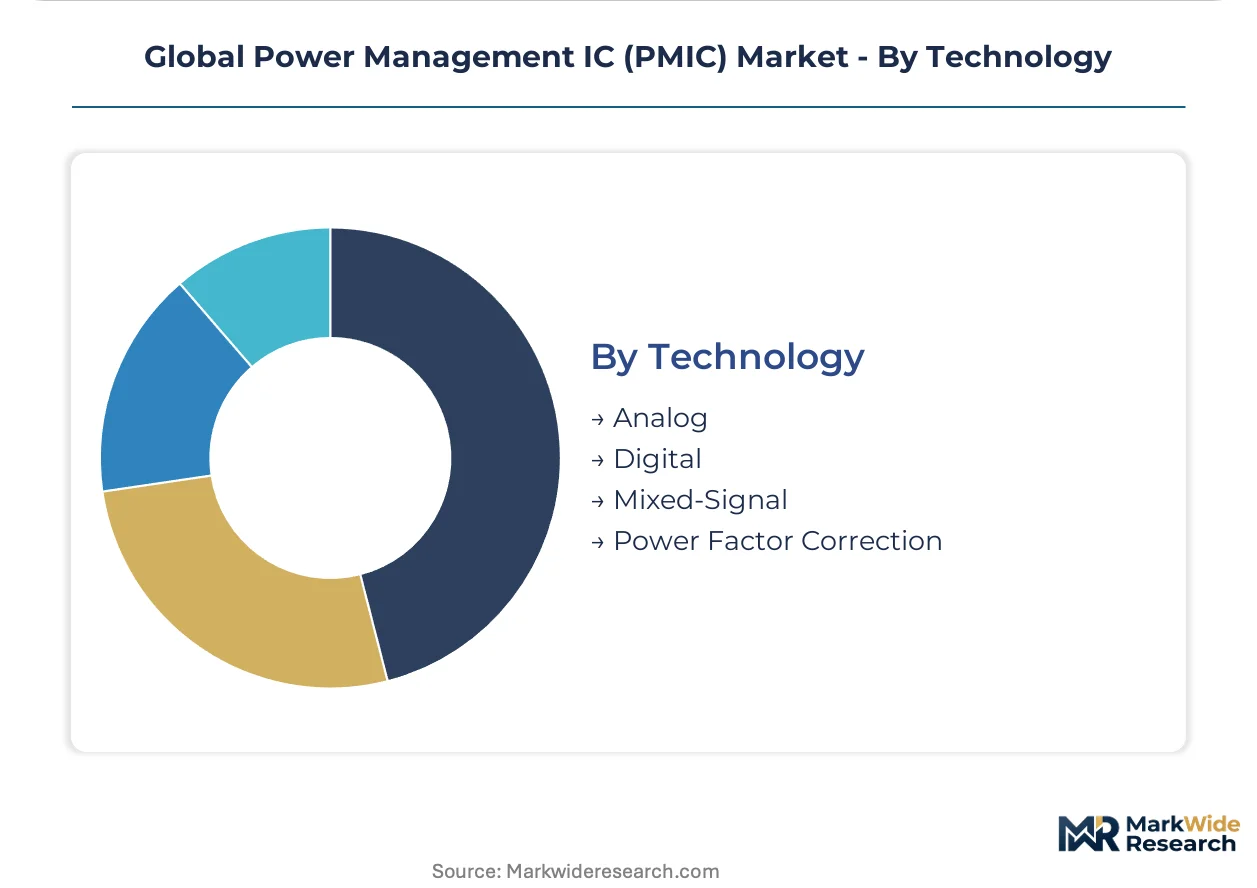
Technology:
Mixed-Signal architectures concentrate design expertise and foundry capacity, creating supply scarcity as analog-digital integration complexity outpaces engineering graduation rates.
- Mixed-Signal:These devices combine precision analog sensing with digital control loops to enable adaptive voltage scaling in AI accelerators and high-performance processors. The EU Green Deal's efficiency mandates are forcing appliance OEMs to adopt digitally compensated regulators with load-profile optimization.
- Digital:Firmware-configurable controllers decompose fixed-analog compensation networks, allowing remote parameter adjustment in server and base station power supplies.
- Analog:Traditional voltage-mode and current-mode controllers persist in cost-sensitive consumer applications with stable load conditions.
- Power Factor Correction:Active bridge and totem-pole topologies satisfy EPA external power supply standards and EU Ecodesign Directive load-profile thresholds.
Mixed-Signal technology anchors supplier margins while Digital controllers expand most quickly in infrastructure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive fabs while Chinese foundries compete on volume terms. Texas Instruments and Infineon Technologies AG command premium tiers through captive 300mm capacity. Domestic Chinese suppliers undercut on cost as BCD process availability expands.
United States
Data center operators in Virginia and Oregon drive multiphase controller demand for AI infrastructure. The EPA enforces external power supply efficiency standards mandating specific load-profile thresholds. Hyperscale facilities in Northern Virginia standardize on PMBus-enabled architectures with remote telemetry capabilities.
Germany
Bavarian automotive OEMs procure high-voltage battery management ICs for 800V electric drivetrains. The EU Green Deal's Ecodesign Directive tightens standby power limits below 0.5W for appliances. Industrial clusters in Baden-Württemberg anchor motor-drive PMIC demand for factory automation systems.
China
Domestic EV manufacturers accelerate PMIC procurement for onboard charging and cell balancing functions. The Ministry of Industry and Information Technology enforces GB standards on standby power consumption for appliances. Shenzhen and Shanghai foundries expand 200mm and 300mm BCD capacity to serve local telecom equipment makers.
Japan
Consumer electronics OEMs demand iterative PMIC redesigns for smartphone and wearable applications. METI's Top Runner program continuously ratchets efficiency benchmarks for domestic appliances. Manufacturing clusters in the Kansai region specialize in precision voltage references for industrial automation.
India
Domestic mobile and appliance manufacturing creates demand for locally sourced PMICs with BIS certification. The Production Linked Incentive scheme incentivizes electronics manufacturing in mobile and white goods segments. Tamil Nadu and Karnataka industrial corridors attract PMIC suppliers seeking tariff-advantaged production bases.
Global Power Management IC (PMIC) Market Competitive Environment
Concentration sits with integrated device manufacturers possessing captive BCD fabrication capacity. Texas Instruments and Infineon Technologies AG anchor the premium tier through proprietary process technologies spanning sub-micron to advanced GaN integration. Fabless suppliers compete on design agility but face allocation vulnerability during wafer shortages. Strategic moves center on multi-year wafer supply agreements and direct material sourcing that bypasses traditional distribution channels.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics NV exemplify the captive-fab archetype with 300mm networks across Germany, Austria, and France. Texas Instruments Inc. anchors the broad-catalog specialist tier with proprietary BCD processes. These three occupy positions defined by process technology ownership rather than pure design services, creating tiered competitive dynamics where fabrication access determines margin capture.
| Leading Market Players |
|---|
| STMicroelectronics NV |
| ON Semiconductor Corp. |
| Texas Instruments Inc. |
| Microchip Technology Inc. |
| Renesas Electronics Corp. |
| Analog Devices, Inc. |
| NXP Semiconductors NV |
| ROHM Co., Ltd. |
| Infineon Technologies AG |
| Others |
Value Chain & Pricing Dynamics
GaN-on-Si integration is displacing silicon MOSFET-plus-driver combinations, simultaneously shifting wafer procurement geography toward Taiwan and China while compressing power stage pricing economics for data center and telecom rectifier applications. This substitution dynamic concentrates foundry negotiations in East Asian BCD capacity while forcing legacy silicon suppliers into defensive pricing postures.
Pricing Analysis
The customization-premium spread between configured-to-order automotive PMICs and standard consumer-grade SKUs spans three-tier pricing structure across premium, standard, and economy levels. Automotive-grade AEC-Q100 qualification and functional safety certification anchor the premium tier, while smartphone PMICs compete on die-size minimization with minimal service bundling. Price differentiation rests on captive fab ownership versus fabless design agility, with margins tightening for non-integrated suppliers exposed to 300mm BCD wafer allocation cuts. Consumer Electronics buyers exhibit highest price sensitivity, whereas Automotive OEMs prioritize supply assurance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Taiwan and South Korea to German automotive clusters have intensified scrutiny of regional BCD foundry alternatives, with port congestion at Rotterdam and Hamburg amplifying lead time uncertainty. Geographic supply concentrates in Taiwan, China, and Germany, with raw material dependencies on gallium, indium, and copper refining concentrated in Chinese operations. Single-source vulnerability in rare earth magnetics for packaging exposes the supply chain to export restriction risk. Distribution runs through direct wafer supply agreements that bypass traditional semiconductor distributors for high-volume automotive and smartphone programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PMIC platform economics are inflecting toward software-defined power management, with PMBus-enabled telemetry creating interoperability ecosystems that lock in hyperscale data center procurement relationships.
For Market Incumbents: Fortify captive 300mm BCD capacity positions in Germany and Austria against fabless competitors facing allocation vulnerability. Prioritize backward integration into gallium and indium refining partnerships to offset Chinese supply concentration. Deepen firmware-configurable control loop R&D to defend against GaN discrete substitution in telecom rectifiers.
For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors for BIS-certified PMIC production serving domestic mobile and appliance manufacturing. Target edge computing voltage rail controllers for AI inference nodes in Guangdong manufacturing clusters. Pursue engineering service contracts with Japanese consumer electronics OEMs facing METI Top Runner redesign cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward mixed-signal analog design boutiques possessing BCD process expertise combining precision voltage references with high-voltage lateral DMOS transistors. Long-term viability hinges on automotive qualification track records and multi-year wafer supply agreements with Taiwanese foundries. Monitor AEC-Q100 validation timeline compression as inflection indicator for automotive PMIC margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Wafer Supply Agreement | Secures 300mm BCD allocation from TSMC or GlobalFoundries for automotive PMIC programs. |
| GaN-on-Si Process Integration | Enables 800V electric drivetrain power stages with higher switching frequency than silicon MOSFETs. |
| PMBus Platform Certification | Unlocks hyperscale data center procurement standards in Northern Virginia and Oregon facilities. |
| India PLI Manufacturing Footprint | Qualifies for BIS certification and tariff advantages in mobile and white goods segments. |
| Automotive Functional Safety Investment | Builds ISO 26262 competency for battery management ICs in 800V architectures. |
Study Parameters
Cross-validation between primary interviews with PMIC design engineers and secondary foundry capacity disclosures anchors the qualitative findings. Semiconductor procurement leads at Tier 1 automotive suppliers, BCD process technologists at integrated device manufacturers, power electronics architects at hyperscale operators, and regulatory compliance officers at appliance OEMs provided operational perspective. SEC 10-K filings, MIIT GB standard publications, EU Ecodesign Directive regulatory texts, and TSMC/GF capacity announcements furnished secondary validation. Bottom-up segment sizing triangulates against top-down semiconductor industry association aggregates.
Sensitivity analysis around BCD wafer allocation scenarios and GaN adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions span voltage conversion topology, end-use thermal requirements, control loop implementation, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and electrification content-per-vehicle trajectories. Forecast inputs incorporate EPA external power supply efficiency mandate compliance deadlines and EU Green Deal standby power threshold ratcheting.
Underlying assumptions cover BCD foundry capacity expansion timelines and automotive electrification penetration curves, with deviation risk concentrated in rare earth export restrictions and AEC-Q100 qualification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Bluetooth IC Market