
 Monolithic Microwave IC (MMIC) Market | 2026-2036
Monolithic Microwave IC (MMIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Monolithic Microwave IC (MMIC) Market Foresight
Market Context with Strategic Players
Defense electronics procurement is decoupling from commercial wireless infrastructure cycles as military radar modernization programs expand across NATO and Indo-Pacific arsenals. Qorvo, Inc. leverages captive GaN foundry capacity in Texas to anchor Pentagon supply chains for active electronically scanned arrays. Analog Devices, Inc. sustains dual-use product architectures that span electronic warfare receivers and 5G massive MIMO base stations. Infineon Technologies AG dominates automotive radar MMIC supply through its 77 GHz silicon-germanium platform, securing design wins with German and Chinese OEMs.
Technical Definition and Structural Segments
A Monolithic Microwave Integrated Circuit integrates active and passive microwave components—transistors, transmission lines, couplers, and bias networks—onto a single semiconductor die, typically operating between 300 MHz and 300 GHz for signal generation, amplification, or frequency translation. GaN-on-SiC technology now delivers power densities exceeding ten watts per millimeter at millimeter-wave frequencies, enabling compact solid-state radar transmitters that previously required vacuum tube devices. Power Amplifiers command the largest revenue pool within product type segmentation due to thermal management complexity and defense qualification premiums, while Frequency Converters accelerate fastest as direct-conversion architectures displace superheterodyne chains in software-defined radios. GaAs retains volume leadership in established satellite payloads and legacy military platforms, though GaN is displacing it in new radar and electronic warfare programs where efficiency and bandwidth dictate selection.
Regulatory Frame and Forward-Looking Close
The U.S. Department of Commerce export controls on advanced compound semiconductor manufacturing equipment constrain foundry expansion in China, while EU REACH chemical restrictions and RoHS substance limits govern material composition for European-qualified MMICs. Japan's METI coordinates national GaN supply chain investments through public-private partnerships targeting 6G base station and radar applications. Stakeholders must monitor foundry qualification timelines against evolving multilateral semiconductor equipment controls, as process node access determines which technology tiers remain commercially viable for cross-border defense and telecommunications contracts.
Market Dynamics
GaN-on-SiC substrate transitions are compressing foundry qualification timelines as defense primes demand higher power density for phased-array radar systems, forcing compound semiconductor fabs to requalify processes under stricter thermal and reliability protocols.
Growth Catalysts
- Phased-array radar modernization:NATO and Indo-Pacific arsenals are replacing mechanically steered antennas with active electronically scanned arrays, creating sustained demand for high-frequency power amplifiers and low-noise amplifiers.
- EU RoHS material compliance:European restrictions on hazardous substances in electronics are accelerating lead-free and halogen-free MMIC packaging qualifications, opening premium supply tiers for compliant foundries.
- 6G terahertz research:Government-funded programs in Japan and Germany are pushing millimeter-wave and sub-terahertz frequencies for next-generation wireless, expanding addressable frequency bands beyond current 5G infrastructure.
Market Restraints
- GaN substrate cost volatility:Silicon carbide wafer prices fluctuate with electric vehicle power electronics demand, squeezing MMIC foundry margins during automotive procurement surges.
- US export controls on deposition equipment:Department of Commerce restrictions on metal-organic chemical vapor deposition systems constrain GaN capacity expansion in China, fragmenting global supply availability.
- GaAs performance ceiling:Gallium arsenide's lower power density and thermal limits prevent its use in next-generation radar transmitters above 100 watts, locking it into legacy satellite and defense maintenance programs.
Strategic Opportunities
- Automotive radar sensor proliferation:German and Chinese OEMs are integrating 4D imaging radar at 77-81 GHz for autonomous driving, creating volume demand for silicon-germanium and CMOS-based MMICs outside defense.
- Japan METI GaN consortium funding:Public-private partnerships targeting domestic 6G base station supply chains offer subsidized foundry access for qualified MMIC developers.
- Direct-conversion architecture adoption:Software-defined radio platforms are eliminating intermediate frequency stages, expanding frequency converter MMIC demand for military and satellite communications.
Industry Challenges
- Compound semiconductor process engineer scarcity:GaN and GaAs fabrication expertise concentrates at a handful of US and European fabs, creating recruitment bottlenecks for capacity expansion.
- Defense qualification timeline compression:MIL-PRF-38534 Class K certification cycles extend 18-24 months, misaligning with rapid radar program schedules and forcing parallel development tracks.
Report Scope
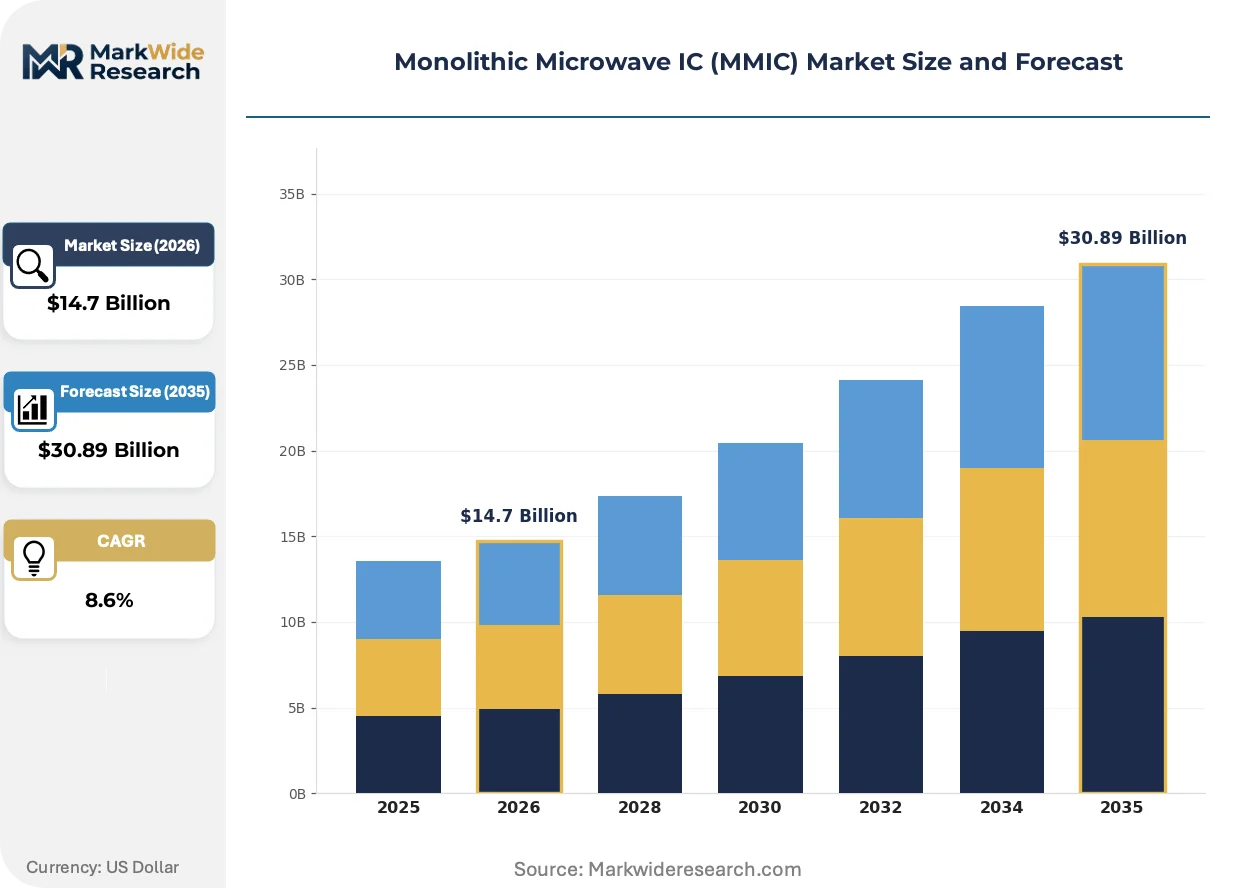
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monolithic Microwave IC (MMIC) Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Amplifiers, Low Noise Amplifiers, Frequency Converters, Attenuators Application: Wireless Communications, Satellite Communications, Radar Systems, Test Equipment Technology: GaAs, GaN, BiCMOS, CMOS End User: Aerospace, Telecommunications, Automotive, Industrial |
| Companies Covered | Infineon Technologies AG, Analog Devices, Inc., Qorvo, Inc., Texas Instruments Incorporated, Mini-Circuits, Inc., MACOM, Skyworks Solutions, Inc., United Monolithic Semiconductors, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monolithic Microwave IC (MMIC) Market Shifts & Advancements
Material science breakthroughs and sovereign supply chain policies are converging to redefine competitive advantage in compound semiconductor fabrication, with thermal performance and export compliance emerging as decisive selection criteria.
GaN-on-SiC technology is consolidating power amplifier architectures across radar and electronic warfare platforms. Pentagon primes are mandating solid-state transmitters for new programs, abandoning traveling wave tubes. This consolidation is compressing supplier tiers to foundries with captive GaN capacity and ITAR clearance.
REACH chemical restrictions and RoHS substance limits are forcing reformulation of MMIC metallization and die-attach materials. European defense contractors now require full material disclosure for phased-array contracts. GaN suppliers with pre-qualified green material stacks are capturing German and French radar program awards ahead of competitors.
Defense procurement offices are bundling long-term sustainment contracts with initial MMIC deliveries, shifting risk to suppliers. Primes in the United States and United Kingdom now demand 15-20 year obsolescence guarantees for radar transceiver modules. This contractual evolution favors vertically integrated manufacturers with in-house packaging and test capabilities over fabless designers.
Monolithic Microwave IC (MMIC) Market Segmentation
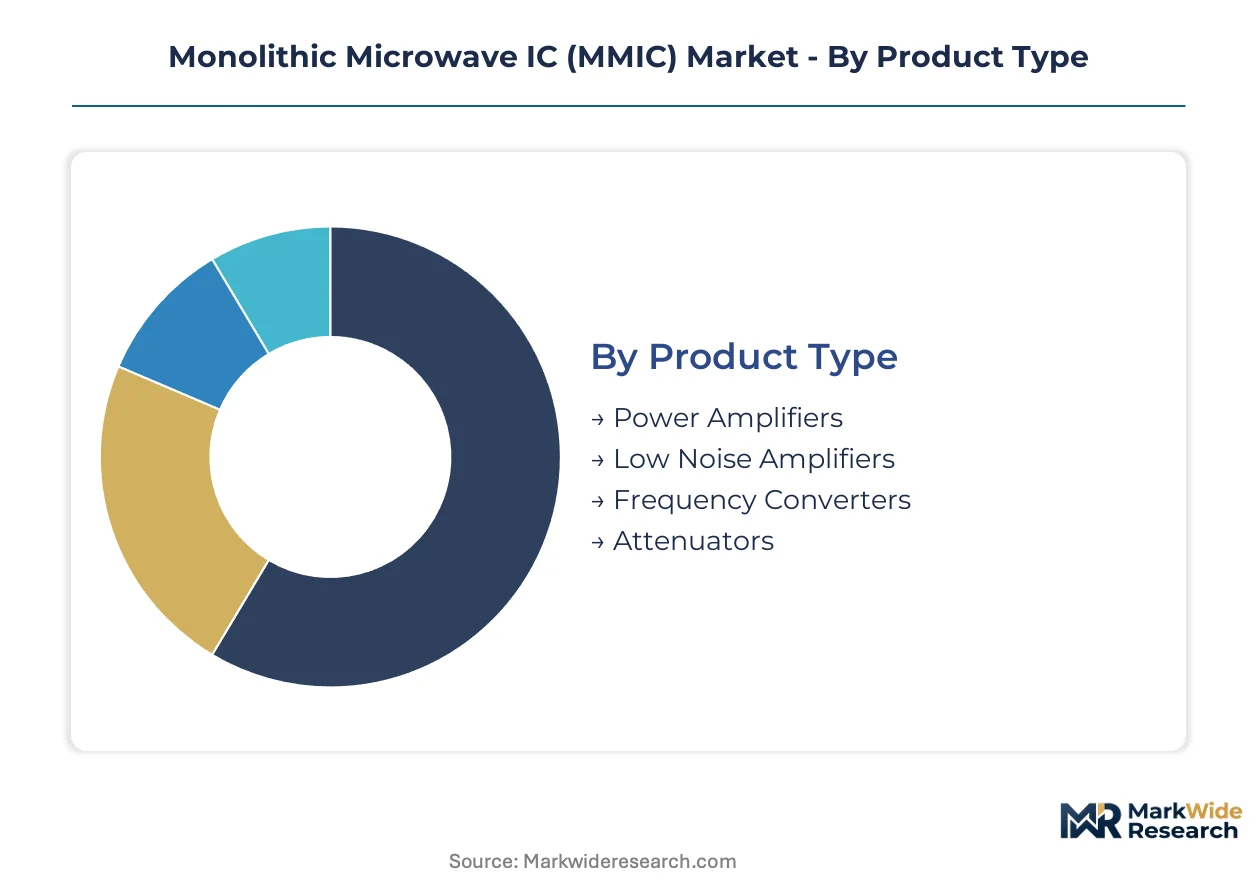
MMIC procurement patterns fragment sharply across defense, automotive, and telecommunications verticals, with substrate technology and thermal specifications acting as the primary sorting mechanisms for supplier qualification. Foundry capacity allocation now follows end-user certification tiers rather than volume economics alone.
Product Type:
Supply concentration clusters around thermal management complexity, with defense primes reserving captive foundry slots for the most demanding amplification stages.
- Power Amplifiers:These devices integrate heterojunction bipolar transistors or high-electron-mobility transistors to deliver output power exceeding ten watts at millimeter-wave frequencies. Pentagon phased-array programs in the United States absorb the bulk of GaN-based power amplifier output, with Lockheed Martin and Raytheon securing multi-year foundry allocations from Qorvo's Texas facilities.
- Frequency Converters:Mixer and multiplier circuits enable direct-conversion receiver architectures that eliminate intermediate frequency stages. Japanese 6G research programs through METI are accelerating sub-terahertz frequency converter development for base station applications beyond current 5G infrastructure limits.
- Low Noise Amplifiers:Front-end amplification with noise figures below one decibel at Ka-band frequencies serves satellite payload downlink chains.
- Attenuators:Voltage-variable and digital step attenuators provide dynamic range control in electronic warfare systems.
Today's leader: Power Amplifiers. Tomorrow's challenger: Frequency Converters.
Application:
Cost tier separation emerges clearly between military-qualified and commercial-grade procurement, with qualification premiums creating distinct supply pools.
- Radar Systems:Active electronically scanned arrays demand transmit-receive modules with simultaneous high power and low noise performance. NATO modernization programs across Germany, France, and the United Kingdom are replacing mechanically steered antennas, with each radar platform requiring thousands of MMICs per array face.
- Wireless Communications:5G massive MIMO base stations and emerging 6G research drive volume demand for beamforming front-ends. China's MIIT spectrum allocations for millimeter-wave 5G are concentrating demand for 28 GHz and 39 GHz power amplifiers among domestic OEMs.
- Satellite Communications:Geostationary and low-earth-orbit payloads require radiation-hardened components with fifteen-year operational lifespans.
- Test Equipment:Vector network analyzers and signal generators need broadband MMICs with calibrated amplitude and phase response.
Defense qualification barriers protect Radar Systems margins, while Wireless Communications offers volume scale for cost curve advancement.
Technology:
Volume distribution reflects maturity curves, with established processes serving maintenance markets and emerging substrates capturing new design wins.
- GaN:Gallium nitride on silicon carbide delivers power densities exceeding ten watts per millimeter with breakdown voltages above one hundred volts. United States Department of Commerce export controls on metal-organic chemical vapor deposition equipment are constraining GaN capacity expansion in China, fragmenting global supply availability.
- GaAs:Gallium arsenide pseudomorphic high-electron-mobility transistors dominate legacy satellite payloads and established military platforms where design requalification costs exceed performance gains from substrate migration.
- BiCMOS:Bipolar-CMOS integration suits automotive radar at 77 GHz with moderate power requirements.
- CMOS:Silicon CMOS enables lowest-cost solutions for consumer wireless applications below six gigahertz.
GaN commands new program awards; GaAs retains installed base service contracts.
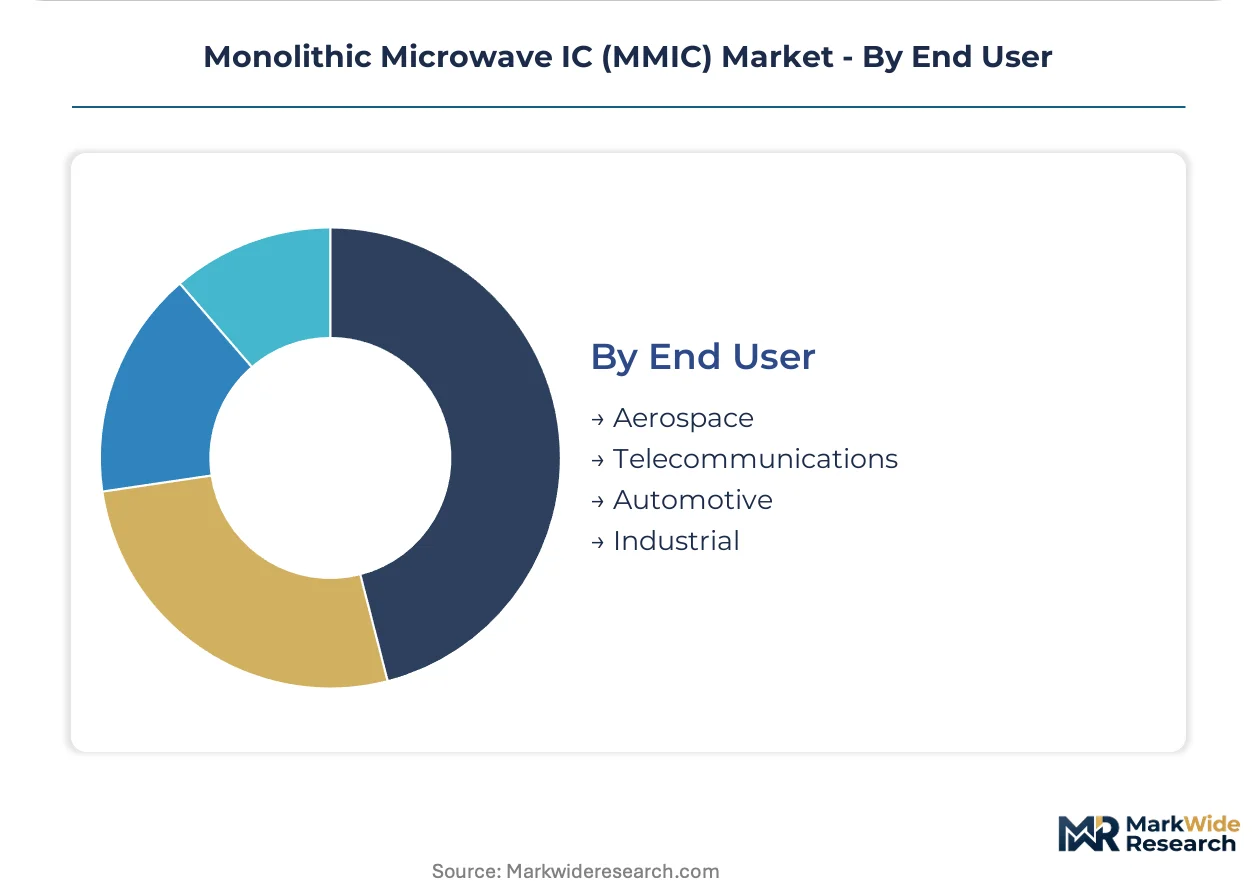
End User:
Customer type determines packaging standards and reliability screening intensity, with aerospace and automotive representing opposite poles of the qualification spectrum.
- Aerospace:Military and space platforms require MIL-PRF-38534 Class K certification with burn-in screening and radiation tolerance verification. United Kingdom defense procurement offices now bundle twenty-year obsolescence guarantees with initial MMIC deliveries for radar transceiver modules.
- Automotive:German OEMs including BMW and Mercedes-Benz are integrating 4D imaging radar at 77-81 GHz for autonomous driving functions, creating volume demand for silicon-germanium MMICs qualified to AEC-Q100 standards.
- Telecommunications:Base station OEMs prioritize cost optimization and supply security over extreme environmental tolerance.
- Industrial:Test and measurement equipment requires broadband performance with calibration traceability.
Aerospace sustains premium pricing; Automotive offers path to volume manufacturing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping where compound semiconductor fabrication concentrates, as defense qualification requirements and export control regimes create divergent cost-of-compliance tiers across sovereign jurisdictions.
United States
Pentagon phased-array radar programs and ITAR-certified foundry capacity anchor domestic demand. Department of Commerce export controls on metal-organic chemical vapor deposition equipment restrict technology transfer to adversarial supply chains. Texas hosts captive gallium nitride fabrication facilities serving Lockheed Martin and Raytheon multi-year procurement contracts.
China
MIIT spectrum allocations for millimeter-wave 5G infrastructure concentrate demand for 28 GHz and 39 GHz power amplifiers among domestic OEMs. SAMR antitrust reviews and dual carbon goals constrain foreign joint venture structures in compound semiconductor manufacturing. Yangtze River Delta clusters in Shanghai and Suzhou pursue indigenous GaN-on-SiC process development despite equipment access limitations.
Germany
Automotive radar integration at 77-81 GHz for autonomous driving functions drives silicon-germanium MMIC procurement from BMW and Mercedes-Benz. EU REACH chemical restrictions and RoHS substance limits govern material composition for defense-qualified components. Bavaria's semiconductor corridor around Munich hosts Infineon Technologies packaging and test operations.
Japan
METI coordinates public-private GaN consortium funding targeting 6G base station and radar applications through 2030. JIS standards and PMDA quality frameworks shape reliability requirements for satellite payload components. Kanto region research institutes in Tsukuba advance sub-terahertz frequency converter development for next-generation wireless.
United Kingdom
Defense procurement offices bundle twenty-year obsolescence guarantees with radar transceiver module contracts, shifting sustainment risk to suppliers. UK Strategic Command prioritizes sovereign compound semiconductor capacity for electronic warfare platforms. South Wales compound semiconductor cluster near Cardiff supplies foundry services for aerospace-qualified MMICs.
Monolithic Microwave IC (MMIC) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-qualified foundries commanding premium positioning against automotive-volume players. The supplier base organizes around three tiers: vertically integrated compound semiconductor fabs with captive GaN capacity, fabless designers dependent on external foundry allocation, and silicon-based CMOS/BiCMOS specialists serving cost-sensitive consumer applications. Dominant competitive moves include backward integration into substrate supply and strategic partnerships for ITAR-cleared packaging capacity.
Among defense-anchored fabricators, Qorvo, Inc. and Analog Devices, Inc. occupy positions within the premium-tier foundry segment, while Infineon Technologies AG exemplifies the automotive-specialist archetype with volume manufacturing scale. These three entities represent distinct strategic postures: captive gallium nitride capacity for Pentagon supply chains, dual-use product architectures spanning military and telecommunications, and silicon-germanium dominance in radar sensor integration for German and Chinese OEMs.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Analog Devices, Inc. |
| Qorvo, Inc. |
| Texas Instruments Incorporated |
| Mini-Circuits, Inc. |
| MACOM |
| Skyworks Solutions, Inc. |
| United Monolithic Semiconductors |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Compound semiconductor process engineers concentrated in Texas and Bavaria create labor-cost differentials that widen spreads between defense-qualified premium tiers and commercial-grade economy offerings. Foundries with captive GaN expertise command pricing power while fabless designers absorb margin compression from external allocation fees.
Pricing Analysis
Distributor margins on ITAR-cleared components run 15-25 points above standard commercial parts, with direct-to-OEM contracts for Pentagon radar programs securing volume discounts unavailable through channel partners. Three-tier pricing structure across defense-certified, automotive-qualified, and consumer-grade levels reflects certification investment recovery timelines. Pricing pressure stems from silicon carbide wafer cost volatility tied to electric vehicle demand surges. Automotive OEMs exhibit highest price sensitivity, while aerospace primes prioritize supply security over unit cost.
Supply Chain Analysis
Returns and refurbishment flows for legacy GaAs satellite components create secondary supply channels that moderate pricing for maintenance programs. Substrate supply concentrates in the United States, Japan, and Germany, with metal-organic chemical vapor deposition equipment drawing from American and Japanese toolmakers. Single-source vulnerability pervades qualified packaging houses with ITAR clearance. Distribution runs through defense primes holding multi-year foundry allocations rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on substrate cost normalization and defense bundling of long-term sustainment contracts that capture lifetime value.
For Market Incumbents: Extend captive GaN foundry capacity through equipment procurement ahead of export control tightening, locking in Pentagon allocation priority. Deepen backward integration into silicon carbide substrate supply to insulate margins from automotive demand surges. Certification investment in EU RoHS-compliant material stacks protects German and French radar program access against green-tier competitors. For New Entrants and Emerging Players: Tier 2 automotive radar suppliers in China present the most penetrable buyer archetype, with domestic OEMs seeking second-source silicon-germanium MMICs for 4D imaging programs. Foundry-less designers targeting 6G frequency converter development can access subsidized capacity through Japan METI consortium partnerships. Direct technical engagement with platform engineering teams at domestic OEMs bypasses entrenched distribution relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless designers with qualified defense IP but constrained foundry access, presenting asymmetric recovery if equipment restrictions ease. Long-term viability favors vertically integrated compound semiconductor fabs with in-house packaging and test capabilities that satisfy 15-20 year obsolescence guarantees. Watch Department of Commerce deposition equipment licensing decisions as the signal for Chinese capacity expansion trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Foundry Expansion | Qorvo's Texas facilities anchor Pentagon phased-array radar supply chains against export control fragmentation. |
| RoHS-Compliant Material Qualification | Infineon's green metallization stacks capture German OEM automotive radar awards ahead of REACH deadlines. |
| Direct-Conversion Architecture Development | Analog Devices' frequency converter IP eliminates intermediate frequency stages in software-defined radio platforms. |
| Silicon-Germanium Platform Scale-Up | Automotive 77-81 GHz radar integration at BMW and Mercedes-Benz creates volume manufacturing economies. |
| Defense Sustainment Contract Bundling | UK Strategic Command's twenty-year obsolescence guarantees shift lifetime risk to vertically integrated suppliers. |
Research Methodology
Multiple input streams — primary interviews with defense procurement officers, foundry operations directors, and automotive platform engineers; secondary validation through Department of Commerce export control filings, METI consortium disclosures, and SEC 10-K compound semiconductor revenue breakdowns; plus customs data on metal-organic chemical vapor deposition equipment trade flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment data was cross-referenced against panel input from radar system integrators and base station OEMs to model volume trajectories across the projection horizon. Segmentation dimensions included product type, substrate technology, end-user certification tier, and regional defense procurement cluster. CAGRs were derived from fitted growth curves calibrated to sovereign capacity-building announcements and spectrum allocation timelines.
Underlying measurement precision varies by segment; defense-qualified power amplifiers carry tighter precision than emerging 6G frequency converter categories where research-stage volumes remain speculative. Forecasts reflect assumptions regarding equipment access permissions and qualification timeline compression that could shift if multilateral semiconductor controls expand. Practitioners should monitor Department of Commerce entity list updates and EU REACH substance restriction amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market