
 Global Application Specific Automotive Analog IC Market | 2026-2036
Global Application Specific Automotive Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Specific Automotive Analog IC Market Foresight
Buyer consolidation among Tier-1 suppliers is repositioning procurement leverage toward vertically integrated module makers. Infineon Technologies AG dominates high-voltage power management segments through captive fab capacity. Texas Instruments leverages its broad catalog to anchor sensor interface sockets across multiple OEM platforms. NXP Semiconductors specializes in motor control solutions that meet ASIL-D functional safety thresholds.
Application Specific Automotive Analog ICs are precision semiconductor devices that condition, convert, and regulate continuous electrical signals within vehicle subsystems, typically manufactured on BiCMOS or silicon-germanium processes to achieve operating temperatures from minus 40 to 150 degrees Celsius. These components enable real-time control of battery charging, traction motor torque, and LED headlamp intensity in electrified powertrains. Power management ICs command the deepest margin pools as voltage regulator architectures grow more complex with 800-volt architectures. Sensor interface amplifiers represent the fastest-expanding category due to proliferating LiDAR and current-sensing nodes. Data converters occupy a mature but defensible niche where resolution requirements now exceed 16 bits for battery management accuracy.
FDA medical device crossover standards, EPA emissions verification protocols, and EU Green Deal carbon-border adjustments collectively tighten traceability and qualification burdens for automotive analog suppliers. NHTSA cybersecurity guidelines from the United States and China's GB standards for new energy vehicles add compliance layers to silicon design cycles. Stakeholders must monitor how functional safety certification timelines interact with raw wafer allocation constraints as electrification programs accelerate.
Market Dynamics
Automotive analog IC procurement is concentrating around 800-volt electric vehicle architectures that demand precision voltage regulation across wider temperature ranges than legacy 12-volt systems. Tier-1 module makers now specify BiCMOS processes with embedded isolation for traction inverters, forcing foundries to qualify new process nodes under accelerated automotive timelines.
Growth Catalysts
- EU Green Deal carbon-border adjustments:European OEMs must source traceable, low-carbon analog components for battery management systems, creating qualified supplier premiums for certified fabs.
- LiDAR sensor proliferation:Autonomous driving programs in China and Germany are multiplying high-speed analog front-ends for time-of-flight signal conditioning in perception stacks.
- EPA tailpipe rule stringency:United States powertrain electrification mandates are expanding addressable sockets for precision current-sensing amplifiers in motor control modules.
Market Restraints
- 300mm silicon wafer allocation:Foundry capacity for automotive-grade BiCMOS remains concentrated among three merchant suppliers, creating allocation risk during demand surges.
- ASIL-D certification timelines:Functional safety documentation for motor control ICs requires 18-24 month validation cycles that lag behind EV platform launch schedules.
- Silicon-germanium process complexity:High-frequency sensor interfaces demand specialized epitaxy equipment with limited installed base, constraining output scaling.
Strategic Opportunities
- India PLI scheme for automotive electronics:Local assembly incentives are creating greenfield demand for analog IC packaging and test capacity serving domestic EV programs.
- Zone architecture consolidation:Domain controller integration is automating distributed power management, opening sockets for multi-channel PMICs with embedded diagnostics.
- China GB standards for new energy vehicles:Mandatory battery monitoring specifications are mandating domestic certification pathways that favor localized analog design houses.
Industry Challenges
- Automotive analog design talent scarcity:Mixed-signal expertise combining high-voltage ruggedness with precision matching is concentrated among aging specialist cohorts in Germany and Japan.
- Legacy 12-volt system coexistence:Dual-voltage platform architectures are forcing redundant analog validation matrices that compress development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Specific Automotive Analog IC Market |
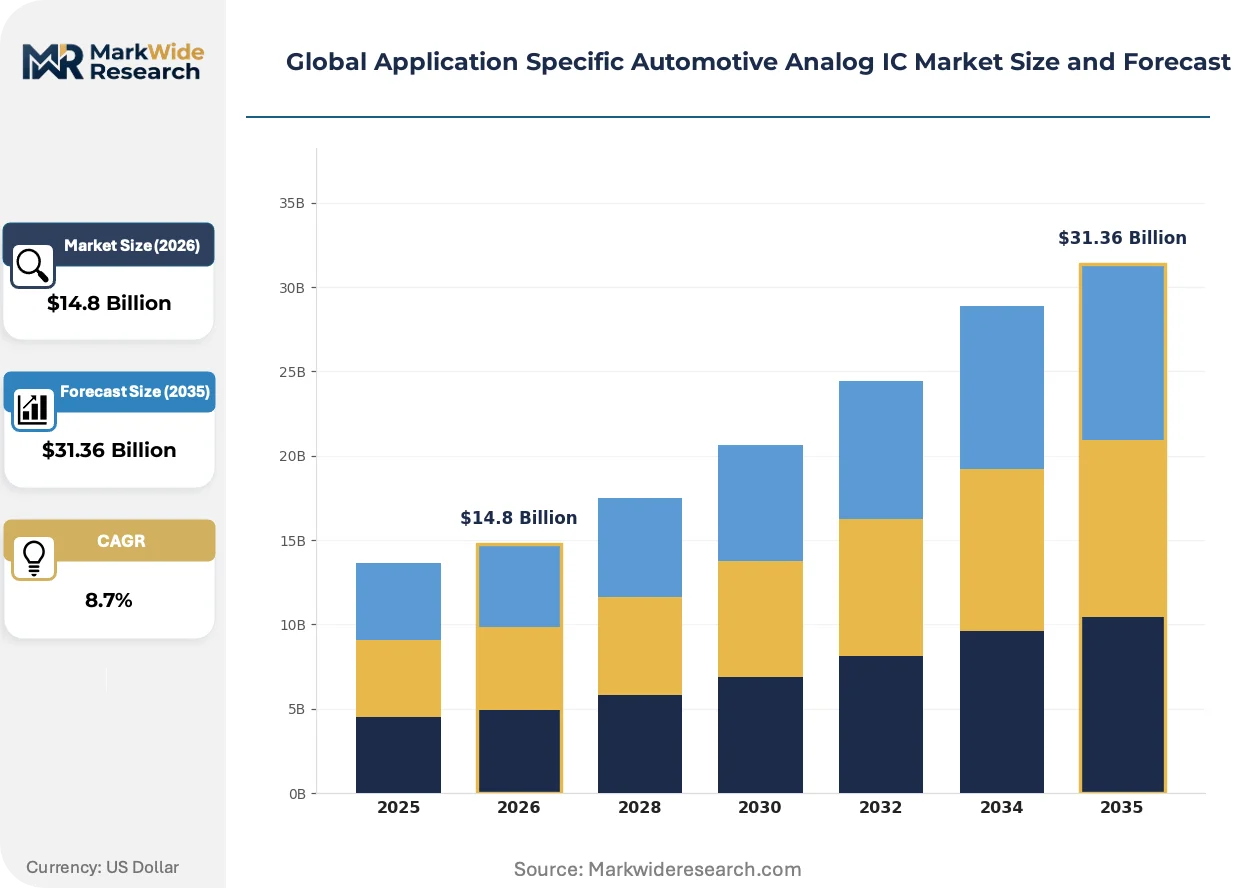
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Management, Sensor Interface, Motor Control, Lighting Control, Audio Systems Product Type: Amplifiers, Voltage Regulators, Analog Switches, Data Converters, Oscillators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Component Manufacturers Technology: CMOS, Bipolar, BiCMOS, Silicon-Germanium, Gallium Arsenide |
| Companies Covered | Microchip Technology, Analog Devices, Infineon Technologies AG, Renesas Electronics, ON Semiconductor, NXP Semiconductors, STMicroelectronics, Qualcomm, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Specific Automotive Analog IC Market Shifts & Advancements
Gallium nitride gate drivers are displacing silicon-based alternatives in traction inverters, while digital calibration engines are embedding into analog signal chains to compensate for process variation. These shifts are compressing the traditional boundary between precision analog and mixed-signal digital control.
Integrated isolated gate drivers with built-in desaturation detection are automating fault protection in 800-volt silicon carbide power stages. European and Chinese inverter manufacturers are adopting these devices at volume production scale. The technology is automating the elimination of discrete protection circuitry that previously occupied significant board area and introduced failure modes.
EPA emissions verification protocols now mandate continuous battery state-of-health monitoring that requires sub-millivolt measurement accuracy across temperature extremes. This regulatory pressure is forcing analog IC architectures toward chopper-stabilized topologies with drift compensation. Power management ICs for United States-market EVs are most affected, with suppliers redesigning reference circuits to meet the new accuracy floors.
Long-term supply agreements with foundries are replacing spot market wafer purchases as OEMs seek allocation certainty for multi-year EV programs. Tier-1 suppliers in Germany and Japan are locking capacity three to four years forward, displacing the quarterly procurement cadence that dominated automotive semiconductors. This behavioral shift is most visible in high-voltage power management categories where sole-source qualification creates switching friction.
Global Application Specific Automotive Analog IC Market Segmentation
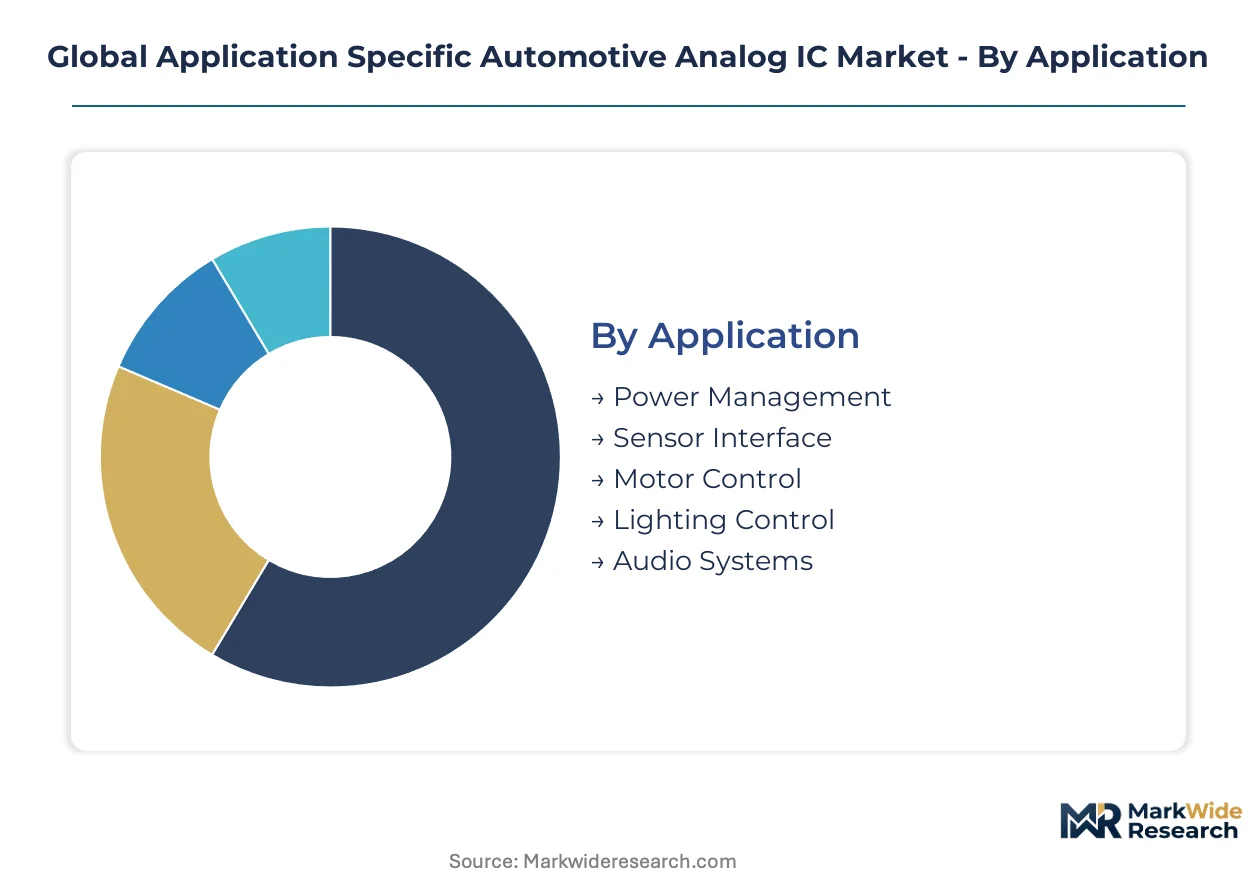
Automotive analog IC procurement patterns diverge sharply across application workloads, with electrification programs reshaping volume concentration toward power-dense categories. Component specifications now cascade across multiple segmentation axes simultaneously, forcing suppliers to qualify identical die across divergent end-user qualification matrices.
Application:
Power Management commands the deepest margin pools while Sensor Interface climbs fastest on LiDAR proliferation, creating a volume-versus-velocity tension across OEM sourcing strategies.
- Power Management:Voltage regulation architectures for 800-volt traction inverters and battery management systems operate across minus 40 to 150 degrees Celsius. German and Chinese OEMs concentrate procurement for these components as their electrified model lineups expand.
- Sensor Interface:High-speed analog front-ends condition time-of-flight signals from LiDAR perception stacks with sub-nanosecond precision. Demand concentrates in autonomous driving programs from Baidu in China and Mercedes-Benz in Germany, where EPA tailpipe stringency accelerates electrification timelines.
- Motor Control:Precision current-sensing circuits meet ASIL-D functional safety thresholds for traction motor torque regulation.
- Lighting Control:LED headlamp intensity modulation requires wide-temperature-range current regulation.
- Audio Systems:Low-noise amplifiers process infotainment signals across divergent vehicle acoustic architectures.
Today's leader: Power Management. Tomorrow's challenger: Sensor Interface.
Product Type:
Voltage Regulators anchor revenue concentration through complexity premiums in high-voltage architectures, while Data Converters defend mature sockets through resolution escalation.
- Voltage Regulators:Multi-phase buck-boost architectures manage load transients across 12-volt to 800-volt platform coexistence. Foundry capacity for automotive-grade BiCMOS processes concentrates among three merchant suppliers, creating allocation risk during demand surges.
- Data Converters:Successive-approximation and delta-sigma architectures now exceed 16-bit resolution for battery cell voltage monitoring. EPA emissions verification protocols mandate continuous state-of-health monitoring with sub-millivolt accuracy, forcing chopper-stabilized topologies with drift compensation in United States-market designs.
- Amplifiers:Instrumentation and operational amplifiers bridge sensor outputs to microcontroller inputs.
- Analog Switches:Multiplexers route signals across shared ADC resources in domain controller architectures.
- Oscillators:Precision timing references synchronize distributed control loops across vehicle networks.
Voltage Regulators capture the steepest margin expansion. Data Converters retain the most defensible incumbent positions.
End User:
Tier-1 Suppliers concentrate procurement leverage through module-level integration, while OEMs pull analog specification authority upward in strategic categories.
- Tier-1 Suppliers:Vertically integrated module makers specify BiCMOS processes with embedded isolation for traction inverters. Long-term supply agreements with foundries now lock capacity three to four years forward, displacing quarterly procurement cadences that previously dominated automotive semiconductors.
- OEMs:Direct analog IC sourcing concentrates in high-voltage power management where sole-source qualification creates switching friction. Germany and Japan anchor this behavior, with Infineon and Renesas capturing captive fab commitments.
- Aftermarket Providers:Replacement component sourcing follows divergent qualification pathways.
- Vehicle Assemblers:Contract manufacturers execute procurement under OEM-directed specifications.
- Component Manufacturers:Sub-tier suppliers fabricate discrete elements for module integration.
Tier-1 Suppliers dominate transaction volume. OEMs control strategic category access.
Technology:
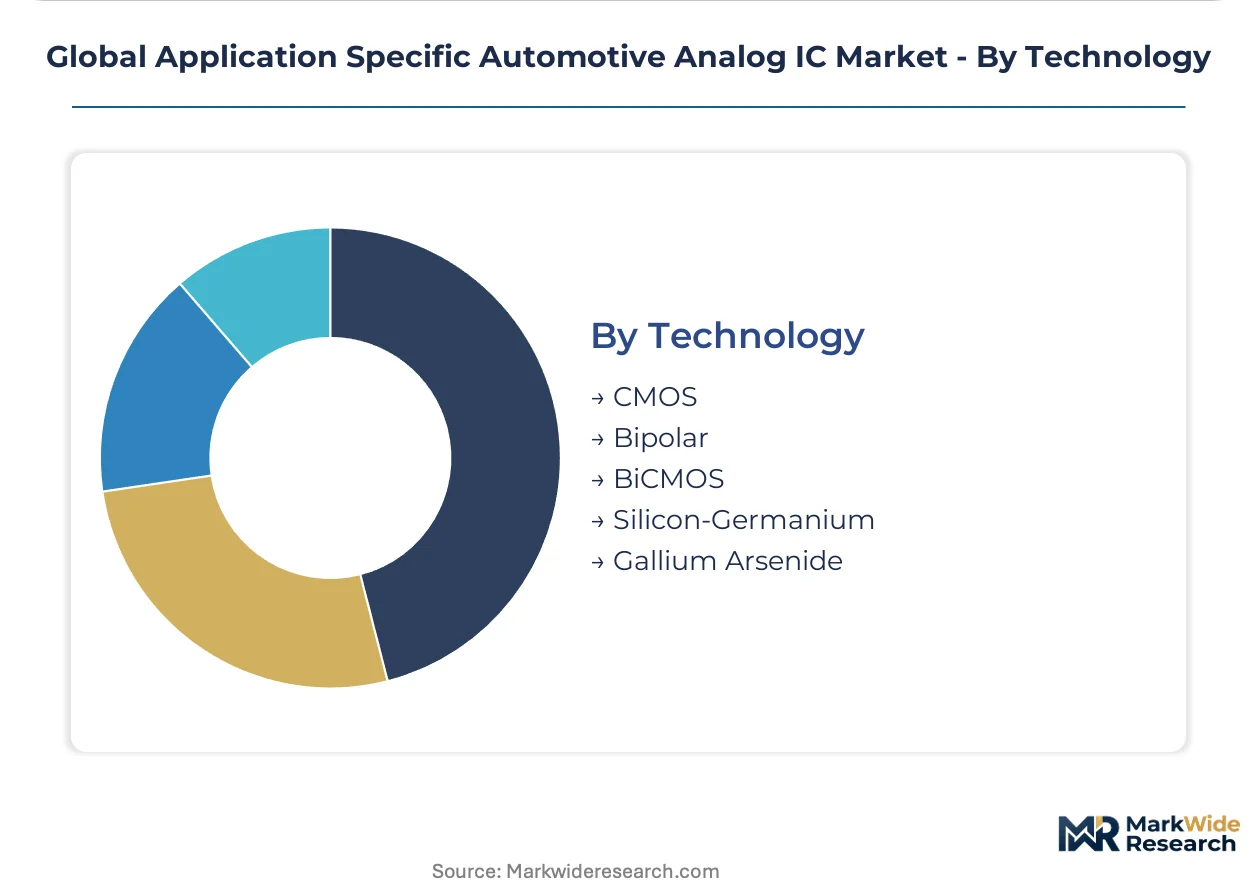
BiCMOS processes balance high-voltage ruggedness with precision matching, while Silicon-Germanium claims frequency-intensive sensor interfaces despite epitaxy equipment constraints.
- BiCMOS:Bipolar-CMOS integration delivers high-current drive with digital calibration engines embedded for process variation compensation. Foundries must qualify new process nodes under accelerated automotive timelines as 800-volt architectures proliferate.
- Silicon-Germanium:Specialized epitaxy enables terahertz-capable transistors for LiDAR analog front-ends. Limited installed base of production equipment constrains output scaling despite autonomous driving program demand from China and Germany.
- CMOS:Pure CMOS dominates cost-sensitive, lower-voltage auxiliary functions.
- Bipolar:Legacy processes persist in linear regulator applications with established reliability records.
- Gallium Arsenide:Specialized RF applications exploit high electron mobility for radar front-ends.
BiCMOS owns the broadest qualification footprint. Silicon-Germanium faces the tightest capacity ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more captive fab capacity for automotive analog ICs than any European peer, while China deploys domestic certification mandates that redirect procurement toward local design houses.
United States
EPA tailpipe rules accelerate powertrain electrification across Detroit and California EV clusters. NHTSA cybersecurity guidelines layer compliance burdens onto silicon design cycles for battery management systems. Austin and Phoenix anchor emerging analog design centers serving domestic OEM electrification programs.
Germany
EU Green Deal carbon-border adjustments mandate traceable, low-carbon components for battery management. KBA vehicle type approval processes intersect with ASIL-D functional safety timelines. Stuttgart and Munich concentrate Tier-1 module procurement leverage through vertically integrated traction inverter specifications.
China
GB standards for new energy vehicles mandate domestic certification pathways for battery monitoring ICs. MIIT industrial policy directs foundry capacity toward automotive-grade BiCMOS processes. Shanghai and Shenzhen clusters localize analog design houses serving BYD and NIO electrification roadmaps.
Japan
METI technology roadmaps prioritize silicon-germanium epitaxy equipment for high-frequency sensor interfaces. JIS automotive electronics standards govern qualification protocols for motor control solutions. Nagoya and Tokyo retain aging specialist cohorts with mixed-signal expertise combining high-voltage ruggedness and precision matching.
India
PLI scheme incentives for automotive electronics create greenfield demand for analog IC packaging and test capacity. CEA power sector regulations intersect with EV charging infrastructure buildouts. Tamil Nadu and Karnataka assemble domestic EV programs requiring localized PMIC sourcing.
Global Application Specific Automotive Analog IC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidated vendor base where three merchant foundries control automotive-grade BiCMOS allocation. The market structures around captive fab ownership, broad catalog breadth, and functional safety certification depth. Dominant competitive moves include long-term supply agreements locking foundry capacity three to four years forward, and strategic partnerships between Tier-1 module makers and qualified analog design houses.
Within the diversified semiconductor tier, Infineon Technologies AG and Texas Instruments exemplify divergent strategic positions. Infineon anchors high-voltage power management segments through captive manufacturing infrastructure. Texas Instruments occupies a catalog-breadth position across sensor interface sockets. STMicroelectronics represents the European-centered archetype with integrated module-level offerings. NXP Semiconductors sits within the functional safety-specialist tier, with Renesas Electronics anchoring Japanese-centered motor control qualifications.
| Leading Market Players |
|---|
| Microchip Technology |
| Analog Devices |
| Infineon Technologies AG |
| Renesas Electronics |
| ON Semiconductor |
| NXP Semiconductors |
| STMicroelectronics |
| Qualcomm |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
Captive fab ownership among German and Japanese conglomerates anchors pricing discipline through in-house BiCMOS capacity, insulating Tier-1 procurement from spot-market volatility while concentrating margin capture upstream. Long-term supply agreements now lock foundry output three to four years forward, compressing quarterly price negotiation leverage for merchant analog suppliers serving 800-volt platform ramps.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for automotive-grade BiCMOS processes, yet three-tier pricing structure across ASIL-D certified, automotive-qualified, and industrial-grade tiers persists. Price differentiation hinges on functional safety certification depth and volume scale commitments from Tier-1 module makers. Cost compression in sensor interface categories is intensifying because silicon-germanium epitaxy equipment constraints limit output scaling. Aftermarket providers exhibit highest price sensitivity; OEM direct sourcing shows lowest, anchored by sole-source qualification friction.
Supply Chain Analysis
Dual-sourcing requirements from German and Chinese OEMs mandate multi-supplier qualification for traction inverter power management ICs, yet merchant foundry capacity concentrates in Taiwan, South Korea, and the United States. Raw material dependencies span 300mm silicon wafers, specialized BiCMOS process chemicals, and high-purity germanium for sensor interfaces. Single-source vulnerability in silicon-germanium epitaxy equipment constrains LiDAR analog front-end scaling. Distribution runs through vertically integrated Tier-1 module makers with captive assembly and test capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through 800-volt architecture complexity premiums, as voltage regulator architectures demand higher-precision BiCMOS processes that resist commoditization. OEM electrification roadmaps concentrate procurement leverage among qualified suppliers with captive fab access.
For Market Incumbents:Cement foundry allocation priority through multi-year supply agreements locking BiCMOS capacity ahead of competitor qualification timelines. Deepen backward integration into silicon-germanium epitaxy equipment to capture LiDAR sensor interface sockets. Defend against emerging Chinese analog design houses by accelerating ASIL-D certification documentation for motor control portfolios.
For New Entrants and Emerging Players:India's PLI scheme for automotive electronics opens a window for greenfield packaging and test capacity serving domestic EV programs. Target sensor interface amplifiers for autonomous driving stacks where silicon-germanium supply constraints create incumbent vulnerability. Pursue joint development agreements with Tier-1 module makers seeking second-source qualification for 800-volt power management.
For Investors and Strategic Acquirers:Valuations sit cheapest among mixed-signal specialists with aging founder-technologist leadership and limited succession planning. Five-to-ten-year viability favors analog design houses with demonstrated GB standards compliance for China's new energy vehicle mandates. Watch MIIT industrial policy directives on domestic foundry capacity allocation as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Foundry Supply Agreement | Locks BiCMOS capacity for German OEM 800-volt platform ramps ahead of allocation crunches. |
| ASIL-D Functional Safety Certification | Opens motor control sockets for traction inverters under KBA and NHTSA compliance timelines. |
| Silicon-Germanium Epitaxy Equipment Investment | Captures LiDAR analog front-end demand from Baidu and Mercedes-Benz autonomous programs. |
| India PLI Scheme Localization | Positions packaging capacity for domestic EV PMIC sourcing under CEA power sector buildouts. |
| GB Standards Compliance Pathway | Enables battery monitoring IC qualification for BYD and NIO electrification roadmaps in China. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each automotive production cluster. The analysis combines structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, foundry operations managers, and aftermarket distribution heads with secondary validation. Sources include vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and MIIT industrial policy directives. Bottom-up segment sizing triangulates against top-down OEM electrification spend forecasts.
Granularity-level modeling disaggregates volume and value across power management, sensor interface, motor control, lighting control, and audio system applications; voltage regulator, data converter, amplifier, analog switch, and oscillator product types; and BiCMOS, silicon-germanium, CMOS, bipolar, and gallium arsenide technology nodes. CAGRs derive from regression analysis of historical content-per-vehicle trajectories mapped to OEM platform launch schedules. Forecast inputs incorporate EPA tailpipe rule stringency, EU Green Deal carbon-border adjustment implementation, and China GB standards compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw wafer allocation constraints or accelerated EV platform cancellations. Deviation in ASIL-D certification timeline compression relative to foundry qualification cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Motor Driver IC Market