
 Box Pouch Market | 2026-2036
Box Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Box Pouch Market Outlook
Pet food packaging is restructuring demand patterns across the Box Pouch Market as premium and subscription-based pet nutrition brands abandon multi-wall paper bags for resealable, shelf-stable formats. Amcor PLC leverages its global film extrusion network to supply high-barrier laminates for this vertical. Mondi Group anchors European demand through kraft-paper-based pouch solutions that target plastic-reduction commitments. ProAmpac LLC specializes in small-batch custom printing for emerging pet food startups seeking rapid turnaround.
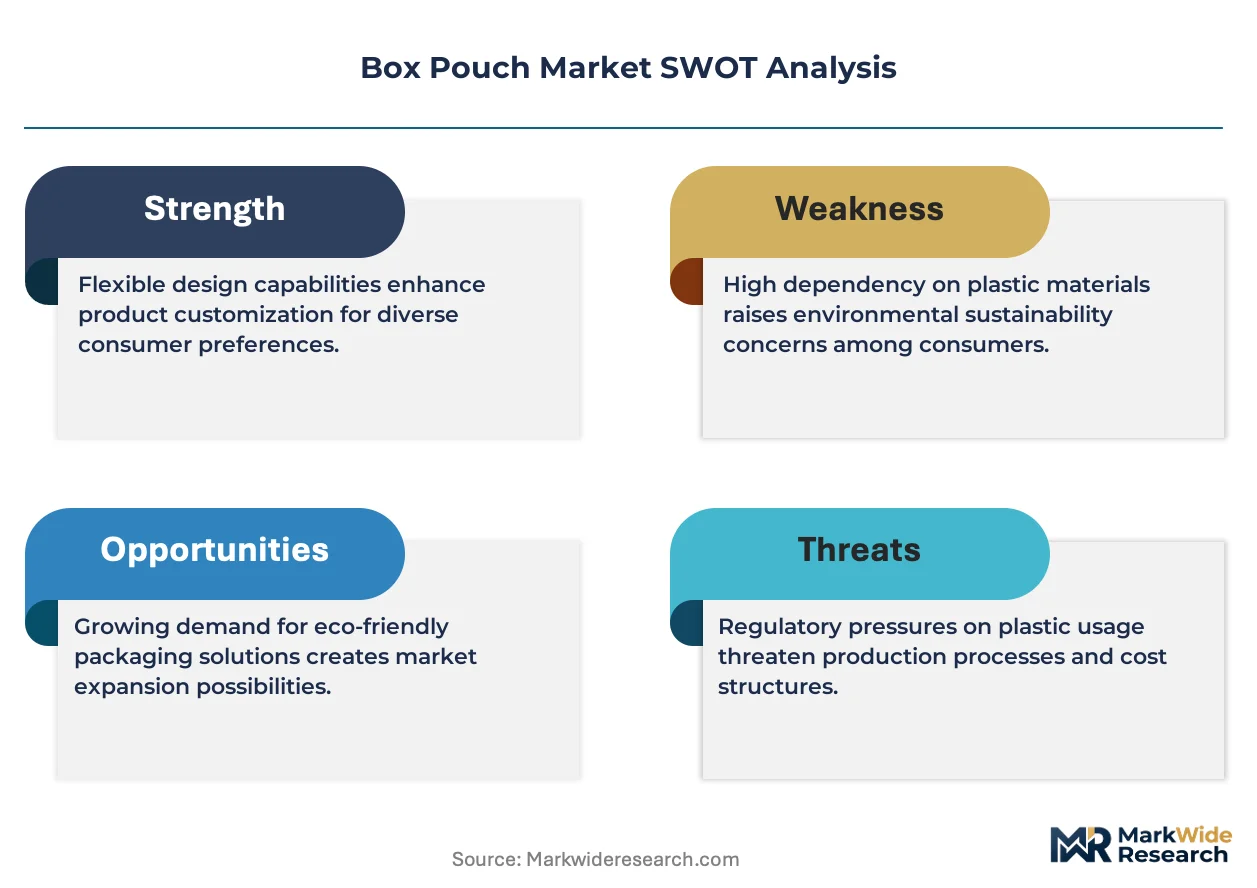
A box pouch is a flat-bottom flexible package with side gussets and a rectangular base that self-stands on retail shelves, typically constructed from multi-layer laminates combining polyethylene terephthalate, polyethylene, and aluminum oxide coatings to achieve oxygen transmission rates below 0.1 cc per square meter per day. The format replaces rigid cans and glass jars in wet pet food, specialty coffee, and powdered supplements where shelf stability and cube efficiency matter. Plastic material types dominate current volume but face margin compression as extended producer responsibility schemes spread across OECD markets. Compostable substrates represent the fastest-growing material category though they currently occupy niche premium positioning due to limited industrial composting infrastructure. Zip lock closures capture disproportionate value share in pet food and household products where resealability drives repeat purchase intent.
The EU Packaging and Packaging Waste Regulation and the US Food and Drug Administration's food contact substance notification program jointly shape material approval pathways and recyclability labeling requirements for box pouch suppliers seeking cross-border market access. REACH compliance in Europe and state-level extended producer responsibility laws in California and Oregon force reformulation of adhesive and ink chemistries. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in warehouses and maintain unified product specifications across manufacturing footprints.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is compressing material choice sets across the value chain, forcing converters to abandon multi-material laminates before recycling infrastructure matures.
Growth Catalysts
- EPR scheme expansion:California and Oregon extended producer responsibility laws create compliance-driven replacement cycles for non-recyclable legacy formats.
- Pet food premiumization:Wet pet food brands abandon metal cans for shelf-stable retort pouches with oxygen barriers below 0.1 cc per square meter per day.
- Aluminum oxide deposition:Thin-film coating technology enables mono-material polyethylene structures that satisfy existing mechanical recycling streams.
Market Restraints
- Resin cost volatility:Ethylene and propylene feedstock swings compress converter margins on fixed-price annual contracts.
- Composting infrastructure gaps:Industrial compostable substrates face limited offtake capacity outside Germany, Austria, and the Netherlands.
- Retort compatibility limits:High-temperature sterilization above 121°C degrades bio-based sealant layers, restricting format adoption in wet pet food.
Strategic Opportunities
- Digital printing integration:HP Indigo and Xeikon systems enable lot sizes below 5,000 units for subscription pet food startups.
- CSRD-aligned reporting:Corporate Sustainability Reporting Directive mandates scope 3 disclosure, creating demand for carbon-labeled packaging.
- Household products pivot:Laundry pods and dishwasher tablets convert from rigid tubs to child-resistant zip-lock pouches.
Industry Challenges
- Adhesive reformulation lag:Solvent-free polyurethane systems require 18-24 month validation cycles against FDA food contact substance notifications.
- Recyclability testing backlog:How2Recycle and OPRL certification queues extend 8-14 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Pouch Market |
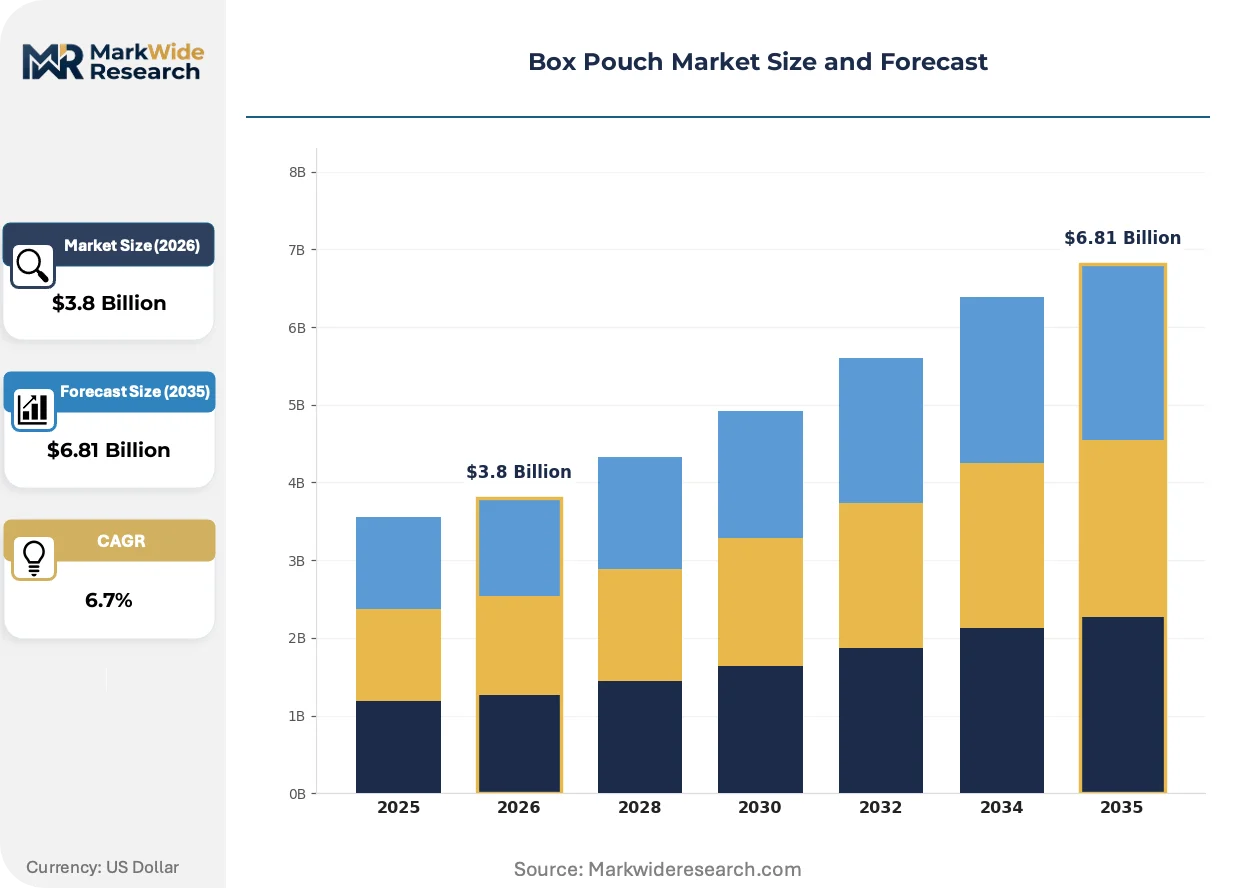
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Aluminum, Compostable Closure Type: Zip Lock, Snap, Heat Seal, Velcro End User: FMCG, Food & Beverage, Personal Care, Household Products Capacity: Small, Medium, Large, Custom Size |
| Companies Covered | Amcor PLC, Mondi Group, ProAmpac LLC, Constantia Flexibles Group GmbH, Sealed Air Corporation, Sonoco Products Company, DS Smith PLC, CDF Corporation, Smurfit Westrock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Pouch Market Strategic Shifts
Material science convergence with digital production methods is collapsing minimum order quantities while regulatory compliance costs are stratifying the supplier base.
Mono-material polyethylene pouch structures with ethylene vinyl alcohol barrier layers is unifying previously incompatible performance requirements. Specialty coffee roasters in Germany and the Netherlands adopt these formats at 40% volume premiums to satisfy retailer recyclability mandates. This unification is compressing the addressable market for aluminum-oxide-coated polyester laminates to premium applications where optical clarity justifies sorting complexity.
REACH substance restriction proposals targeting per- and polyfluoroalkyl substances in food contact materials force immediate reformulation of grease-resistant coatings. European converters face 2025 implementation timelines for PFAS-free alternatives with comparable oil transmission rates. Wet pet food and confectionery segments accelerate testing of silicon dioxide and clay-based barrier coatings to maintain shelf life claims.
Direct-to-subscription fulfillment models displace wholesale club packaging specifications. Pet food brands ship 2.5-kilogram refill pouches through postal networks rather than 15-kilogram bulk formats through distributors. This channel rotation concentrates demand in North American and European urban corridors where last-mile density supports flexible delivery windows.
Box Pouch Market Segmentation
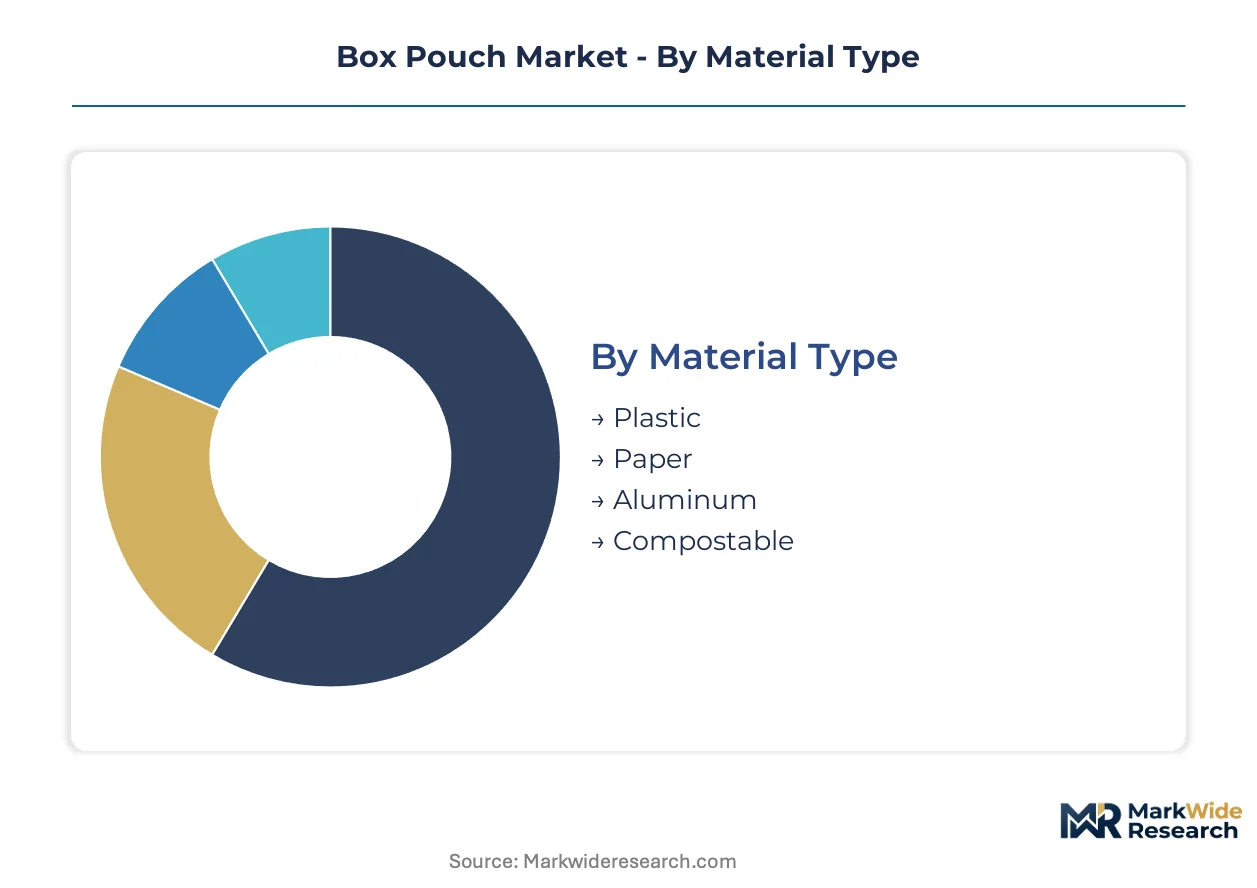
Box pouch format conversion cycles differ sharply by material chemistry and closure mechanism, with regulatory deadlines forcing synchronized upgrades across converter tooling. Segmentation reveals where compliance costs concentrate versus where premium positioning unlocks margin expansion.
Material Type:
Replacement cycles accelerate as extended producer responsibility laws invalidate multi-material laminates before recycling infrastructure matures.
- Plastic:Multi-layer polyethylene terephthalate and polyethylene laminates with aluminum oxide coatings achieve oxygen transmission rates below 0.1 cc per square meter per day. Wet pet food brands in Germany and the Netherlands convert metal can lines to these structures for shelf-stable retort compatibility. Volume placements concentrate in plastic; the faster expansion belongs to compostable.
- Paper:Kraft-paper-based pouch solutions with bio-based barrier coatings target plastic-reduction commitments from European confectionery and coffee roasters. Mondi Group anchors regional supply through integrated pulp-to-pouch operations in Austria and Sweden. REACH substance restrictions on per- and polyfluoroalkyl substances force immediate reformulation of grease-resistant coatings.
- Aluminum:Foil-containing laminates retain niche positioning in pharmaceutical and high-fat food applications where complete oxygen and light exclusion is mandatory.
- Compostable:Industrial compostable substrates face limited offtake capacity outside Germany, Austria, and the Netherlands.
Converters with integrated film extrusion capabilities capture margin from plastic volume; specialty paper and compostable lines command 40% premiums where retailer mandates apply.
Closure Type:
Resealability specifications diverge by channel format, with postal fulfillment networks demanding puncture-resistant mechanisms that wholesale club distribution never required.
- Zip Lock:Child-resistant zip-lock mechanisms capture disproportionate value share in pet food and household products where resealability drives repeat purchase intent. ProAmpac LLC specializes in small-batch custom printing for emerging pet food startups seeking rapid turnaround with these closures.
- Snap:Audible closure confirmation suits pharmaceutical and supplement applications where dosing integrity requires user feedback.
- Heat Seal:Permanent hermetic seals dominate single-serve coffee and portion-controlled confectionery where reclosure is unnecessary.
- Velcro:Hook-and-loop systems appear in reusable bulk refill formats for laundry pods and dishwasher tablets converting from rigid tubs.
Zip lock placements dominate premium pet food; snap closures gain fastest in pharmaceutical compliance packaging.
End User:
Channel rotation toward direct-to-subscription fulfillment collapses minimum order quantities and fragments specifications across customer types.
- FMCG:Fast-moving consumer goods brands deploy box pouches for cube efficiency in retail distribution, replacing rigid glass and metal where shelf stability permits. Amcor PLC leverages its global film extrusion network to supply high-barrier laminates for multinational FMCG accounts.
- Food & Beverage:Specialty coffee roasters in Germany adopt mono-material polyethylene structures at volume premiums to satisfy retailer recyclability mandates. Wet pet food accelerates format conversion from traditional rigid containers.
- Personal Care:Powdered supplements and cosmeceuticals adopt oxygen-barrier pouches for shelf stability and portability.
- Household Products:Laundry pods and dishwasher tablets convert from rigid tubs to child-resistant zip-lock pouches for postal fulfillment density.
FMCG commands current volume concentration; household products post the steepest expansion trajectory as postal networks displace wholesale clubs.
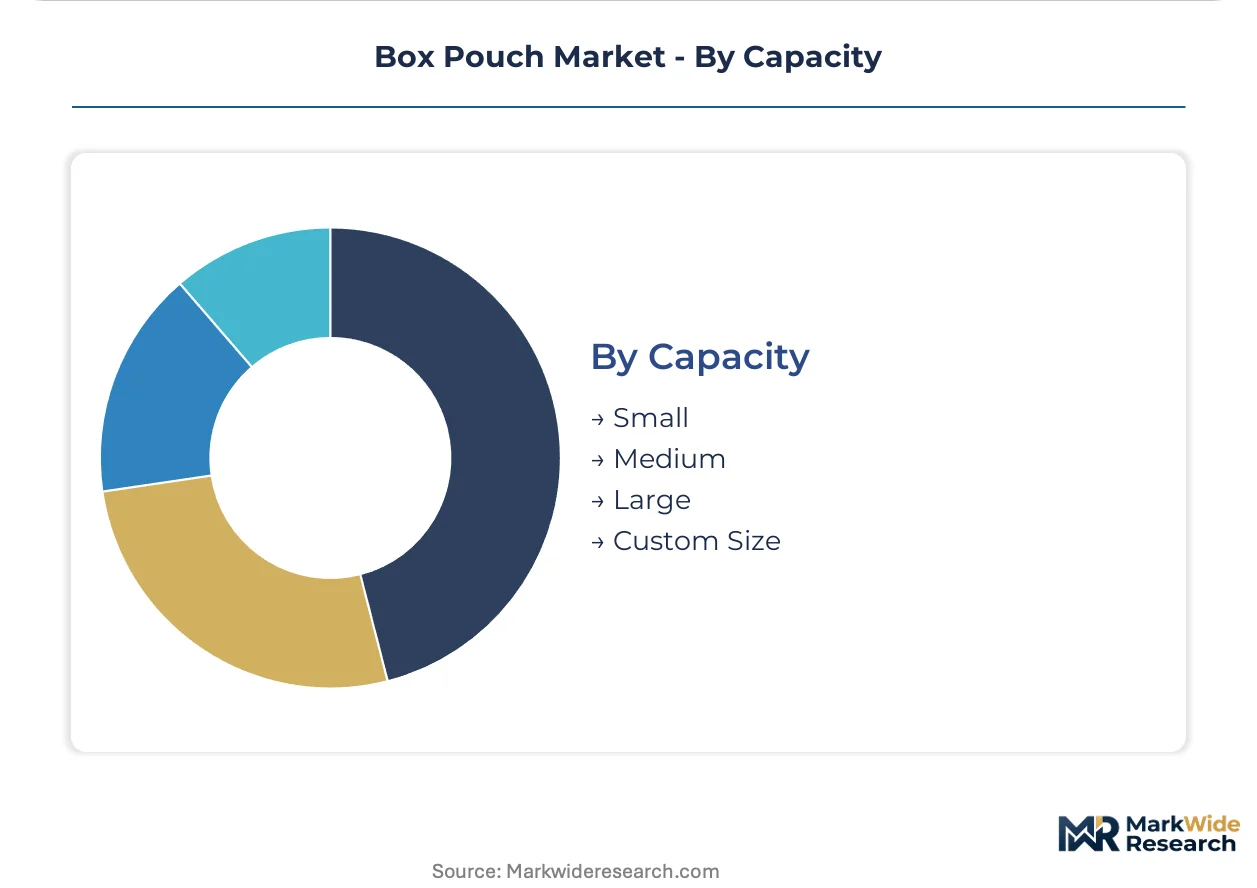
Capacity:
Direct-to-subscription fulfillment models concentrate demand in mid-size formats that balance postal dimensional weight with consumption velocity.
- Small:Single-serve and sample formats below 250 grams serve specialty coffee and supplement subscription trials. HP Indigo and Xeikon digital printing systems enable lot sizes below 5,000 units for these applications.
- Medium:2.5-kilogram refill pouches dominate pet food subscription shipments through North American and European urban corridors where last-mile density supports flexible delivery windows.
- Large:Bulk formats above 10 kilograms retain relevance in wholesale club and veterinary clinic channels.
- Custom Size:Bespoke dimensions serve OEM equipment and industrial chemical applications with non-standard fill requirements.
Medium capacity segments capture placement concentration; custom sizes climb fastest in industrial chemical outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Noida Special Economic Zone in India concentrates flexible packaging manufacturing capacity through tax holidays and duty exemptions on imported barrier film equipment. This zone anchors South Asian supply for export-oriented FMCG brands.
Germany
Confectionery and coffee brands in Hamburg and Bremen accelerate format conversion from rigid containers to mono-material polyethylene box pouches. The EU Packaging and Packaging Waste Regulation tightens material compliance timelines for 2025 implementation. Industrial composting infrastructure in Bavaria supports pilot programs for bio-based sealant layers in wet pet food applications.
United States
Subscription pet food startups in Austin and Denver shift procurement toward digital-printed medium-capacity pouches for postal fulfillment density. California and Oregon extended producer responsibility laws force compliance-driven replacement of multi-material laminates. Midwest converter clusters around Chicago retool lines for aluminum oxide deposition on mono-material structures.
Netherlands
Specialty coffee roasters in Amsterdam and Rotterdam adopt mono-material polyethylene structures at volume premiums to satisfy retailer recyclability mandates. REACH substance restrictions on per- and polyfluoroalkyl substances drive 18-month reformulation cycles for grease-resistant coatings. Eindhoven-based film extrusion facilities supply barrier laminates to German and Belgian brand owners.
China
Domestic FMCG brands in Shanghai and Guangzhou deploy box pouches for cube efficiency in e-commerce distribution channels. The country's national packaging standards authority accelerates mechanical recycling compatibility requirements for flexible formats. Yangtze River Delta converters expand aluminum oxide coating capacity to serve export demand from European coffee roasters.
India
Premium pet food brands in Mumbai and Bengaluru abandon multi-wall paper bags for resealable box pouches with oxygen barriers. The Food Safety and Standards Authority of India tightens food contact material notification requirements for imported laminates. Gujarat-based flexible packaging parks attract investment from multinational converters seeking South Asian manufacturing footprints.
Box Pouch Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated film extruders capturing margin from plastic volume while specialty paper and compostable lines command premiums where retailer mandates apply. The supplier base stratifies around regulatory compliance capabilities, as extended producer responsibility schemes invalidate legacy multi-material formats before recycling infrastructure matures. Three archetypes dominate: global integrated converters with captive resin supply, regional kraft-paper specialists with pulp-to-pouch integration, and digital-enabled custom printers serving subscription startups. Competitive moves concentrate on adhesive reformulation for PFAS-free compliance and aluminum oxide deposition technology licensing for mono-material barrier performance.
Among global integrated converters, Amcor PLC and Mondi Group occupy positions at opposite ends of the material spectrum. Amcor leverages its film extrusion network to anchor multinational FMCG accounts with high-barrier laminates. Mondi exemplifies the regional kraft-paper specialist archetype through integrated pulp-to-pouch operations in Austria and Sweden. ProAmpac LLC sits within the custom-printing tier, serving emerging pet food startups with rapid-turnaround digital production.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi Group |
| ProAmpac LLC |
| Constantia Flexibles Group GmbH |
| Sealed Air Corporation |
| Sonoco Products Company |
| DS Smith PLC |
| CDF Corporation |
| Smurfit Westrock |
| Others |
Value Chain & Pricing Dynamics
Subscription pet food brands in Austin and Denver concentrate procurement volume for medium-capacity pouches, locking in annual contract structures that trade price certainty against resin cost pass-through clauses. This buyer archetype consolidation rewards converters with captive film extrusion capabilities while squeezing spot-market-dependent competitors.
Pricing Analysis
Short lead-time premiums of 15-25% apply to digital-printed runs below 5,000 units for emerging pet food startups needing rapid turnaround. Three-tier pricing structure across premium, standard, and economy levels separates CSRD-aligned carbon-labeled laminates from conventional multi-material structures and commodity-grade mono-polyethylene formats. Price differentiation hinges on certification tier (How2Recycle/OPRL approval status) and volume scale. Pricing pressure stems from ethylene and propylene feedstock volatility compressing converter margins on fixed-price contracts. Emerging pet food startups exhibit highest price sensitivity; multinational FMCG accounts with captive resin supply show lowest.
Supply Chain Analysis
Direct-to-brand channels handle subscription pet food demand, while wholesale club distribution serves legacy bulk formats. Raw material supply concentrates in Germany, the Netherlands, and China for barrier film extrusion and aluminum oxide coating equipment. The chain draws from polyethylene terephthalate resin, ethylene vinyl alcohol barrier layers, and solvent-free polyurethane adhesives. Single-source vulnerability in aluminum oxide deposition technology creates bottleneck risk as mono-material conversion accelerates. Distribution runs through converter-direct relationships for multinational accounts and digital-enabled custom printers for subscription startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive film extrusion and adhesive formulation capabilities has become the defining competitive race, as extended producer responsibility schemes invalidate outsourced multi-material laminates.
For Market Incumbents: Cement barrier film supply security through in-house polyethylene extrusion lines or long-term offtake agreements with Yangtze River Delta coating facilities. Accelerate PFAS-free adhesive validation cycles ahead of REACH implementation timelines to avoid stranded inventory. Threat: Digital-enabled custom printers capturing subscription startup volume with sub-5,000-unit minimums. Lever: Aluminum oxide deposition technology licensing for mono-material recyclability compliance. For New Entrants and Emerging Players: Digital printing integration offers the most penetrable wedge, targeting specialty coffee roasters in Hamburg and Amsterdam with lot sizes below 5,000 units and carbon-labeled positioning. White-space targets include child-resistant zip-lock pouches for household products converting from rigid tubs, and compostable substrates for German retail mandates. Go-to-market angle: CSRD-aligned scope 3 disclosure partnerships with sustainability-focused brand owners. For Investors and Strategic Acquirers: The window for entry favors regional kraft-paper specialists with pulp-to-pouch integration and existing retailer recyclability certifications. Long-term viability centers on converters with validated PFAS-free coating portfolios and aluminum oxide deposition capabilities. Acquisition archetype: Mid-tier European converters with How2Recycle/OPRL certification queues already cleared. Signal to watch: Backlog extension in recyclability testing queues indicating demand acceleration ahead of regulatory deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Adhesive Reformulation | REACH substance restrictions force 18-24 month validation cycles against FDA food contact notifications. |
| Aluminum Oxide Deposition Licensing | Mono-material polyethylene structures with ethylene vinyl alcohol barriers satisfy EU mechanical recycling mandates. |
| Digital Printing Integration | HP Indigo and Xeikon systems collapse minimum order quantities for subscription pet food startups. |
| Backward Integration into Film Extrusion | Captive polyethylene supply insulates margins from ethylene feedstock volatility on fixed-price contracts. |
| CSRD-Aligned Carbon Labeling | Corporate Sustainability Reporting Directive mandates scope 3 disclosure, creating premium positioning for certified converters. |
Study Parameters
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with converter plant managers, pet food brand procurement leads, flexible packaging R&D directors, and retailer sustainability officers. Bottom-up and top-down triangulation validated volume estimates across material type, closure mechanism, and end-use segments.
Bottom-up modeling anchored projections in individual converter capacity announcements and brand format conversion timelines, while top-down analysis tracked EPR scheme implementation schedules and REACH substance restriction proposals. Segmentation dimensions included material chemistry, closure type, end-user vertical, and capacity tier. CAGRs derived from weighted average of historical placement trajectories and regulatory-driven replacement cycle assumptions. Industry-specific inputs encompassed aluminum oxide coating capacity expansion data and How2Recycle certification queue lengths.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction timelines or delayed industrial composting infrastructure buildout. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pre-Made Pouch Packaging Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Ziplock Products Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
Monodose Packs Market
Pouch
Foil Pouch Packaging Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Self-Seal Pouches Market
Pouch
Stick Pouches Packaging Market
Pouch
Spouted Pouches Market
Pouch
Clear Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Peel Pouches Market